
 Wooden Furniture Market | 2026-2036
Wooden Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Furniture Market Analysis
Flat-pack modularization is rebalancing buyer choice toward self-assembly configurations that cut last-mile logistics costs. IKEA leverages its captive flat-pack engineering and global retail footprint to sustain volume leadership. Ashley Furniture Industries anchors its position through vertical control over North American upholstery and case goods manufacturing. Vaughan-Bassett Furniture competes via domestic hardwood sourcing and quick-turn customization for regional dealers.
Wooden furniture comprises solid and engineered wood assemblies joined through doweling, mortise-and-tenon, or CNC-machined interlock methods, finished with stains, lacquers, or oil treatments to achieve specified abrasion resistance and moisture tolerance; its primary commercial purpose spans residential dwelling outfitting, workplace fit-out, and hospitality environment furnishing. Residential end users dominate absolute consumption, though hospitality represents the fastest-expanding demand pool as boutique hotel chains specify custom millwork. Oak material grades command premium positioning in heritage and craftsman-style lines, while pine occupies mass-market flat-pack and rental-housing channels where cost minimization governs procurement.
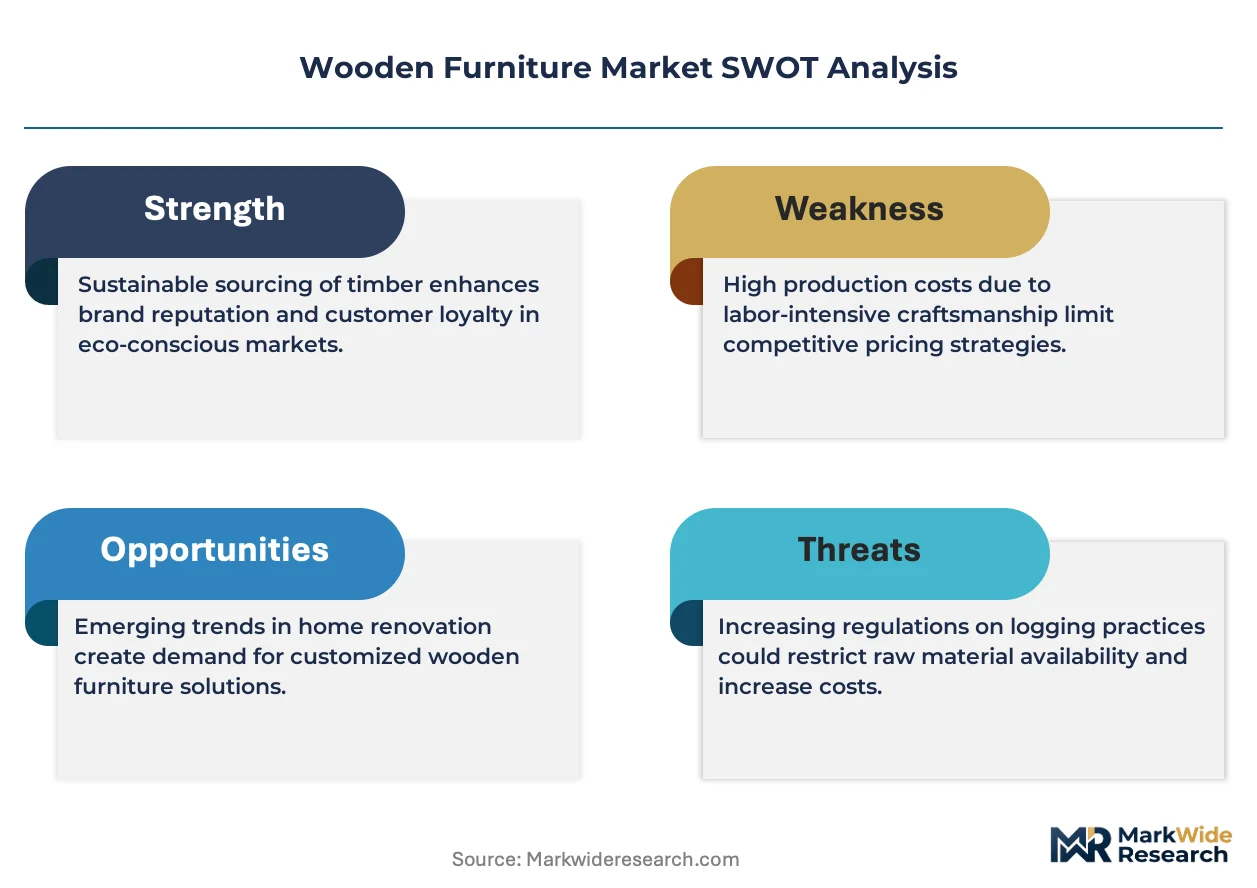
The EU Timber Regulation and the US Lacey Act impose chain-of-custody documentation that filters uncertified tropical hardwood from legitimate trade channels, while California Air Resources Board formaldehyde emissions standards shape panel substrate selection for products entering that state. ISO 14001 environmental management certification and FSC chain-of-custody accreditation increasingly function as qualifying criteria rather than differentiators in contract bidding. Stakeholders must monitor enforcement divergence between jurisdictions and decide whether to maintain parallel inventory pools or standardize to the strictest applicable standard.
Market Dynamics
EU Timber Regulation due diligence obligations are forcing importers to restructure supplier verification systems and segregate certified inventory pools by jurisdiction.
Growth Catalysts
- Hospitality experiential design:Boutique hotel chains specify custom millwork for differentiated guest environments, pulling hardwood fixtures into renovation cycles.
- FSC chain-of-custody accreditation:Retail procurement mandates in Germany and France now require documented sustainable sourcing for contract eligibility.
- CNC-machined interlock methods:Precision manufacturing reduces assembly labor and enables flat-pack distribution at scale.
Market Restraints
- Tropical hardwood supply concentration:Uncertified Southeast Asian suppliers face exclusion from EU and US trade channels under EUTR and Lacey Act enforcement.
- Formaldehyde substrate compliance:California Air Resources Board emissions standards impose panel selection constraints that increase material costs for products entering that state.
- Engineered wood substitution ceiling:Heritage and craftsman-style lines maintain specification preference for solid oak grades that resist full displacement.
Strategic Opportunities
- Vietnam manufacturing cluster expansion:North American and European retailers are consolidating contract orders in Vietnamese production hubs to exploit labor cost differentials.
- Self-assembly channel innovation:Direct-to-consumer flat-pack platforms bypass traditional dealer networks and capture margin previously allocated to last-mile logistics.
- ISO 14001 qualification threshold:Environmental management certification is shifting from differentiator to baseline requirement, creating consolidation pressure on uncertified competitors.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel inventory pools for EU, US, and Asian regulatory standards extend product development cycles and complicate forecasting.
- Skilled doweling and mortise-and-tenon craft scarcity:Traditional joinery expertise is concentrating in aging workforces without adequate apprenticeship pipeline replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Furniture Market |
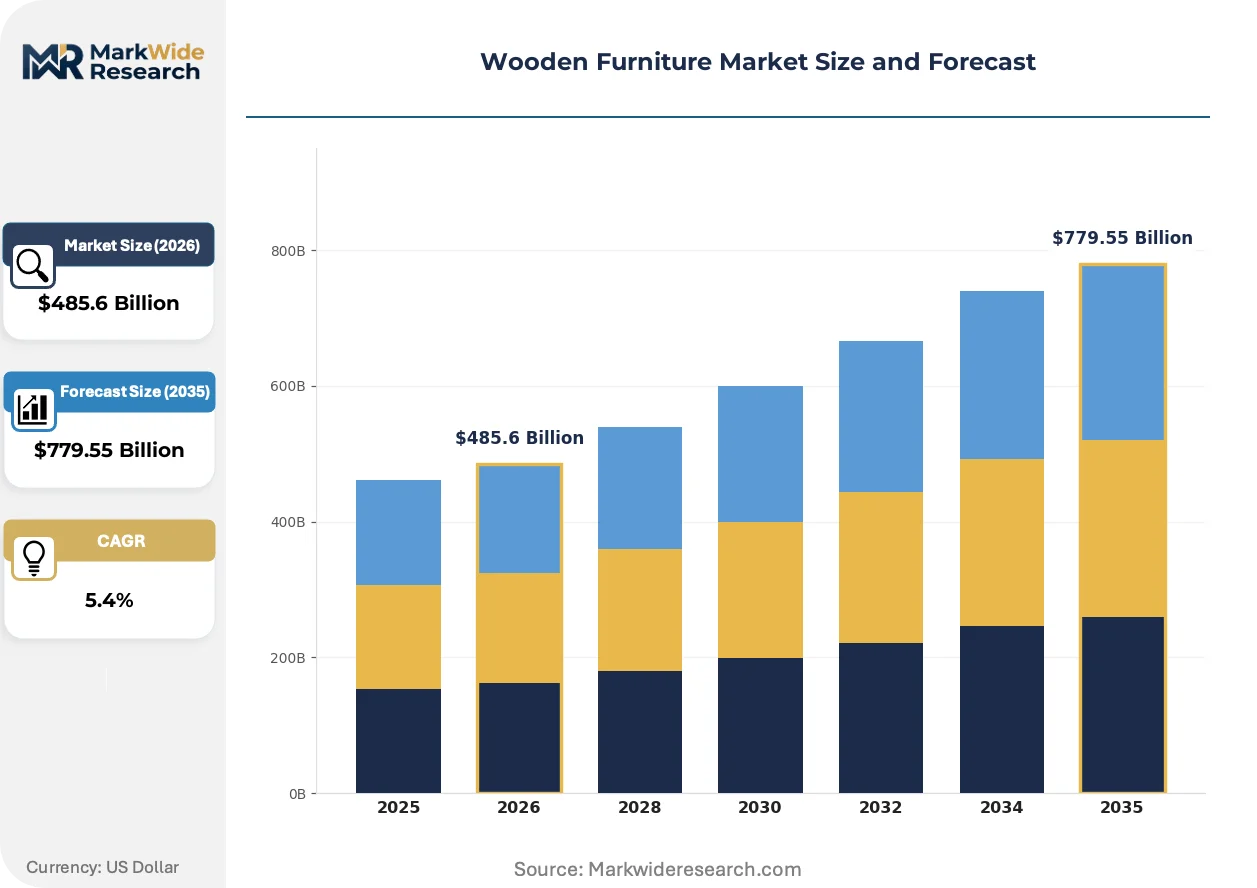
| Market Size in 2026 | $485.6 Billion |
| Market Size in 2035 | $779.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tables, Chairs, Cabinets, Sofas Material: Oak, Pine, Mahogany, Teak End User: Residential, Commercial, Hospitality, Educational Style: Modern, Rustic, Vintage, Contemporary |
| Companies Covered | IKEA, Ashley Furniture Industries, Williams-Sonoma, Stickley Furniture, Durham Furniture, Vaughan-Bassett Furniture, Bassett Furniture, Haworth, HNI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Furniture Market Emerging Trajectories
Digital fabrication and regulatory harmonization pressures are compressing traditional manufacturing timelines while fragmenting distribution channels away from consolidated retail.
CNC-machined interlock joinery is unifying precision manufacturing with modular assembly protocols. Hospitality fit-out contractors are specifying these systems for rapid on-site installation. The technology is unifying design flexibility with logistics cost reduction across contract furniture procurement.
EU Timber Regulation enforcement is intensifying chain-of-custody documentation requirements for all tropical hardwood imports. German customs authorities are conducting physical verification audits at Hamburg and Bremerhaven ports. Panel manufacturers serving EU markets are responding by segregating certified and uncertified substrate inventories.
Direct specification by hospitality operators is disintermediating traditional dealer networks for large fixture contracts. Boutique hotel development teams now engage millwork shops directly for custom lobby and guest room installations. This pattern is most visible in urban redevelopment corridors across Spain and Portugal where independent design studios coordinate fabrication.
Wooden Furniture Market Segmentation
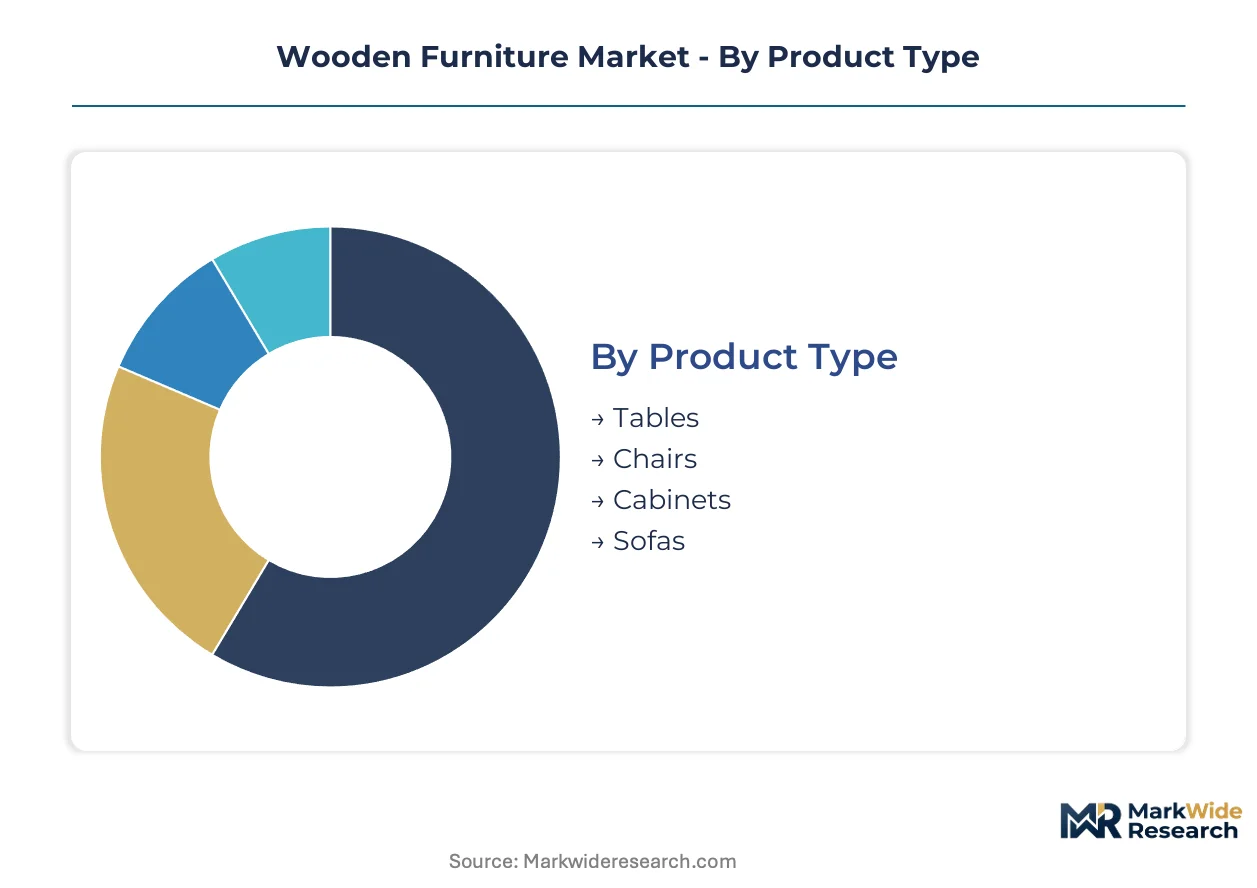
Wooden furniture procurement patterns diverge sharply across application contexts, with specification requirements for hospitality millwork bearing little resemblance to mass-market residential flat-pack economics. Understanding these segment boundaries enables suppliers to align certification investments, manufacturing configurations, and distribution channel selection with actual demand concentration.
Product Type:
The customization-to-standardization spectrum runs from bespoke built-in casework to volume-manufactured seating, with assembly complexity and logistics modularity determining channel economics.
- Tables:Dining and occasional tables span solid-slab live-edge constructions for hospitality statement pieces to CNC-machined knockdown designs for residential e-commerce. Demand concentrates in hospitality renovation cycles across Spain and Portugal, where boutique hotel operators specify custom dimensions for differentiated guest environments.
- Chairs:Seating assemblies range from hand-carved hardwood frames with mortise-and-tenon joinery to press-formed plywood shells with metal or wood leg systems. Residential channels in Germany and France dominate volume procurement, though FSC chain-of-custody accreditation now gates contract eligibility with major retailers.
- Cabinets:Storage systems include freestanding case goods and built-in millwork for residential kitchens, offices, and hospitality back-of-house.
- Sofas:Upholstered seating frames combine engineered wood substrates with hardwood legs and structural elements, governed by California Air Resources Board emissions standards for panel substrates.
Most installed capacity flows through Chairs. Expansion is steepest in Cabinets.
Material:
Cost tier stratification separates heritage-grade hardwoods from utility softwoods, with certification status and regulatory compliance adding premium layers.
- Oak:Dense hardwood with prominent grain patterns, specified for craftsman and heritage furniture lines requiring abrasion resistance and refinishing longevity. Demand concentrates in premium residential and hospitality segments across France and Germany, where EU Timber Regulation documentation requirements filter uncertified supply from legitimate trade channels.
- Pine:Softwood with uniform texture and high workability, dominant in mass-market flat-pack and rental-housing channels where cost minimization governs procurement decisions.
- Mahogany:Tropical hardwood with fine, even grain, traditionally specified for high-end traditional and reproduction furniture.
- Teak:Oil-rich tropical hardwood with natural moisture and decay resistance, specified for outdoor and marine applications.
Volume leadership sits with Pine. Value concentration tilts toward Oak.
End User:
Application context determines specification rigor, with contract hospitality and educational procurement imposing documentation and performance standards absent from consumer-direct residential channels.
- Residential:Consumer-direct and dealer-channel procurement for dwelling outfitting, spanning mass-market flat-pack to custom millwork. Volume concentrates in owner-occupied housing across suburban and urban markets, with e-commerce platforms capturing share from traditional furniture retailers through self-assembly logistics economics.
- Hospitality:Boutique hotel chains, restaurants, and experiential venues specifying custom millwork for differentiated guest environments. This segment is gaining share fastest as renovation cycles accelerate across urban redevelopment corridors in Spain and Portugal.
- Commercial:Workplace fit-out and corporate environment furnishing, governed by durability specifications and warranty requirements.
- Educational:Institutional procurement for schools and universities, subject to public-sector bidding protocols and budget constraints.
Residential channels absorb the largest absolute volume. Hospitality specifications are climbing the fastest.
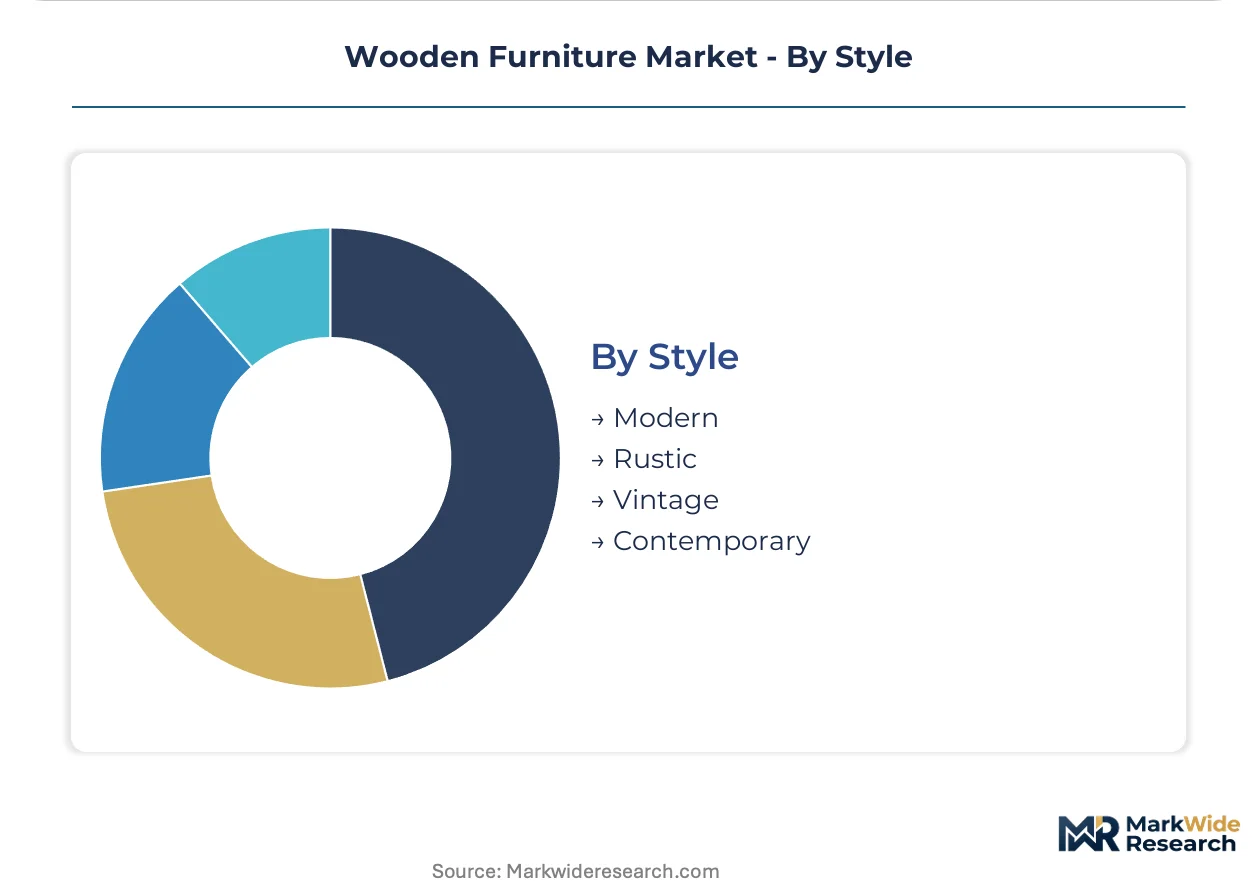
Style:
Design lineage determines material grade requirements, joinery method selection, and finishing protocol complexity, with direct implications for manufacturing cost structure and lead time.
- Modern:Clean lines, minimal ornamentation, and engineered wood substrates with lacquer or oil finishes. Demand concentrates in urban residential markets and commercial fit-out across Germany, where precision manufacturing enables flat-pack distribution at scale.
- Rustic:Distressed surfaces, live edges, and visible joinery celebrating material character. Hospitality operators across Portugal and Spain specify these aesthetics for differentiated guest environments in boutique properties.
- Vintage:Reproduction and antique-styled pieces with traditional proportions and decorative details.
- Contemporary:Current design trends blending material innovation with updated silhouettes, often incorporating mixed-material construction.
Modern styling commands the largest production volume. Rustic specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wooden furniture manufacturing traces its modern industrial lineage to 19th-century craft guilds in Central Europe and New England, where mechanized sawmilling and standardized joinery methods first enabled volume production. Contemporary demand patterns reflect this heritage, with established clusters in Northern Europe and North America maintaining specification influence while Asian manufacturing hubs capture contract assembly volumes.
Germany
FSC chain-of-custody procurement mandates from major retailers concentrate demand for certified oak and beech furniture across residential channels. The country's national timber regulation enforces EUTR due diligence requirements that filter uncertified tropical hardwood from legitimate trade. Manufacturing gravity sits in North Rhine-Westphalia and Bavaria, where precision CNC machining clusters serve both domestic contract furniture and export flat-pack assembly.
United States
Boutique hotel renovation cycles and experiential venue design are accelerating hardwood fixture procurement across hospitality channels. The Lacey Act imposes chain-of-custody documentation requirements that reshape import verification systems for tropical hardwood substrates. Production concentrates in North Carolina and Virginia furniture corridors, where domestic hardwood sourcing and quick-turn customization capabilities serve regional dealer networks.
Vietnam
North American and European retailers are consolidating contract orders in Vietnamese production hubs to exploit labor cost differentials and expanding manufacturing capacity. The country's national forestry administration maintains timber legality assurance systems aligned with EU market access requirements. Export-oriented clusters in Binh Duong and Dong Nai provinces specialize in flat-pack assembly and hospitality millwork for contract fulfillment.
France
Premium residential demand for heritage-grade oak furniture sustains specification preference for solid hardwood grades across craftsman and vintage styling lines. The national environment agency enforces EUTR compliance verification that segments certified and uncertified inventory pools at port entry. Manufacturing concentrates in Auvergne-Rhône-Alpes and Nouvelle-Aquitaine, where traditional joinery expertise intersects with precision finishing for contract hospitality procurement.
Spain
Urban redevelopment corridors across Madrid and Barcelona are driving boutique hotel specification of custom millwork for differentiated guest environments. The national consumer affairs authority coordinates with EU customs on timber legality enforcement at Valencia and Barcelona ports. Design studios in Catalonia and Madrid increasingly engage millwork shops directly, disintermediating traditional dealer networks for large fixture contracts.
Wooden Furniture Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and customization depth. The vendor base stratifies into three concentration levels: integrated multinationals with captive retail footprints, domestic hardwood specialists with regional dealer relationships, and contract manufacturing hubs serving private-label procurement. Three archetypes dominate competitive positioning: flat-pack engineering specialists, vertical upholstery-case goods integrators, and domestic craft-scale customizers. Consolidation pressure operates through ISO 14001 qualification thresholds and multi-jurisdiction certification timelines that favor standardized compliance investment.
Within the integrated multinational tier, IKEA exemplifies flat-pack engineering and global retail footprint deployment. Among North American domestic specialists, Vaughan-Bassett Furniture occupies a position emphasizing domestic hardwood sourcing and quick-turn customization capabilities. At the contract manufacturing end, Ashley Furniture Industries anchors vertical control over upholstery and case goods production. These three represent divergent strategic postures on certification investment, channel configuration, and geographic sourcing concentration.
| Leading Market Players |
|---|
| IKEA |
| Ashley Furniture Industries |
| Williams-Sonoma |
| Stickley Furniture |
| Durham Furniture |
| Vaughan-Bassett Furniture |
| Bassett Furniture |
| Haworth |
| HNI Corporation |
| Others |
Supply Flow & Price Mechanics
Certified oak feedstock costs transmit downstream through three distinct pricing tiers that separate heritage-grade solid hardwood from mass-market engineered alternatives, with EU Timber Regulation compliance premiums layering onto FSC-accredited inventory pools before reaching hospitality procurement teams in Spain and Portugal.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs wooden furniture procurement, with certification grade and customization depth serving as the primary price differentiation drivers. Pricing pressure stems from formaldehyde substrate compliance costs for California-bound products, compressing margins in the mid-market engineered wood tier. Mass-market residential buyers exhibit highest price sensitivity, while boutique hospitality operators absorb premiums for documented chain-of-custody and rapid-turn custom dimensions.
Supply Chain Analysis
Skilled doweling and mortise-and-tenon craft scarcity concentrates in aging Vietnamese and French workforces, constraining output expansion for heritage joinery specifications. Raw material sourcing draws from certified oak forests in France, plantation pine in Vietnam, and tropical hardwood reserves subject to EUTR documentation requirements. Single-source vulnerability runs through concentrated Binh Duong manufacturing clusters serving North American contract orders. Distribution runs through direct specification by hospitality operators disintermediating traditional dealer networks, alongside flat-pack e-commerce platforms capturing residential self-assembly demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wooden furniture markets are entering a late-cycle quality phase as hospitality procurement shifts toward certified heritage-grade specifications with documented provenance, rewarding suppliers who invested early in FSC chain-of-custody and ISO 14001 accreditation.
For Market Incumbents: Anchor market position through captive certification investment and geographic diversification of supplier verification systems. Consolidate regional dealer relationships in France and Germany where FSC mandates now gate contract eligibility. Defend against Vietnam-based contract manufacturers by emphasizing quick-turn customization capabilities and domestic hardwood sourcing transparency that satisfies EUTR due diligence without cross-border documentation lag. For New Entrants and Emerging Players: EU Timber Regulation enforcement intensification across German and French port authorities opens a window for certified-only sourcing platforms that aggregate verified inventory pools for mid-size hospitality developers. Target urban redevelopment corridors in Spain and Portugal where boutique hotel chains disintermediate traditional dealers for direct millwork engagement. Lead with digital fabrication capabilities enabling rapid prototype-to-production cycles for custom dimensions without legacy tooling investment. For Investors and Strategic Acquirers: Roll-up economics work for domestic craft-scale customizers with established FSC accreditation because certification timelines create moats against uncertified competitors facing multi-jurisdiction compliance burdens. Target North American and French hardwood specialists with regional dealer networks and quick-turn capabilities. Watch enforcement divergence between EU customs authorities and US Lacey Act implementation as the signal indicating which certification standard will dominate cross-border procurement requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment Acceleration | FSC chain-of-custody and ISO 14001 accreditation shift from differentiator to baseline contract eligibility across German and French retail procurement. |
| Direct-to-Hospitality Channel Development | Bypassing dealer networks captures margin previously allocated to intermediaries in Spain and Portugal boutique hotel renovation cycles. |
| CNC-Machined Interlock Scale-Up | Precision manufacturing reduces assembly labor and enables flat-pack distribution economics for hospitality fit-out contractors. |
| Vietnam Manufacturing Footprint Expansion | Consolidating contract orders in Binh Duong and Dong Nai exploits labor cost differentials for North American and European retailer fulfillment. |
| Domestic Hardwood Sourcing Control | Vertical integration into North Carolina and Virginia timber supplies insulates against tropical hardwood supply concentration risks under EUTR enforcement. |
Methodological Framework
Multiple input streams — structured interviews with hospitality procurement directors and millwork shop owners, trade data from customs documentation systems, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged furniture manufacturing executives, FSC certification auditors, and German retail category buyers alongside secondary validation against EU Timber Regulation enforcement records, California Air Resources Board substrate compliance databases, and Vietnamese export licensing disclosures.
Data-stream reconciliation across product type, material grade, end-use application, and geographic manufacturing cluster dimensions informed analytical framework construction over the projection horizon. CAGRs were derived from segment-level volume and value trajectory modeling incorporating hospitality renovation cycle timing, certification adoption curves, and CNC machining capacity expansion patterns. Industry-specific forecast inputs included flat-pack logistics cost compression rates and skilled joinery workforce replacement ratios.
Revisions become necessary when regulatory enforcement divergence accelerates, tropical hardwood supply disruptions materialize, or hospitality capital expenditure cycles shift materially from baseline assumptions. Forecasts reflect documented assumptions subject to revision triggers including EUTR audit intensity changes, California formaldehyde standard amendments, and Vietnamese manufacturing cluster labor cost trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United Kingdom Furniture Market
Furniture
North America School Furniture Market
Furniture
Global Furniture Market
Furniture
Poland Home Furniture Market
Furniture
Mexico Home Furniture Market
Furniture
Italy Office Furniture Market
Furniture
Japan Furniture Market
Furniture
Entryway Furniture Market
Furniture
Kids Table and Chair Market
Furniture
Europe School Furniture Market
Furniture
HORECA Furniture Market
Furniture
Europe Furniture Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Europe Outdoor Furniture Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
India Upholstered Furniture Market