
 Asia-Pacific Contract Furniture Market | 2026-2036
Asia-Pacific Contract Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Contract Furniture Market Outlook
Multi-source procurement toward integrated workspace solutions is recalibrating how regional buyers evaluate vendor partnerships. Kokuyo Furniture leverages its domestic manufacturing footprint to serve Japanese corporate headquarters with rapid lead times. Hyundai Livart anchors its position through specialized hospitality furnishing lines that serve Seoul's hotel construction pipeline. Itoki competes by extending R&D investment into height-adjustable desking systems for technology-sector clients.
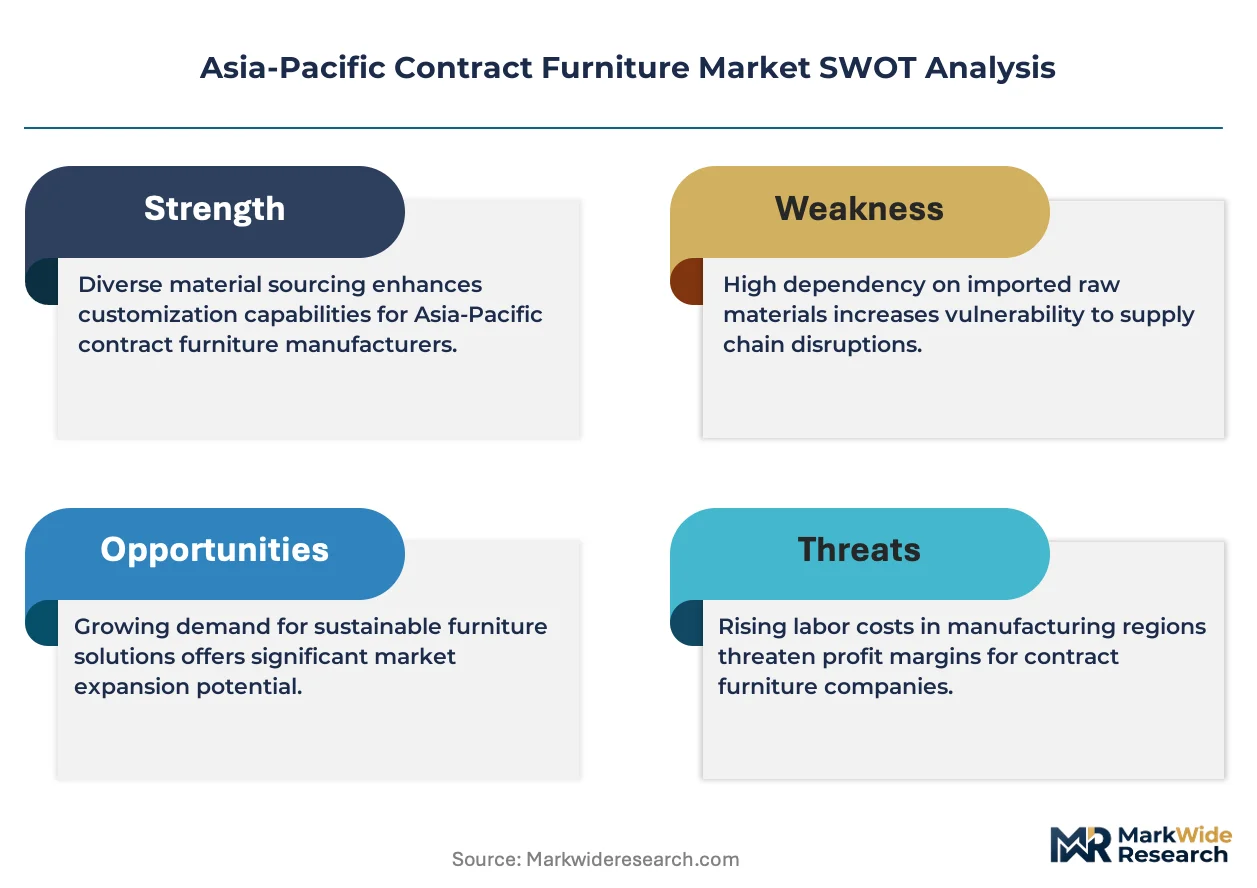
Asia-Pacific contract furniture encompasses commercial-grade seating, surfaces, and storage systems engineered for durability cycles exceeding residential standards, typically rated for eight to twelve hours of daily use in high-traffic environments. Manufacturers employ steel-reinforced frames, commercial-grade laminates, and fire-retardant upholstery to meet institutional safety requirements across office, hospitality, and healthcare installations. The office end-user segment dominates current volume as hybrid workplace redesigns sustain replacement demand across the region's central business districts. Metal-based products capture premium positioning due to extended lifecycle performance in high-occupancy settings, while upholstered seating commands higher margin pools in hospitality applications.
Japan's METI enforces energy-efficiency benchmarks that influence manufacturing equipment standards, while China's GB standards govern structural stability and formaldehyde emission limits for wood-based furniture sold domestically. Australia's WHS regulations mandate ergonomic compliance for employer-provided workstations, directly shaping product specification requirements. Buyers must monitor how evolving ESG disclosure rules across multiple Asia-Pacific jurisdictions will reshape supplier qualification criteria and material traceability obligations.
Market Dynamics
Hybrid workplace mandates across Asia-Pacific commercial districts are compressing furniture replacement cycles as employers redesign floorplates for activity-based working. Procurement teams now prioritize modular systems that reconfigure without full replacement.
Growth Catalysts
- India's BIS certification mandates:Safety compliance requirements are tightening across the furniture supply chain, elevating quality thresholds and filtering out informal manufacturers. Certified suppliers gain preferential access to institutional tenders.
- Co-working space operators:China's tier-one cities are scaling bulk orders for standardized workstation packages. These operators require rapid deployment capabilities and volume pricing flexibility.
- Ergonomic workstation specifications:Australia's WHS regulations mandate employer-provided ergonomic compliance, directly shaping product requirements for height-adjustable desking and task seating.
Market Restraints
- Steel and aluminum input volatility:Metal-based furniture frames face margin pressure from commodity price swings. Manufacturers with captive metalworking capacity buffer exposure better than assembly-only operations.
- Formaldehyde emission compliance:China's GB standards impose strict limits on wood-based panel emissions. Testing and certification add 8-12 weeks to product development timelines.
- Domestic manufacturing concentration:Japan's METI energy-efficiency benchmarks favor local production with advanced equipment. Import-dependent vendors face competitive disadvantages on lead times and carbon disclosure.
Strategic Opportunities
- Southeast Asia hospitality pipeline:Vietnam and Thailand hotel construction is accelerating demand for specialized furnishing lines. Custom upholstery and casegoods for boutique properties command premium positioning.
- Healthcare facility expansion:Australia's aged care infrastructure investment is creating demand for infection-control seating and mobile storage. Antimicrobial surfaces and cleanable designs differentiate bids.
- Digital specification platforms:BIM-compatible furniture libraries are winning architect and designer preference. Early movers in 3D product visualization secure specification lock-in before competitive bidding.
Industry Challenges
- Fire-retardant chemistry transitions:Evolving safety standards across multiple jurisdictions require reformulation of foam and fabric treatments. Dual inventory management strains working capital.
- Skilled upholstery technician shortages:Commercial-grade stitching and pattern-matching expertise is concentrating in legacy manufacturing clusters. Training pipelines have not scaled with demand recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Contract Furniture Market |
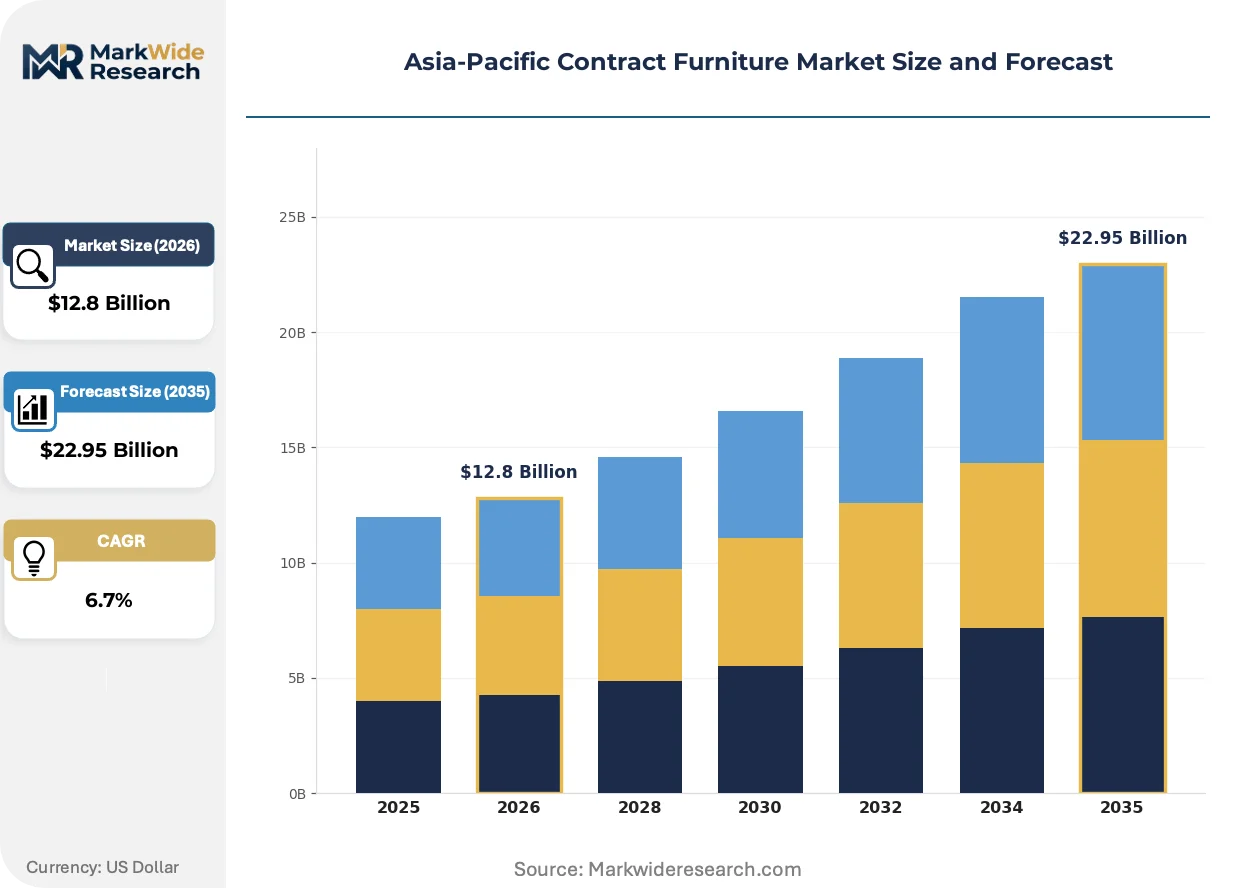
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Desks, Sofas Material: Wood, Metal, Plastic, Upholstery End User: Office, Hospitality, Educational, Healthcare Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Kokuyo Furniture, UE Furniture, Kinwai, Uchida Yoko, Fursys, Hyundai Livart, Haworth Inc, Warisan, Itoki, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Contract Furniture Market Strategic Shifts
Sensor-embedded furniture and circular material flows are redefining how contract furniture delivers value beyond physical durability. Manufacturers now compete on data integration and end-of-life recovery capabilities.
Electrified height-adjustable desking is electrifying workstation categories across technology-sector fit-outs. Singapore and Sydney corporate headquarters are specifying sit-stand surfaces as baseline requirements. This electrification is compressing demand for static-height desks into replacement-only volumes.
Japan's METI energy-efficiency benchmarks now extend to manufacturing equipment standards for furniture production. Suppliers must document power consumption and thermal recovery in capital equipment procurement. Woodworking and metal fabrication facilities in Osaka and Nagoya are retrofitting lines to maintain preferred vendor status with domestic headquarters buyers.
Subscription-based furniture-as-a-service models are displacing outright purchase in co-working and flexible office portfolios. Operators in Shanghai and Beijing prefer per-seat monthly fees covering maintenance, refresh, and reconfiguration. This shift transfers obsolescence risk to manufacturers while locking in multi-year revenue streams.
Asia-Pacific Contract Furniture Market Segmentation
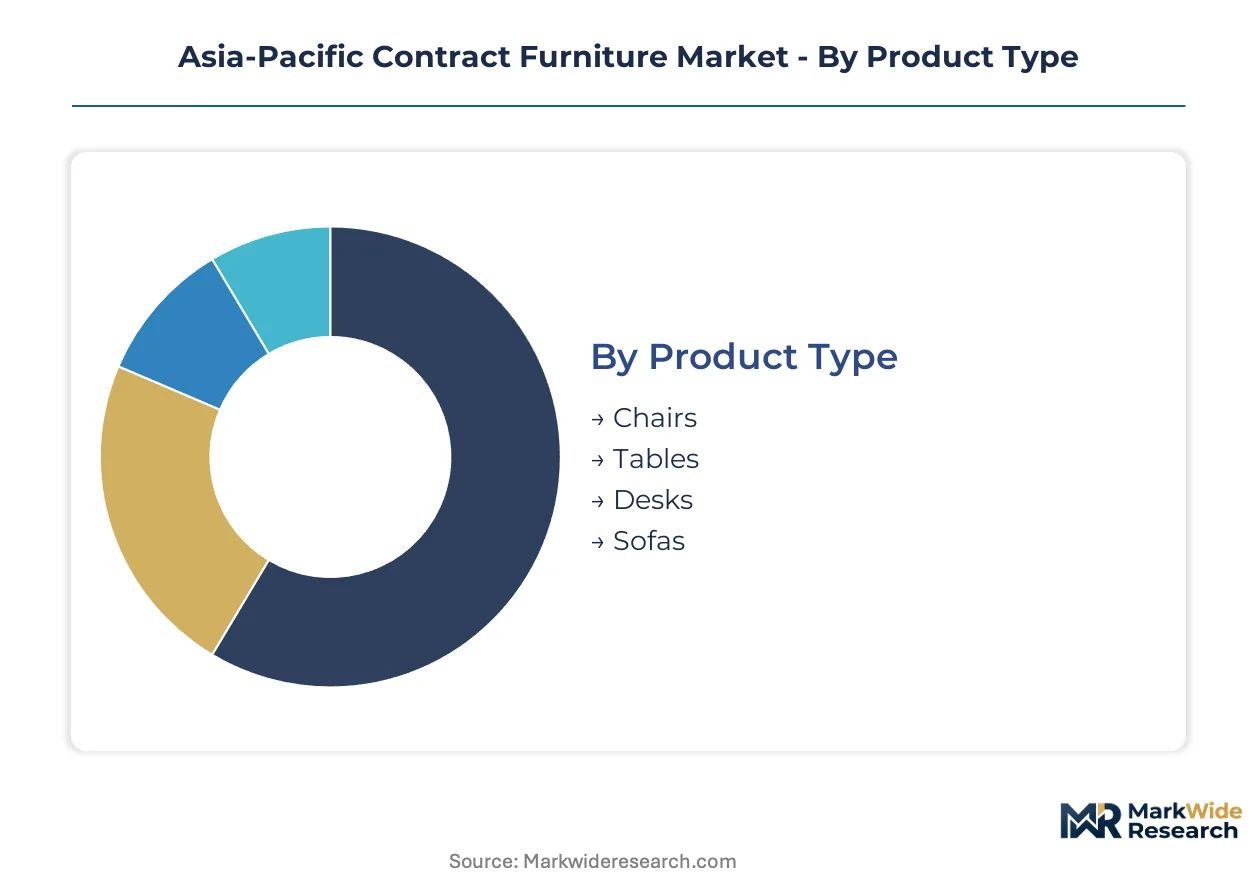
Segmentation in the Asia-Pacific contract furniture market reveals how procurement priorities diverge across institutional buyers, material specifications, and channel economics. Each dimension carries distinct margin profiles, compliance burdens, and competitive dynamics that reshape vendor selection criteria.
Product Type:
Buyers prioritize lifecycle durability and reconfiguration flexibility when selecting product categories for high-occupancy installations.
- Chairs:Task seating incorporates synchronized tilt mechanisms and breathable mesh backs rated for eight-hour continuous use. Australia's WHS regulations mandate ergonomic adjustability for employer-provided workstations, compressing demand into certified product lines.
- Tables:Conference and collaborative surfaces employ steel-reinforced frames with modular connection systems. Co-working operators in Shanghai and Beijing specify standardized table packages that deploy rapidly across multiple floorplates.
- Desks:Electrified height-adjustable workstations dominate technology-sector fit-outs in Singapore and Sydney.
- Sofas:Lounge seating for hospitality and reception applications commands premium upholstery specifications in Vietnam and Thailand hotel construction.
Volume sits with chairs; growth tilts toward desks.
Material:
Raw material selection determines compliance pathways, carbon disclosure obligations, and supplier qualification thresholds across institutional tenders.
- Metal:Steel and aluminum frames deliver extended lifecycle performance in high-traffic environments. Manufacturers with captive metalworking capacity in Japan buffer margin exposure from commodity volatility better than assembly-only competitors.
- Wood:Engineered panels and solid timber constructions face China's GB standards for structural stability and formaldehyde emission limits. Testing and certification add eight to twelve weeks to product development timelines, filtering out informal manufacturers.
- Plastic:Polymer-based components serve cost-sensitive educational and healthcare applications requiring cleanable surfaces.
- Upholstery:Commercial-grade fabrics with fire-retardant treatments differentiate hospitality bids in Seoul's hotel pipeline.
Metal captures institutional volume; upholstery delivers margin expansion.
End User:
Application-specific durability standards and regulatory mandates reshape product specification requirements across vertical markets.
- Office:Hybrid workplace redesigns sustain replacement demand across central business districts in Singapore, Sydney, and Tokyo. Activity-based working compresses furniture replacement cycles as employers reconfigure floorplates.
- Hospitality:Boutique hotel construction in Vietnam and Thailand accelerates demand for custom casegoods and specialized furnishing lines. Pattern-matching expertise concentrates in legacy manufacturing clusters with limited training pipeline scaling.
- Educational:Institutional procurement prioritizes cost efficiency and vandal-resistant construction for K-12 and university installations.
- Healthcare:Australia's aged care infrastructure investment creates demand for infection-control seating with antimicrobial surfaces and mobile storage systems.
Office maintains volume dominance; healthcare exhibits the steepest expansion trajectory.
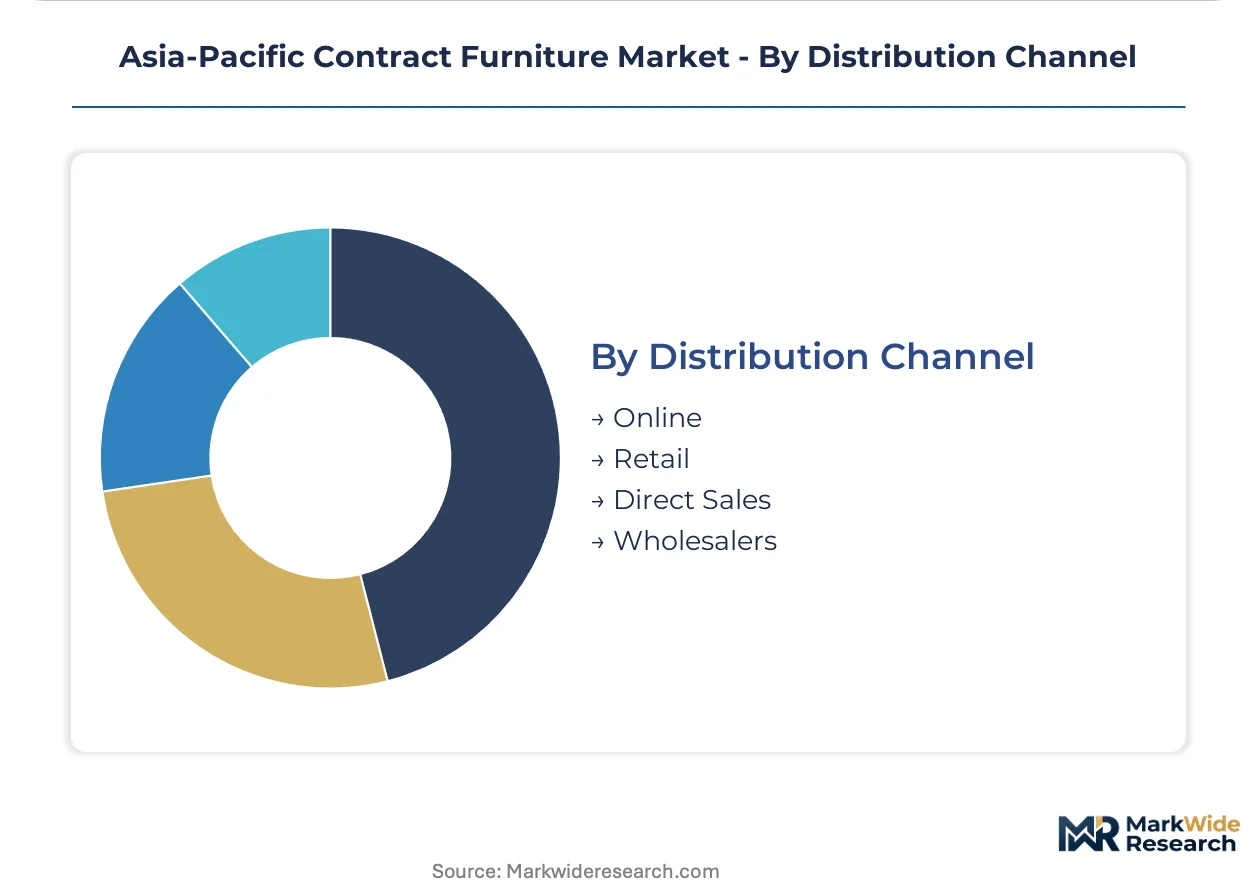
Distribution Channel:
Channel economics determine working capital intensity, specification influence, and customer relationship durability across buyer segments.
- Direct Sales:Manufacturer-direct relationships with corporate headquarters and co-working operators enable volume pricing flexibility and rapid deployment capabilities. Kokuyo Furniture leverages domestic Japanese manufacturing to serve headquarters buyers with compressed lead times.
- Online:Digital specification platforms with BIM-compatible furniture libraries win architect and designer preference before competitive bidding commences.
- Retail:Showroom-based channels serve small and mid-size commercial buyers requiring tactile evaluation.
- Wholesalers:Inventory-heavy intermediaries aggregate demand from fragmented regional installers.
Direct sales anchor enterprise volume; online channels are climbing the fastest for specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and engineered wood feedstock availability in China's Yangtze River Delta anchors regional manufacturing capacity. Japanese domestic metalworking clusters supply precision components to headquarters buyers. Southeast Asian upholstery workshops serve hospitality construction pipelines.
China
Co-working operators in Shanghai and Beijing are scaling bulk procurement of standardized workstation packages. GB standards govern structural stability and formaldehyde emission limits for wood-based panel products. Manufacturing concentrates in the Pearl River Delta where facilities retrofit lines to meet dual carbon disclosure requirements.
Japan
Corporate headquarters in Tokyo and Osaka sustain demand for rapid-lead-time ergonomic systems. METI enforces energy-efficiency benchmarks that influence capital equipment procurement in woodworking and metal fabrication. Industrial clusters in Nagoya and Osaka supply domestic headquarters buyers with compressed delivery schedules.
Australia
Corporate fit-outs in Sydney and Melbourne are expanding procurement of height-adjustable desking and task seating. WHS regulations mandate ergonomic compliance for employer-provided workstations, shaping product specifications. Aged care infrastructure investment in Victoria and New South Wales creates demand for infection-control seating with antimicrobial surfaces.
India
Institutional tenders from corporate campuses in Bengaluru and Hyderabad are elevating quality thresholds for certified suppliers. BIS certification mandates for furniture safety are tightening compliance requirements across the supply chain. Manufacturing concentrates in Gujarat and Maharashtra where formal producers gain preferential access to large-scale contracts.
South Korea
Hotel construction in Seoul drives demand for specialized hospitality furnishing lines with custom upholstery specifications. The country's national industrial standards body influences fire-retardant treatment requirements for commercial installations. Manufacturing clusters in the Seoul Capital Area supply boutique properties with pattern-matched casegoods and reception seating.
Asia-Pacific Contract Furniture Market Competitive Environment
Global majors compete with regional champions across distribution reach and specification influence. The vendor base organizes into three tiers: integrated manufacturers with captive metalworking capacity, assembly-focused specialists sourcing components from distributed supplier networks, and hospitality-centric upholstery houses with concentrated pattern-matching expertise. Dominant competitive moves include backward integration into steel fabrication and strategic partnerships with co-working operators for furniture-as-a-service deployment.
Among Japan-based manufacturers, Kokuyo Furniture and Itoki occupy positions within the integrated domestic supply tier, leveraging proximity to headquarters buyers. Hyundai Livart anchors the hospitality-specialist archetype among Korean fabricators. These named entities exemplify how geographic clustering around industrial cities reinforces competitive positioning through lead-time compression and regulatory familiarity.
| Leading Market Players |
|---|
| Kokuyo Furniture |
| UE Furniture |
| Kinwai |
| Uchida Yoko |
| Fursys |
| Hyundai Livart |
| Haworth Inc |
| Warisan |
| Itoki |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap manufacturers across Japan's Nagoya industrial belt anchor pricing discipline through captive metalworking capacity, compressing procurement timelines for domestic headquarters buyers while insulating margin structures from commodity volatility that strains assembly-only competitors.
Pricing Analysis
Warranty and service bundling separates premium-tier positioning from transactional procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade against BIS and GB standards alongside volume scale. Cost compression in standard-tier metal seating is intensifying because steel input volatility feeds through frame fabrication. Small and mid-size commercial buyers via retail channels exhibit highest price sensitivity; corporate headquarters buyers with direct manufacturer relationships show least sensitivity due to total-cost-of-ownership evaluation.
Supply Chain Analysis
Steel and engineered wood panel supply rests on China's Yangtze River Delta manufacturing clusters, Japanese domestic metalworking facilities, and Southeast Asian upholstery workshops. Raw material dependencies span cold-rolled steel, commercial-grade laminates, and fire-retardant foam treatments. Single-source vulnerability concentrates in pattern-matched upholstery expertise concentrated in legacy manufacturing clusters. Distribution runs through direct sales for enterprise volume, digital specification platforms for architect influence, and inventory-heavy wholesalers for fragmented regional installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over captive metalworking capacity determines lead-time competitiveness and carbon disclosure compliance against Japan's METI benchmarks.
For Market Incumbents: Hedge against commodity volatility through backward integration into steel fabrication or long-term offtake agreements with Yangtze River Delta suppliers. Deepen specification lock-in by accelerating BIM-compatible furniture library deployment before competitive bidding commences. Certification investment against India's tightening BIS mandates filters tender access and protects institutional revenue pools.
For New Entrants and Emerging Players: Launch via furniture-as-a-service subscription models targeting co-working operators in Shanghai and Beijing seeking per-seat monthly fees with maintenance bundling. White-space sits with infection-control seating for Australia's aged care infrastructure expansion. Digital specification platforms offer fastest specification influence accumulation against legacy showroom-dependent competitors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hospitality-centric upholstery houses with concentrated pattern-matching expertise in Vietnam and Thailand. Long-term viability across the projection horizon hinges on circular material recovery capabilities and end-of-life take-back infrastructure. Monitor co-working operator consolidation as inflection indicator for subscription-model revenue durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Captive metalworking capacity buffers margin exposure from commodity volatility better than assembly-only operations. |
| BIM-Compatible Furniture Library Deployment | Digital specification platforms win architect preference before competitive bidding commences in Singapore and Sydney. |
| Furniture-as-a-Service Subscription Launch | Per-seat monthly fees transfer obsolescence risk to manufacturers while locking multi-year revenue with co-working operators. |
| Antimicrobial Surface Certification Investment | Infection-control seating differentiation captures Australia's aged care infrastructure procurement requirements. |
| Circular Material Recovery Infrastructure | End-of-life take-back capabilities satisfy evolving ESG disclosure rules across multiple Asia-Pacific jurisdictions. |
Study Parameters
Independent corroboration across procurement directors at corporate headquarters, specification leads at architecture firms, and operations managers at co-working operators underwrites the qualitative findings. Primary fieldwork combined structured interviews with facility managers, tender evaluation committees at institutional buyers, and channel partners at wholesale distributors. Secondary validation drew from customs trade data, BIS certification registries, GB standards documentation, and METI equipment efficiency disclosures. Bottom-up demand aggregation across end-user segments triangulated against top-down manufacturing capacity assessments.
Comparable-period anchoring referenced historical replacement cycle compression during hybrid workplace transitions. The analytical framework modeled demand across product type, material specification, end-user vertical, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectory blending. Industry-specific forecast inputs incorporated co-working operator expansion pipelines and hospitality construction permit flows.
The model assumes a particular technology adoption path; alternative pathways for sensor-embedded furniture and electrified desking would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency for BIS and GB standards. Commodity price volatility, fire-retardant chemistry transitions, and skilled upholstery technician shortages warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Mexico Home Furniture Market
Furniture
Chaises Longue Market
Furniture
RTA Furniture Market
Furniture
Portering Chair Market
Furniture
Global Furniture Fittings Market
Furniture
United Arab Emirates Furniture Market
Furniture
Ergonomic Chair Market
Furniture
Luxury Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Kids Table and Chair Market
Furniture
Wood Furniture Market
Furniture
Global Multifunctional Furniture Market
Furniture
Laminated Door Market
Furniture
Japan Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
Bounding Table Market