
 Children's Home Study Desks Market | 2026-2036
Children's Home Study Desks Market Size, Share, and Industry Trends Forecast 2026-2036
Children's Home Study Desks Market Insights
Parental workforce flexibility is reorganizing how families allocate space for children's learning at home, creating sustained demand for dedicated study furniture. Loctek leverages its ergonomic engineering heritage to dominate adjustable-height desk categories. Guidecraft anchors its position through specialized early-childhood designs that emphasize safety certification and dimensional proportioning for toddlers and preschoolers.
Children's home study desks are purpose-built furniture units designed with scaled dimensions, safety-rounded edges, and load-rated surfaces typically supporting monitor weights while accommodating seated heights from 18 to 30 inches. Primary commercial purpose centers on creating ergonomically appropriate, distraction-managed environments for developmental learning and homework completion. Compact desks and adjustable desks lead volume as urban apartment dwellers prioritize space efficiency and multi-year usability across growth stages. Wood material construction commands premium positioning among design-conscious buyers, while plastic formats compete aggressively on entry-price accessibility for mass-market channels.
EPA guidelines on formaldehyde emissions in composite wood products and the EU's REACH chemical restrictions directly shape material selection and finishing processes for manufacturers serving North American and European households. China's GB standards for children's furniture mandate specific stability tests and gap dimensions that dictate structural design for products manufactured domestically. BIS certification requirements in India create incremental compliance costs that filter market access for imported desk assemblies. Stakeholders must monitor evolving chemical safety thresholds and dimensional regulations across their target production geographies to avoid redesign cycles that erode margin structures.
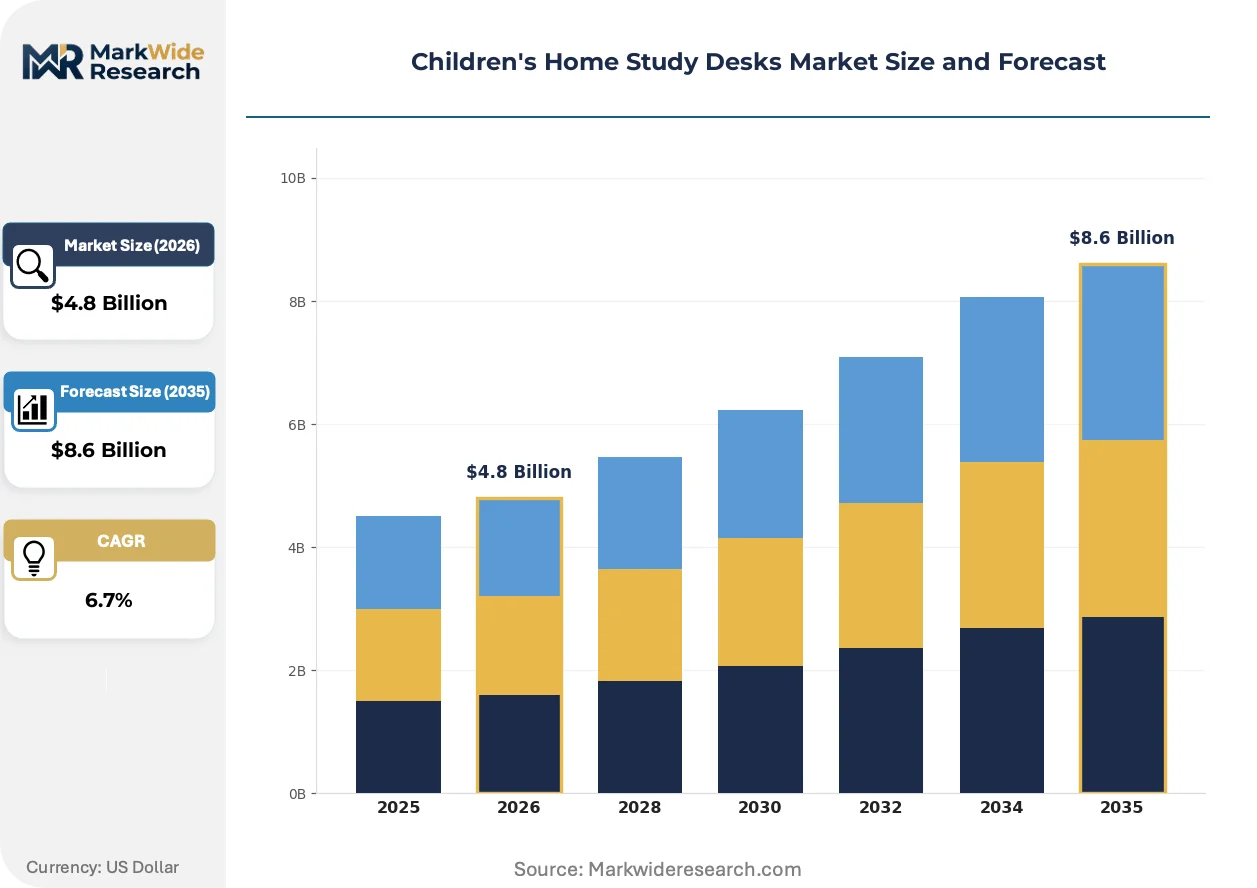
Market Dynamics
Hybrid learning permanence has converted temporary pandemic purchases into sustained replacement cycles, with parents now treating study desks as essential furniture rather than discretionary items. This behavioral stickiness is compressing replacement timelines and elevating ergonomic specifications as non-negotiable purchase criteria.
Growth Catalysts
- EU Green Deal material mandates:Certification requirements for sustainable wood and recycled polymers are redirecting manufacturer R&D budgets toward circular supply chains, creating premium positioning for compliant producers.
- Elementary-age household formation:Millennial parents with children entering primary education are prioritizing dedicated learning spaces in multi-functional apartments, driving compact-format demand.
- Adjustable-height engineering advances:Pneumatic and electric lift mechanisms from adjacent office furniture sectors are migrating downward into children's SKUs, extending usable product lifespan across growth stages.
Market Restraints
- Certified wood input cost volatility:FSC and PEFC lumber carries 15-30% premiums over conventional alternatives, compressing margins for mid-market manufacturers without brand pricing power.
- China manufacturing concentration:Overreliance on Zhejiang and Guangdong province production clusters exposes supply chains to regional logistics disruptions and energy rationing protocols.
- REACH chemical compliance friction:ECHA substance restrictions on surface coatings and adhesives force reformulation cycles that delay EU market entry by 6-12 months for new entrants.
Strategic Opportunities
- India tier-2 urban expansion:BIS certification creates defensible moats for early movers in cities like Pune and Ahmedabad where organized furniture retail penetration remains below 15%.
- Smart-desk technology convergence:Integration of posture sensors and ambient lighting controls with traditional furniture frames opens subscription-service revenue models for hardware manufacturers.
- Direct-to-parent digital channels:Social commerce platforms are collapsing traditional furniture retail markups, enabling vertically integrated brands to capture full margin stack.
Industry Challenges
- Ergonomic certification talent scarcity:Shortage of credentialed furniture safety engineers familiar with GB standards, EN norms, and ASTM protocols simultaneously is delaying multi-market product launches.
- Cross-border regulatory misalignment:Divergent gap-dimension requirements between China's GB 28007 and EU's EN 747 create SKUs that cannot share component tooling, fragmenting production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children's Home Study Desks Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Desks, Adjustable Desks, L-Shaped Desks, Writing Desks Material: Wood, Metal, Plastic, Glass Age Group: Toddlers, Preschoolers, Elementary School, Middle School Design Style: Modern, Classic, Minimalist, Themed |
| Companies Covered | Loctek, Xihao, Guidecraft, Elk and Friends, Unicoo, Utex, Vivo, Pottery Barn Kids, Winsns, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children's Home Study Desks Market Trends and Innovations
Product development cycles in children's furniture are compressing as safety standards tighten and parental expectations migrate from basic functionality toward wellness-integrated design. Manufacturers now compete on developmental appropriateness rather than durability alone.
Modular desk systems with tool-free reconfiguration are displacing fixed-height legacy formats in urban markets. Parents of children aged 6-12 are adopting these systems at twice the rate of conventional alternatives. The shift is compressing average selling prices per unit while expanding lifetime value through accessory attachment sales.
REACH restrictions on formaldehyde-emitting composite boards are forcing substrate transitions toward solid wood and engineered bamboo across European-bound production. Manufacturers serving Germany and France are accelerating water-based finish adoption ahead of 2025 enforcement milestones. The regulatory pressure is advantaging producers with captive timber processing capabilities.
Subscription-based furniture-as-a-service models are emerging among digitally native parents who reject ownership of rapidly outgrown items. Retailers in Shanghai and Shenzhen are piloting return-and-refresh programs that replace desks as children age. The behavioral pivot is most visible among dual-income households prioritizing space flexibility over asset accumulation.
Children's Home Study Desks Market Segmentation
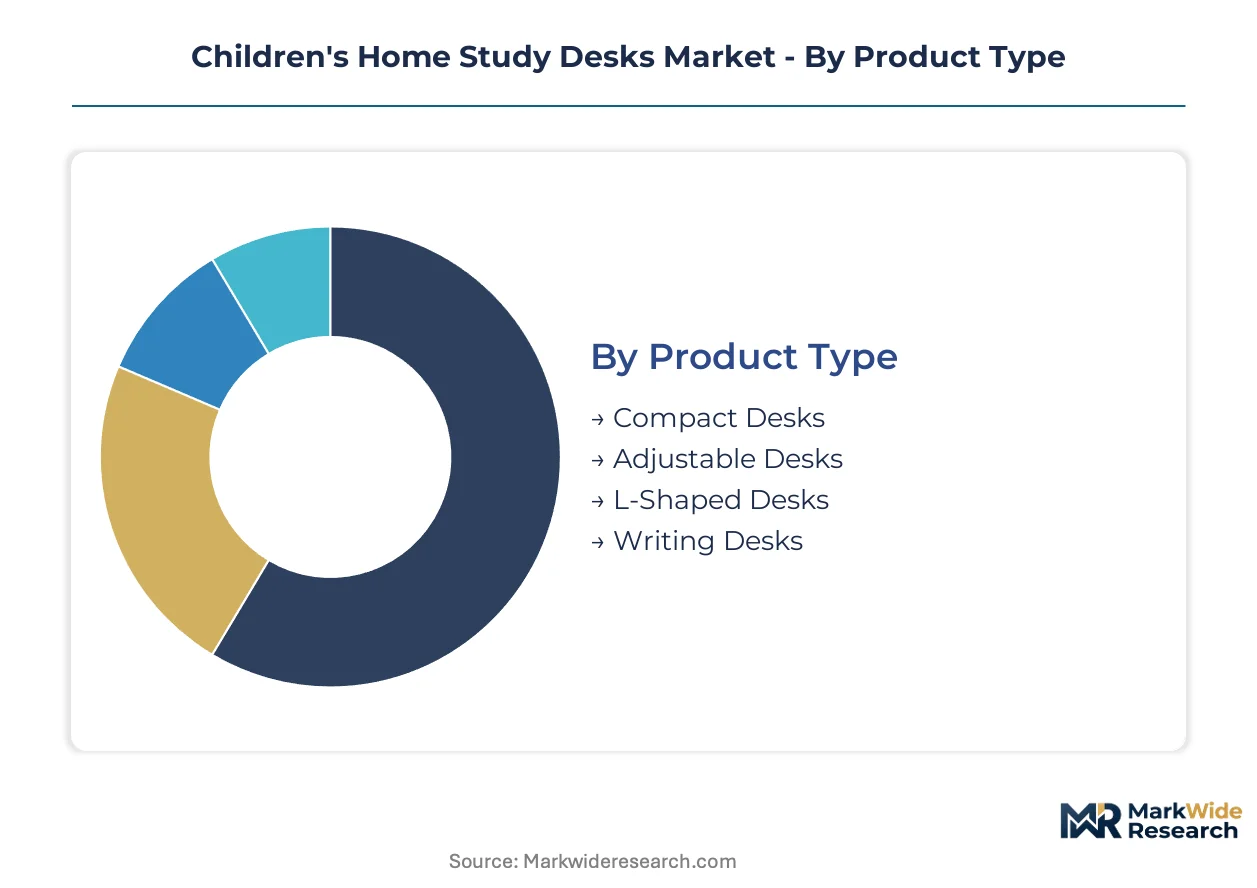
Segmentation in children's home study desks reveals how purchasing decisions split between space-constrained urban parents and design-focused households. Manufacturers configure production lines around these divides, with material sourcing and safety certification requirements varying sharply across each axis.
Product Type:
Domestic demand in China and India concentrates on compact formats for dense urban housing, while export markets toward Germany and France prioritize adjustable mechanisms with ergonomic certification.
- Compact Desks:Fixed-dimension units typically spanning 80-100cm widths with integrated storage cubbies. Demand clusters in Shanghai, Mumbai, and Shenzhen apartment complexes where floor space averages under 60 square meters; parents sacrifice surface area for footprint efficiency.
- Adjustable Desks:Height-modifying frames using pneumatic cylinders or manual crank systems accommodating seated heights from 45cm to 75cm. German and French buyers drive specification intensity here, requiring EN 747 stability compliance and multi-year growth-stage coverage.
- L-Shaped Desks:Corner-fitting configurations maximizing wall-adjacent surface area for multi-monitor or craft-supply setups.
- Writing Desks:Traditional flat-surface designs emphasizing simplicity and lower price points for temporary or secondary learning spaces.
Compact desks hold the largest share; momentum sits with adjustable desks.
Material:
Cost tiers separate certified sustainable inputs from mass-market alternatives, with REACH and GB standards forcing substrate migrations that fragment supplier bases.
- Wood:Solid timber and engineered variants commanding premium positioning through FSC or PEFC chain-of-custody documentation. European Union Green Deal procurement rules and parental preference for natural finishes in Stuttgart and Milan sustain demand despite 15-30% cost premiums over conventional alternatives.
- Plastic:Recycled polymer and virgin polypropylene formats competing on entry-price accessibility. Indian mass-market channels and Chinese e-commerce platforms move volume here, though BIS and GB standards for structural rigidity constrain formulation flexibility.
- Metal:Steel and aluminum framing components providing structural stability for adjustable mechanisms.
- Glass:Tempered surface treatments appearing in premium aesthetic configurations with limited penetration due to weight and safety certification complexity.
Wood dominates value capture; plastic expands most quickly in unit terms.
Age Group:
Customer type determines dimensional specifications and safety feature intensity, with regulatory thresholds stepping up for younger cohorts.
- Elementary School:Children aged 6-12 requiring seated heights from 50cm to 65cm and load-rated surfaces for tablet and laptop use. Millennial parent households in Beijing, Bangalore, and São Paulo treat this as essential furniture, compressing replacement cycles and elevating ergonomic requirements.
- Preschoolers:Ages 3-5 needing rounded-edge construction and anti-tip anchoring under GB 28007 and ASTM F2057 protocols. Safety certification costs filter out smaller manufacturers in this segment.
- Toddlers:Under-3 demographic with the most stringent gap-dimension and chemical-emission constraints.
- Middle School:Teen-oriented designs approaching adult furniture dimensions with reduced growth-adjustment needs.
Elementary School commands the deepest buyer commitment; Preschoolers show the steepest expansion trajectory as early-education investment rises.
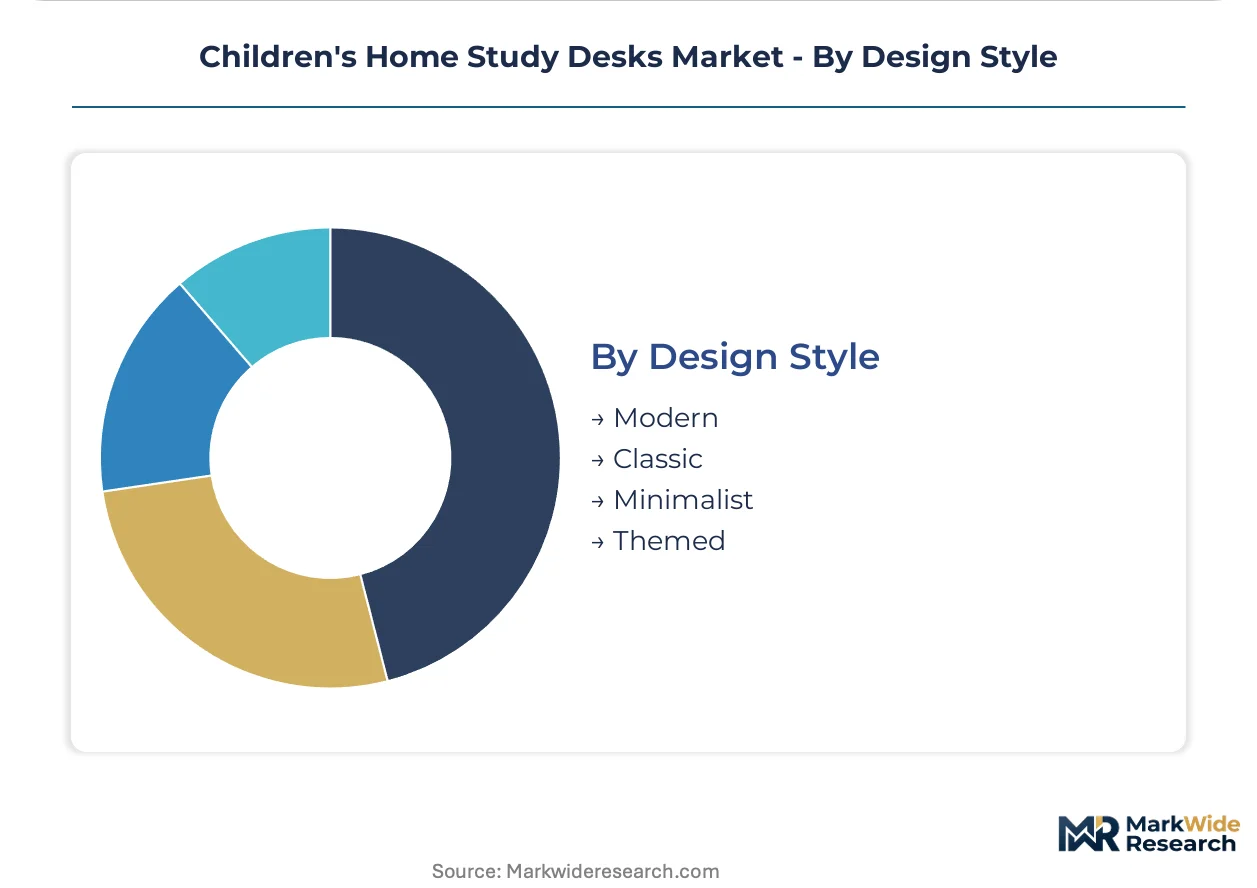
Design Style:
Application context splits between distraction-minimized study environments and bedroom-integrated aesthetic statements.
- Modern:Clean lines, neutral palettes, and hidden cable management appealing to design-conscious parents in Copenhagen and Amsterdam. This segment captures the highest margin per unit through material quality signaling.
- Minimalist:Reduced-component construction emphasizing visual calm and spatial efficiency. Japanese and South Korean urban buyers drive specification here, with Muji-influenced retailers in Tokyo and Seoul commanding loyalty through restraint.
- Classic:Traditional joinery and heritage aesthetic references for bedroom-furniture coordination.
- Themed:Character-licensed or color-saturated designs targeting younger children's preferences with shorter usable lifespans.
Modern styling leads revenue concentration; Minimalist formats gain share fastest among dual-income professional households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards from China's State Administration for Market Regulation anchor the dominant geography, where dense urban housing and dual-income household formation drive compact-format demand. Regulatory divergence between major markets fragments production tooling and compliance pathways.
China
Shanghai and Shenzhen apartment complexes under 60 square meters prioritize footprint-efficient desks with integrated storage. GB 28007 mandates anti-tip anchoring and gap-dimension testing that shapes structural design for domestic production. Zhejiang and Guangdong province manufacturing clusters concentrate adjustable-height engineering capacity.
Germany
Stuttgart and Munich households demand EN 747-certified adjustable mechanisms with multi-year growth-stage coverage. EU Green Deal procurement rules redirect sourcing toward FSC-certified timber and water-based finishes. Bavarian furniture fabricators accelerate solid wood transitions ahead of 2025 REACH enforcement milestones.
United States
EPA formaldehyde emission limits on composite wood products filter substrate selection for products serving California and Northeast corridor markets. Millennial parents in Austin and Denver treat dedicated study furniture as essential rather than discretionary. Pacific Northwest retail channels emphasize ergonomic certification as a non-negotiable purchase criterion.
India
Pune and Ahmedabad tier-2 urban expansion creates defensible moats for organized furniture retail penetration below 15%. BIS certification requirements for children's furniture create incremental compliance costs that filter imported desk assemblies. Maharashtra and Gujarat production clusters serve domestic mass-market channels with plastic-format accessibility.
France
Paris and Lyon design-conscious buyers sustain premium positioning for natural wood finishes despite cost premiums. ECHA substance restrictions on surface coatings force reformulation cycles that delay market entry. Île-de-France distribution networks prioritize REACH-compliant water-based finishes ahead of regulatory deadlines.
Children's Home Study Desks Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure with limited overlap between premium ergonomic specialists and mass-market assemblers. The vendor base splits across three strategic archetypes: adjustable-height engineering specialists, early-childhood safety certification leaders, and vertically integrated mass-market producers. Dominant competitive moves include geographic expansion into underpenetrated tier-2 cities and portfolio diversification toward subscription-based furniture-as-a-service models.
Among the adjustable-height engineering tier, Loctek and Vivo occupy positions representing pneumatic and electric lift mechanism migration from adjacent office furniture sectors. Guidecraft anchors the early-childhood specialization vector through safety certification intensity for preschool-aged demographics. Xihao sits within the cost-optimized mass-market archetype serving Chinese e-commerce platform volume. These three exemplify how divergent capability investments create non-overlapping competitive territory.
| Leading Market Players |
|---|
| Loctek |
| Xihao |
| Guidecraft |
| Elk and Friends |
| Unicoo |
| Utex |
| Vivo |
| Pottery Barn Kids |
| Winsns |
| Others |
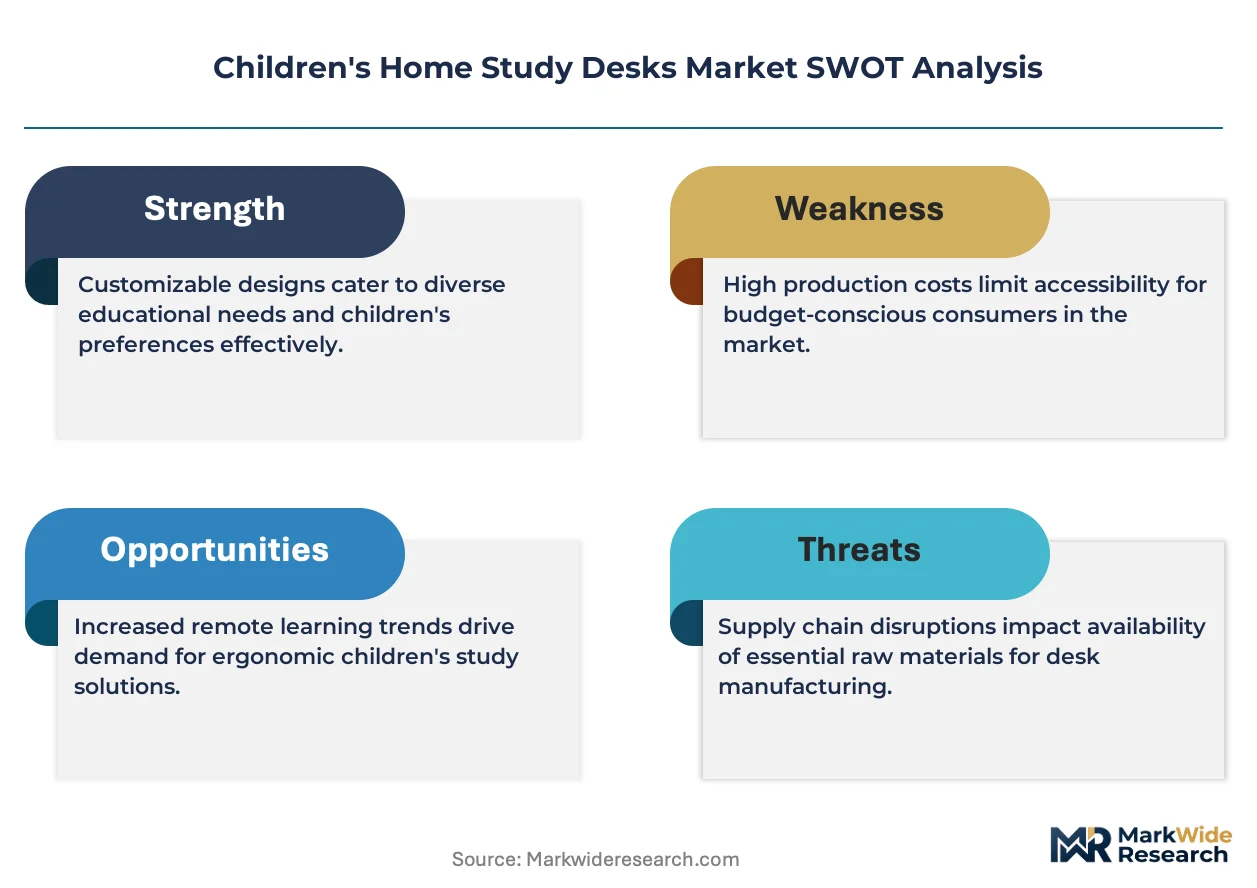
Pricing and Supply Chain Analysis
Water-based finish substitution for solvent-based coatings is simultaneously relocating production toward captive timber processors in Bavaria and Zhejiang while compressing margin structures for manufacturers lacking in-house finishing capabilities. This input transition feeds directly into pricing power concentration among vertically integrated producers who control both substrate sourcing and surface treatment.
Pricing Analysis
Price spreads between Stuttgart and Ahmedabad exceed threefold for equivalent adjustable-height configurations. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified solid wood offerings from engineered board alternatives and virgin polypropylene entry formats. Cost compression in the mid-market tier is intensifying because REACH reformulation cycles and BIS certification delays extend new product development timelines. Mass-market Indian buyers exhibit highest price sensitivity, while German design-conscious households accept substantial premiums for EN 747 compliance and natural finish aesthetics.
Supply Chain Analysis
Malacca Strait container throughput underwrites just-in-time delivery schedules for European-bound finished goods from Guangdong province clusters. Manufacturing gravity draws from Zhejiang and Guangdong in China, Maharashtra and Gujarat in India, and Bavaria in Germany. Raw material dependencies center on FSC-certified timber from Nordic and Baltic sources, pneumatic lift mechanisms from Taiwanese component specialists, and water-based resin formulations from German chemical producers. Single-source vulnerability concentrates in adjustable-height actuator supply from three dominant Taiwanese OEMs. Distribution runs through organized furniture retail chains in developed markets and platform-integrated direct-to-parent digital channels in Chinese tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ergonomic certification talent scarcity defines competitive moats in this market, with credentialed engineers capable of navigating simultaneous GB, EN, and ASTM protocols commanding premium compensation and extending product launch timelines for uncredentialed competitors.
For Market Incumbents: Consolidate adjustable-height engineering capabilities through selective acquisition of pneumatic lift mechanism specialists in Taiwan and Zhejiang. Deepen captive timber processing in Bavaria and Nordic regions to secure water-based finish supply ahead of REACH enforcement milestones. Channel control through exclusive partnerships with Shanghai and Shenzhen furniture-as-a-service platforms defends against direct-to-parent digital entrants eroding traditional retail markups.
For New Entrants and Emerging Players: Anchor in Indian tier-2 cities such as Pune and Ahmedabad where organized retail penetration remains below fifteen percent and BIS certification creates defensible barriers against imported assemblies. Target the preschooler demographic where safety certification intensity filters out smaller manufacturers and early-childhood design specialization commands loyalty from millennial parents. A direct-to-parent social commerce go-to-market angle collapses traditional distribution markups and enables full margin capture.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed adjustable-height engineering specialists who have exhausted geographic expansion options and now require portfolio diversification into adjacent children's furniture categories. Long-term viability over a five-to-ten year horizon rests on subscription-based furniture-as-a-service model adoption rates among dual-income urban households prioritizing space flexibility. Acquisition targets should display captive certification capabilities across multiple regulatory jurisdictions. The signal to watch is pilot program expansion of return-and-refresh desk replacement schemes in Shanghai and Shenzhen.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | Multi-jurisdictional GB, EN, and ASTM compliance accelerates product launches across China, Germany, and US markets. |
| Backward Integration | Captive timber processing in Bavaria secures water-based finish supply ahead of REACH enforcement deadlines. |
| Direct-to-Parent Digital Launch | Social commerce platform integration collapses traditional retail markups for Shanghai and Shenzhen households. |
| Geographic Expansion | Tier-2 Indian city penetration exploits BIS certification barriers filtering imported desk assemblies. |
| Subscription Service Model | Furniture-as-a-service pilots in dense urban housing address millennial rejection of rapidly outgrown asset ownership. |
Research Methodology
A standing panel of furniture safety engineers, procurement leads at organized retail chains, category buyers at direct-to-parent digital platforms, and regulatory affairs specialists at certification bodies provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against customs records, GB and EN standard filings, BIS certification databases, and SEC disclosures from publicly traded furniture manufacturers. Bottom-up demand modeling across product type, material, age group, and design style segments triangulated against top-down macroeconomic indicators.
Consistency checks validated volume and value outputs against external benchmarks including production cluster capacity disclosures from Zhejiang and Guangdong provinces, retail audit data from European furniture trade associations, and platform transaction volumes from Chinese e-commerce operators. The analytical framework modeled growth trajectories across the projection horizon by product type, material substrate, age demographic, and regional regulatory cluster. CAGRs derived from segment-level demand elasticity analysis incorporating household formation rates, urban housing density metrics, and parental workforce flexibility indices.
Material uncertainties — regulatory enforcement timing on REACH water-based finish mandates, energy rationing protocols affecting Zhejiang manufacturing clusters, and subscription model adoption rates among dual-income households — sit outside the modeled envelope. Forecasts reflect documented assumptions on hybrid learning permanence and ergonomic specification elevation as non-negotiable purchase criteria. Practitioners should keep alternative scenarios live as EU Green Deal procurement rule implementation and China dual carbon policy enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Armchair on Casters Market
Furniture
China Furniture Market
Furniture
Australia Smart Furniture Market
Furniture
HORECA Furniture Market
Furniture
Vietnam Home Furniture Market
Furniture
Bar Stools Market
Furniture
Europe Smart Furniture Market
Furniture
United States Upholstered Furniture Market
Furniture
Germany Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
GCC Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
Salon Chairs Market
Furniture
Global Multifunctional Furniture Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
China Upholstered Furniture Market