
 Cabinet Market | 2026-2036
Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Cabinet Market Analysis
Modular cabinet configuration is pivoting buyer preference toward pre-assembled, flat-pack systems that reduce installation labor and enable mass customization. IKEA leverages its global retail footprint to dominate this format, while MasterBrand Cabinets sustains manufacturing scale across multiple price tiers. Wellborn Cabinet differentiates through made-to-order specialization in solid wood construction, and American Woodmark anchors supply relationships with national homebuilders through dedicated production capacity.
Cabinets are rigid, box-like storage furniture typically constructed from engineered wood panels, solid lumber, or metal substrates, joined via dowel, cam-lock, or face-frame assembly methods and finished with laminates, thermofoil, or paint coatings to resist moisture and abrasion in kitchen, bath, and commercial environments. Base cabinets and wall cabinets together constitute the volume core, with tall cabinets and specialty units capturing premium margin pools in custom residential and healthcare applications. Wood and laminate materials lead residential specification, while metal and MDF gain traction in commercial and cost-optimized segments where durability and uniformity outweigh aesthetic warmth.
EPA TSCA Title VI formaldehyde standards, CARB Phase 2 limits, and EU E1/E0 emission classifications constrain panel substrate selection and finishing chemistry across major supply regions. Compliance with these frameworks elevates sourcing costs for imported components but simultaneously creates market access barriers that favor domestic producers with certified supply chains. Stakeholders must monitor evolving material certification requirements and assess whether captive panel production or third-party verified sourcing delivers superior cost and compliance positioning.
Market Dynamics
Residential renovation intensity and EPA formaldehyde emission standards are restructuring cabinet procurement toward certified domestic supply chains and modular flat-pack formats that compress installation labor.
Growth Catalysts
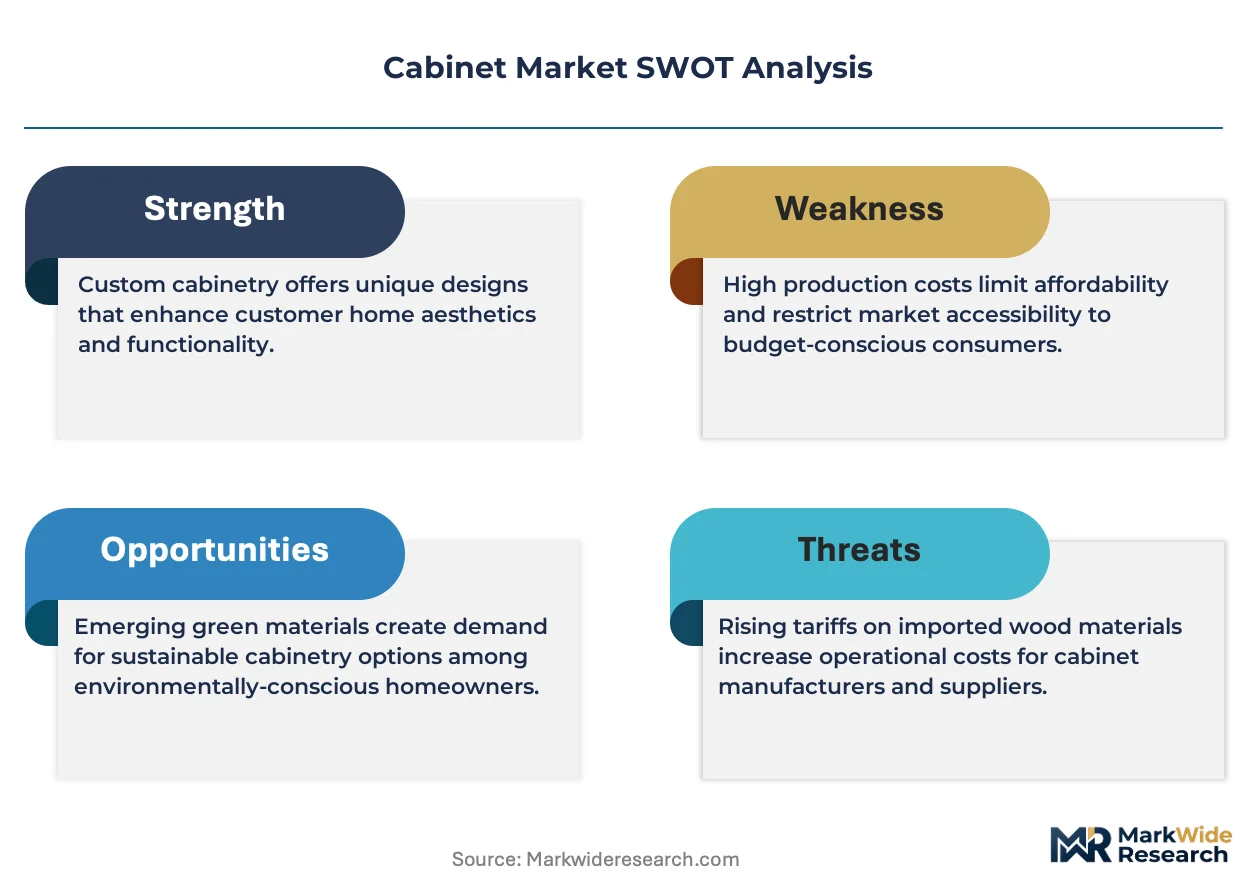
- CARB Phase 2 compliance:California's composite wood emission limits are accelerating certified panel adoption across North American manufacturing, creating sourcing advantages for domestic producers with verified supply chains.
- Modular flat-pack systems:Pre-assembled cabinet configurations are displacing site-built alternatives in residential kitchen renovations by reducing skilled labor requirements and enabling mass customization.
- Housing stock age:The United States maintains substantial vintage housing inventory where replacement cycles for kitchen and bath storage systems generate sustained demand pull.
Market Restraints
- Engineered wood panel cost volatility:MDF and particleboard substrate prices fluctuate with resin chemistry and forestry input costs, compressing margin predictability for volume manufacturers.
- Import certification friction:EPA TSCA Title VI documentation requirements create customs delays for offshore panel sourcing, elevating landed costs versus domestic alternatives.
- Skilled installation labor scarcity:Cabinet fit-out demands finish carpentry expertise that remains concentrated in aging trade populations, constraining project velocity in high-renovation markets.
Strategic Opportunities
- Healthcare facility specification:Antimicrobial cabinet surfaces and seamless thermofoil finishes are penetrating hospital and clinic storage applications where infection control protocols dominate material selection.
- EU E0 emission tier:European ultra-low formaldehyde classifications are creating premium positioning opportunities for manufacturers with captive panel production and third-party verification infrastructure.
- Direct-to-contractor digital channels:Configurator platforms are bypassing traditional distributor networks, enabling manufacturers to capture margin and reduce specification leakage to competing brands.
Industry Challenges
- Multi-certification management:Simultaneous compliance with EPA, CARB, and EU emission frameworks requires dedicated regulatory staff and testing budgets that burden mid-tier producers.
- Legacy ERP integration:Made-to-order cabinet specialists face system incompatibility when connecting configure-price-quote platforms to existing production scheduling software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cabinet Market |
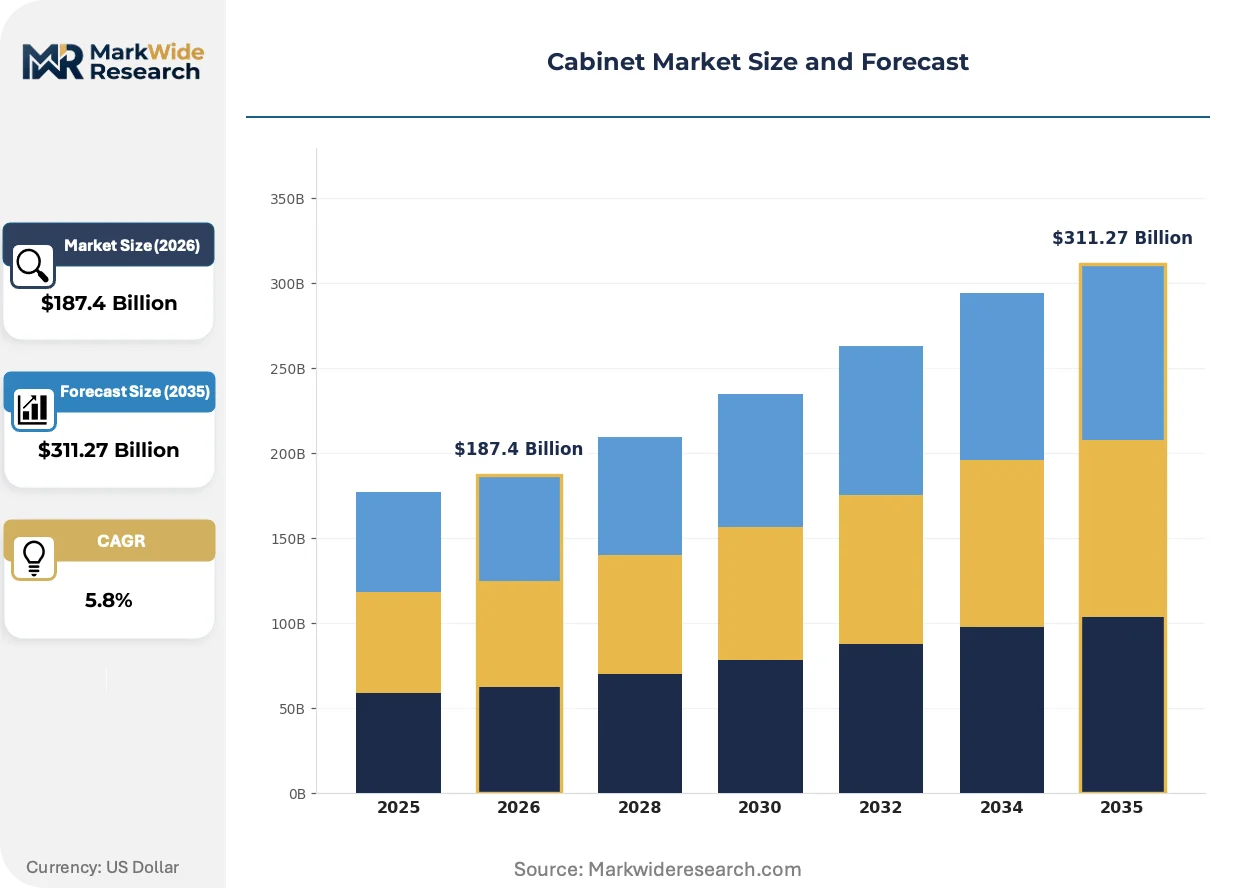
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Cabinets, Wall Cabinets, Tall Cabinets, Specialty Cabinets Material: Wood, Metal, Laminate, MDF End User: Residential, Commercial, Industrial, Retail Style: Modern, Traditional, Rustic, Shaker |
| Companies Covered | IKEA, Nobia, MasterBrand Cabinets, Wellborn Cabinet, Merillat, American Woodmark, KraftMaid, Oppolia Home, Cabinetworks Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cabinet Market Emerging Trajectories
Digital configuration tools and emission-certified material science are compressing traditional specification cycles while elevating compliance documentation to a competitive differentiator in residential and commercial procurement.
Thermally fused laminate (TFL) surfacing technology is unifying decorative aesthetics with abrasion resistance in cost-optimized cabinet segments. Multi-family developers and property management portfolios are specifying TFL at expanding rates for durability in high-turnover residential units. This material convergence is compressing the performance gap between premium veneer and economy laminate, forcing mid-market suppliers to reposition on service velocity rather than material distinction.
EPA TSCA Title VI formaldehyde standards are mandating chain-of-custody documentation for all composite wood products entering US commerce. The regulation requires third-party certification of panel mills and finished goods importers, elevating compliance infrastructure costs. Kitchen cabinet manufacturers with captive particleboard production or long-term domestic supplier contracts are capturing specification preference from builders facing liability exposure.
Homebuilder direct procurement is consolidating specification authority away from traditional kitchen dealers and remodeling contractors. National production builders now maintain approved manufacturer lists with dedicated capacity allocations, compressing distributor intermediary roles. This channel compression is most visible in the United States, where top-ten homebuilders command sufficient volume to negotiate exclusive product lines and priority production scheduling.
Cabinet Market Segmentation
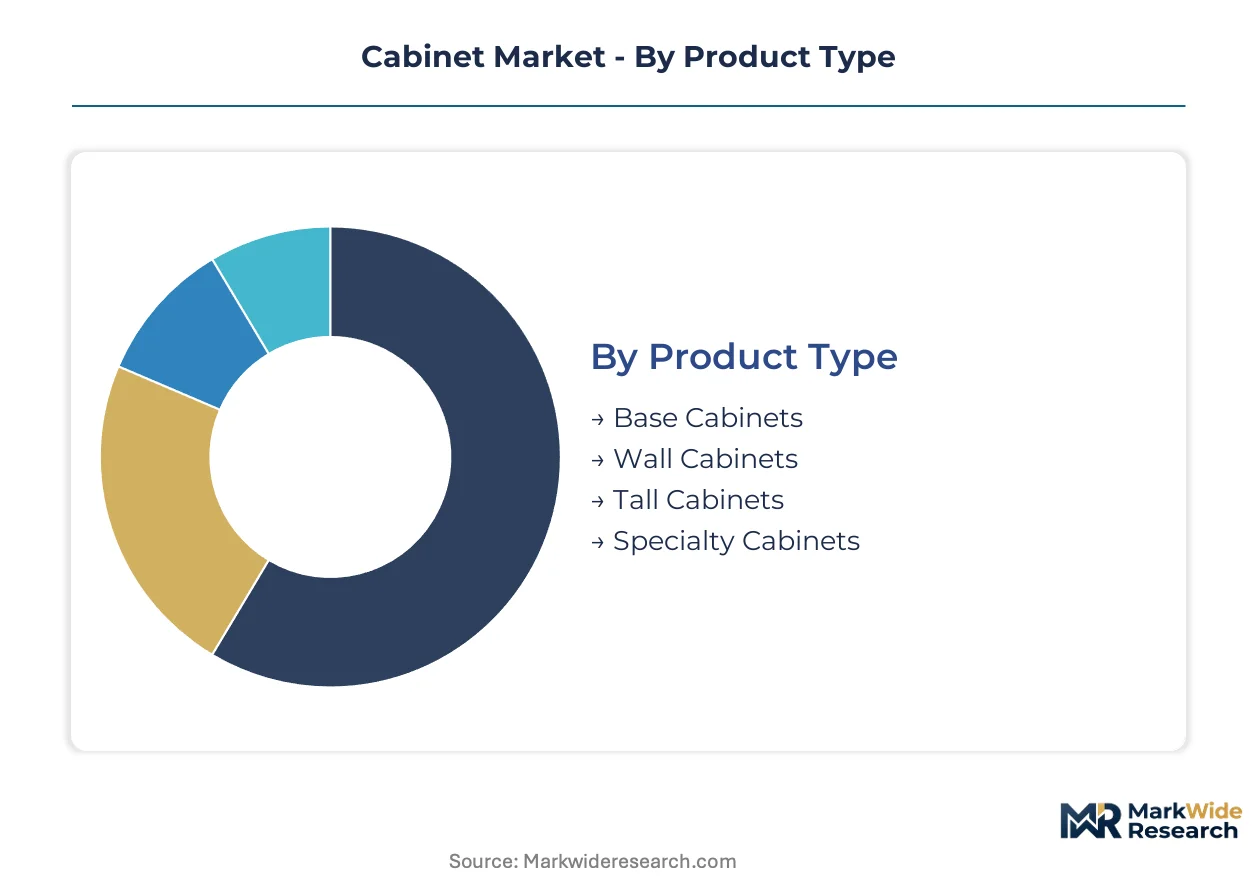
Cabinet procurement decisions bifurcate between volume-driven replacement cycles and specification-intensive new construction. Understanding segment boundaries clarifies where material certification, installation labor, and design customization exert pricing leverage.
Product Type:
Base cabinets dominate unit volume while tall cabinets command premium positioning through vertical storage optimization.
- Base Cabinets:Floor-mounted units with countertop support functions constitute the procurement volume core across residential kitchen renovations. Demand concentrates in the United States where aging housing stock sustains replacement cycles for sink and cooktop housing configurations.
- Wall Cabinets:Overhead storage units mounted at ergonomic heights capture specification priority in space-constrained urban kitchens. Installation labor scarcity elevates demand for pre-assembled configurations that reduce field fitting time.
- Tall Cabinets:Full-height pantry and utility units command margin premiums through integrated appliance housing and pull-out storage systems.
- Specialty Cabinets:Corner units, appliance garages, and custom dimensions serve niche renovation requirements with extended lead times.
Today's leader: Base Cabinets. Tomorrow's challenger: Tall Cabinets.
Material:
Material selection trades emission compliance burden against surface durability and aesthetic warmth in end-use environments.
- Wood:Solid lumber and veneer constructions dominate premium residential specification where natural grain patterns command price premiums. EPA TSCA Title VI documentation requirements favor domestic producers with certified supply chains over import-dependent competitors.
- Metal:Steel and aluminum substrates penetrate healthcare and commercial applications where antimicrobial surface protocols and impact resistance outweigh thermal conductivity concerns.
- Laminate:Thermally fused and high-pressure laminate surfaces unify decorative breadth with abrasion resistance in cost-optimized multi-family housing.
- MDF:Medium-density fiberboard enables intricate routed profiles and painted finishes with uniform substrate density.
Wood retains specification authority at the premium tier. Metal is gaining fastest in institutional procurement.
End User:
Customer type determines whether procurement flows through retail channels or direct manufacturer relationships.
- Residential:Single-family and multi-family housing drives volume demand through renovation and new construction cycles. Homebuilder direct procurement is consolidating specification authority away from traditional kitchen dealers.
- Commercial:Office, hospitality, and institutional fit-outs specify durability-rated hardware and modular reconfiguration capability.
- Industrial:Workshop and manufacturing facility storage prioritizes load-bearing capacity and chemical resistance over aesthetic considerations.
- Retail:Point-of-sale fixtures and display cabinetry demand rapid turnaround and brand-coordinated finishes.
Residential commands current volume concentration. Commercial offers the steepest expansion trajectory through healthcare facility specification.
Style:
Aesthetic categorization aligns manufacturing batch economics with regional design preferences and housing architectural periods.
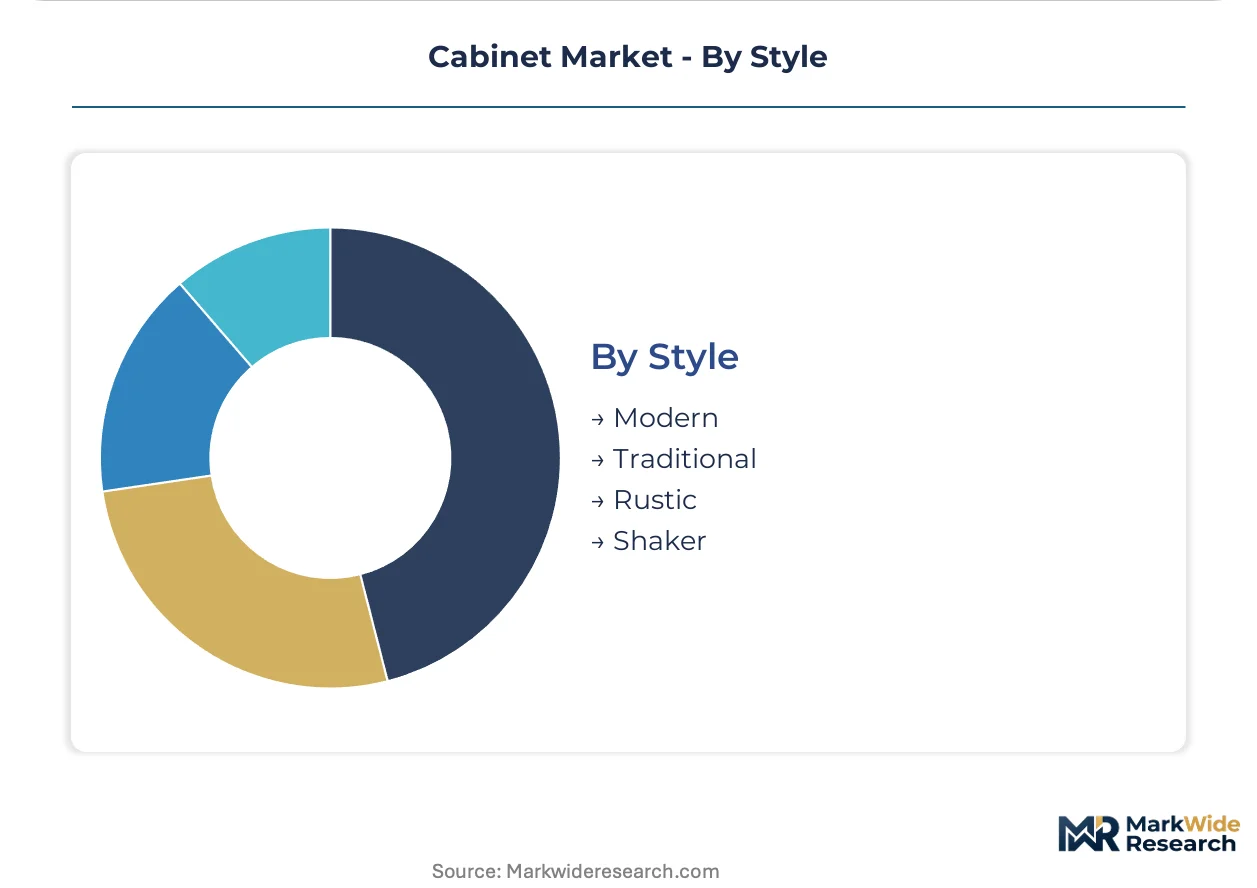
- Modern:Flat-panel slab doors with minimal ornamentation align with contemporary architecture and European import aesthetics. Thermofoil and high-gloss lacquer finishes dominate this specification tier.
- Traditional:Raised-panel profiles with decorative molding satisfy replacement demand in vintage housing stock where architectural continuity influences resale value.
- Rustic:Distressed finishes and reclaimed wood appearances serve vacation property and farmhouse renovation segments with authenticity signaling requirements.
- Shaker:Five-piece recessed panel construction balances transitional appeal across demographic cohorts with manufacturing simplicity that supports flat-pack distribution.
Shaker styling bridges contemporary and traditional preferences with production scalability. Modern styling is climbing fastest in urban infill construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cabinet industry traces its modern mass-production origins to post-war Sweden, where flat-pack engineering and democratic design principles first merged to create scalable kitchen storage systems for global export.
United States
Vintage housing stock averaging 40-plus years sustains replacement demand for kitchen and bath renovations. EPA TSCA Title VI formaldehyde standards mandate third-party certification for all composite wood products, elevating compliance costs for import-dependent distributors. Manufacturing clusters concentrate in Indiana and Virginia, where dedicated production lines serve national homebuilder direct procurement programs.
Germany
Precision engineering traditions support premium cabinetry specification across European residential and commercial fit-outs. EU E1 and E0 emission classifications under REACH framework constrain panel substrate selection, favoring domestic producers with captive supply chains. Industrial concentration in North Rhine-Westphalia hosts integrated manufacturing corridors linking panel mills to finished goods assembly.
China
Urbanization and middle-class expansion drive modular kitchen adoption in tier-one and tier-two cities. GB standards for formaldehyde emission in wood-based panels align with stricter domestic environmental enforcement under MEE directives. Manufacturing gravity centers on Guangdong and Zhejiang provinces, where export-oriented production hubs supply flat-pack systems to Southeast Asian and Middle Eastern markets.
Canada
Housing market resilience and cross-border supply chain integration sustain demand for certified domestic production. Health Canada and PMRA coordinate with EPA on aligned emission standards, reducing friction for integrated North American manufacturing. Ontario and British Columbia anchor production capacity serving both domestic renovation cycles and US export channels.
Japan
Space-constrained urban housing elevates demand for compact, multi-functional storage systems with precise dimensional tolerances. JIS standards for building materials and METI energy efficiency guidelines influence cabinet specification in residential construction. Industrial clusters in Aichi and Shizuoka prefectures maintain specialized production for domestic renovation and replacement markets.
Cabinet Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification and installation service dimensions, creating a tiered structure where domestic supply chain verification commands specification preference. The vendor base spans multinational retail networks, dedicated manufacturing specialists, and regional fabricators with localized installation capabilities. Three archetypes dominate: flat-pack mass retailers with global sourcing infrastructure, made-to-order specialists emphasizing solid wood construction, and homebuilder-aligned producers with dedicated capacity allocations. Competitive dynamics center on backward integration into panel production and digital configuration platforms that compress specification cycles.
Among scale-driven manufacturers, MasterBrand Cabinets and American Woodmark occupy positions aligned with national homebuilder procurement consolidation. Wellborn Cabinet exemplifies the made-to-order specialization archetype, while IKEA anchors the flat-pack retail format globally. These three entities represent distinct strategic postures within a market where certification infrastructure and channel access determine competitive viability.
| Leading Market Players |
|---|
| IKEA |
| Nobia |
| MasterBrand Cabinets |
| Wellborn Cabinet |
| Merillat |
| American Woodmark |
| KraftMaid |
| Oppolia Home |
| Cabinetworks Group |
| Others |
Supply Flow & Price Mechanics
Thermally fused laminate surfacing adoption is compressing production batch economics while simultaneously concentrating panel supply among certified domestic producers with captive resin chemistry capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs cabinet procurement, with EPA TSCA Title VI certification grade and volume scale driving price differentiation. Cost compression in the economy tier is intensifying because MDF substrate prices fluctuate with resin input volatility. Homebuilder direct buyers exhibit lowest price sensitivity due to dedicated capacity allocations, while independent remodeling contractors face acute margin pressure from skilled labor scarcity.
Supply Chain Analysis
Engineered wood panel supply rests on integrated production corridors in the United States, Germany, and China with varying emission certification infrastructure. Raw material dependencies span phenol-formaldehyde resins, decorative paper overlays, and hardwood veneer feeds. Single-source vulnerability concentrates in specialty laminate impregnation lines serving North American certification requirements. Distribution runs through homebuilder direct procurement programs, bypassing traditional kitchen dealer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cabinet market functions as a regulatory compounder where EPA TSCA Title VI formaldehyde standards continuously restructure procurement toward certified domestic supply chains.
For Market Incumbents: Extend backward integration into particleboard production to secure certification documentation and reduce import friction. Deepen digital configuration platform investment to compress specification cycles against emerging flat-pack competitors. Prioritize captive panel production in Indiana and Virginia manufacturing clusters where homebuilder direct relationships anchor volume stability. For New Entrants and Emerging Players: Direct-to-contractor digital channels offer the most penetrable route into specification workflows, bypassing entrenched distributor networks. Target healthcare facility storage applications where antimicrobial surface requirements create premium positioning opportunities. Lead with EU E0 emission tier compliance to differentiate against domestic producers with legacy EPA-only certification. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional fabricators lacking digital configuration infrastructure or captive panel supply. Long-term viability favors manufacturers with verified domestic supply chains over import-dependent competitors facing persistent customs documentation friction. Watch EPA enforcement intensity and potential CARB Phase 2 expansion as the primary inflection signal for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Panel Production | Captive particleboard supply secures EPA TSCA Title VI chain-of-custody documentation against import delays. |
| Digital Configuration Platform Deployment | Configure-price-quote tools compress specification cycles and reduce margin leakage to competing brands. |
| Healthcare Facility Specification Push | Antimicrobial thermofoil surfaces penetrate hospital procurement where infection control dominates material selection. |
| EU E0 Emission Tier Certification | Ultra-low formaldehyde positioning commands premium pricing in export markets with REACH framework alignment. |
| Homebuilder Direct Channel Expansion | Dedicated capacity allocations with national production builders bypass traditional kitchen dealer intermediaries. |
Methodological Framework
Bottom-up residential renovation modeling reconciled against top-down panel production tracking forms the analytical core. Primary interviews with kitchen dealer owners, homebuilder procurement directors, cabinet manufacturing plant managers, and EPA compliance officers combined with secondary validation from EPA TSCA Title VI certification databases, CARB-approved panel mill listings, and housing permit data. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of replacement cycle intensity and material specification shifts informs the projection framework across the analysis window. Segmentation dimensions include product type, material substrate, end-user category, and style archetype. CAGRs derive from regression analysis of housing stock age demographics, renovation spending patterns, and emission standard compliance cost trajectories. Key inputs incorporate skilled labor availability indices and homebuilder direct procurement penetration rates.
The model assumes a particular technology adoption path; alternative pathways for thermally fused laminate surfacing would alter the outlook. Forecasts reflect assumptions regarding EPA enforcement continuity, resin chemistry cost stability, and homebuilder procurement consolidation velocity. A small set of triggers—CARB standard expansion, trade policy shifts on panel imports, and digital configuration platform adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Portering Chair Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Global Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Children's Home Study Desks Market
Furniture
Global Folding Furniture Market
Furniture
Vietnam Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
North America Furniture Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
India Luxury Furniture Market
Furniture
Europe Sustainable Furniture Market
Furniture
Lecterns Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
Wooden Furniture Market