
 Entryway Furniture Market | 2026-2036
Entryway Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Entryway Furniture Market Foresight
Urban apartment dwellers is redrawing demand patterns away from suburban single-family buyers. IKEA leverages flat-pack logistics to dominate entry-level price bands across dense metropolitan markets. Ashley Furniture anchors its position through captive manufacturing of solid wood benches and console tables. Wayfair competes on digital shelf breadth, sustaining inventory advantages in narrow hallway configurations.
Entryway furniture encompasses storage and seating fixtures designed for residential transition zones between exterior and interior living spaces, typically constructed from engineered wood, solid hardwood, powder-coated steel, or woven upholstery composites with dimensional constraints under 48 inches in width for corridor compatibility. The category serves both functional organization and first-impression aesthetics in residential and hospitality settings. Console tables and shoe cabinets command the strongest margin pools as consumers prioritize concealed storage over open display formats. Wood material grades retain premium positioning, though metal frames gain traction in industrial-style specifications among younger homeowner segments. The modern style category leads volume, while rustic finishes sustain regional strength in North American and European rural markets.
EPA formaldehyde emission standards under TSCA Title VI govern composite wood substrates, while California Air Resources Board (CARB) Phase 2 requirements extend compliance burdens for manufacturers distributing in the state. The EU Timber Regulation (EUTR) and evolving deforestation-free supply chain mandates reshape sourcing for European market participants. Stakeholders must monitor regulatory divergence between North American and European chemical compliance frameworks when configuring multi-region product lines.
Market Dynamics
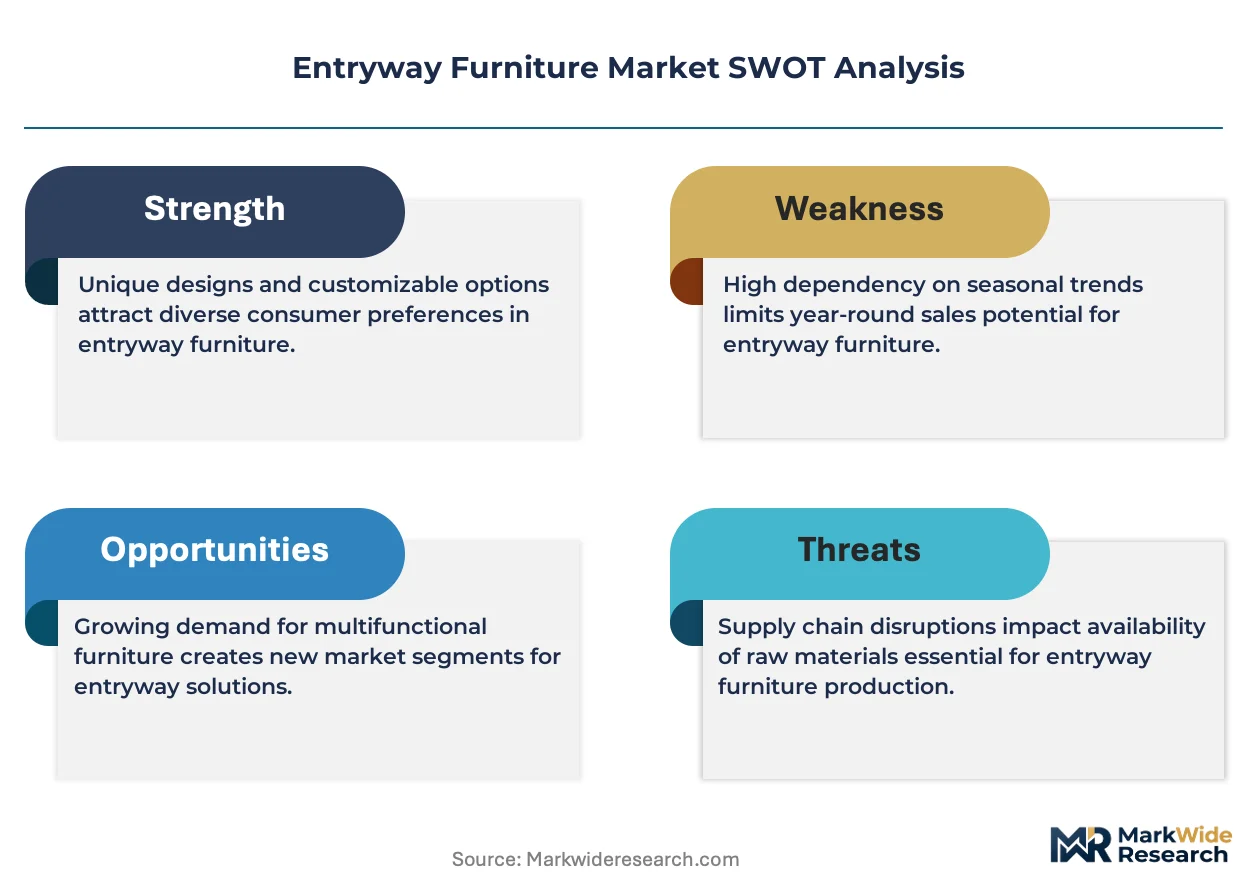
Urban density pressures and California's Title 24 building efficiency standards are compressing entryway furniture dimensions while elevating material compliance burdens for cross-border manufacturers.
Growth Catalysts
- California Title 24 standards:Mandates for energy-efficient residential transition zones accelerate demand for space-optimized storage benches and console tables with integrated LED lighting in new construction.
- EU deforestation-free supply chain rules:Due diligence requirements for timber sourcing favor certified hardwood suppliers, creating competitive advantage for FSC-tracked manufacturers in European distribution channels.
- Engineered wood substrate innovations:Low-emission particleboard and MDF formulations meeting EPA TSCA Title VI thresholds enable mass-market penetration without solid wood cost premiums.
Market Restraints
- Hardwood input cost volatility:Oak and maple price fluctuations tied to North American lumber futures compress margin stability for solid wood bench and console table producers.
- Chinese manufacturing concentration:Powder-coated steel frame production clusters in Zhejiang and Guangdong provinces create single-source vulnerability for industrial-style specification lines.
- Dimensional corridor constraints:The 48-inch width ceiling for hallway compatibility limits premium pricing power on oversized statement pieces in dense metropolitan markets.
Strategic Opportunities
- German Passivhaus retrofit wave:Airtight entry vestibule requirements in energy-efficient home renovations create specification pull for sealed storage benches with thermal break construction.
- Direct-to-installer digital platforms:Contractor-facing procurement portals bypass traditional furniture retail markups, capturing margin from commercial hospitality fit-out projects.
- Metal-wood hybrid construction convergence:Powder-coated steel frames with hardwood tops address both industrial aesthetic demand and durability requirements in high-traffic rental properties.
Industry Challenges
- Multi-jurisdiction chemical compliance:Divergent EPA formaldehyde limits, CARB Phase 2 extensions, and evolving EU REACH substance restrictions force redundant testing protocols for cross-Atlantic product lines.
- Flat-pack assembly skill gaps:Consumer frustration with complex hardware installation drives return rates and negative digital reviews, pressuring brand equity for entry-level price bands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Entryway Furniture Market |
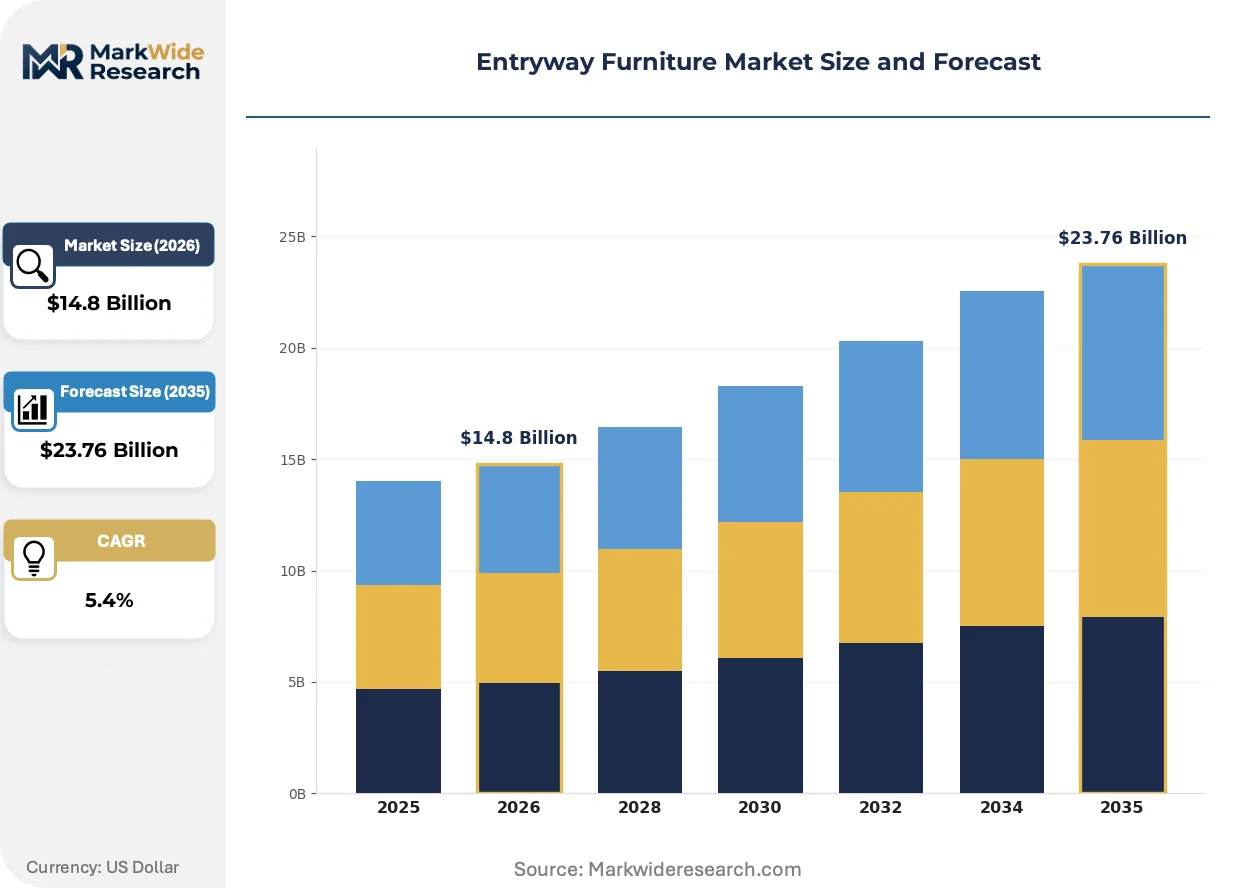
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benches, Coat Racks, Shoe Cabinets, Console Tables Material: Wood, Metal, Plastic, Upholstered Style: Modern, Rustic, Traditional, Industrial Customer Type: Homeowners, Interior Designers, Retailers, Online Shoppers |
| Companies Covered | IKEA, Ashley Furniture, Wayfair, Williams-Sonoma, Sauder Woodworking, West Elm, Home Depot, Herman Miller, Target Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Entryway Furniture Market Shifts & Advancements
Material science advances and procurement channel fragmentation are reconfiguring how entryway furniture reaches residential and commercial buyers, with sustainability credentials and spatial efficiency now table stakes.
Modular storage systems with magnetic or tool-free connection hardware are miniaturizing traditional joinery requirements while maintaining structural integrity. Younger homeowner segments in Tokyo, Seoul, and Singapore apartment complexes adopt these configurations fastest. The technology is miniaturizing assembly footprints to under 15 minutes, compressing the after-sales support burden for direct-to-consumer brands.
REACH substance restrictions on formaldehyde-releasing agents and EU Timber Regulation due diligence mandates are elevating documentation requirements for composite wood substrates. Manufacturers serving European markets now embed blockchain-tracked chain-of-custody certificates at the SKU level. Hospitality specification buyers in Germany and France increasingly disqualify uncertified suppliers from RFP shortlists.
Subscription-based furniture access models are disrupting ownership patterns among urban renters with high relocation frequency. Corporate housing providers and co-living operators in New York, London, and Shanghai pilot monthly console table and storage bench programs. These arrangements bundle damage protection and seasonal style swaps, shifting capital expenditure to operating expense for property managers.
Entryway Furniture Market Segmentation
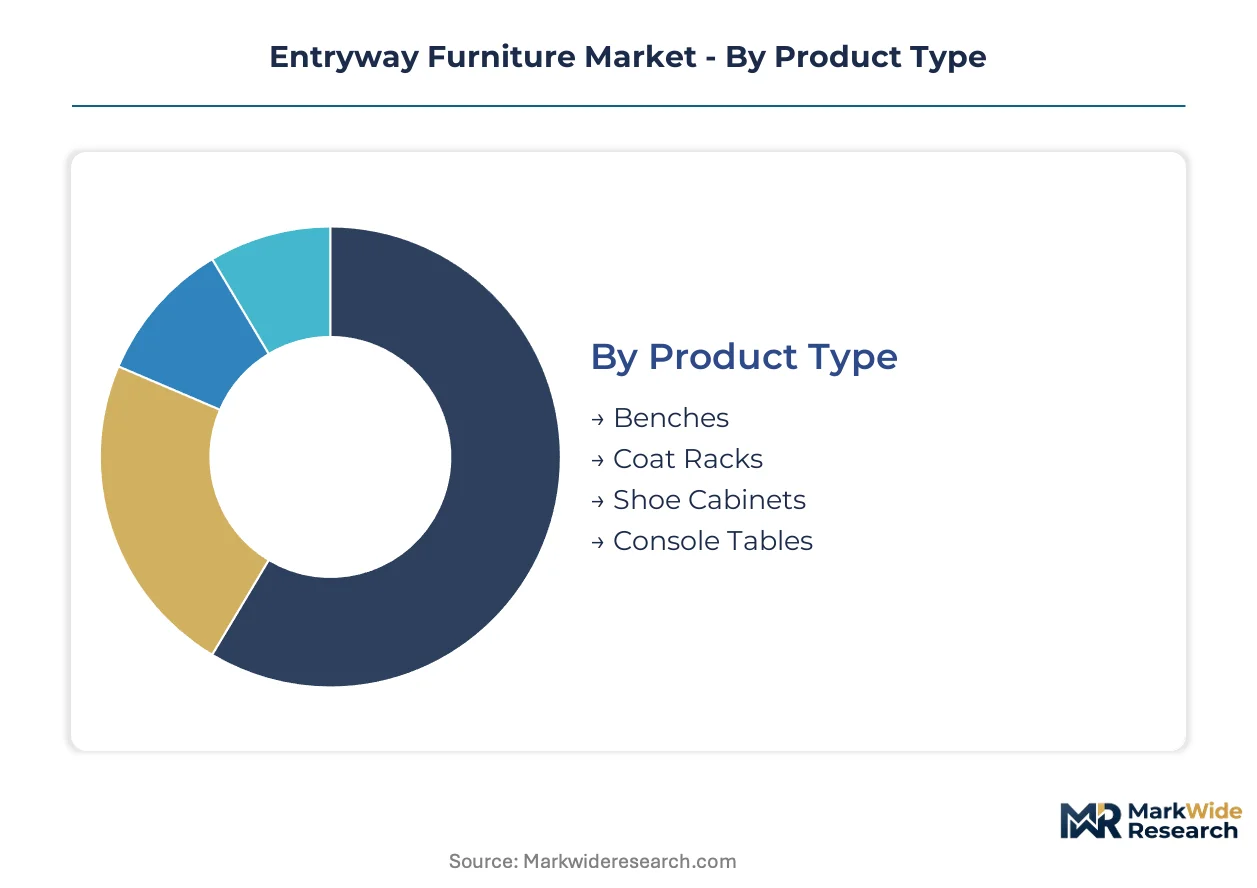
Entryway furniture segmentation reveals how substitution pressures reshape competitive boundaries across product categories. Material choices face displacement from engineered alternatives, while style preferences fragment along generational and geographic lines. Understanding these fault lines exposes where margin pools concentrate and where commoditization threatens.
Product Type:
Substitution pressure runs strongest against open-display formats as concealed storage solutions capture preference shifts in dense urban housing.
- Console Tables:Narrow-profile surfaces, typically 12-16 inches deep, designed for corridor placement with integrated drawer systems or lower shelf storage. Demand concentrates in United States metropolitan corridors where foyers average under 40 square feet, driven by California Title 24 efficiency mandates favoring multi-functional transition zone fixtures.
- Shoe Cabinets:Enclosed vertical storage units with tilted internal shelving or pull-out drawers, constructed to contain odor and conceal clutter. German Passivhaus retrofits specify these for airtight entry vestibules, with thermal break construction requirements elevating specification standards above mass-market alternatives.
- Benches:Seating fixtures with open or concealed storage below, ranging from 36-60 inches in width.
- Coat Racks:Freestanding or wall-mounted vertical hangers for outerwear and accessories.
Console tables anchor the volume base while shoe cabinets gain share at the steepest rate.
Material:
Cost tier stratification separates certified sustainable inputs from commodity substrates facing regulatory compliance burdens.
- Wood:Solid hardwoods and engineered substrates including oak, maple, particleboard, and MDF formulations. EPA TSCA Title VI and CARB Phase 2 emission thresholds filter supplier bases, with FSC-tracked chain-of-custody documentation now mandatory for European distribution channels under EUTR and evolving deforestation-free mandates.
- Metal:Powder-coated steel and aluminum frames, often hybridized with wood tops for industrial aesthetic specifications. Zhejiang and Guangdong province production clusters supply global demand, creating single-source vulnerability for specification lines dependent on Chinese manufacturing concentration.
- Plastic:Injection-molded polypropylene and ABS components for entry-level price bands.
- Upholstered:Fabric or leather-wrapped seating surfaces over foam and composite frames.
Wood materials command premium positioning while metal hybrids expand most quickly among younger homeowner segments.
Style:
Application context determines style selection, with hospitality fit-outs diverging sharply from residential preference patterns.
- Modern:Clean lines, minimal ornamentation, and neutral palettes emphasizing spatial efficiency. Tokyo, Seoul, and Singapore apartment complexes adopt modular modern configurations fastest, with magnetic connection hardware reducing assembly footprints to under 15 minutes.
- Rustic:Distressed finishes, reclaimed wood aesthetics, and farmhouse-inspired proportions. Regional strength persists in North American and European rural markets where traditional architectural contexts demand aesthetic continuity.
- Traditional:Ornate detailing, turned legs, and classic proportions referencing historical furniture forms.
- Industrial:Exposed metal frames, raw material finishes, and utilitarian aesthetics.
Modern styling leads volume while industrial specifications climb the fastest among rental property investors and co-living operators.
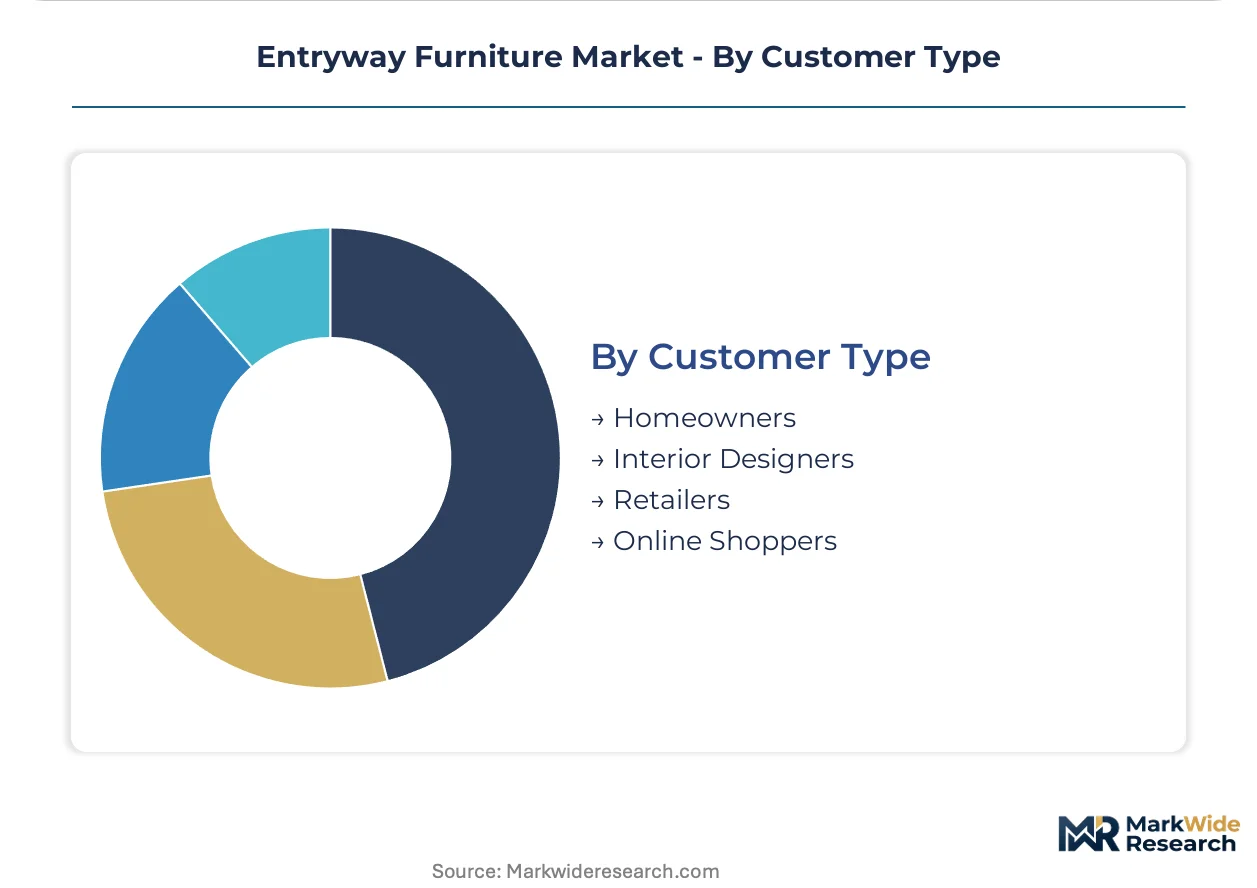
Customer Type:
Procurement channel fragmentation separates professional specification buyers from direct-to-consumer purchasers with divergent service expectations.
- Homeowners:Individual purchasers upgrading mudrooms, foyers, and entry corridors in owned residences. United States residential renovation activity drives strongest adoption, with space-efficient storage solutions prioritized in urban apartment conversions.
- Interior Designers:Professional specification agents sourcing for client projects with documented chain-of-custody requirements. Hospitality buyers in Germany and France increasingly disqualify uncertified suppliers from RFP shortlists, elevating compliance documentation to competitive threshold status.
- Retailers:Brick-and-mortar and omnichannel furniture merchants curating assortments for local market preferences.
- Online Shoppers:Direct-to-consumer purchasers through digital marketplaces and brand-owned e-commerce platforms.
Homeowners anchor the volume base while interior designers gain share at the steepest rate as commercial hospitality fit-out activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential homeowners upgrading mudrooms and foyers concentrate demand in the United States, Germany, and China, with urban apartment dwellers in dense metropolitan corridors reshaping space-efficiency requirements across all three markets.
United States
California Title 24 building efficiency standards mandate energy-efficient residential transition zones, accelerating specification of space-optimized storage benches and console tables with integrated LED lighting in new construction. EPA TSCA Title VI formaldehyde emission thresholds govern composite wood substrates nationwide, with CARB Phase 2 requirements extending compliance burdens for manufacturers distributing in California. Los Angeles and San Francisco metro corridors drive strongest adoption of narrow-profile console tables averaging under 40 square feet per foyer.
Germany
Passivhaus retrofit wave requirements for airtight entry vestibules create specification pull for sealed storage benches with thermal break construction in energy-efficient home renovations. EUTR due diligence mandates and evolving EU deforestation-free supply chain rules favor certified hardwood suppliers, with FSC-tracked chain-of-custody documentation now mandatory for distribution channels. Berlin and Munich manufacturing clusters anchor production of thermal-break entryway systems for Central European export markets.
China
Urban apartment dwellers in dense metropolitan markets seek space-efficient storage solutions, with powder-coated steel frame production concentrated in Zhejiang and Guangdong provinces. MIIT industrial standards and evolving dual carbon goals reshape material sourcing requirements for domestic manufacturers. Shanghai and Shenzhen apartment complexes adopt modular configurations fastest, with magnetic connection hardware reducing assembly footprints to under 15 minutes.
Japan
Tokyo apartment complexes adopt modular modern entryway configurations with tool-free assembly hardware, driven by extreme space constraints in dense urban housing. METI energy efficiency guidelines influence residential fixture specifications, with JIS standards governing structural integrity of flat-pack furniture. Osaka and Nagoya industrial clusters specialize in miniaturized joinery systems for metropolitan corridor compatibility.
United Kingdom
London metropolitan renters prioritize concealed storage over open display formats, with narrow hallway configurations driving demand for sub-48-inch width furniture. EUTR compliance requirements extend to UK distribution channels post-Brexit, with timber due diligence documentation elevating procurement thresholds for hospitality fit-out projects. Manchester and Birmingham manufacturing hubs serve regional renovation activity with space-optimized bench and cabinet lines.
Entryway Furniture Market Competitive Landscape
Player mix skews toward flat-pack logistics specialists and captive manufacturing operators with divergent approaches to corridor-width constraints and assembly complexity. Market structure fragments across three tiers: mass-market retailers leveraging digital shelf breadth, mid-market specialists with vertical manufacturing control, and premium design houses targeting hospitality specification channels. Two dominant competitive moves define current positioning: backward integration into captive hardwood sourcing to secure FSC-tracked supply chains, and direct-to-installer digital platform development to bypass traditional retail markups in commercial fit-out procurement.
Among mass-market retailers, IKEA exemplifies flat-pack logistics dominance across dense metropolitan corridors, while Ashley Furniture anchors the captive manufacturing tier through in-house production of solid wood benches and console tables. Wayfair occupies a position on the digital breadth vector, sustaining inventory advantages in narrow hallway configurations through marketplace aggregation models.
| Leading Market Players |
|---|
| IKEA |
| Ashley Furniture |
| Wayfair |
| Williams-Sonoma |
| Sauder Woodworking |
| West Elm |
| Home Depot |
| Herman Miller |
| Target Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with North American hardwood suppliers lock in both FSC-certified timber access and eighteen-month price visibility for console table and bench manufacturers serving California Title 24 construction pipelines. These arrangements insulate solid wood producers from lumber futures volatility while embedding CARB Phase 2 compliance costs into baseline pricing.
Pricing Analysis
Cost-plus contracts indexed to CME lumber futures govern oak and maple procurement for solid wood entryway furniture, with EPA TSCA Title VI testing fees passed through as line-item surcharges. Three-tier pricing structure across premium, standard, and economy levels separates FSC-tracked certified hardwood from compliant particleboard and untraced commodity substrates. Pricing pressure stems from Chinese powder-coated steel frame oversupply compressing industrial-style bench margins. Online shoppers exhibit highest price sensitivity, while hospitality specification buyers prioritize chain-of-custody documentation over unit cost.
Supply Chain Analysis
Strategic stockpiling of CARB Phase 2-compliant MDF and low-emission particleboard dominates inventory strategy among mass-market manufacturers, buffering against EPA testing backlog delays. Raw material flows draw from Zhejiang and Guangdong steel frame clusters, North American hardwood belts, and European FSC-certified forestry operations. Single-source vulnerability concentrates in Chinese metal finishing capacity. Distribution runs through flat-pack logistics networks serving IKEA and direct-to-consumer digital platforms, with contractor-facing procurement portals gaining share in commercial hospitality fit-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospitality procurement groups and co-living operators with multi-unit annual volume commitments, fragmenting leverage among individual residential purchasers.
For Market Incumbents: Secure captive hardwood sourcing through backward integration into FSC-tracked North American forestry assets, insulating margin stability against lumber futures volatility and EUTR documentation requirements. Anchor digital platform development for contractor-direct procurement, bypassing traditional retail markups in commercial fit-out channels threatened by Wayfair's marketplace aggregation. For New Entrants and Emerging Players: Differentiate on thermal-break construction expertise for German Passivhaus retrofit specifications, where airtight entry vestibule requirements exceed mass-market technical capabilities. Target subscription-based furniture access models for New York and London corporate housing providers, converting capital expenditure to operating expense through bundled damage protection and seasonal style swaps. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among modular system manufacturers with magnetic connection hardware, where replacement part streams and reconfiguration services extend customer lifetime value. Long-term viability favors metal-wood hybrid construction specialists with cross-regional chemical compliance capabilities. Watch EU deforestation-free supply chain rule implementation timelines as inflection indicator for FSC-certified supplier acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber | FSC-tracked chain-of-custody documentation satisfies EUTR mandates for European distribution channels. |
| Direct-to-Installer Digital Platform Launch | Contractor-facing procurement portals capture margin from hospitality fit-out projects bypassing retail markups. |
| Metal-Wood Hybrid Product Line Expansion | Powder-coated steel frames with hardwood tops address industrial aesthetic demand in high-traffic rental properties. |
| Subscription Access Model Pilot | Monthly console table programs shift capital expenditure to operating expense for co-living operators. |
| Thermal-Break Construction Certification | Sealed storage benches meet German Passivhaus airtight entry vestibule specifications above mass-market tiers. |
Research Methodology
Operator-level perspectives from furniture manufacturing plant managers, retail category buyers, hospitality procurement directors, and residential renovation contractors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EPA TSCA Title VI filing databases, CARB compliance registries, FSC chain-of-custody tracking systems, and customs trade records for hardwood and steel frame imports. Bottom-up SKU-level demand modeling and top-down construction spending forecasts were triangulated to anchor volume estimates.
Sensitivity analysis tested forecast outputs against lumber futures volatility bands, regulatory implementation timeline delays, and Chinese manufacturing capacity utilization shifts across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, style category, customer archetype, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle analysis, with California Title 24 new construction permits and German Passivhaus retrofit registrations serving as industry-specific demand proxies.
The analysis sits within stated boundaries; outcomes outside sustained urban apartment construction volumes and current regulatory enforcement intensity would require recalibration. Forecasts reflect assumptions regarding FSC certification adoption rates and flat-pack assembly skill convergence among consumers. Revision becomes warranted when EU deforestation-free supply chain compliance thresholds cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Outdoor Furniture and Grills Market
Furniture
China Upholstered Furniture Market
Furniture
Europe School Furniture Market
Furniture
Recliner Chair Market
Furniture
Italy Luxury Furniture Market
Furniture
Children Furniture Market
Furniture
HORECA Furniture Market
Furniture
Armchair on Casters Market
Furniture
Cabinet Market
Furniture
School Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
China Furniture Market
Furniture
United Arab Emirates Furniture Market
Furniture
Global Home Furniture Market
Furniture
Global Multifunctional Furniture Market
Furniture
India Upholstered Furniture Market