
 Europe Multifunctional Furniture Market | 2026-2036
Europe Multifunctional Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Multifunctional Furniture Market Foresight
Premium multifunctional furniture is decoupling from commodity tiers on the basis of material certification, customization depth, and after-sales service. IKEA leverages its flat-pack logistics network to sustain volume leadership across European markets. Ekornes Group anchors the premium recliner-sofa hybrid segment through Norwegian ergonomic engineering. DFS Furniture competes on upholstery breadth and British retail density.
Multifunctional furniture comprises engineered pieces that perform two or more domestic functions—sleeping, seating, storage, or work surfaces—through reconfigurable mechanisms, integrated hardware, and modular frames. Typical specifications include particleboard or solid wood cores with steel pivot hinges rated for cycles exceeding durability thresholds, finished with low-VOC laminates or woven textiles. Convertible sofas and Murphy beds lead residential volume, while storage ottomans capture outsized margin in urban micro-apartments where every square meter commands premium utility. The hospitality application segment shows structural momentum as European hotel chains retrofit compact guest rooms with wall-bed systems and nesting tables.
REACH and the EU Green Deal constrain chemical inputs in adhesives and surface treatments, compelling manufacturers to reformulate finishes or lose market access. ECHA substance restrictions and national building codes in Germany and France further shape product safety and dimensional standards for wall-mounted and fold-away systems. Stakeholders must monitor regulatory tightening on formaldehyde emissions and circular-economy disclosure requirements to protect positioning.
Market Dynamics
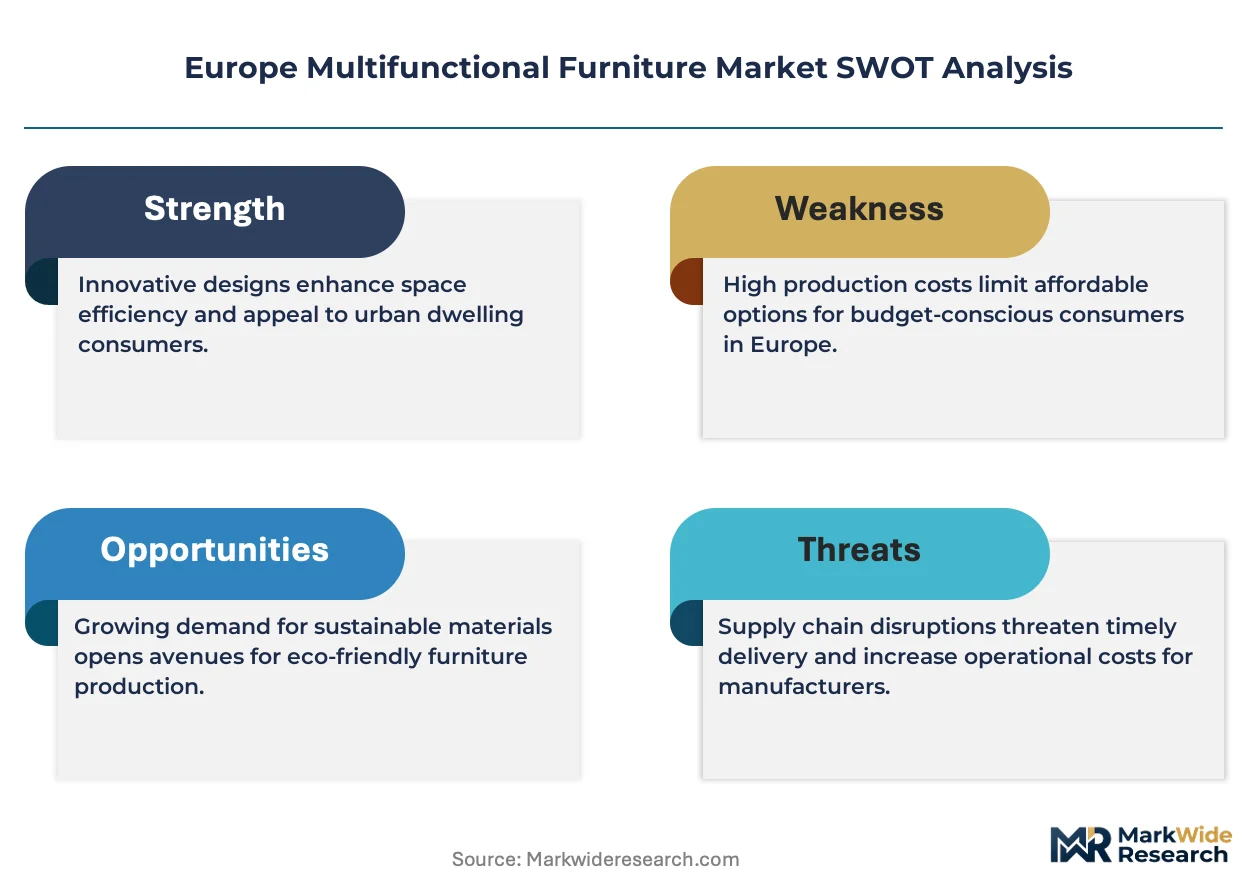
EU Green Deal emission targets and REACH chemical restrictions are compressing formulation timelines for European manufacturers while simultaneously opening premium positioning for certified low-VOC finishes.
Growth Catalysts
- REACH formaldehyde restrictions:Regulatory tightening on wood-based panel emissions forces legacy producers to upgrade finishing lines, accelerating turnover of compliant inventory.
- Remote-work permanence:Hybrid employment models in Germany and France sustain demand for home-office convertible systems that partition living space.
- Particleboard core innovation:Lightweight engineered substrates reduce shipping costs and enable single-person assembly, expanding direct-to-consumer penetration.
Market Restraints
- Steel hinge supply concentration:Pivot mechanism fabrication clusters in Northern Italy, creating vulnerability to regional logistics disruption.
- Low-VOC adhesive cost premium:Water-based binding agents command price spreads against solvent alternatives, compressing margin at economy tiers.
- Wall-bed installation complexity:Load-bearing requirements and French building code anchoring standards limit retrofit penetration in pre-1960 housing stock.
Strategic Opportunities
- Netherlands micro-apartment pipeline:Amsterdam and Rotterdam zoning reforms mandate sub-40-square-meter units, expanding addressable demand for nesting table and ottoman-storage configurations.
- CSRD circular-economy disclosure:Mandatory sustainability reporting creates procurement preference for take-back program operators among institutional furniture buyers.
- Modular frame + IoT convergence:Sensor-embedded convertible sofas that track usage patterns enable predictive maintenance subscriptions for hospitality fleet operators.
Industry Challenges
- CE marking timeline compression:Mechanical safety testing for wall-mounted systems faces backlog at notified bodies, delaying product launches.
- Cross-border SKU fragmentation:Divergent national electrical standards for powered recliner mechanisms force inventory duplication between German and French distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Multifunctional Furniture Market |
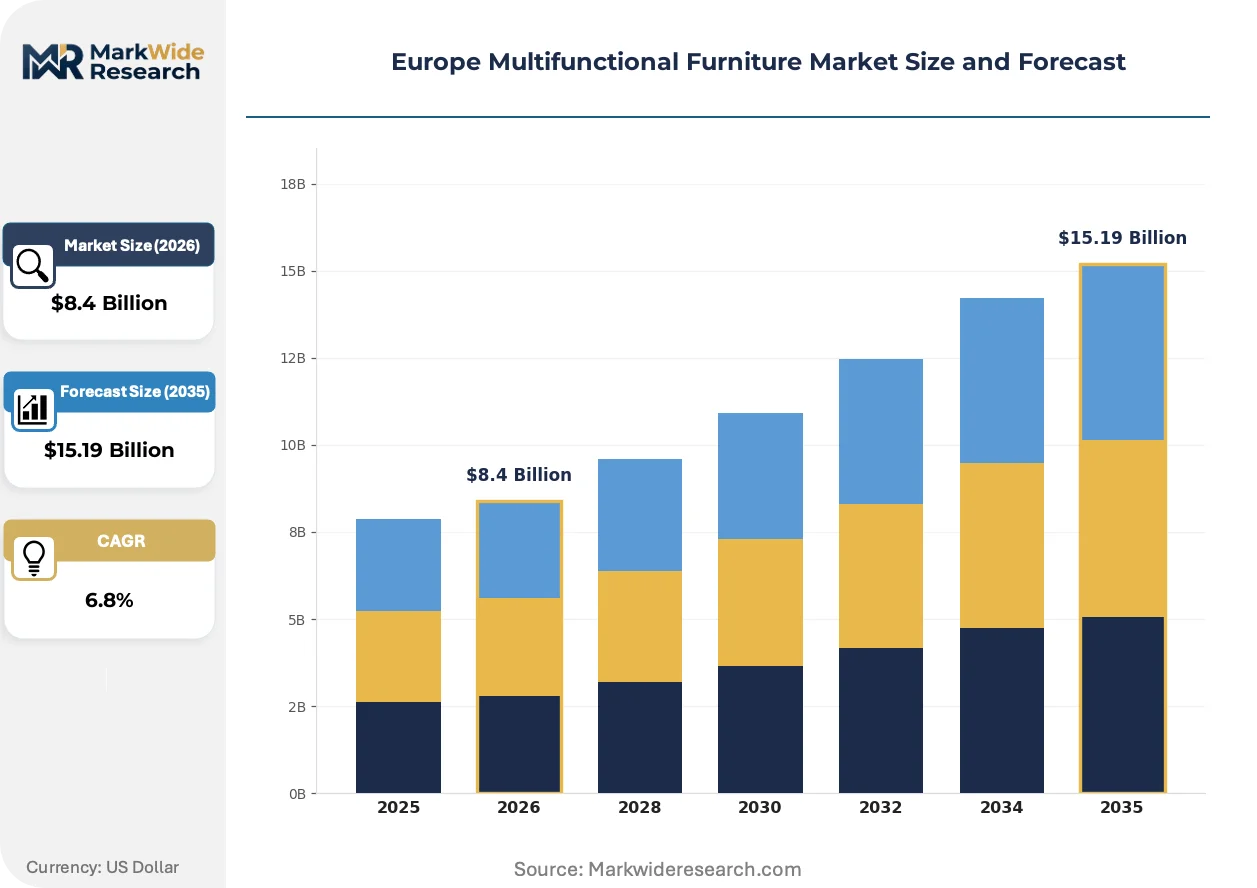
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convertible Sofas, Murphy Beds, Storage Ottomans, Nesting Tables Material: Wood, Metal, Plastic, Upholstered Application: Residential, Office, Hospitality, Retail Style: Modern, Industrial, Traditional, Minimalistic |
| Companies Covered | La-Z-Boy Inc, Ashley Furniture Industries, IKEA, Ekornes Group, Actona, DFS Furniture, Haworth Inc, Ahrend Groep, Dorel Industries Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Multifunctional Furniture Market Shifts & Advancements
Electromechanical actuation and digital fabrication are converging to transform how European manufacturers approach customization depth and assembly labor content.
Soft-close electromechanical actuation is electrifying the premium convertible sofa segment. Italian upholstery specialists deploy motorized frame extension to eliminate manual lifting. Hospitality procurement teams in Spain and Portugal specify these systems for aging guest demographics. The technology is electrifying competitive positioning by collapsing the ergonomic gap between mid-tier manual mechanisms and luxury fixed-frame seating.
ECHA substance restriction expansions are tightening permissible chemical inputs in textile flame retardants. Manufacturers reformulate polyurethane foam treatments to maintain ignition resistance without halogenated compounds. German residential upholstery faces the steepest compliance curve due to stricter federal fire safety codes than Mediterranean neighbors. Reformulation costs concentrate margin pressure on small-batch producers lacking captive chemical engineering.
Rental-furniture subscription models are capturing urban cohorts aged 25-34 in Copenhagen and Stockholm. Consumers prioritize access over ownership for transitional life stages. Traditional retail channels lose transaction volume to platform-managed circular services. Nordic markets exhibit the highest penetration where housing tenure instability and sustainability signaling overlap most intensely.
Europe Multifunctional Furniture Market Segmentation
Segmentation reveals how regulatory burdens, material costs, and end-use durability requirements fragment competitive positioning across European multifunctional furniture. Manufacturers optimize formulation and testing investments differently for wall-mounted systems versus freestanding units, for hospitality fleet contracts versus residential direct-to-consumer channels.
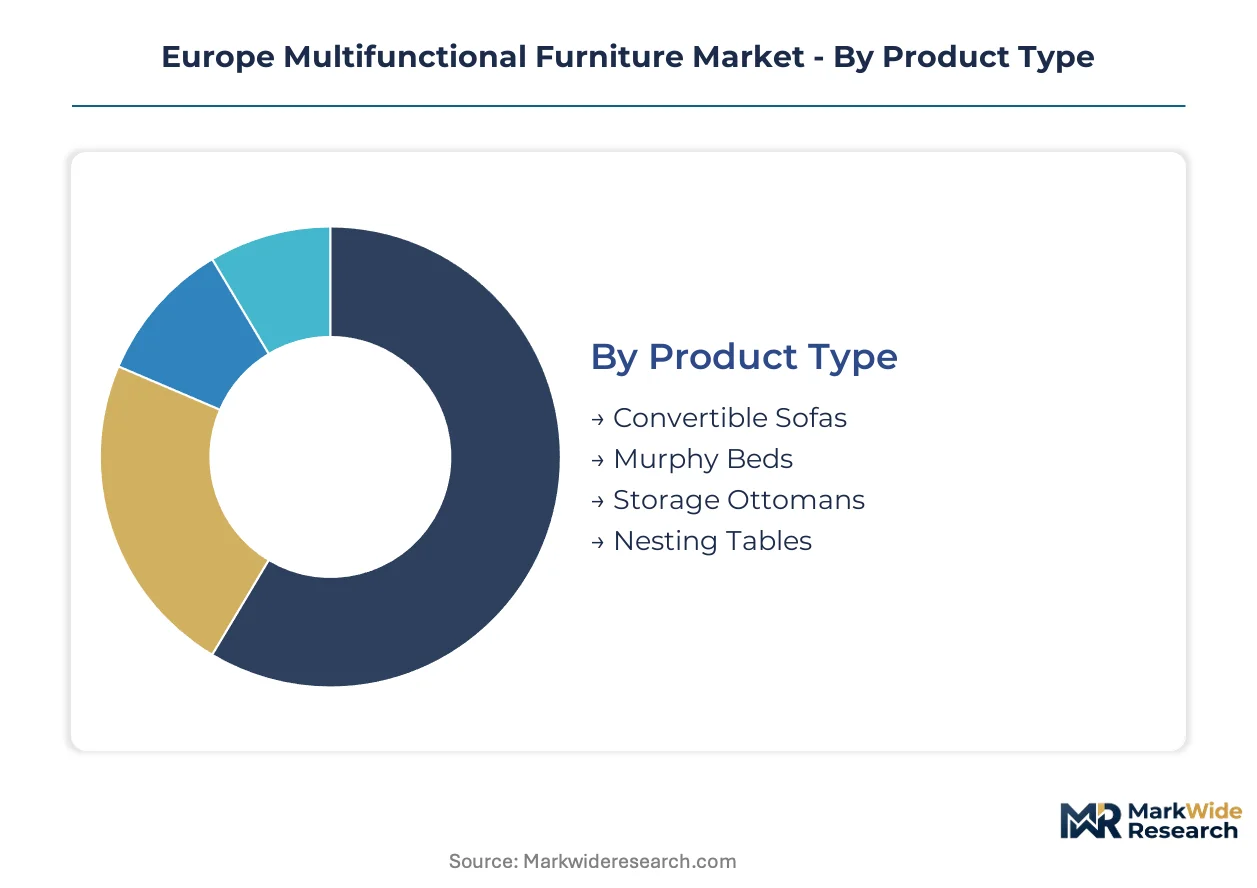
Product Type:
CE marking intensity varies sharply across this category: Murphy beds trigger full mechanical safety testing under EN 14749 for wall-mounted load-bearing systems, while nesting tables face lighter conformity assessment. REACH substance restrictions apply uniformly to surface treatments regardless of mechanism complexity.
- Convertible Sofas:Steel pivot hinge assemblies with particleboard or engineered wood cores, rated for cycle durability thresholds. Demand concentrates in German and French urban apartments where remote-work permanence sustains home-office conversion needs. ECHA scrutiny on polyurethane foam flame retardants elevates compliance costs for upholstered mechanisms.
- Murphy Beds:Vertical wall-bed systems with steel frame counterbalance mechanisms and integrated safety locks. French building code anchoring standards and German load-bearing requirements limit retrofit penetration in pre-1960 housing stock, concentrating new-build specification in Amsterdam and Rotterdam micro-apartments.
- Storage Ottomans:Dual-function seating with hinged lid access to interior compartments, typically upholstered over engineered wood frames. Netherlands housing density drives specification.
- Nesting Tables:Stacked table sets that separate for flexible surface deployment, metal or wood construction. Mediterranean hospitality procurement favors lightweight variants.
Convertible sofas sit at the top of the volume ranking, with Murphy beds climbing the fastest on Netherlands zoning reforms and urban micro-apartment construction.
Material:
Cost tier stratification runs deepest here: premium solid wood and certified low-VOC upholstery command price spreads against particleboard and untreated metal frames, with regulatory compliance acting as the primary tier separator rather than raw material scarcity.
- Wood:Solid hardwood cores and engineered particleboard substrates, finished with low-VOC laminates or natural oils. REACH formaldehyde restrictions on wood-based panel emissions force legacy producers to upgrade finishing lines, accelerating inventory turnover for compliant stock in German residential channels.
- Upholstered:Woven textiles or leather over foam cushioning and frame structures, requiring flame-retardant treatments. ECHA substance restriction expansions on halogenated compounds concentrate margin pressure on small-batch producers lacking captive chemical engineering, particularly in German federal jurisdiction with stricter fire safety codes.
- Metal:Steel or aluminum framing for structural components and mechanism housings. Northern Italian hinge fabrication clusters create supply concentration.
- Plastic:Polymer components for lightweight nesting and auxiliary pieces. Limited penetration in load-bearing applications.
Wood dominates absolute volume on heritage residential preference, while upholstered configurations gain share fastest on hospitality retrofit demand and premium apartment specification.
Application:
Customer type determines service model and margin structure: institutional buyers demand take-back program integration and CSRD-aligned circular-economy disclosure, while residential channels prioritize flat-pack logistics and single-person assembly.
- Residential:Individual household procurement for space-constrained urban apartments. Berlin, Paris, and Milan household formation drives specification of convertible sofas and Murphy beds as primary space-saving solutions.
- Hospitality:Hotel and serviced-apartment fleet procurement for compact guest room optimization. Spanish and Portuguese operators specify electromechanical actuation for aging guest demographics, with wall-bed systems and nesting tables capturing structural retrofit momentum.
- Office:Corporate workspace and co-location facility furnishing for flexible collaboration zones. Hybrid employment permanence sustains demand in German and French metropolitan markets.
- Retail:Furniture showroom and commercial space display fixtures requiring modular reconfiguration. Limited segment scale.
Residential application sits at the top of the volume ranking, with hospitality climbing the fastest on European hotel chain retrofit cycles and micro-room standardization.
Style:
Geography of demand concentration shapes aesthetic preference: Nordic markets exhibit highest rental-furniture subscription penetration where sustainability signaling and housing tenure instability overlap, favoring minimalistic and modern lines over ornate traditional forms.
- Modern:Clean lines, neutral palettes, and reconfigurable modularity without ornamental detail. Copenhagen and Stockholm urban cohorts aged 25-34 prioritize access-over-ownership models, with platform-managed circular services displacing traditional retail transaction volume.
- Minimalistic:Stripped-down forms emphasizing negative space and material honesty. Netherlands micro-apartment mandates favor space-efficient configurations with reduced visual mass.
- Industrial:Exposed metal framing, reclaimed wood accents, and utilitarian hardware. Urban loft conversions in Berlin and Milan sustain niche specification.
- Traditional:Ornamented profiles, carved wood details, and heritage upholstery patterns. Mediterranean residential markets retain stronger preference.
Modern style sits at the top of the volume ranking, with minimalistic climbing the fastest on Nordic rental-platform expansion and Netherlands compact housing regulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Design talent clusters in Milan, Copenhagen, and Berlin anchor Europe's multifunctional furniture innovation pipeline. These urban centers concentrate both heritage craftsmanship and digital fabrication expertise that shapes product development cycles across the continent.
Germany
Remote-work permanence in Berlin and Munich sustains demand for home-office convertible systems. REACH formaldehyde restrictions on wood-based panel emissions force legacy producers to upgrade finishing lines, accelerating inventory turnover for compliant stock. The North Rhine-Westphalia industrial corridor hosts steel hinge fabrication clusters that supply pivot mechanisms regionally.
France
Parisian micro-apartment construction drives wall-bed specification for sub-40-square-meter units. French building code anchoring standards for load-bearing wall-mounted systems limit retrofit penetration in pre-1960 housing stock. The Île-de-France region concentrates upholstery specialists serving hospitality procurement teams.
Netherlands
Amsterdam and Rotterdam zoning reforms mandate compact housing units, expanding addressable demand for nesting tables and ottoman-storage configurations. CSRD circular-economy disclosure requirements create procurement preference for take-back program operators. The Randstad urban agglomeration leads rental-furniture subscription model penetration among 25-34 cohorts.
Italy
Milan's design heritage and Northern Italian metalworking clusters dominate electromechanical actuation component supply. ECHA substance restrictions on halogenated flame retardants concentrate reformulation costs on small-batch producers. The Brianza furniture district anchors premium convertible sofa upholstery specialization.
Sweden
Stockholm and Copenhagen urban consumers prioritize access-over-ownership models for transitional life stages. Nordic housing tenure instability overlaps with sustainability signaling to drive platform-managed circular services. Flat-pack logistics networks originating in Scandinavian distribution centers enable single-person assembly penetration.
Europe Multifunctional Furniture Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base separates into integrated manufacturers controlling substrate production, specialist upholstery houses, and platform-managed circular service operators. Strategic moves concentrate on CSRD-aligned sustainability certification and direct-to-consumer logistics optimization rather than capacity expansion.
Among scale-driven fabricators, IKEA anchors volume leadership through flat-pack distribution density. Ekornes Group occupies the premium ergonomic recliner-sofa hybrid segment. DFS Furniture exemplifies retail-density competition through British market coverage. These three represent distinct archetypes: logistics-platform scale, engineering-led premium positioning, and national retail network depth.
| Leading Market Players |
|---|
| La-Z-Boy Inc |
| Ashley Furniture Industries |
| IKEA |
| Ekornes Group |
| Actona |
| DFS Furniture |
| Haworth Inc |
| Ahrend Groep |
| Dorel Industries Inc |
| Others |
Supply & Pricing Matrix
The EU Green Deal emission targets and REACH chemical restrictions gate both qualified supply and premium-tier pricing access, forcing manufacturers to absorb reformulation costs or surrender market position to certified competitors. Low-VOC adhesive premiums and circular-economy disclosure requirements stratify pricing power along compliance depth rather than raw material scarcity alone.
Pricing Analysis
Bundled after-sales service and unbundled component-only procurement split the pricing landscape across residential and hospitality channels. Three-tier pricing structure across premium, standard, and economy levels separates certified low-VOC finishes from commodity particleboard cores, with customization depth and installation complexity driving spreads. Cost compression in economy tiers intensifies because water-based binding agents command persistent price premiums against solvent alternatives. Residential direct-to-consumer buyers exhibit highest price sensitivity, while hospitality fleet operators prioritize lifecycle durability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for take-back programs and refurbishment cycles are emerging as structural differentiators under CSRD disclosure mandates. Northern Italian metalworking clusters, German engineered wood substrate producers, and Nordic flat-pack distribution centers anchor continental supply. Steel pivot hinges, low-VOC laminates, and certified upholstery textiles constitute critical input dependencies. Single-source vulnerability concentrates in electromechanical actuation component fabrication around Milan. Distribution runs through hybrid direct-to-consumer platforms and traditional retail density networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe multifunctional furniture market reads as a late-cycle quality story, with remote-work permanence and regulatory compliance driving specification toward premium certified tiers rather than commodity substitution.
For Market Incumbents: Hedge against margin erosion in economy tiers by deepening backward integration into low-VOC adhesive production and captive steel hinge fabrication. Secure CSRD-aligned circular-economy certification ahead of mandatory disclosure timelines to defend procurement preference among institutional buyers facing sustainability reporting obligations. For New Entrants and Emerging Players: Sensor-embedded convertible mechanisms with predictive maintenance software offer a technology-first wedge into hospitality fleet management contracts. Target Netherlands micro-apartment developers and Nordic rental-furniture platforms as penetrable demand pockets. Lead with direct-to-consumer flat-pack logistics and single-person assembly value propositions. For Investors and Strategic Acquirers: Valuations sit cheapest among specialist upholstery houses lacking REACH-compliant chemical engineering capabilities but possessing established hospitality relationships. Five-to-ten year viability favors operators with integrated take-back infrastructure and ECHA pre-certified formulation libraries. Monitor CE marking backlog duration at notified bodies as inflection signal for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD-Aligned Circular-Economy Certification | Mandatory sustainability reporting creates procurement preference among institutional furniture buyers. |
| Low-VOC Adhesive Backward Integration | In-house formulation control defends margin position against REACH-driven input cost inflation. |
| Electromechanical Actuation R&D Partnership | Motorized frame extension collapses ergonomic gap between manual mechanisms and luxury fixed-frame seating. |
| Direct-to-Consumer Logistics Optimization | Flat-pack density and single-person assembly expand penetration in urban micro-apartment channels. |
| Take-Back Program Infrastructure Buildout | Reverse-logistics capabilities satisfy CSRD disclosure requirements and secure hospitality fleet contracts. |
Research Methodology
Bottom-up residential and hospitality demand modeling reconciled against top-down substrate production and distribution tracking forms the analytical core of this study. Primary interviews with furniture product development executives, procurement leads at European hotel chains, REACH compliance officers, and flat-pack logistics operators combined with secondary validation from ECHA substance restriction databases, EU Green Deal policy filings, national building code registries, and customs trade data. Triangulation across these sources ensures dimensional accuracy.
Input-output matrix framing maps raw material flows through fabrication stages to end-use consumption across the projection horizon. Segmentation dimensions include product type, material certification tier, application channel, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity constraints. Forecast inputs incorporate REACH formaldehyde restriction implementation timelines and Netherlands zoning reform construction permits.
The model holds under stable regulatory enforcement and continued remote-work permanence; deviation in ECHA substance expansion scope or CE marking processing delays would shift trajectory. Forecasts reflect documented assumptions about compliance cost pass-through rates and hospitality retrofit cycle timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
UAE Home Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Kids Furniture Market
Furniture
Luxury Furniture Market
Furniture
High End Furnitures Market
Furniture
Canada Home Furniture Market
Furniture
India Upholstered Furniture Market
Furniture
Back Mount Frames Market
Furniture
Europe Luxury Furniture Market
Furniture
Mexico Home Furniture Market
Furniture
Exam Tables Market
Furniture
Italy Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
Italy Luxury Furniture Market
Furniture
United Arab Emirates Furniture Market
Furniture
Children Furniture Market