
 Europe Furniture Market | 2026-2036
Europe Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Furniture Market Analysis
Subscription-based furniture leasing is expanding across European commercial real estate, altering ownership patterns for office fit-outs and co-working spaces. IKEA leverages its flat-pack logistics network to control last-mile costs in urban markets. Roche Bobois SA anchors its position through made-to-order upholstery craftsmanship in France and Italy. Steelcase competes on ergonomic certification depth for enterprise workplace contracts.
Europe furniture encompasses movable objects constructed from wood, metal, upholstery textiles, or glass composites, engineered for human support, storage, or workspace functionality across residential and commercial environments. Wood and upholstery materials dominate value pools due to premium positioning in heritage manufacturing clusters, while metal and glass segments capture specification-driven demand from architects and interior designers. The office and hospitality end-user categories lead volume absorption, with residential style preferences bifurcating between contemporary minimalism in Nordic markets and traditional craftsmanship in Southern Europe.
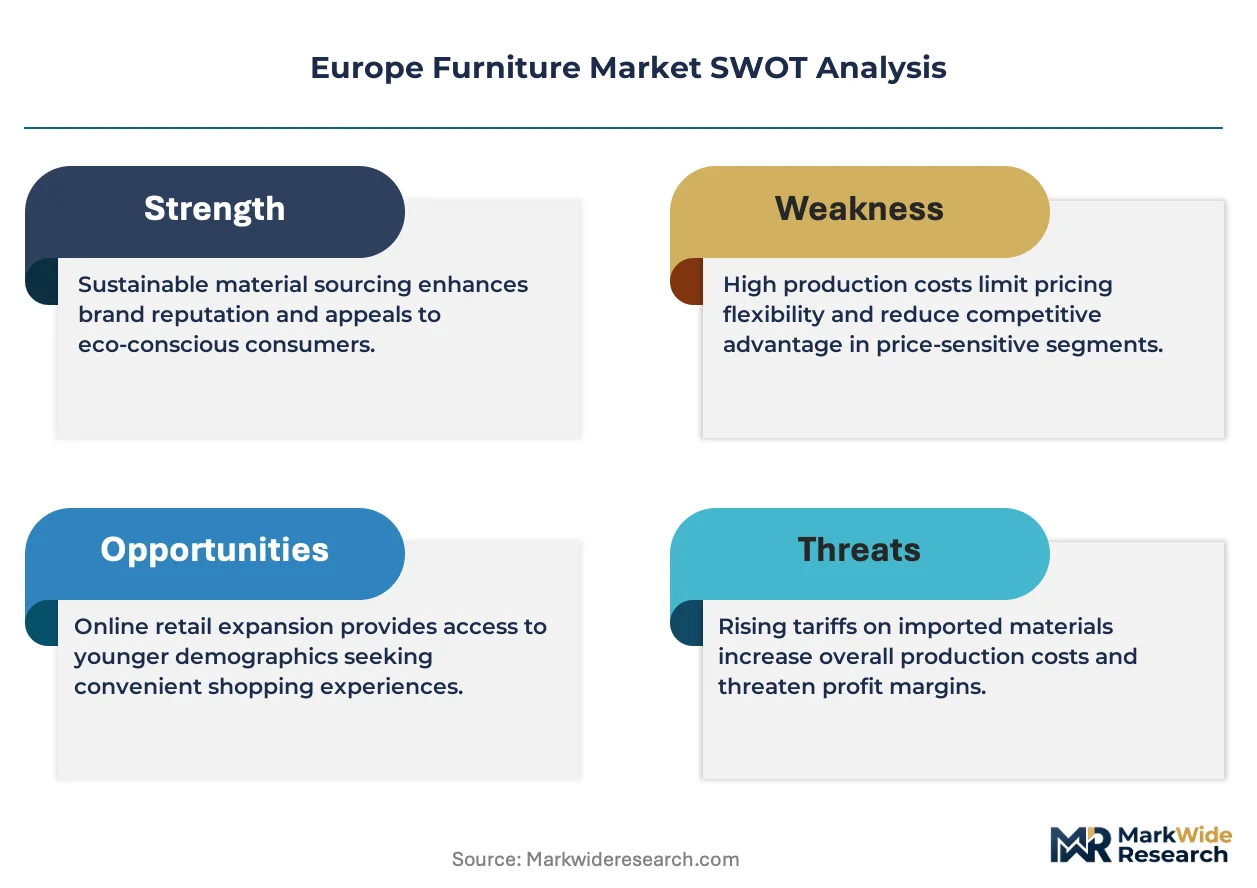
REACH compliance and the EU Green Deal mandate chemical transparency and recycled content thresholds, forcing reformulation of adhesives, finishes, and foam substrates across supply chains. ECHA substance restrictions and national extended producer responsibility schemes in France and Germany tighten market access for uncertified imports. Stakeholders must monitor evolving ecodesign criteria and carbon border adjustments to protect margin structures.
Market Dynamics
The EU Green Deal's ecodesign mandates are forcing wholesale reformulation of adhesives, finishes, and foam substrates across European furniture supply chains, compressing margins for uncertified imports while rewarding compliant domestic manufacturers.
Growth Catalysts
- Hospitality procurement acceleration:Hotel renovation cycles across Southern Europe and the Nordics are absorbing contract-grade seating and casegoods at elevated volumes, with boutique properties specifying heritage craftsmanship.
- REACH compliance premium:Chemical transparency requirements under ECHA substance restrictions are creating market access barriers that protect margin structures for certified EU-based producers.
- Co-working space densification:Flexible office operators in Germany and the Netherlands are leasing workstation systems rather than purchasing, expanding recurring revenue pools for modular furniture providers.
Market Restraints
- Baltic birch plywood supply concentration:Russian-origin hardwood feedstock disruptions have shifted sourcing to Nordic and Baltic mills, elevating input costs for curved plywood components.
- Polyurethane foam reformulation lag:ECHA restrictions on isocyanates and flame retardants are forcing R&D cycles that outpace product launch timelines for seating manufacturers.
- Artisan labor scarcity:Upholstery craftsmanship guilds in France and Italy face demographic contraction, constraining made-to-order capacity for premium positioning.
Strategic Opportunities
- Polish manufacturing hub expansion:Lower labor costs combined with EU regulatory alignment are attracting component fabrication and final assembly investment from German brands.
- Carbon border adjustment preparation:Early compliance with embedded carbon reporting under the EU Green Deal creates first-mover advantage for export-oriented producers.
- Textile-to-textile recycling integration:Post-consumer upholstery fabric recovery networks in Belgium and the Netherlands enable closed-loop material sourcing for sustainability-positioned lines.
Industry Challenges
- CAD-to-CAM skill bridging:Heritage manufacturers struggle to recruit operators capable of translating hand-drawn upholstery patterns into CNC cutting paths for automated production.
- Extended producer responsibility administration:French and German take-back scheme compliance requires new reverse logistics infrastructure that smaller producers lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Furniture Market |
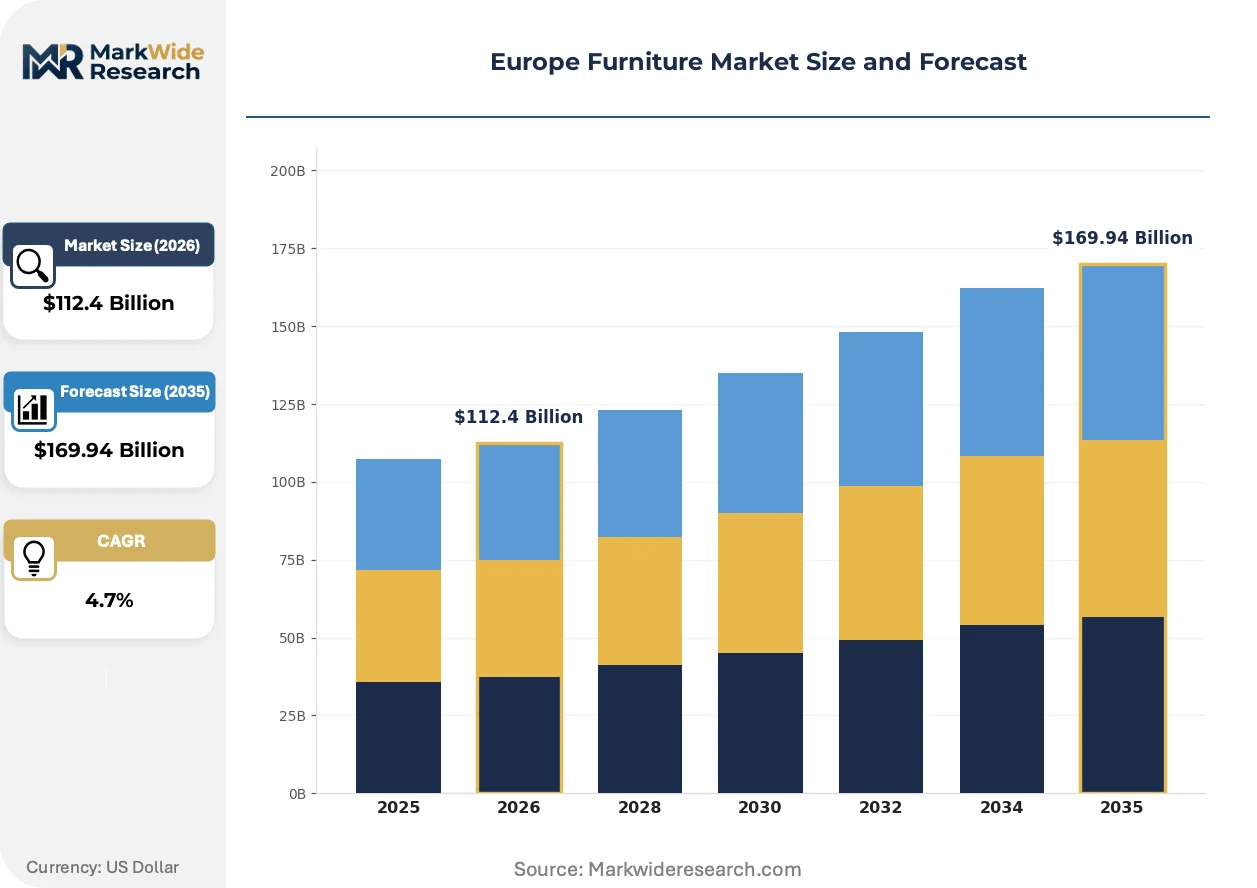
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Sofas, Beds Material: Wood, Metal, Upholstery, Glass Style: Contemporary, Traditional, Rustic, Minimalist End User: Residential, Commercial, Hospitality, Office |
| Companies Covered | Roche Bobois SA, Steelcase, IKEA, Nowy Styl, Kinnarps, Natuzzi S.p.A., BoConcept Holding A/S, Haworth, Poltrona Frau Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Furniture Market Emerging Trajectories
Digital fabrication and circular material flows are converging to compress production lead times while embedding compliance documentation directly into product passports, reshaping how specification-grade furniture reaches commercial buyers.
Cross-laminated timber and engineered wood composites are displacing solid hardwood in structural furniture frames, offering dimensional stability and reduced moisture sensitivity. Specifiers in Nordic commercial projects are adopting these materials at accelerating rates. This substrate shift is modularizing supply chains, enabling flat-pack distribution that collapses last-mile costs for urban fit-out contractors.
ECHA substance restrictions under REACH are mandating disclosure of chemical content across adhesive and finish formulations, forcing reformulation investments that favor larger manufacturers with in-house R&D laboratories. Upholstery foam suppliers are accelerating waterborne adhesive transitions to maintain market access. Contract seating categories face the steepest compliance timelines, with German and French procurement officers now requiring full material passports.
Corporate real estate managers are unbundling furniture ownership from facility service contracts, treating workstations as operational expenditures rather than capital assets. Leasing providers are capturing this demand shift with refresh-cycle guarantees that displace traditional dealer networks. This procurement model evolution is most visible in Amsterdam and Berlin co-working clusters, where operators prioritize flexibility over asset control.
Europe Furniture Market Segmentation
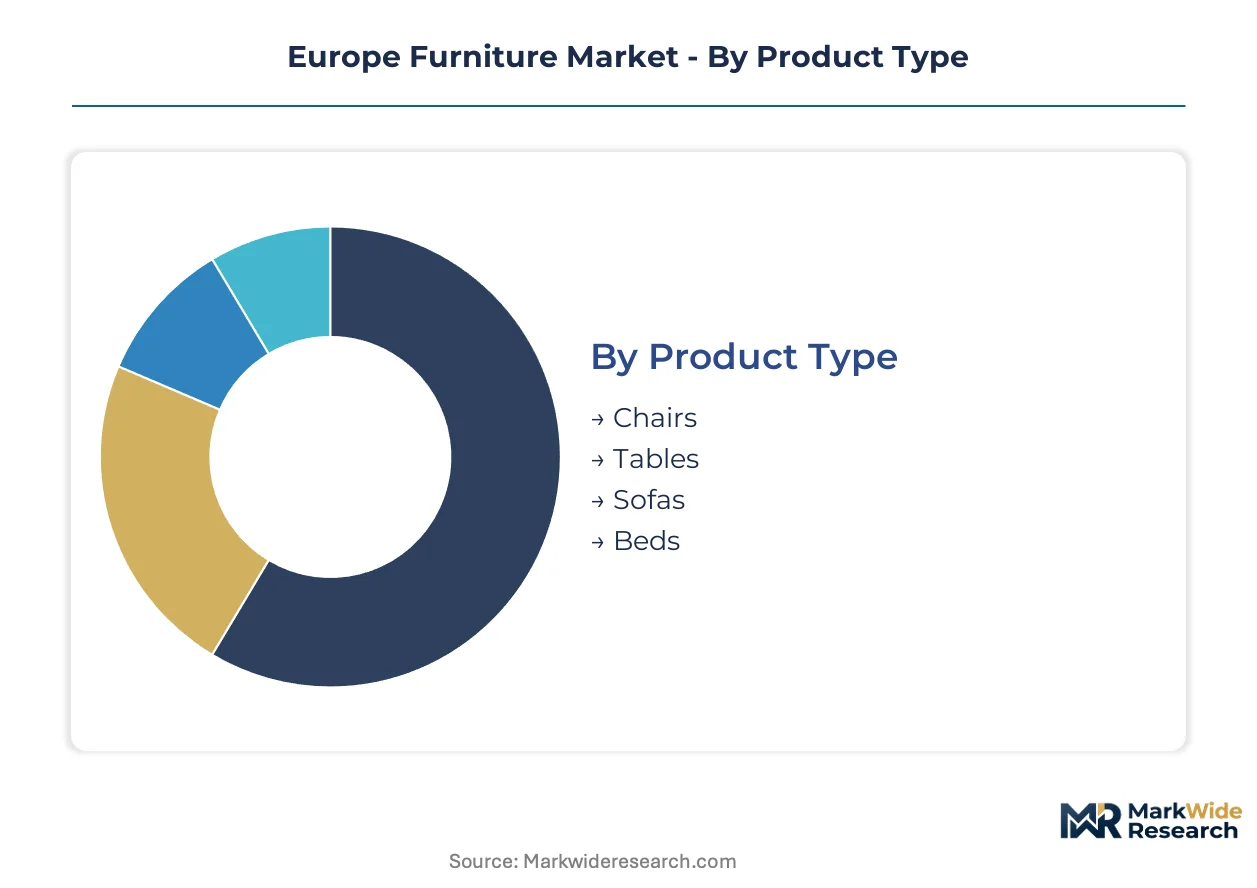
Segmentation reveals how capital deployment and regulatory exposure vary across Europe's furniture value chain. Manufacturers prioritize segments where REACH compliance costs can be amortized across higher-margin production runs.
Product Type:
Chairs demand the heaviest upfront tooling investment due to ergonomic certification requirements and molded component complexity.
- Chairs:Engineered with lumbar support structures and adjustable mechanisms for task seating. German office fit-out contractors specify certified ergonomic systems for enterprise workplace contracts, with procurement officers requiring full material passports under ECHA disclosure mandates.
- Sofas:Constructed with multi-density foam cores and suspension systems for residential and hospitality applications. French and Italian upholstery workshops face capacity constraints from aging artisan guilds, compressing made-to-order lead times for boutique hotel specifications.
- Tables:Span dining, conference, and occasional categories with surface durability requirements.
- Beds:Incorporate slatted bases and adjustable frames with regional size standardization challenges.
Most installed capacity flows through Chairs. Expansion is steepest in Sofas.
Material:
Cost tier stratification separates premium heritage substrates from specification-driven alternatives.
- Wood:Solid hardwood and engineered composites dominate value pools in Nordic manufacturing clusters. Cross-laminated timber substrates are displacing traditional framing in Dutch and Danish commercial projects, enabling flat-pack distribution that collapses last-mile logistics costs.
- Upholstery:Textile-covered foam and spring systems command premium positioning in French and Italian heritage production. Belgian and Dutch textile-to-textile recovery networks are enabling closed-loop sourcing for sustainability-positioned lines under EU Green Deal circularity mandates.
- Metal:Steel and aluminum framing captures specification-driven demand from architects.
- Glass:Tempered and laminated surfaces serve display and occasional furniture categories.
Wood retains the largest production footprint. Upholstery is gaining share fastest.
Style:
Geographic preference bifurcation drives parallel supply chain configurations across the continent.
- Contemporary:Clean-lined forms with engineered material palettes dominate Nordic and Dutch residential markets. Amsterdam and Berlin co-working operators specify modular contemporary systems with refresh-cycle guarantees through leasing arrangements.
- Traditional:Ornamented hardwood construction with heritage finishing techniques anchors Southern European positioning. Italian and French procurement for boutique hospitality properties specifies hand-finished traditional craftsmanship at substantial premiums.
- Minimalist:Reduced form vocabulary with hidden hardware concentrates in Scandinavian markets.
- Rustic:Distressed finishes and reclaimed material aesthetics serve Alpine and rural hospitality segments.
Contemporary commands the broadest distribution network. Traditional maintains the highest margin structure.
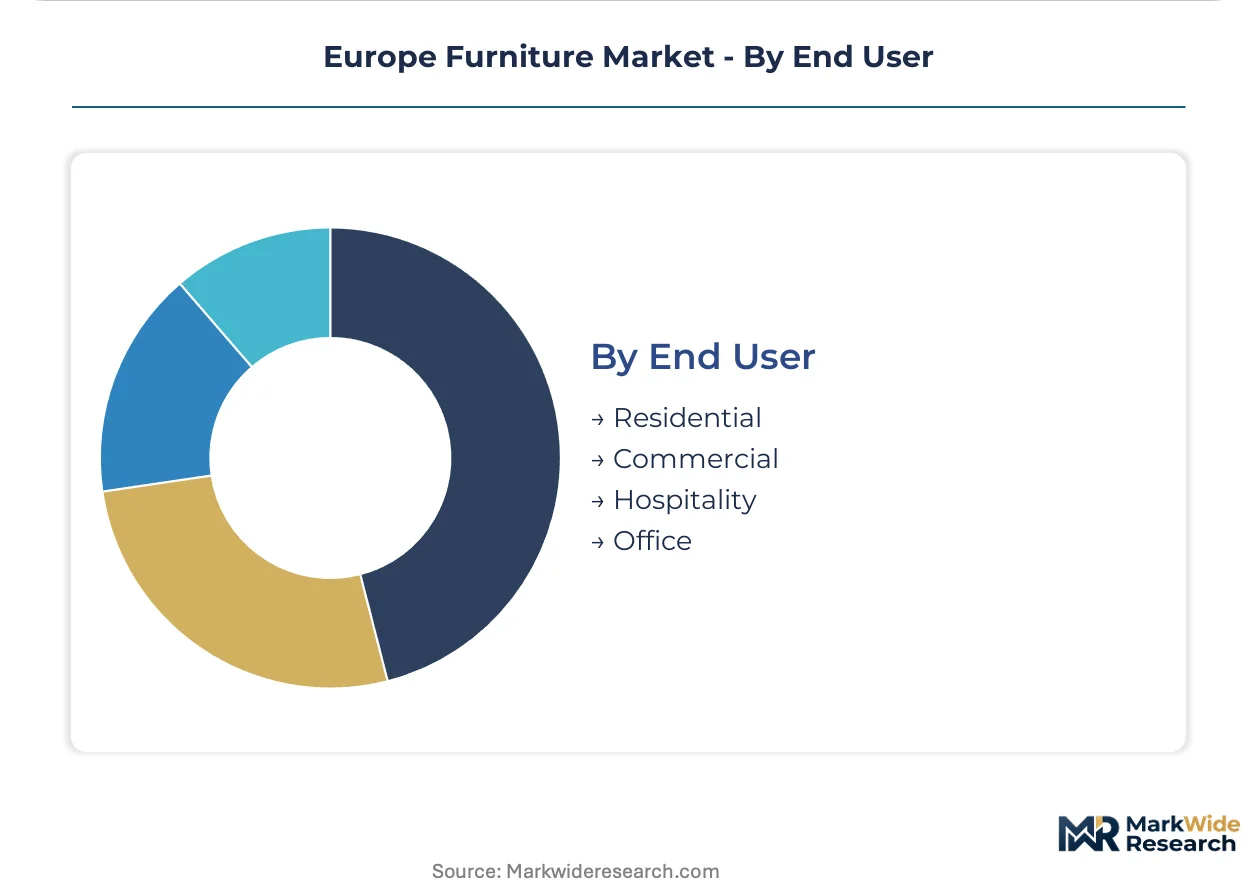
End User:
Customer type determines contract structure, with ownership models diverging sharply between asset-heavy and service-oriented procurement.
- Office:Workstation systems and ergonomic seating for corporate real estate and flexible workspace operators. German and Dutch co-working clusters are shifting from purchase to operational expenditure treatment, with leasing providers capturing recurring revenue pools through refresh-cycle service contracts.
- Hospitality:Contract-grade seating and casegoods for hotel renovation cycles across Southern Europe and the Nordics. Boutique properties specify heritage craftsmanship with extended durability warranties, absorbing elevated volumes from accelerated renovation timelines.
- Residential:Direct consumer purchase through retail and e-commerce channels.
- Commercial:Non-hospitality contract applications including healthcare and education.
Office absorbs the most modular system capacity. Hospitality shows the steepest procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps across Europe as manufacturers relocate assembly to jurisdictions with lower REACH compliance costs while maintaining design and finishing in heritage clusters.
Germany
Enterprise workplace contracts and co-working densification drive workstation system demand. Extended producer responsibility schemes under national packaging and waste directives tighten reverse logistics requirements. Berlin and Hamburg host leasing providers capturing operational expenditure shifts from corporate real estate managers.
France
Boutique hospitality renovation cycles absorb made-to-order upholstery at premium price points. ECHA substance restrictions on flame retardants force foam reformulation investments. Upholstery craftsmanship guilds in Paris and Lyon face demographic contraction, compressing capacity for heritage finishing techniques.
Poland
Component fabrication and final assembly investment accelerates from German brands seeking labor cost advantages. EU regulatory alignment eliminates customs friction for REACH-compliant exports. Lower Silesia manufacturing zones attract CNC-equipped mills serving curved plywood demand from Nordic markets.
Italy
Traditional craftsmanship positioning commands specification premiums from Southern European hospitality procurement. National extended producer responsibility administration burdens smaller producers lacking capital for reverse logistics infrastructure. Brianza and Tuscany clusters concentrate hand-finished casegoods capacity for luxury hotel contracts.
Netherlands
Textile-to-textile recycling networks enable closed-loop upholstery sourcing for sustainability-positioned lines. Amsterdam co-working operators prioritize furniture-as-a-service models with refresh-cycle guarantees. Rotterdam logistics hubs facilitate flat-pack distribution collapsing last-mile costs for urban fit-out contractors.
Europe Furniture Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage positioning commanding margin premiums in hospitality while scale-driven fabricators capture modular office volumes. The vendor base organizes around three archetypes: made-to-order upholstery ateliers, flat-pack logistics platforms, and ergonomic certification specialists. Consolidation pressure concentrates among mid-tier producers lacking in-house R&D for REACH reformulation. Dominant competitive moves include backward integration into engineered wood substrates and geographic expansion into Polish manufacturing corridors.
Among France-based heritage specialists, Roche Bobois SA exemplifies made-to-order craftsmanship positioning. Steelcase and IKEA represent divergent scale strategies—one anchoring enterprise ergonomic certification depth, the other leveraging flat-pack logistics networks for last-mile cost control. These three occupy positions across the premium-to-mass tier spectrum without overlapping segment focus.
| Leading Market Players |
|---|
| Roche Bobois SA |
| Steelcase |
| IKEA |
| Nowy Styl |
| Kinnarps |
| Natuzzi S.p.A. |
| BoConcept Holding A/S |
| Haworth |
| Poltrona Frau Group |
| Others |
Supply Flow & Price Mechanics
Baltic birch plywood index volatility cascades through European furniture supply chains, compressing margins for curved-component manufacturers while amplifying pricing power for Nordic mill operators with alternative hardwood feedstock arrangements.
Pricing Analysis
Distributor markups of 35-45 percent separate factory gate prices from end-user contract values across German and French procurement channels. Three-tier pricing structure across heritage craftsmanship, certified contract-grade, and mass-market flat-pack levels stratifies the market, with REACH compliance premiums widening spreads between certified and uncertified tiers. Pricing pressure stems from polyurethane foam reformulation costs under ECHA isocyanate restrictions, squeezing mid-tier seating producers lacking in-house R&D. Hospitality buyers exhibit lowest price sensitivity due to durability warranty requirements, while co-working operators prioritize operational expenditure minimization.
Supply Chain Analysis
Hardwood feedstock rests on Nordic and Baltic mill capacity after Russian-origin disruptions forced sourcing realignments. Cross-laminated timber substrates, waterborne adhesive formulations, and upholstery textile recovery streams anchor material flows. Single-source vulnerability concentrates in curved plywood component fabrication where Polish CNC-equipped mills serve fragmented downstream demand. Distribution runs through Rotterdam logistics hubs for flat-pack consolidation, with final-mile delivery increasingly handled by leasing providers rather than traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European furniture hinges on carbon border adjustment readiness and textile-to-textile recycling integration, with early compliance investments converting regulatory burden into pricing power.
For Market Incumbents: Deploy backward integration into engineered wood substrates to capture substrate cost compression and secure dimensional stability advantages. Consolidate upholstery craftsmanship capacity in France and Italy through apprenticeship pipeline investments, countering demographic contraction in artisan guilds. Strengthen Polish manufacturing corridors to amortize REACH compliance costs across higher-volume production runs. For New Entrants and Emerging Players: Launch via furniture-as-a-service leasing models targeting Amsterdam and Berlin co-working clusters where operational expenditure treatment displaces capital purchase patterns. White-space opportunity concentrates in textile-to-textile recycling integration for sustainability-positioned upholstery lines, with Belgian and Dutch recovery networks enabling closed-loop material sourcing. Position around carbon border adjustment compliance as first-mover differentiation for export-oriented production. For Investors and Strategic Acquirers: Asymmetric upside sits with Polish-based component fabricators combining EU regulatory alignment with labor cost advantages. Five-to-ten year viability favors manufacturers with captive engineered wood substrate production and established reverse logistics infrastructure for extended producer responsibility compliance. Monitor ECHA substance restriction expansion timelines as inflection indicator for reformulation cost burden redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Wood Substrates | Captures cost compression from cross-laminated timber displacement of solid hardwood in Nordic commercial projects. |
| Textile-to-Textile Recycling Network Integration | Enables closed-loop upholstery sourcing under EU Green Deal circularity mandates for sustainability-positioned lines. |
| Polish Manufacturing Corridor Expansion | Combines lower labor costs with EU regulatory alignment to amortize REACH compliance investments across volume production. |
| Furniture-as-a-Service Leasing Model Launch | Captures operational expenditure shift from corporate real estate managers in German and Dutch co-working clusters. |
| Carbon Border Adjustment Compliance Investment | Creates first-mover advantage for export-oriented producers under embedded carbon reporting requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant managers at Polish component fabrication facilities, procurement leads at German co-working operators, upholstery workshop owners in France and Italy, and distribution channel partners in Dutch logistics hubs with secondary validation from customs trade data, Cefic chemical industry reports, SEC filings of listed furniture manufacturers, and ECHA substance restriction databases. Bottom-up production capacity assessments and top-down demand absorption estimates were triangulated to anchor market sizing.
Historical reference periods spanning the decade preceding the analysis window established baseline growth trajectories and volatility patterns for projection anchoring. Segmentation modeling incorporated product type, material substrate, style positioning, and end-user procurement model dimensions. CAGRs were derived from regression analysis against macroeconomic indicators and industry-specific demand drivers including hospitality renovation cycle timing and corporate real estate expenditure classification shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA restriction timelines or extended Baltic birch supply disruptions. Forecasts reflect assumptions regarding regulatory implementation pacing and material substitution elasticity. A small set of named triggers—including carbon border adjustment enforcement dates and upholstery craftsmanship guild enrollment trends—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Contract Furniture Market
Furniture
Massive Wood Slabs Market
Furniture
India Upholstered Furniture Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
Outdoor Furniture and Grills Market
Furniture
United States Upholstered Furniture Market
Furniture
Canada Secondary Wood Products Market
Furniture
Japan Home Furniture Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
Italy Home Furniture Market
Furniture
North America High-End Furniture Market
Furniture
Study Carrels Market
Furniture
Bean Bag Chairs Market
Furniture
Recliner Chair Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
Lecterns Market