
 Germany Mattress Market | 2026-2036
Germany Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Mattress Market Foresight
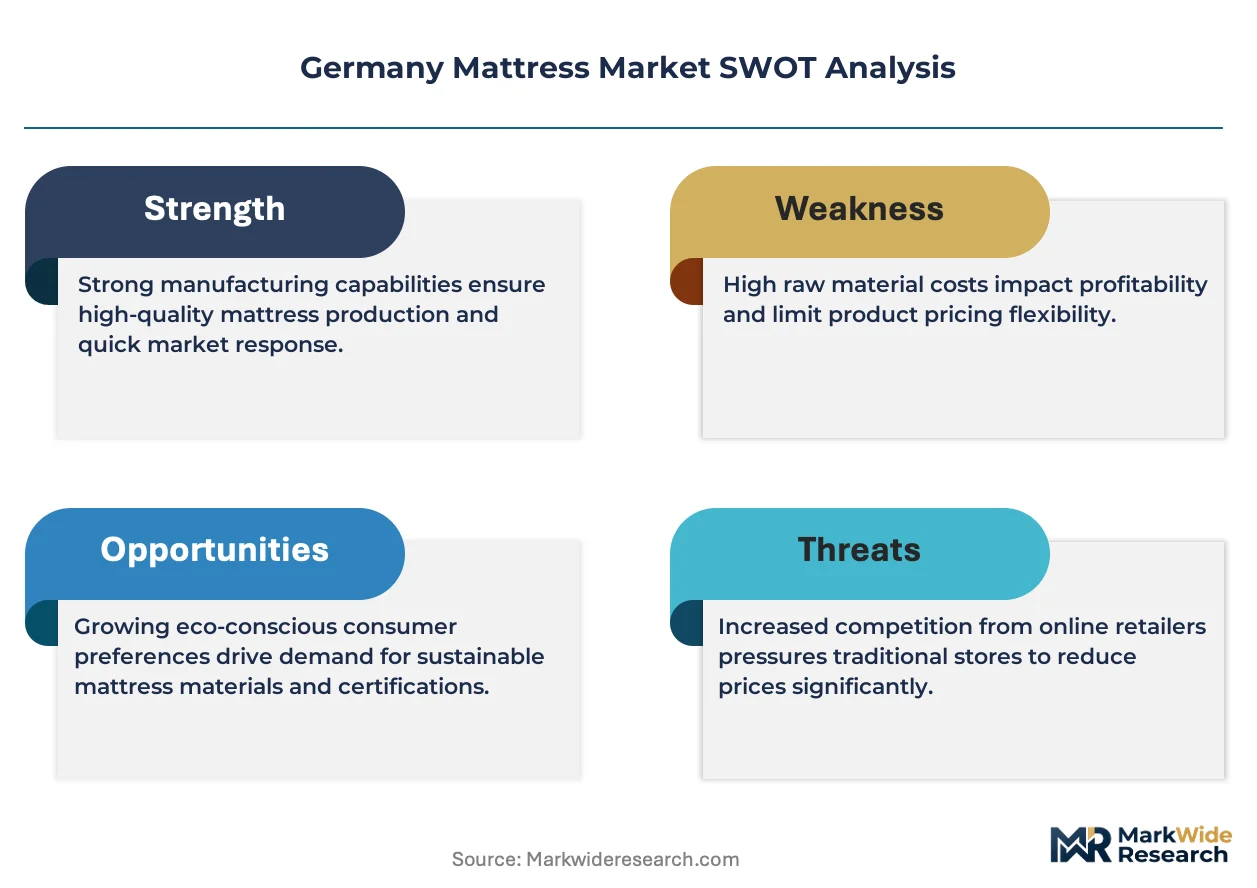
The EU Green Deal's textile sustainability targets is realigning procurement criteria across German retail chains. Emma Sleep GmbH leverages direct-to-consumer logistics to sustain margin control in a crowded digital channel. Tempur Sealy International Inc. anchors its German position through specialized memory foam formulations developed for European ergonomic preferences. Hilding Anders International AB competes via manufacturing scale across multiple European production sites.
A mattress is a sleep support system engineered from layered foam, spring, or latex assemblies with specified density ratings and ergonomic zoning for spinal alignment. German industrial standards mandate flammability resistance and dimensional stability testing for all commercial mattress sales. Memory foam and hybrid constructions now capture the fastest-growing demand pools as consumers prioritize pressure relief and thermal regulation. The online retail channel is displacing traditional specialty store foot traffic, though showroom-based consultation still dominates the luxury and premium price tiers.
KBA guidelines for commercial vehicle operator rest facilities indirectly shape fleet mattress specifications, while REACH chemical restrictions govern polyurethane foam formulations used by domestic manufacturers. The EU Ecodesign Directive pressures producers to document circular material flows and end-of-life recyclability. Stakeholders must monitor how the EU AI Act's emerging product transparency requirements could reshape smart mattress data collection practices.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are forcing polyurethane foam manufacturers to reformulate supply chains around bio-based feedstocks, compressing margins for conventional petrochemical-dependent producers while advantaging early movers with certified circular material flows.
Growth Catalysts
- Hospitality refurbishment cycles:Berlin and Munich hotel operators are replacing sleep infrastructure at scale as occupancy rates recover post-pandemic, creating concentrated demand spikes in southern German metropolitan corridors.
- REACH compliance innovation:ECHA's evolving substance restrictions are accelerating R&D investment in plant-derived polyols and water-based adhesives among domestic foam compounders.
- Smart mattress sensor integration:Sleep tracking hardware embedded in hybrid constructions is capturing consumer interest in premium price tiers, with biometric data collection becoming a standard feature expectation.
Market Restraints
- Petrochemical input volatility:Toluene diisocyanate and polyether polyol pricing swings expose foam producers to margin compression without long-term supplier contracts.
- Southern German manufacturing concentration:Production clusters in Bavaria and Baden-Württemberg create geographic vulnerability to regional logistics disruptions or energy price spikes.
- Latex substitution pressure:Natural rubber mattress cores from Southeast Asian suppliers compete on sustainability credentials against domestic synthetic foam production.
Strategic Opportunities
- EU Ecodesign Directive circularity mandates:Producers who document end-of-life recyclability and establish take-back programs gain preferential positioning with retail procurement teams.
- Eastern German retail underpenetration:Saxony and Thuringia exhibit lower specialty mattress store density per capita, creating whitespace for direct-to-consumer logistics models.
- Commercial fleet sleeper cab specifications:KBA guidelines for truck operator rest facilities are expanding addressable demand beyond residential and hospitality segments.
Industry Challenges
- Flammability testing certification timelines:DIN EN 597 and CAL 117 compliance documentation creates 8-12 week product launch delays for new foam formulations.
- Polyurethane foam chemist talent scarcity:Formulation expertise for bio-based alternatives concentrates among retiring specialists, constraining R&D pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Mattress Market |
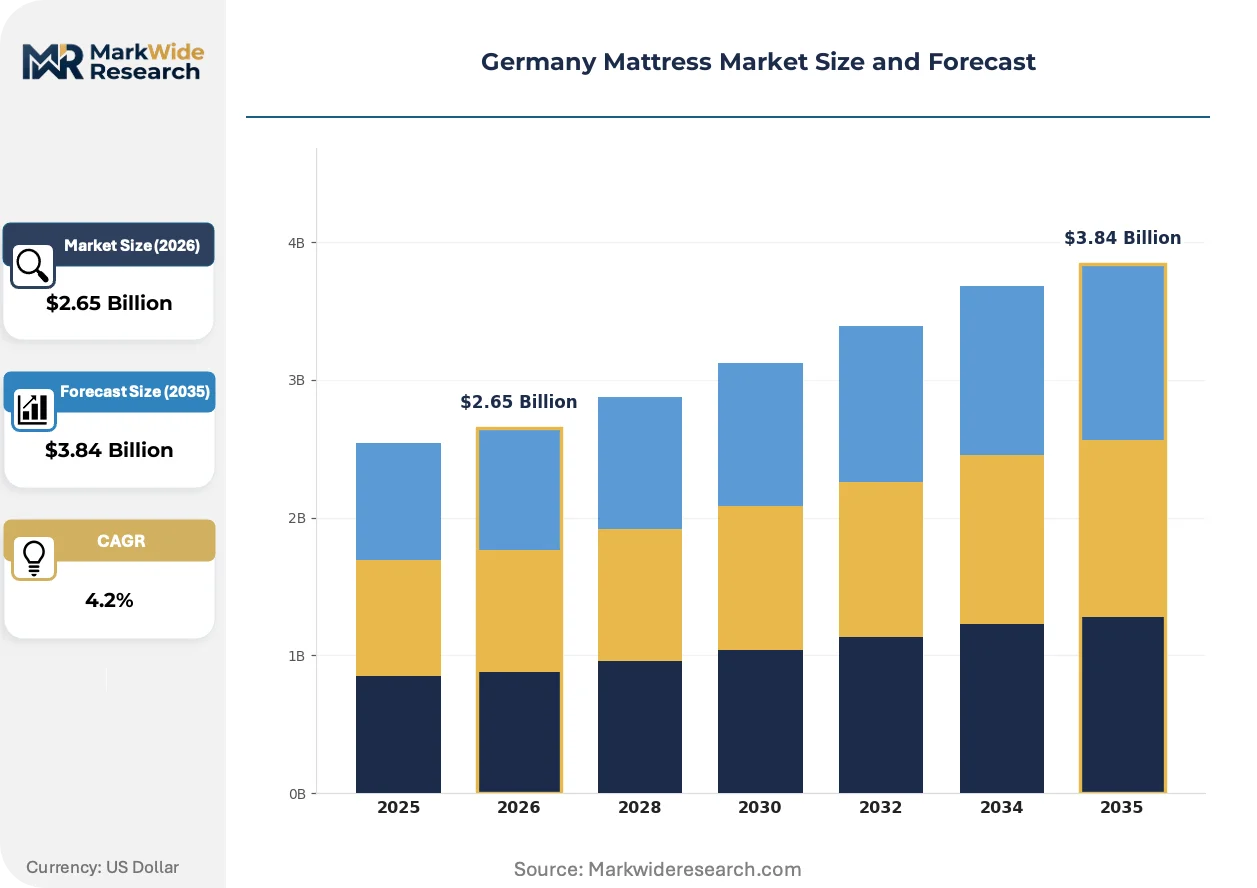
| Market Size in 2026 | $2.65 Billion |
| Market Size in 2035 | $3.84 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
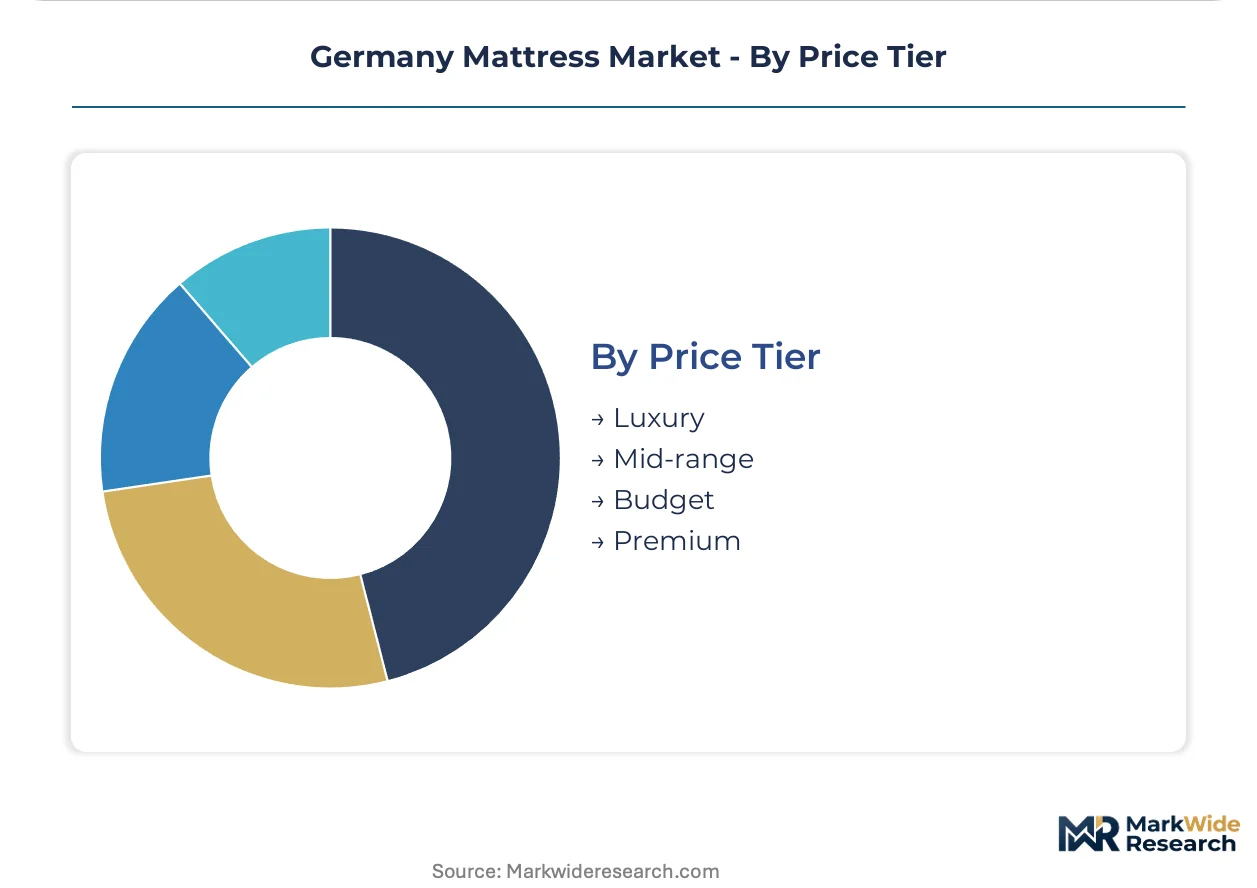
| Segmentation | Product Type: Memory Foam, Innerspring, Latex, Hybrid Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Residential, Hotels, Hospitals, Co-living Spaces Price Tier: Luxury, Mid-range, Budget, Premium |
| Companies Covered | Emma Sleep GmbH, Bett1.de GmbH, Tempur Sealy International Inc., Matratzen Concord GmbH, Hilding Anders International AB, Recticel NV, Breckle GmbH & Co. KG, Ravensberger Matratzen GmbH, Badenia Bettcomfort GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Mattress Market Shifts & Advancements
Sleep technology convergence with biometric monitoring hardware is redefining product architecture, while regulatory chemistry constraints and channel disintermediation reshape how mattresses reach German consumers.
Copper-infused and phase-change material foams is overtaking conventional open-cell constructions in premium segment positioning. Munich and Stuttgart hospitality buyers specify thermal-regulating surfaces for guest satisfaction metrics. This material transition is compressing margins for legacy foam compounders without cooling technology licenses.
ECHA's 2023-2027 restriction roadmap for isocyanates and flame retardants is forcing reformulation investments across Bavarian production facilities. Small-batch foam producers face disproportionate compliance costs versus integrated chemical operations with in-house toxicology teams. Southern German manufacturing clusters are consolidating around shared testing laboratory infrastructure to defray certification burdens.
Direct-to-consumer compressed mattress delivery is displacing traditional specialty store trial experiences among urban apartment dwellers under age 40. Berlin's dense logistics network enables same-day fulfillment that showroom-based retailers cannot match. This channel rotation concentrates volume with digitally native brands while legacy furniture chains retreat to premium consultation-dependent segments.
Germany Mattress Market Segmentation
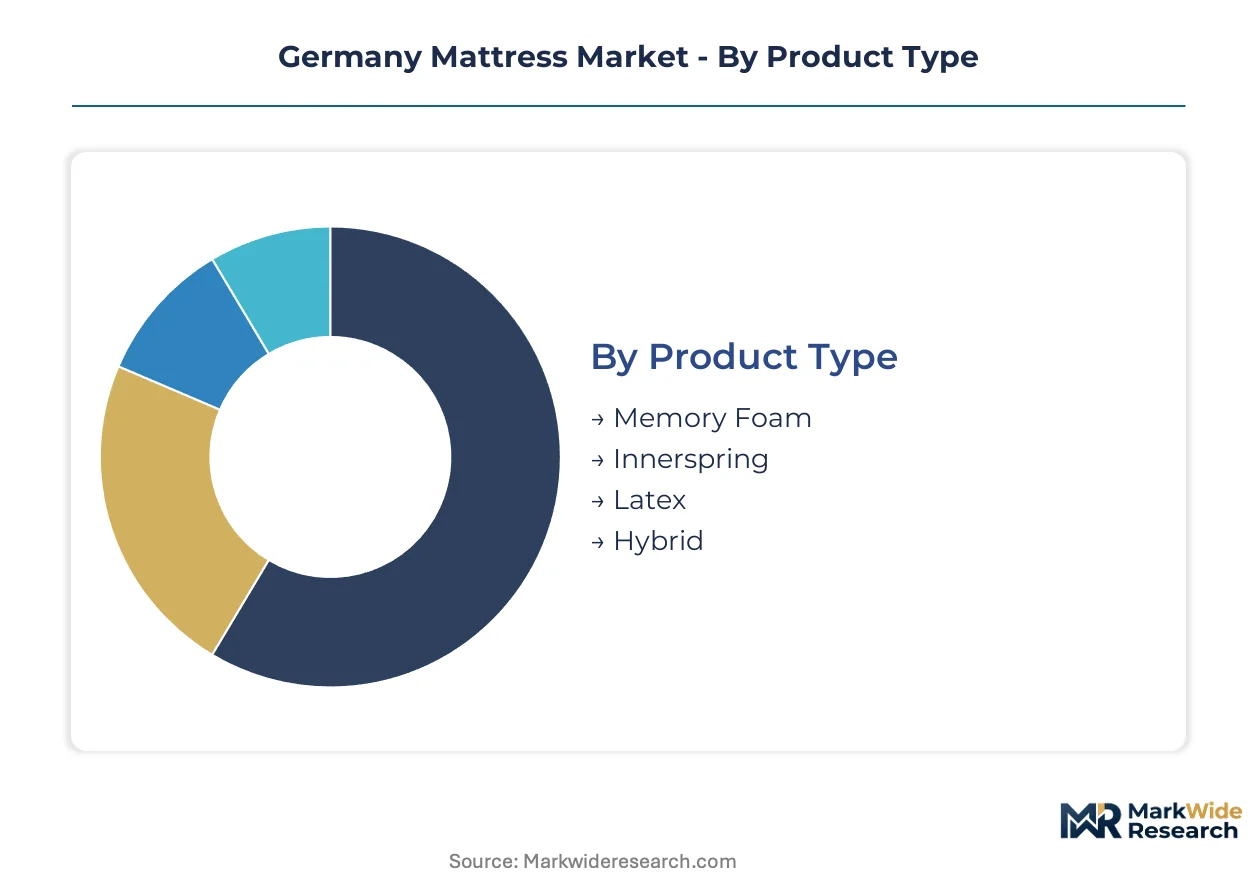
German mattress procurement splits sharply between hospitality bulk contracts and residential replacement cycles. REACH compliance costs and channel economics create divergent margin profiles across each segment boundary.
Product Type:
Material composition determines thermal performance, pressure relief characteristics, and circularity compliance burden under EU Ecodesign Directive.
- Memory Foam:Open-cell polyurethane formulations with viscoelastic recovery properties dominate Berlin and Munich hospitality refurbishment contracts. Southern German hotel operators specify density ratings above 50 kg/m³ for durability benchmarking against DIN standards.
- Hybrid:Pocket spring assemblies layered with foam comfort zones capture premium residential demand in Stuttgart and Frankfurt metropolitan corridors. KBA fleet specifications increasingly reference hybrid constructions for commercial vehicle sleeper cabs.
- Innerspring:Bonnell and pocket coil systems retain volume in budget-tier retail through established Bavarian manufacturing clusters.
- Latex:Natural rubber cores from Southeast Asian supply chains compete on bio-based credentials against domestic synthetic foam production.
Innerspring leads volumes today; Hybrid is gaining share fastest.
Distribution Channel:
Logistics infrastructure density and consumer trial preferences reshape how mattresses reach end users across eastern and western Germany.
- Online Retail:Compressed vacuum-packed delivery models exploit Berlin's same-day fulfillment networks. Direct-to-consumer brands bypass specialty store overhead while biometric sensor integration drives premium digital conversion.
- Specialty Stores:Showroom-based consultation retains dominance above €1,500 price thresholds where ergonomic zoning and flammability certification documentation influence purchase decisions.
- Supermarkets:Limited assortment rotation targets impulse replacement cycles in discount-oriented retail formats.
- Direct Sales:Hospitality procurement teams in Munich negotiate manufacturer-direct volume contracts with custom density specifications and bulk disposal clauses.
Specialty Stores anchor revenue concentration; Online Retail climbs the fastest.
End User:
Facility type dictates replacement frequency, certification stringency, and circular material documentation requirements.
- Residential:Individual replacement cycles average 8-10 years with pressure relief and thermal regulation priorities driving foam formulation preferences.
- Hotels:Berlin and Munich operators execute synchronized refurbishment waves post-pandemic, creating demand spikes concentrated in southern German metropolitan corridors.
- Hospitals:Antimicrobial surface treatments and pressure ulcer prevention specifications govern procurement criteria under German medical device hygiene standards.
- Co-living Spaces:Flexible lease terms accelerate turnover rates and compress replacement cycles versus traditional residential patterns.
Residential commands absolute volume; Hotels demonstrate steepest expansion trajectory.
Price Tier:
Certification grade and sensor integration separate tiers more than core material cost differentials alone.
- Premium:Copper-infused foams and phase-change materials with embedded sleep tracking hardware target Stuttgart and Frankfurt high-income demographics.
- Mid-range:Standardized foam densities without biometric features capture mass-market replacement demand through omnichannel distribution.
- Luxury:Hand-tufted constructions with natural fiber comfort layers and extended warranty terms dominate showroom consultation-dependent transactions.
- Budget:Basic polyurethane blocks with minimal zoning specifications serve price-sensitive segments through supermarket and hypermarket channels.
Mid-range holds volume leadership; Premium expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane foam chemists and textile engineers concentrate in southern German industrial corridors, anchoring the country's mattress manufacturing workforce density.
Bavaria
Munich hospitality operators drive bulk procurement cycles for hotel refurbishment waves. KBA commercial vehicle rest facility guidelines shape fleet sleeper cab specifications across Bavarian logistics hubs. The Munich-Stuttgart corridor hosts integrated foam compounders serving both automotive seating and mattress comfort layer demand.
Baden-Württemberg
Stuttgart metropolitan households generate premium-tier residential replacement demand with thermal-regulating product preferences. REACH chemical restrictions from ECHA accelerate reformulation investments among Stuttgart-area foam producers. The region's manufacturing clusters consolidate around shared flammability testing laboratories to defray DIN EN 597 certification costs.
North Rhine-Westphalia
Cologne-Düsseldorf retail density supports specialty store consultation-dependent transactions above €1,500 price thresholds. The EU Ecodesign Directive pressures producers to document circular material flows through take-back program infrastructure. Foam converters in the Ruhr industrial zone supply budget-tier polyurethane blocks to supermarket distribution channels.
Berlin-Brandenburg
Urban apartment dwellers under age 40 accelerate compressed mattress delivery adoption through same-day fulfillment networks. Direct-to-consumer logistics models exploit Berlin's dense last-mile infrastructure to bypass traditional showroom overhead. The capital's co-living space expansion compresses replacement cycles versus traditional residential patterns.
Lower Saxony
Hanover-area hospital procurement teams specify antimicrobial surface treatments under German medical device hygiene standards. Eastern German retail underpenetration in adjacent Saxony-Thuringia creates whitespace for digital-native brands with logistics reach. The region's furniture manufacturing heritage supports component sourcing for hybrid spring-foam constructions.
Germany Mattress Market Competitive Landscape
Capital-heavy foam compounders compete with asset-light direct-to-consumer brands across divergent margin structures. The vendor base splits between integrated chemical operations with in-house toxicology teams and digitally native marketers outsourcing production to contract manufacturers. Three archetypes dominate: southern German manufacturing specialists with DIN certification depth, Scandinavian-origin comfort technology licensors, and logistics-first direct-to-consumer platforms. Competitive intensity centers on bio-based formulation patents and same-day fulfillment network density.
Within the integrated manufacturing tier, Tempur Sealy International Inc. and Hilding Anders International AB exemplify scale-driven positions anchored by multi-site European production footprints. Emma Sleep GmbH occupies the digitally native archetype, leveraging compressed logistics and biometric sensor integration to capture urban apartment demand. These three entities represent distinct strategic postures: formulation-led, manufacturing-scale-led, and channel-infrastructure-led.
| Leading Market Players |
|---|
| Emma Sleep GmbH |
| Bett1.de GmbH |
| Tempur Sealy International Inc. |
| Matratzen Concord GmbH |
| Hilding Anders International AB |
| Recticel NV |
| Breckle GmbH & Co. KG |
| Ravensberger Matratzen GmbH |
| Badenia Bettcomfort GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap foam compounders across Bavaria and Baden-Württemberg anchor supply-side discipline, translating concentrated regional production into pricing power over hospitality procurement teams while compressing margins for distant competitors lacking DIN certification depth.
Pricing Analysis
Bundled take-back and disposal services separate premium hospitality contracts from stripped residential transactions. Certification grade under EU Ecodesign Directive and biometric sensor integration drive price differentiation between tiers. Cost compression in mid-range polyurethane blocks intensifies as REACH-compliant bio-based formulations raise input expenses. Budget-tier supermarket channels exhibit highest price sensitivity; luxury showroom consultation segments show lowest.
Supply Chain Analysis
Reverse-logistics flows for end-of-life mattress collection and foam reprocessing are consolidating around shared regional facilities in southern Germany. Raw material sourcing draws from Belgian polyether polyol producers, Dutch adhesive suppliers, and Southeast Asian natural latex plantations. Single-source vulnerability concentrates in toluene diisocyanate feedstock from Ludwigshafen-area chemical complexes. Distribution runs through compressed direct-to-consumer fulfillment for urban residential demand and bulk manufacturer-direct contracts for hospitality buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany mattress market reads as a geographic-arbitrage play where eastern German retail underpenetration offers expansion runway at lower customer acquisition cost than saturated western metropolitan corridors.
For Market Incumbents: Anchor manufacturing scale advantages through backward integration into bio-based polyol production, defending against latex substitution pressure from Southeast Asian suppliers. Prioritize shared testing laboratory investments in Bavarian clusters to defray REACH compliance documentation timelines. For New Entrants and Emerging Players: Biometric sensor integration capabilities offer a technology-first wedge into premium residential segments where thermal-regulating foam specifications command margin premiums. Target Berlin-Brandenburg co-living space operators with compressed same-day fulfillment models bypassing showroom overhead. For Investors and Strategic Acquirers: Valuations sit cheapest among legacy foam compounders lacking circular material flow documentation. Long-term viability hinges on Ecodesign Directive compliance infrastructure. Watch for KBA fleet specification expansions as inflection signal for commercial vehicle sleeper cab addressable demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polyols | REACH restrictions from ECHA are forcing feedstock substitution away from petrochemical dependence. |
| Shared Flammability Testing Infrastructure | DIN EN 597 certification delays compress launch timelines for small-batch foam producers. |
| Direct-to-Consumer Compressed Logistics | Berlin's same-day fulfillment networks displace specialty store foot traffic among urban apartment dwellers. |
| Take-back Program Establishment | EU Ecodesign Directive circularity mandates govern retail procurement team vendor selection criteria. |
| Smart Mattress Sensor Platform Development | Sleep tracking hardware integration is becoming standard feature expectation in premium price tiers. |
Research Methodology
Bottom-up residential and hospitality demand modeling reconciled against top-down foam production capacity tracking forms the analytical core. Primary interviews with foam compounder R&D directors, hospitality procurement managers, specialty store category buyers, and logistics network operators combined with secondary validation from ECHA restriction roadmaps, DIN standards documentation, KBA commercial vehicle guidelines, and customs trade data for polyurethane raw material flows.
Input-output matrices map raw material feedstock availability through manufacturing conversion to end-use segment absorption across the projection horizon. Segmentation dimensions span product type, distribution channel, end user facility, and price tier. CAGRs derive from elasticity-adjusted replacement cycle modeling and hospitality refurbishment wave timing. Industry-specific inputs include REACH compliance cost trajectories and smart mattress sensor adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA isocyanate restriction timelines and bio-based feedstock scale-up velocity. Practitioners should monitor KBA fleet specification revisions and eastern German retail penetration rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Australia Mattress Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
China Mattress Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
Malaysia Pillow Market
Bedroom Furniture
Malaysia Mattress Market