
 Home Office Furniture Market | 2026-2036
Home Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Home Office Furniture Market Intelligence
ISO 9241-5 ergonomic workstation standards is reorganizing competitive access in the home office furniture sector. Steelcase leverages its R&D intensity to dominate premium ergonomic seating development. Herman Miller anchors its position through brand strength in design-forward residential workstations. Haworth competes by controlling channel access through direct-to-consumer platforms alongside contract dealer networks.
Home office furniture encompasses desks, chairs, storage systems, and accessories engineered for residential workspace deployment, typically incorporating adjustable height mechanisms, lumbar support structures, and cable management integration to support sustained productivity outside traditional corporate environments. The product type dimension shows chairs capturing the dominant margin pool due to ergonomic certification premiums, while desks represent the fastest-growing category as sit-stand motorized bases displace static surfaces. Wood materials sustain volume leadership across consumer segments, though metal frames are gaining share in compact urban installations where durability-to-footprint ratios matter.
FCC emissions compliance governs powered adjustable furniture connectivity, while California TB 117-2013 shapes upholstery foam and fabric specifications across North American supply chains. The EU Green Deal's embodied carbon requirements for imported goods are beginning to filter into sourcing decisions for European-bound production. Stakeholders must monitor how fragmented national flammability and chemical disclosure regimes will reshape supplier qualification costs and regional manufacturing placement.
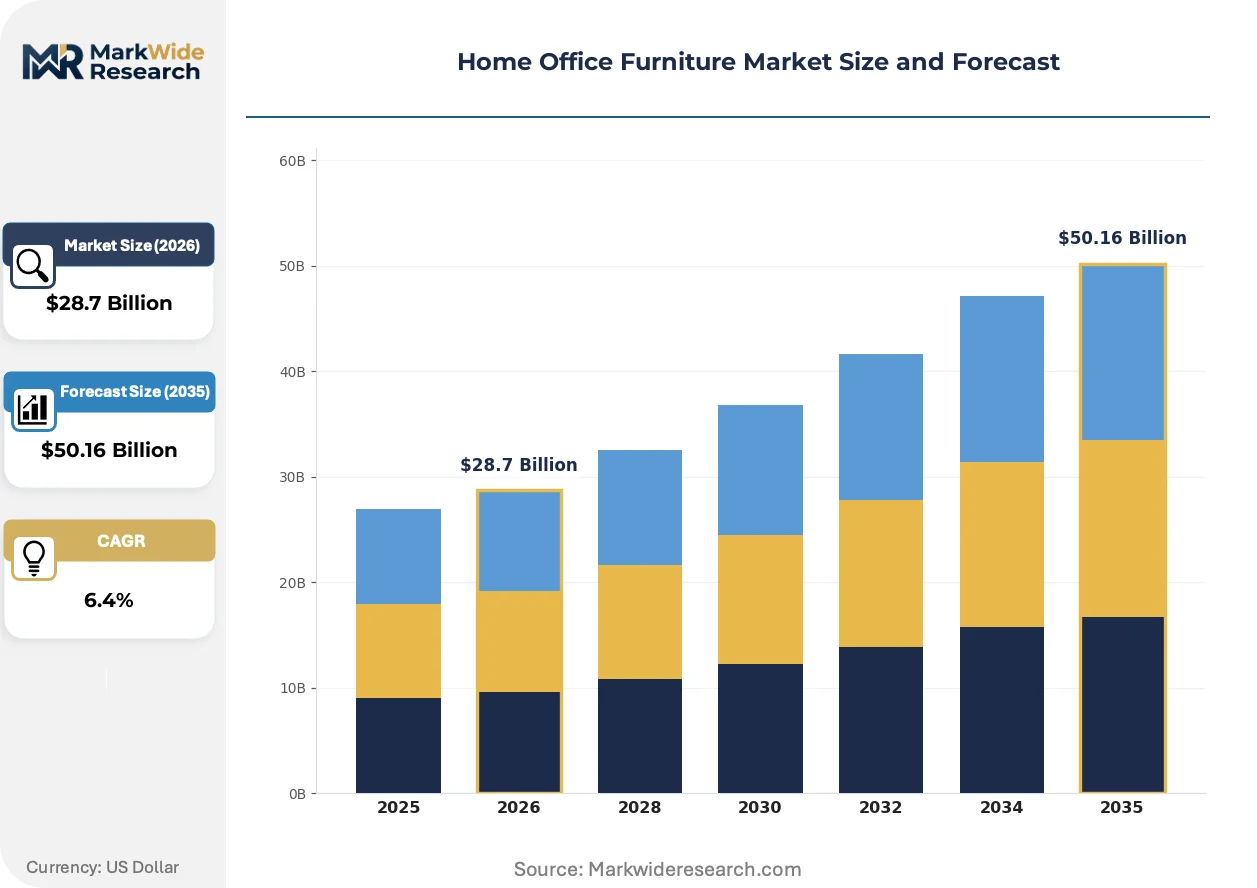
Market Dynamics
Freelancer adoption of ergonomic workstations is compressing product development cycles and forcing rapid certification against ISO 9241-5 standards, while California's TB 117-2013 flammability rules are restructuring upholstery supply chains across North American manufacturing.
Growth Catalysts
- ISO 9241-5 ergonomic workstation standards:Freelancer and remote worker demand for certified seating is pulling premium product development and creating certification premiums in residential channels.
- Sit-stand motorized desk bases:Compact urban installations in Germany and Japan are displacing static surfaces as durability-to-footprint ratios become decisive purchase criteria.
- California TB 117-2013:Smolder-resistant upholstery foam mandates are filtering into national supply chains, qualifying foam suppliers for multi-state residential furniture distribution.
Market Restraints
- Steel and aluminum input volatility:Metal frame cost swings are compressing margins on compact urban furniture lines where durability specifications cannot be relaxed.
- Chinese upholstery foam concentration:TB 117-2013 compliant foam supply clusters in Guangdong province, creating single-source qualification risk for North American assemblers.
- Legacy cable management integration:Powered adjustable furniture requires FCC emissions compliance that static furniture avoids, adding design validation cost and timeline risk.
Strategic Opportunities
- EU Green Deal embodied carbon requirements:European-bound production sourcing decisions are opening premium positioning for low-carbon frame and surface material suppliers.
- Direct-to-consumer platform expansion:Contract dealer networks are losing share to manufacturer-controlled digital channels that capture margin and usage data.
- Biophilic material convergence:Wood volume leadership is creating white space for certified sustainable timber paired with recycled metal frame systems in design-forward segments.
Industry Challenges
- Ergonomic certification talent scarcity:ISO 9241-5 testing capability is concentrated among specialized third-party laboratories, creating bottlenecks for new product launches.
- Multi-jurisdiction flammability compliance:Fragmented national chemical disclosure regimes are forcing parallel SKU development and regional manufacturing placement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Office Furniture Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Bookcases, Storage Units Material: Wood, Metal, Glass, Plastic Customer Type: Freelancers, Remote Workers, Small Businesses, Corporations Distribution Channel: Online Retailers, Furniture Stores, Wholesale Distributors, Catalogs |
| Companies Covered | Ashley Furniture Industries, HNI Corporation, Steelcase, La-Z-Boy, Herman Miller, Haworth, MillerKnoll, Teknion, IKEA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Office Furniture Market Strategic Shifts & Innovations
Adjustable furniture electronics, sustainability mandates, and channel restructuring are simultaneously reshaping product architecture, material selection, and go-to-market economics in home office furniture.
Motorized sit-stand desk controllers are miniaturizing drive mechanisms and sensor arrays into sub-surface footprints compatible with residential aesthetics. Urban apartment dwellers in Japan and Germany are specifying these systems for space-constrained installations at accelerating rates. Component miniaturization is compressing the cost gap between motorized and static desk bases, eroding the premium positioning that powered adjustability once commanded.
California TB 117-2013 is mandating smolder-resistant upholstery foam and fabric barrier specifications across North American residential furniture. Manufacturers serving California are qualifying multi-state suppliers against this standard, creating de facto national compliance baselines. Upholstery material selection in contract and residential channels is converging as a result, with foam suppliers consolidating around TB 117-2013 certified formulations.
Buying committees at distributed enterprises are unbundling home office furniture procurement from traditional corporate real estate contracts. Individual employees in the United States and Germany are selecting and expensing residential-grade ergonomic seating through self-directed allowance programs. This fragmentation is compressing sales cycles and forcing manufacturers to maintain simultaneous presence in contract dealer and direct-to-consumer channels.
Home Office Furniture Market Segmentation
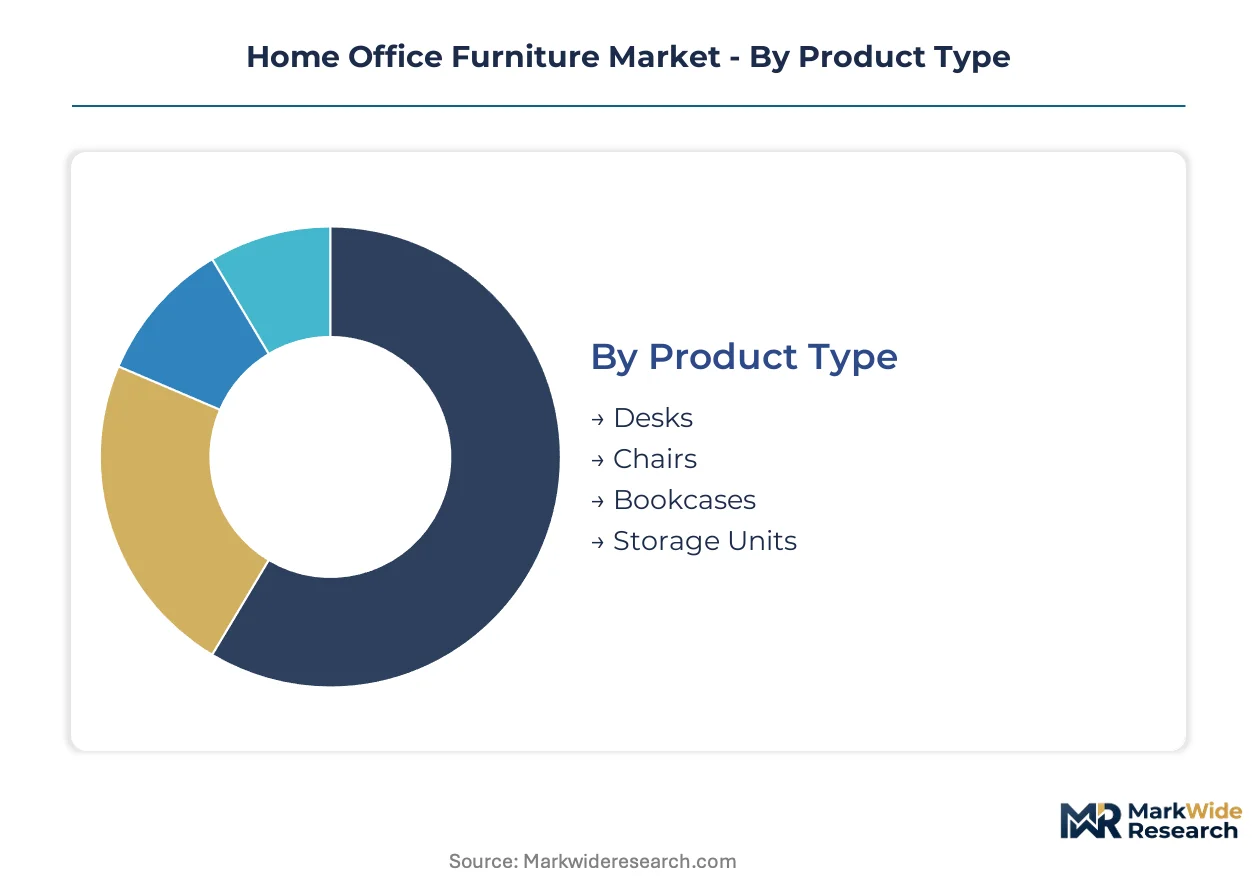
Segmentation in home office furniture reveals where certification premiums concentrate and how channel fragmentation is reshaping margin capture. Understanding these divides exposes which product-material-customer combinations sustain pricing power versus commodity pressure.
Product Type:
Margin pools concentrate in seating where ergonomic certification against ISO 9241-5 commands sustained premiums, while surface categories compete on footprint efficiency and motorized functionality.
- Chairs:Engineered with lumbar support structures, adjustable armrests, and breathable mesh or foam upholstery. Demand clusters among remote workers in Germany and Japan seeking ISO 9241-5 certification for extended residential use. California TB 117-2013 compliance adds foam qualification costs that filter into national pricing.
- Desks:Span static surfaces to motorized sit-stand bases with integrated cable management. Compact urban installations in Japan displace traditional surfaces as durability-to-footprint ratios dominate purchase criteria. FCC emissions compliance for powered variants adds design validation overhead.
- Bookcases:Vertical storage systems with adjustable shelving for document and equipment organization.
- Storage Units:Filing cabinets, credenzas, and modular systems engineered for residential space constraints.
The dominant share belongs to chairs, while desks are closing the gap fastest.
Material:
Cost tiers separate premium sustainable timber from mass-market metal and synthetic alternatives, with embodied carbon metrics beginning to reshape European sourcing decisions.
- Wood:Solid hardwoods and engineered composites sustaining volume leadership across consumer segments. Certified sustainable timber paired with recycled metal frames is gaining share in design-forward German and United States residential markets.
- Metal:Steel and aluminum frames dominating compact urban installations where durability-to-footprint ratios determine selection. Input cost volatility from steel and aluminum swings compresses margins on urban furniture lines.
- Glass:Tempered surface materials for executive residential workstations.
- Plastic:Polymer composites and molded components for entry-level seating shells.
Wood retains the dominant position by volume, though metal is climbing the fastest in urban-constrained applications.
Customer Type:
Application context distinguishes self-directed procurement from corporate-negotiated contracts, with allowance programs fragmenting traditional buying committees.
- Freelancers:Self-employed professionals purchasing certified ergonomic seating through personal expenditure. ISO 9241-5 compliance accelerates product development cycles as this segment pulls premium residential-grade specifications.
- Remote Workers:Distributed employees expensing furniture through corporate allowance programs in the United States and Germany. Self-directed selection compresses sales cycles and forces simultaneous manufacturer presence in contract and direct channels.
- Small Businesses:Owner-operated enterprises furnishing home-based commercial premises.
- Corporations:Enterprise procurement teams unbundling residential furniture from traditional real estate contracts.
Remote workers command the dominant share of current demand expansion, while freelancers represent the steepest expansion trajectory as independent workforce participation rises.
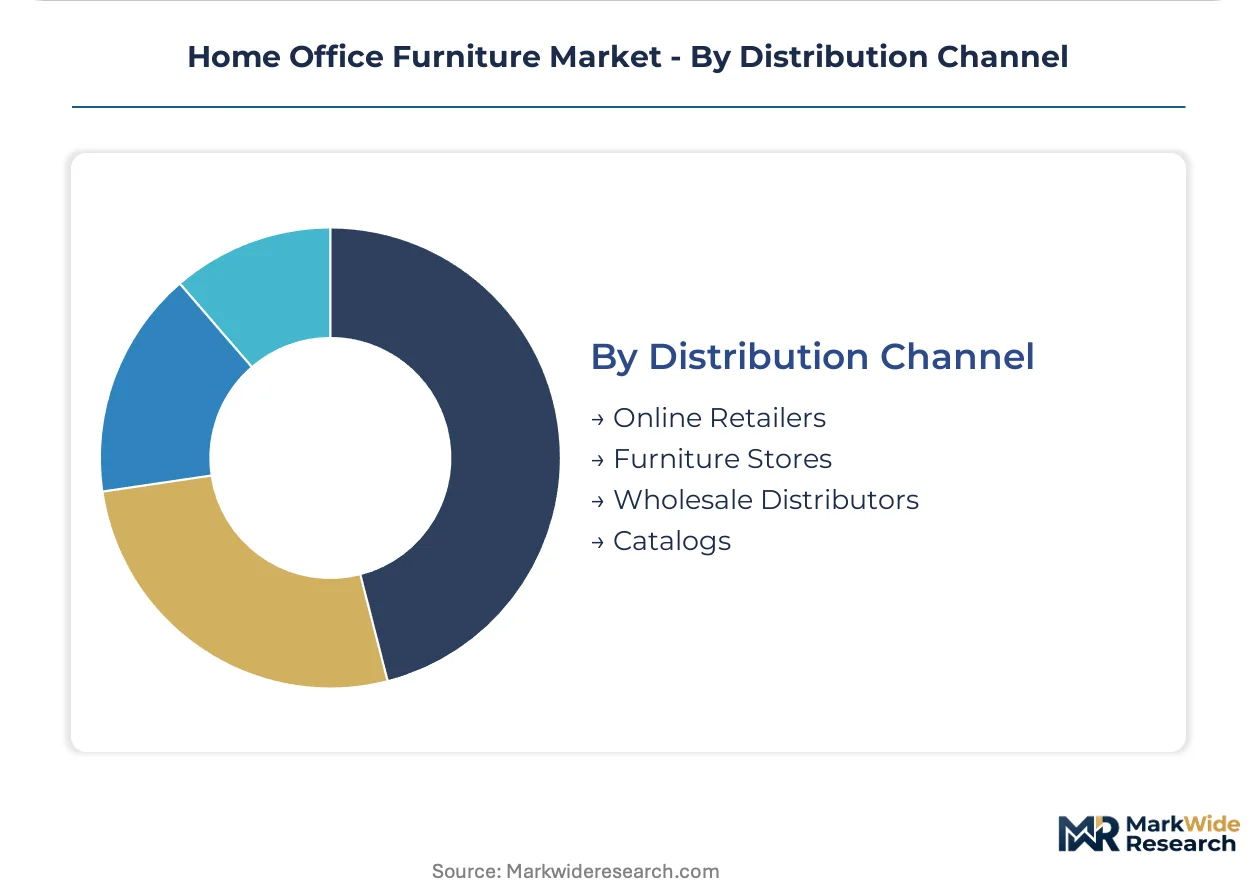
Distribution Channel:
Channel control determines margin retention and data access, with manufacturer-direct platforms displacing traditional intermediaries.
- Online Retailers:E-commerce platforms capturing share through comparison tools and fulfillment speed. Direct-to-consumer expansion enables manufacturers to retain margin and capture usage data that contract dealer networks cannot access.
- Furniture Stores:Brick-and-mortar showrooms with tactile evaluation and white-glove delivery. Physical presence remains critical for ergonomic seating trials where fit verification precedes purchase.
- Wholesale Distributors:B2B intermediaries serving small business and corporate accounts.
- Catalogs:Direct mail and digital lookbooks targeting established customer relationships.
Online retailers hold the dominant share, while furniture stores are gaining share fastest through experiential showroom investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American distribution for containerized furniture imports, while Germany's Rhine-Main rail corridor underwrites European inland logistics for flat-pack desk and chair assemblies.
United States
Remote worker allowance programs in Texas and California are accelerating self-directed ergonomic seating procurement. The Consumer Product Safety Commission enforces California TB 117-2013 as a de facto national flammability baseline for residential upholstery. Furniture assembly clusters in High Point, North Carolina and Grand Rapids, Michigan are retooling for ISO 9241-5 certified production lines.
Germany
Freelancer density in Berlin and Munich is compressing sales cycles for premium sit-stand desk systems. The EU Green Deal's embodied carbon requirements are filtering into sourcing decisions for European-bound frame and surface materials. Industrial furniture fabrication concentrates in Baden-Württemberg, where metalworking heritage supports compact urban durability specifications.
Japan
Tokyo and Osaka apartment dwellers are specifying motorized desk bases where footprint efficiency dominates purchase criteria. METI energy efficiency standards govern powered adjustable furniture connectivity in residential deployments. Manufacturing activity clusters in Aichi Prefecture, where precision drive mechanism suppliers serve both automotive and furniture miniaturization demands.
China
Guangdong Province upholstery foam suppliers are consolidating around TB 117-2013 certified formulations for North American export. The national standardization administration's GB standards for furniture safety create parallel compliance tracks for domestic and export production. Shenzhen and Dongguan electronics clusters are miniaturizing sit-stand desk controllers for residential aesthetic integration.
India
Bengaluru and Hyderabad remote technology workers are pulling demand for entry-level ergonomic seating through self-expense channels. BIS furniture safety standards are evolving to address powered adjustable mechanisms in residential settings. Manufacturing investment concentrates in Gujarat, where metal frame fabrication scales for compact urban durability requirements.
Home Office Furniture Market Key Industry Players
Listed leaders compete with private specialists across channel control and certification intensity. The vendor base separates into three tiers: scale-driven diversified manufacturers, design-forward premium specialists, and direct-to-consumer platform operators. Strategic moves center on backward integration into foam and frame supply, and simultaneous presence in contract dealer and manufacturer-controlled digital channels.
Among diversified manufacturers, Ashley Furniture Industries and La-Z-Boy represent scale-driven archetypes with residential distribution breadth. Steelcase and Herman Miller occupy positions within the premium ergonomic tier, where ISO 9241-5 certification anchors pricing power. Haworth exemplifies the channel-control specialist, maintaining parallel contract dealer and direct-to-consumer platform presence.
| Leading Market Players |
|---|
| Ashley Furniture Industries |
| HNI Corporation |
| Steelcase |
| La-Z-Boy |
| Herman Miller |
| Haworth |
| MillerKnoll |
| Teknion |
| IKEA |
| Others |
Cost & Logistics Intelligence
California TB 117-2013 flammability standards gate both supply qualification and price differentiation simultaneously, forcing foam suppliers to absorb certification costs while manufacturers pass compliance premiums to residential buyers seeking multi-state distribution eligibility.
Pricing Analysis
Volume-discount tiering structures stratify across premium ergonomic seating with ISO 9241-5 certification, standard static desks, and economy polymer-shell chairs. Price differentiation hinges on certification grade and brand heritage, with Steelcase and Herman Miller commanding sustained premiums. Cost compression in the standard tier intensifies because metal frame input volatility squeezes assembler margins. Freelancer self-expense channels exhibit highest price sensitivity, while corporate allowance programs sustain premium tier demand.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time coordination for motorized desk electronics from Shenzhen and Dongguan, while strategic stockpiling dominates TB 117-2013 compliant foam sourcing from Guangdong Province. Raw material dependencies center on steel and aluminum frames, smolder-resistant upholstery foam, and miniaturized drive mechanisms. Single-source vulnerability concentrates in Guangdong foam certification clusters. Distribution runs through Port of Long Beach containerized imports and contract dealer networks alongside manufacturer-direct platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 9241-5 ergonomic certification mandates are disrupting competitive access, compressing product development timelines and forcing simultaneous investment in laboratory testing capacity and direct-to-consumer channel infrastructure.
For Market Incumbents: Consolidate backward integration into TB 117-2013 certified foam supply to neutralize Guangdong single-source risk. Capture ISO 9241-5 testing capability through captive laboratory investment or exclusive third-party partnerships, defending margin position against emerging direct-to-consumer specialists eroding contract dealer channel share.
For New Entrants and Emerging Players: Anchor in biophilic material convergence, pairing certified sustainable timber with recycled metal frame systems for design-forward German and United States residential segments. Target freelancer self-expense channels through digital-native ergonomic seating platforms with rapid fulfillment and virtual fit-assessment tools.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across motorized sit-stand desk manufacturing due to FCC emissions compliance validation and drive mechanism miniaturization R&D. Five-to-ten year viability favors acquirers of specialized ergonomic certification laboratories and precision electronics assemblers with existing METI or FCC compliance track records. Watch for EU Green Deal embodied carbon threshold announcements as inflection indicator for European-bound production sourcing decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Foam Supply | Neutralizes Guangdong single-source concentration risk for TB 117-2013 compliance. |
| ISO 9241-5 Testing Laboratory Acquisition | Captures scarce certification capacity bottlenecking competitor product launches. |
| Direct-to-Consumer Platform Expansion | Retains margin and usage data inaccessible through contract dealer networks. |
| Biophilic Material Product Line Launch | Positions for EU Green Deal embodied carbon requirements in European-bound production. |
| Precision Drive Mechanism Joint Venture | Secures Aichi Prefecture miniaturization expertise for residential aesthetic integration. |
Research Approach
A spread of perspectives from furniture manufacturing executives, ergonomic certification laboratory directors, contract dealer network managers, and direct-to-consumer platform operators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC 10-K filings, and California Bureau of Electronic and Appliance Repair regulatory databases. Bottom-up demand modeling triangulated against top-down production capacity assessments.
Segmentation dimensions modeled span product type, material composition, customer archetype, and distribution channel across the analysis window. CAGRs derived from historical shipment trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated ISO 9241-5 certification adoption curves and motorized desk base cost compression rates.
Material uncertainties — steel and aluminum input volatility, TB 117-2013 enforcement intensity variations, and EU Green Deal threshold finalization — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding freelancer workforce participation and remote worker allowance program expansion. Revision becomes warranted when Guangdong foam supplier consolidation crosses critical concentration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Office Seat Cushion Market
Office Furniture
India Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
Institutional Furniture Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
Japan Office Furniture Market
Office Furniture
Office Chairs Market
Office Furniture
Home Office Desk Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Canada Office Furniture Market