
 North America Smart Furniture Market | 2026-2036
North America Smart Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Furniture Market Analytics
Market Context
Modular workstation bundling is consolidating buyer choice across the North America Smart Furniture Market as enterprises shift from standalone desks to integrated productivity pods. Sleep Number Corporation leverages biometric sleep tracking to anchor its position in residential wellness segments. Steelcase Inc. competes through embedded IoT desk systems designed for hybrid office redeployment. HNI Corporation sustains manufacturing scale advantages across mid-market commercial seating with programmable ergonomic controls.
Technical Definition and Segments
North America Smart Furniture comprises electronically augmented interior fixtures incorporating sensor arrays, microcontrollers, and wireless connectivity modules to enable automated adjustment, usage analytics, and environmental responsiveness in built environments. These systems typically integrate pressure sensors, ambient light detectors, and low-energy Bluetooth transceivers to deliver real-time posture correction, climate synchronization, or occupancy-based power management for commercial and residential installations. Smart Beds lead product type revenue pools due to premium pricing of biometric monitoring capabilities, while IoT-enabled connectivity infrastructure represents the fastest-expanding technology layer as interoperability standards mature. The Commercial end user segment commands concentrated margin pools, though Hospitality applications are gaining traction through guest experience differentiation programs.
Regulatory Outlook
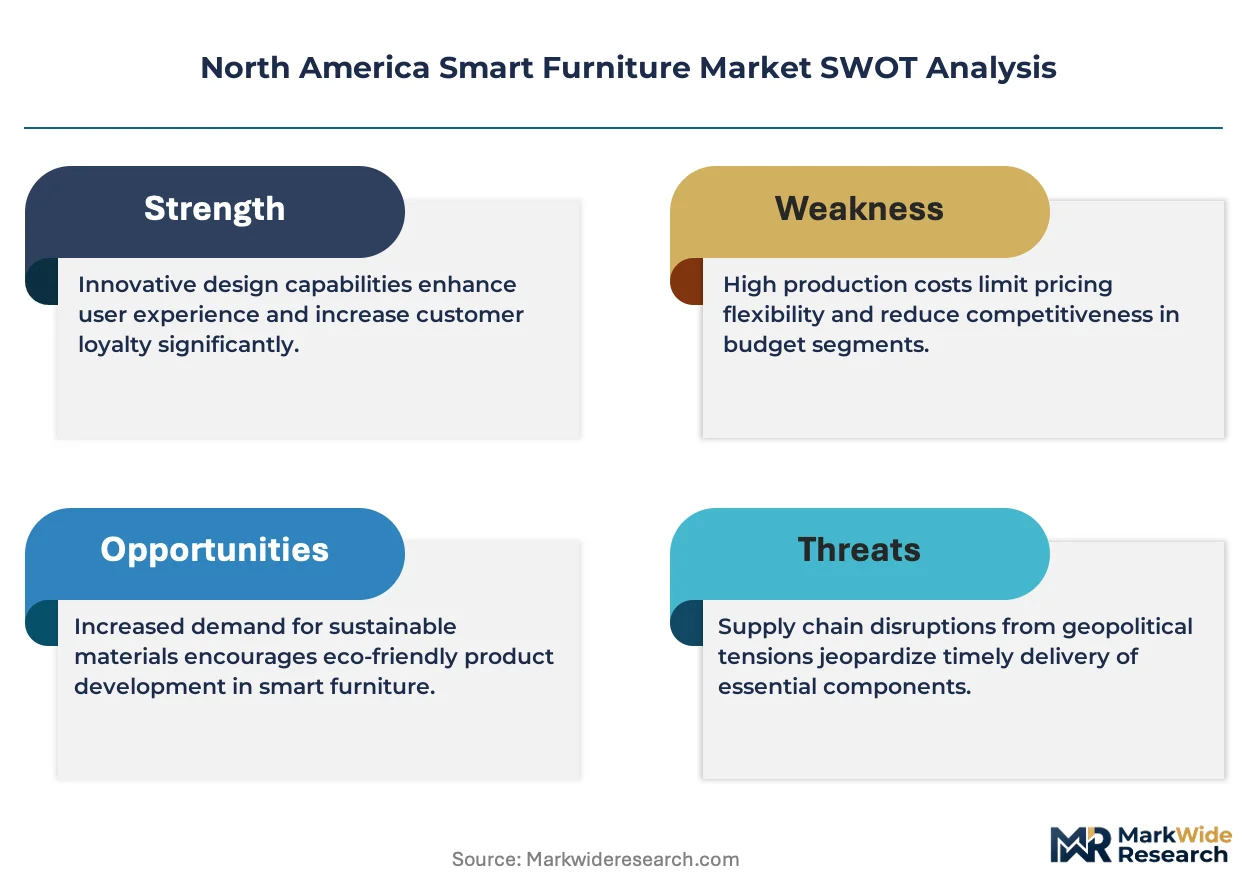
The FCC governs wireless transmission protocols embedded in connected furniture, while OSHA ergonomic guidelines shape workplace product specifications and California's Title 24 building efficiency standards directly influence sensor-activated power management feature requirements. The EPA Energy Star program and evolving state-level e-waste directives in New York and Illinois are tightening material disclosure and end-of-life protocol obligations for manufacturers. Stakeholders must monitor harmonization gaps between federal wireless certification and emerging state privacy rules governing biometric data collection from embedded furniture sensors.
Market Dynamics
Modular workstation bundling is compressing buyer decision cycles across corporate retrofit programs, while California's Title 24 efficiency mandates force sensor-activated power management into specification sheets. Procurement teams now treat furniture as networked infrastructure rather than depreciable assets.
Growth Catalysts
- OSHA Ergonomic Guidelines:Workplace safety standards are mandating adjustable workstation specifications, accelerating sensor-embedded desk deployments across Fortune 500 headquarters and government facilities.
- Texas Metro Clusters:Corporate relocation waves into Austin and Dallas are generating concentrated demand for hybrid-ready office infrastructure with embedded occupancy analytics.
- Biometric Sleep Tracking:Residential wellness segments are absorbing premium-priced smart bed systems as consumers integrate sleep data into health management routines.
Market Restraints
- Semiconductor Supply Concentration:Microcontroller and Bluetooth transceiver sourcing remains vulnerable to Taiwan and South Korea fabrication bottlenecks, extending lead times for sensor-embedded fixtures.
- FCC Certification Timelines:Wireless protocol approvals for new furniture product lines add six to nine months to commercialization schedules, compressing margin recovery windows.
- Manual Ergonomic Furniture:Non-connected adjustable desks and chairs continue capturing price-sensitive mid-market segments, limiting smart product penetration below enterprise tiers.
Strategic Opportunities
- Hospitality Guest Experience Programs:Hotels in California and Florida are piloting connected room fixtures that synchronize lighting, climate, and furniture positioning through unified guest preference profiles.
- Canada Building Energy Codes:Provincial efficiency mandates in Ontario and British Columbia are creating regulatory pull for sensor-activated power management in commercial installations.
- Matter Protocol Convergence:Interoperability between Thread and Wi-Fi is enabling cross-brand furniture networks that reduce buyer lock-in concerns and expand ecosystem attach rates.
Industry Challenges
- Embedded Firmware Talent Scarcity:Furniture manufacturers face acute shortages of engineers capable of integrating low-energy Bluetooth stacks with real-time sensor fusion algorithms.
- Biometric Data Compliance:Illinois BIPA and emerging state privacy frameworks impose complex consent and retention protocols for sleep and posture data harvested from residential smart beds.
- Legacy Building Management System Integration:Commercial smart furniture deployments require costly middleware development to interface with existing HVAC and access control networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Furniture Market |
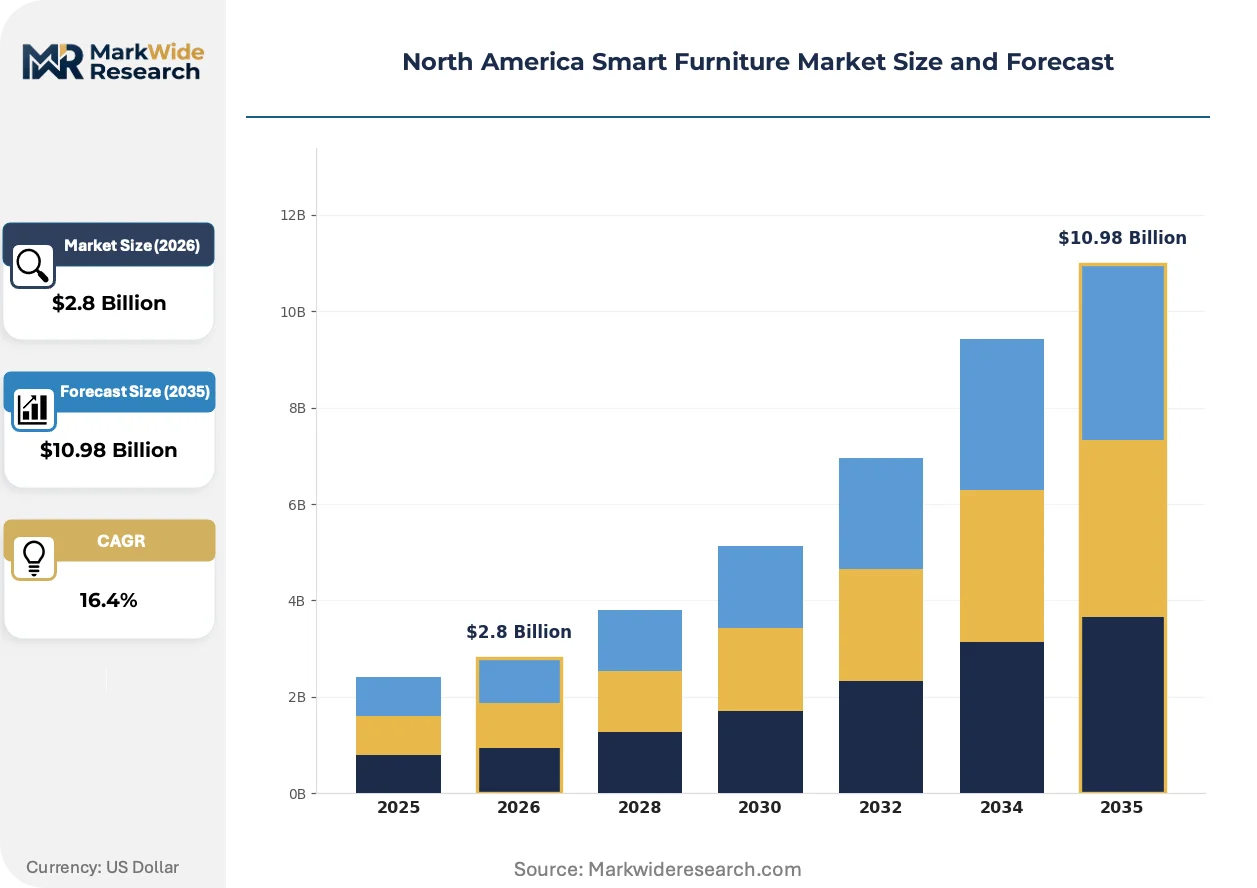
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Desks, Smart Sofas, Smart Tables, Smart Beds Technology: IoT, RFID, Bluetooth, Wireless Charging End User: Residential, Commercial, Hospitality, Educational Distribution Channel: E-commerce, Retail, Direct Sales, Distributors |
| Companies Covered | IKEA, Sobro, Modoola Ltd, Milano Smart Living, Carlo Ratti, HNI Corporation, Sleep Number Corporation, Steelcase Inc., Haworth Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Furniture Market Evolving Landscape
Edge computing architectures are migrating sensor processing from cloud endpoints into furniture-mounted microcontrollers, reducing latency for real-time posture correction and occupancy detection. This shift is compressing hardware BOMs while raising firmware complexity requirements.
Capacitive sensing arrays with embedded AI inference engines are consolidating multiple biometric inputs—pressure distribution, heart rate variability, respiration patterns—into single-module sleep monitoring systems. High-end hospitality chains and luxury residential developers are specifying these integrated platforms to differentiate amenity packages. The technology is consolidating vendor landscapes as standalone sensor suppliers lose socket space to all-in-one module providers.
California's Title 24 Building Efficiency Standards are mandating automated daylight harvesting and plug load control in new commercial construction, directly embedding sensor-activated power management into furniture procurement specifications. Manufacturers serving the California tech corridor must now certify products through the California Energy Commission's appliance efficiency database. The regulation is forcing rapid SKU rationalization as non-compliant product lines lose specification access in the continent's largest smart furniture demand cluster.
Enterprise procurement teams are unbundling furniture acquisition from facilities management contracts, creating direct vendor relationships that bypass traditional dealer networks. Corporate real estate departments in Texas and Illinois are negotiating multi-year sensor data licensing agreements separate from hardware purchase orders. This disintermediation is most pronounced among technology sector employers with in-house workplace analytics capabilities, who treat furniture sensor streams as strategic workforce intelligence assets rather than operational overhead.
North America Smart Furniture Market Segmentation
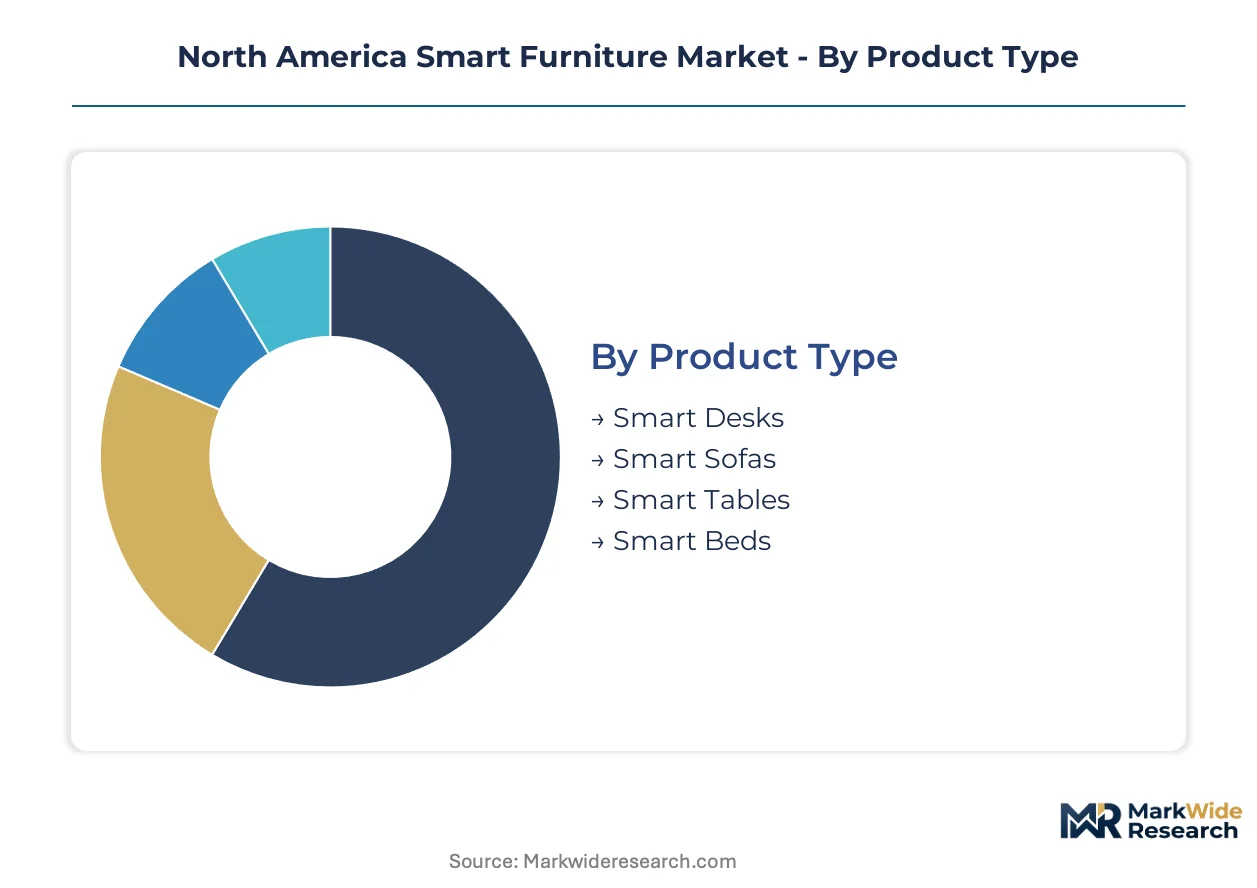
Segmentation in the North America Smart Furniture Market reveals distinct procurement patterns across connected fixture categories. Technology integration depth and end-use application complexity determine pricing architecture and vendor selection criteria for buyers across the United States and Canada.
Product Type:
Supply concentration among biometric sensor manufacturers favors integrated platforms over modular component sourcing across all furniture categories.
- Smart Beds:Capacitive sensing arrays with embedded AI inference engines consolidate pressure distribution, heart rate variability, and respiration monitoring into single-module systems. California and Texas luxury residential developers specify these platforms for amenity differentiation, though Illinois BIPA compliance adds consent protocol complexity for biometric data retention.
- Smart Desks:Embedded IoT desk systems incorporate pressure sensors, ambient light detectors, and low-energy Bluetooth transceivers for real-time posture correction and occupancy-based power management. Fortune 500 headquarters in Austin and Dallas drive concentrated demand as OSHA ergonomic guidelines mandate adjustable workstation specifications.
- Smart Sofas:Connected seating platforms integrate climate synchronization and positioning memory through unified guest preference profiles in hospitality pilot programs.
- Smart Tables:Sensor-activated surfaces enable automated daylight harvesting responses required under California Title 24 building efficiency standards.
Smart Beds absorb the bulk of installed capacity; Smart Desks are expanding most quickly.
Technology:
Cost tier differentiation separates premium integrated platforms from connectivity-only configurations across the technology stack.
- IoT:Interoperability between Thread and Wi-Fi protocols enables cross-brand furniture networks that reduce buyer lock-in concerns. Enterprise procurement teams in Texas metro clusters treat IoT-enabled connectivity infrastructure as strategic workforce intelligence assets separate from hardware acquisition.
- Bluetooth:Low-energy transceiver integration delivers real-time environmental responsiveness with minimal power draw for battery-operated residential fixtures.
- RFID:Asset tracking capabilities support inventory management for commercial furniture fleets in government facilities.
- Wireless Charging:Inductive power transfer modules embed into work surfaces for device charging without cable clutter in hybrid office deployments.
IoT-enabled platforms command premium positioning; Bluetooth maintains volume leadership across price-sensitive segments.
End User:
Application complexity varies dramatically between residential wellness integration and commercial building management system interfacing requirements.
- Commercial:Corporate real estate departments unbundle furniture acquisition from facilities management contracts, negotiating multi-year sensor data licensing agreements. Middleware development costs for HVAC and access control integration create significant deployment barriers.
- Residential:Consumers integrate sleep data from biometric tracking systems into personal health management routines, absorbing premium pricing for wellness-connected fixtures.
- Hospitality:California and Florida hotels pilot connected room fixtures synchronizing lighting, climate, and furniture positioning through guest preference profiles.
- Educational:Campus procurement programs specify adjustable workstations for student health compliance in institutional retrofit programs.
Commercial deployments dominate revenue concentration; Hospitality applications gain share through guest experience differentiation programs.
Distribution Channel:
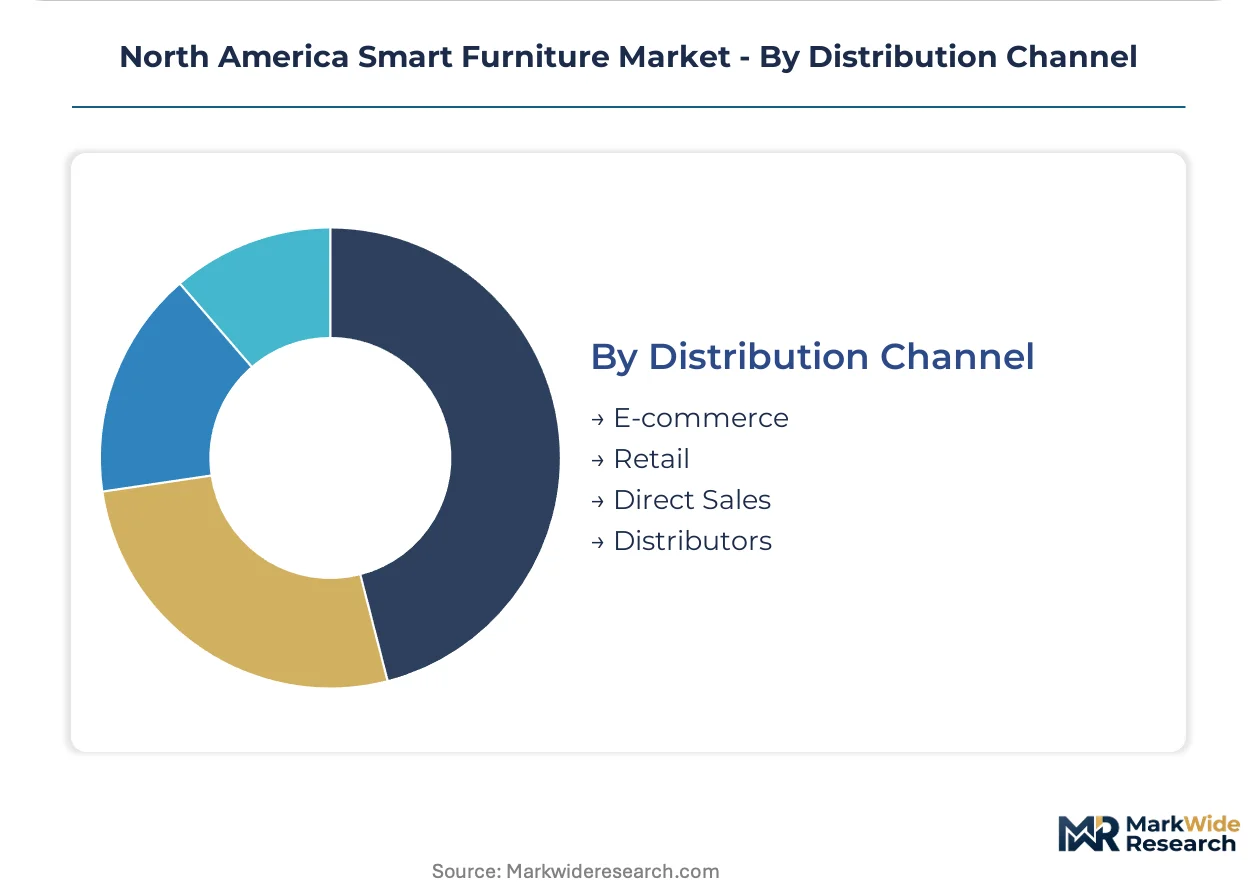
Customer type segmentation separates enterprise direct procurement from consumer retail pathways with distinct margin structures.
- Direct Sales:Corporate real estate departments establish direct vendor relationships bypassing traditional dealer networks, treating furniture sensor streams as operational intelligence assets.
- E-commerce:Digital platforms enable residential consumers to configure biometric sleep systems with home delivery and self-installation options.
- Retail:Brick-and-mortar showrooms support tactile evaluation of ergonomic adjustment mechanisms for mid-market commercial buyers.
- Distributors:Dealer networks maintain specification influence in government and educational procurement channels with formal bidding requirements.
Direct Sales channels capture the steepest expansion trajectory; Distributor relationships retain institutional segment control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in the United States and Canada while consumption spreads across major metropolitan corridors. Production clusters serve retrofit demand from corporate headquarters and residential wellness installations. Regulatory divergence between federal and state levels shapes procurement specifications differently across sub-regions.
United States
Corporate office retrofits and hospitality guest experience programs drive procurement volumes across Texas metro clusters and California's tech corridor. OSHA ergonomic guidelines mandate adjustable workstation specifications for Fortune 500 headquarters, while FCC wireless certification governs embedded connectivity modules. Austin and Dallas generate concentrated demand for hybrid-ready infrastructure with occupancy analytics.
Canada
Provincial building energy codes in Ontario and British Columbia tighten efficiency requirements for connected fixtures in commercial installations. Health Canada oversees product safety standards for biometric sensor integration in residential wellness systems. Toronto and Vancouver anchor specification activity for sensor-activated power management in new construction.
California
Title 24 Building Efficiency Standards mandate automated daylight harvesting and plug load control in commercial construction, embedding sensor-activated power management into furniture specifications. The California Energy Commission certifies products through its appliance efficiency database. San Francisco Bay Area and Los Angeles metro areas represent the continent's largest smart furniture demand cluster.
Texas
Corporate relocation waves into Austin and Dallas generate concentrated procurement of IoT-enabled desk systems for hybrid office redeployment. State-level business incentives attract technology sector employers with in-house workplace analytics capabilities. Houston and San Antonio extend demand for connected fixtures through hospitality and healthcare facility expansions.
Illinois
Biometric data compliance requirements under state privacy frameworks impose consent protocols for sleep and posture data from residential smart beds. Chicago anchors commercial retrofit activity for government and educational procurement channels. The state's e-waste directives tighten material disclosure obligations for manufacturers serving Midwest institutional buyers.
North America Smart Furniture Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures intensify as procurement teams unbundle furniture acquisition from facilities management contracts, favoring vendors with integrated sensor data platforms. Three archetypes dominate: legacy furniture manufacturers with IoT retrofit capabilities, sleep technology specialists with biometric platforms, and modular workstation bundlers serving hybrid office deployments. M&A activity targets firmware engineering talent, while strategic partnerships address legacy building management system integration gaps.
Among legacy furniture specialists, Steelcase Inc. and HNI Corporation exemplify scale-driven commercial positioning with programmable ergonomic controls. Sleep Number Corporation anchors the residential wellness tier through biometric sleep tracking specialization. These three entities represent distinct competitive vectors: enterprise IoT infrastructure, mid-market manufacturing scale, and consumer health integration.
| Leading Market Players |
|---|
| IKEA |
| Sobro |
| Modoola Ltd |
| Milano Smart Living |
| Carlo Ratti |
| HNI Corporation |
| Sleep Number Corporation |
| Steelcase Inc. |
| Haworth Inc. |
| Others |
Value Network & Pricing Analysis
Firmware engineering talent scarcity in the San Francisco Bay Area and Austin tech corridors widens labor-cost differentials between premium integrated platforms and connectivity-only configurations. These labor-cost spreads translate directly into pricing-tier stratification across enterprise IoT infrastructure and mid-market ergonomic seating categories.
Pricing Analysis
Margin tightening in mid-market commercial seating traces to manual ergonomic furniture alternatives capturing price-sensitive procurement below enterprise tiers. Three-tier pricing structure across premium integrated platforms, standard connected fixtures, and economy manual alternatives dominates the market. Certification through California Energy Commission appliance efficiency databases and FCC wireless protocol approvals drives price differentiation between compliant and non-compliant product lines. Enterprise buyers in Texas metro clusters exhibit lowest price sensitivity as they unbundle furniture acquisition from facilities management contracts and negotiate separate sensor data licensing agreements.
Supply Chain Analysis
Returns and refurbishment flows for sensor-embedded residential beds create reverse-logistics complexity as Illinois BIPA compliance requirements mandate secure biometric data destruction prior to remanufacturing. Semiconductor fabrication concentrates in Taiwan and South Korea for microcontroller and Bluetooth transceiver components, while final assembly clusters in Mexico and domestic United States facilities. Supply chain risk centers on single-source vulnerability for capacitive sensing arrays with embedded AI inference engines. Distribution runs through direct sales channels for enterprise procurement, e-commerce platforms for residential consumers, and traditional dealer networks for government and educational institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as firmware engineering talent scarcity forces weaker manufacturers lacking embedded systems capabilities toward exit or acquisition.
For Market Incumbents: Deploy certification investment as the primary lever to defend specification access against emerging modular workstation bundlers. Steelcase Inc. and HNI Corporation should accelerate California Energy Commission database certification for sensor-activated power management features before Title 24 compliance becomes mandatory. Incumbents must acquire firmware engineering talent through targeted hiring in Austin and Dallas metro clusters to offset embedded systems capability gaps. For New Entrants and Emerging Players: Capture hospitality guest experience programs in California and Florida as the most penetrable white-space target, where connected room fixtures remain undersupplied relative to corporate retrofit demand concentration. New entrants should pursue direct vendor relationships with boutique hotel chains bypassing traditional dealer networks, offering unified guest preference profile synchronization as the core go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with sleep technology specialists possessing biometric platform expertise given residential wellness integration tailwinds. Long-term viability favors vendors with captive firmware development capabilities and established California Energy Commission certification pathways. Investors should monitor Matter protocol convergence adoption rates across Thread and Wi-Fi interoperability as the inflection indicator for ecosystem attach rate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Engineering Acquisition | Addresses acute talent scarcity in low-energy Bluetooth stack integration for sensor-embedded fixtures. |
| California Energy Commission Certification | Secures specification access in the continent's largest smart furniture demand cluster under Title 24 mandates. |
| Hospitality Pilot Program Expansion | Captures guest experience differentiation budgets in California and Florida hotel renovation cycles. |
| Direct Sales Channel Development | Bypasses traditional dealer networks as enterprise procurement teams unbundle furniture from facilities contracts. |
| Matter Protocol Integration | Enables cross-brand furniture networks that reduce buyer lock-in concerns and expand ecosystem attach rates. |
Research Methodology
Document review covered SEC 10-K filings, FCC equipment authorization databases, California Energy Commission appliance efficiency listings, and OSHA ergonomic guideline publications, complemented by interviews with corporate real estate directors, furniture procurement managers, firmware engineering leads, and hospitality operations executives. Primary fieldwork validated secondary data points through structured conversations with commercial facility managers in Texas metro clusters and residential smart bed consumers in California and Illinois markets. Bottom-up demand estimation triangulated against top-down market sizing derived from trade association membership data and customs import records.
Segment-level outputs across the projection horizon reflect modeling of product type integration depth, technology protocol architecture, end-use application complexity, and distribution channel margin structure. CAGRs were derived from regression analysis of historical procurement velocity against regulatory mandate implementation timelines and corporate relocation patterns. Industry-specific forecast inputs included semiconductor lead time indices from Taiwan and South Korea fabrication facilities and Title 24 building permit issuance data from California metropolitan statistical areas.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to harmonization gaps between federal wireless certification and emerging state privacy rules governing biometric data collection. Practitioners should monitor Illinois BIPA enforcement patterns and Ontario building energy code adoption timelines for early signals of compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United Kingdom Home Furniture Market
Furniture
USA and Canada Teak Veneer Sheet Market
Furniture
Global Smart Furniture Market
Furniture
Bounding Table Market
Furniture
Canada Home Furniture Market
Furniture
Spain Furniture Market
Furniture
Europe Furniture Market
Furniture
Brazil Furniture Market
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
Italy Office Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Children Furniture Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Ready-To-Assemble (RTA) Furniture Market