
 Europe Office Furniture Market | 2026-2036
Europe Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Office Furniture Market Analysis
Subscription-based workspace furnishing is recalibrating how office furniture gets monetized across Europe. Steelcase leverages its European manufacturing footprint to anchor large corporate rollouts. Vitra differentiates through design-led ergonomic systems that command specification in architect-driven projects. Kinnarps competes on rapid configuration tools that let facility managers re-plan offices without external consultants.
Europe office furniture encompasses workstations, seating, storage, and partitioning systems engineered to EN 527 and EN 1335 standards for dimensional stability, load-bearing capacity, and user safety in commercial environments. Manufacturers typically employ steel tube framing with laminated particleboard surfaces, powder-coated finishes, and modular connection hardware to enable reconfiguration as floor plans evolve. The product type dimension shows chairs capturing disproportionate margin pools due to ergonomic certification requirements, while desks face commoditization pressure from flat-pack imports. By material, metal-and-wood hybrid construction leads specification in corporate headquarters, whereas all-plastic seating gains traction in high-turnover coworking locations where sanitization protocols dominate purchasing criteria.
The EU Ecodesign Directive and national transpositions through Germany's Federal Environment Agency shape mandatory durability and recyclability thresholds that filter market access for non-compliant imports. France's AGEC law and extended producer responsibility schemes force brands to finance end-of-life collection, tilting procurement toward domestic and near-European suppliers with established reverse logistics. REACH compliance on surface treatments and flame retardants adds further testing burden that favors mid-to-large manufacturers with in-house chemical assessment capacity. Stakeholders must monitor how the EU's forthcoming Digital Product Passport requirements will reshape competitive advantage toward data-transparent supply chains.
Market Dynamics
The EU Ecodesign for Sustainable Products Regulation and the Digital Product Passport mandate are compressing product development cycles while forcing manufacturers to re-engineer supply chains for material traceability and end-of-life accountability.
Growth Catalysts
- Flexible workspace expansion:Operators across Germany and France are scaling procurement volumes for modular systems that accommodate rapid tenant turnover.
- REACH compliance infrastructure:Chemical assessment capabilities at mid-to-large manufacturers create market access barriers that protect domestic European producers from flat-pack import competition.
- Circular economy pilots:Furniture-as-a-service leasing models in the Benelux cluster generate recurring revenue streams and premium positioning for certified recycled material offerings.
Market Restraints
- Particleboard cost volatility:Laminated wood composite pricing fluctuates with European timber harvest quotas and energy-intensive resin production costs.
- Reverse logistics concentration:France's AGEC law extended producer responsibility schemes favor domestic suppliers with established collection networks, limiting cross-border supplier entry.
- Flame retardant technical limitations:REACH-compliant surface treatments reduce durability in high-sanitization coworking environments compared to legacy chemistries.
Strategic Opportunities
- Eastern European manufacturing footprint:Nearshoring production to Poland and Romania reduces logistics costs for German and Austrian corporate headquarters markets.
- Architect-driven specification channel:Design-led ergonomic systems command premium positioning in Netherlands and Denmark commercial development projects.
- EU Green Deal procurement mandates:Public sector tender requirements for recycled content create protected demand pools for certified domestic manufacturers.
Industry Challenges
- Chemical assessment talent scarcity:In-house REACH compliance expertise concentrates at large manufacturers, creating recruitment bottlenecks for mid-tier firms.
- Legacy system integration friction:Facility management software from incumbent providers resists interoperability with rapid configuration tools for office re-planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Office Furniture Market |
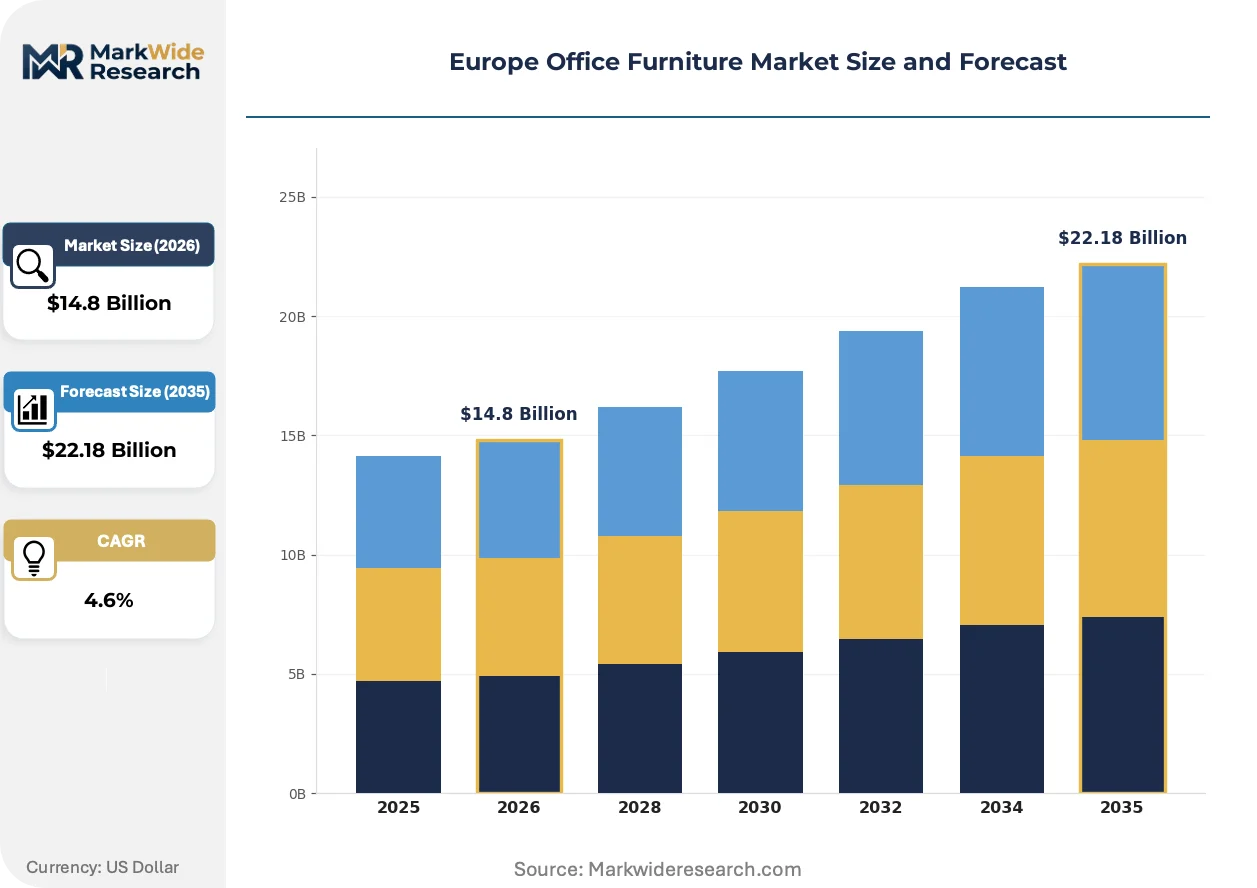
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Storage Units, Cubicles Material: Wood, Metal, Plastic, Glass End User: Corporate Offices, Small Businesses, Coworking Spaces, Government Agencies Design Style: Modern, Ergonomic, Traditional, Minimalist |
| Companies Covered | Nowy Styl, Vitra, Steelcase, Flokk, Bene, Herman Miller, Kinnarps, Sedus Stoll, Haworth, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Office Furniture Market Emerging Trajectories
Sensor-embedded furniture and AI-driven space analytics are transforming how European facility managers optimize real estate utilization, compressing the traditional seven-year furniture replacement cycle.
Occupancy-sensing desk systems is integrating real-time utilization data into building management platforms. Corporate real estate teams in London and Frankfurt are piloting these systems at scale. The technology is integrating lease negotiation leverage by providing granular space-efficiency metrics that justify denser floor plans.
France's AGEC law anti-waste provisions mandate repairability indices and spare parts availability for commercial furniture. Manufacturers must now maintain decade-long component inventories and publish disassembly instructions. Seating categories face the steepest compliance burden due to mechanical wear parts and ergonomic certification dependencies.
Subscription-based furnishing contracts are displacing capital expenditure procurement in flexible workspace and satellite office deployments. Landlords in Amsterdam and Berlin now bundle furniture-as-a-service into lease agreements. This shift concentrates purchasing authority with property developers rather than tenant facility managers.
Europe Office Furniture Market Segmentation
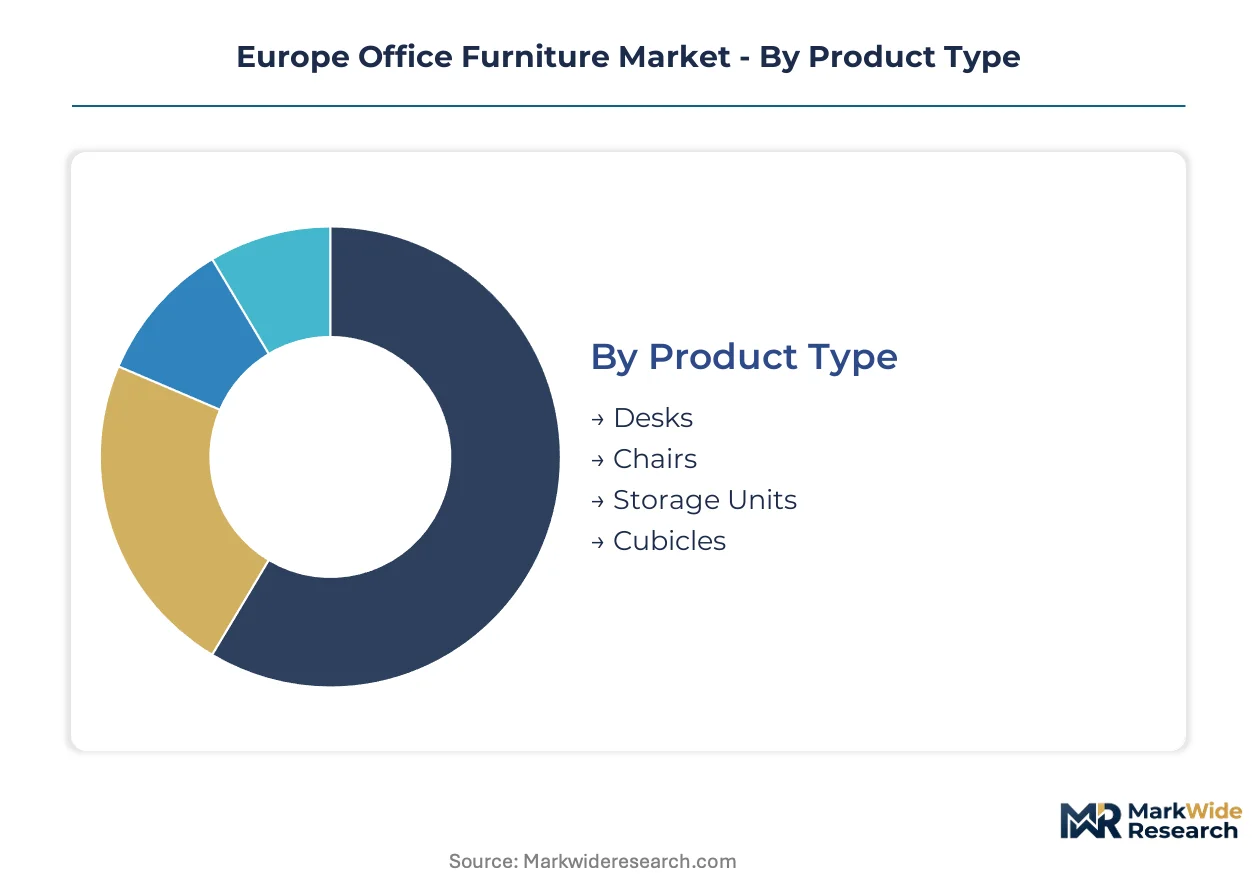
Segmentation in the Europe office furniture market reveals how procurement authority is fragmenting across new buyer types and how regulatory pressure is reshaping material specifications. Understanding these divides helps manufacturers calibrate product development and channel strategy for distinct margin pools.
Product Type:
Standalone furniture systems dominate capital expenditure budgets, while embedded sensor-enabled products are penetrating lease-based procurement models.
- Desks:Engineered to EN 527 standards for dimensional stability and load-bearing capacity, typically employing steel tube framing with laminated particleboard surfaces. Procurement concentrates in Germany and France where flexible workspace operators are scaling modular systems for rapid tenant turnover, though flat-pack imports are compressing margins in this category.
- Chairs:Subject to EN 1335 ergonomic certification requirements with mechanical wear parts that trigger France's AGEC law repairability mandates. Benelux clusters command premium positioning for certified recycled material offerings, creating disproportionate margin pools relative to other product types.
- Storage Units:Metal-and-wood hybrid construction leads specification in corporate headquarters across the Netherlands and Denmark.
- Cubicles:Demand is softening as open-plan and activity-based working models displace traditional partitioning systems in new London and Frankfurt commercial developments.
Chairs lead volumes today; desks are gaining share fastest in coworking deployments.
Material:
Cost tiers separate premium-specified corporate projects from high-turnover flexible workspace procurement where sanitization protocols dominate purchasing criteria.
- Wood:Laminated particleboard pricing fluctuates with European timber harvest quotas and energy-intensive resin production costs. REACH-compliant surface treatments add testing burden that favors mid-to-large manufacturers with in-house chemical assessment capacity.
- Metal:Steel tube framing with powder-coated finishes enables modular reconfiguration as floor plans evolve. Germany's Federal Environment Agency shapes mandatory durability thresholds that filter market access for non-compliant imports.
- Plastic:All-plastic seating gains traction in high-sanitization coworking locations across Berlin and Amsterdam where landlords bundle furniture-as-a-service into lease agreements.
- Glass:Premium positioning in architect-driven Netherlands and Denmark commercial development projects where design-led ergonomic systems command specification.
Metal-and-wood hybrids dominate corporate headquarters today; certified recycled materials are climbing the fastest under EU Green Deal procurement mandates.
End User:
Customer type determines whether procurement flows through facility managers, property developers, or public sector tender processes with diverging technical requirements.
- Corporate Offices:Large corporate rollouts anchor demand for rapid configuration tools that let facility managers re-plan offices without external consultants. Steelcase leverages its European manufacturing footprint to serve this segment.
- Small Businesses:Price-sensitive procurement favors flat-pack imports, though REACH compliance infrastructure creates market access barriers that protect domestic European producers.
- Coworking Spaces:Subscription-based furnishing contracts are displacing capital expenditure procurement, concentrating purchasing authority with property developers in Amsterdam and Berlin.
- Government Agencies:Public sector tender requirements for recycled content create protected demand pools for certified domestic manufacturers under EU Green Deal frameworks.
Corporate offices anchor revenue today; coworking spaces are expanding most quickly.
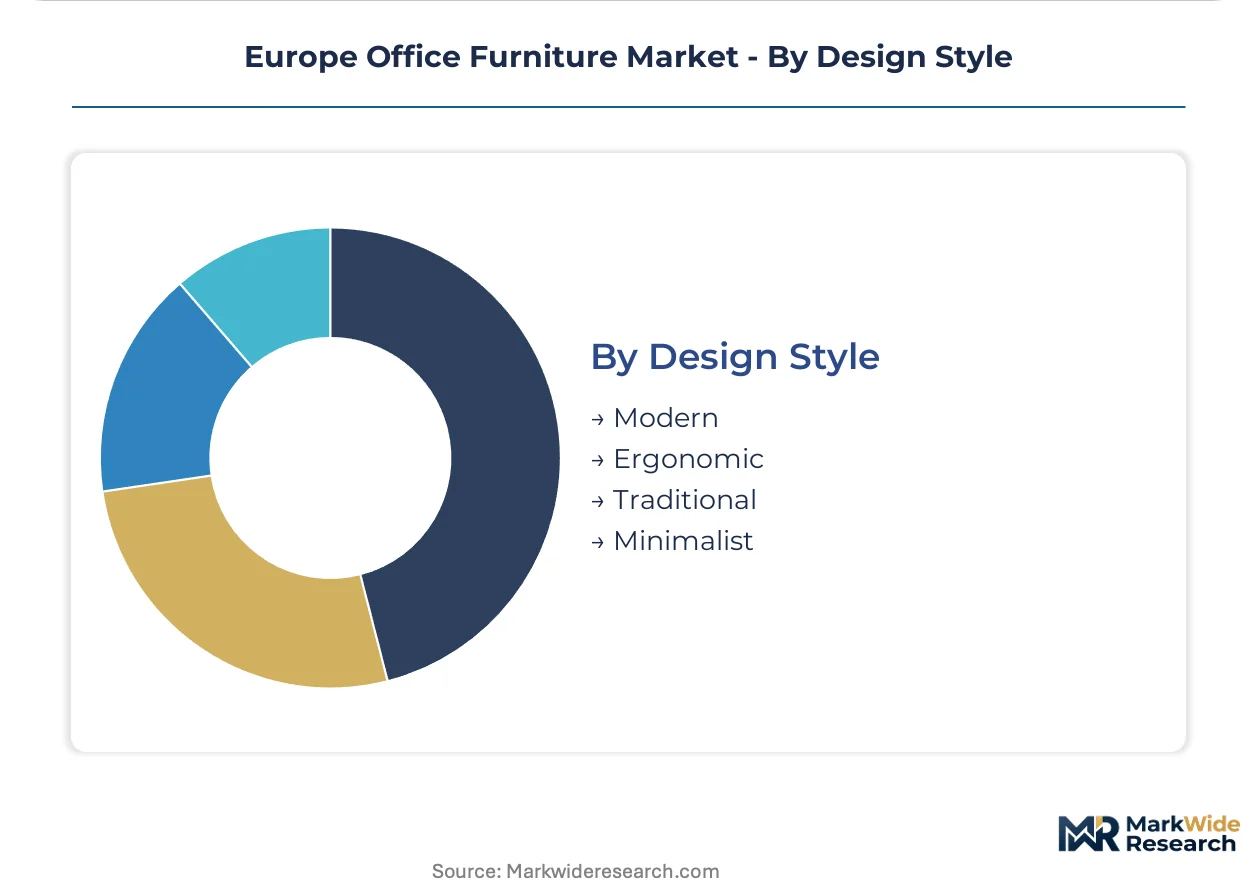
Design Style:
Maturity curves separate established ergonomic certification systems from emerging minimalist aesthetics targeting satellite office deployments.
- Modern:Clean lines and modular connection hardware dominate specification in flexible workspace rollouts across Germany and France.
- Ergonomic:Design-led systems command premium positioning in architect-driven projects, with Vitra differentiating through specification in Netherlands and Denmark commercial developments.
- Traditional:Legacy wood finishes retain niche demand in established corporate headquarters undergoing phased refurbishment rather than full replacement cycles.
- Minimalist:Stripped-down aesthetics align with denser floor plans justified by occupancy-sensing desk systems and AI-driven space analytics in London and Frankfurt pilots.
Ergonomic systems lead specification value today; minimalist designs are gaining share fastest in satellite office deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in flexible workspace furniture procurement volumes, while the Netherlands commands premium positioning for circular economy leasing models that other markets are beginning to replicate.
Germany
Flexible workspace operators in Berlin and Frankfurt are scaling modular system procurement for rapid tenant turnover. The Federal Environment Agency enforces mandatory durability thresholds through national transpositions of the EU Ecodesign Directive. Bavaria's manufacturing corridor anchors production for large corporate rollouts serving Austrian and Swiss headquarters markets.
France
AGEC law extended producer responsibility schemes are forcing brands to finance end-of-life collection networks. Repairability indices and spare parts availability mandates concentrate compliance burden on seating manufacturers with mechanical wear parts. The Paris-Saclay cluster hosts pilot programs for furniture-as-a-service contracts bundled into commercial lease agreements.
Netherlands
Amsterdam landlords are pioneering subscription-based furnishing contracts that displace traditional capital expenditure procurement. EU Green Deal public sector tender requirements create protected demand pools for certified recycled content offerings. The Randstad conurbation dominates architect-driven specification for design-led ergonomic systems in commercial development projects.
United Kingdom
Corporate real estate teams in London are piloting sensor-embedded desk systems at scale to optimize space utilization metrics. REACH compliance on surface treatments and flame retardants adds testing burden that favors mid-to-large manufacturers with in-house chemical assessment capacity. The Southeast corridor concentrates demand for rapid configuration tools that let facility managers re-plan offices without external consultants.
Belgium
Circular economy pilots for furniture leasing command premium positioning in the Benelux cluster relative to neighboring markets. ECHA enforcement of chemical regulations filters market access for non-compliant imports from outside the European Economic Area. Brussels serves as a regulatory intelligence hub where manufacturers monitor forthcoming Digital Product Passport requirements.
Europe Office Furniture Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with design-driven specification channels favoring established European names while high-turnover flexible workspace procurement opens entry points for agile configurators. The market structure shows moderate concentration at the premium tier alongside fragmentation in standardized seating and storage categories. Three archetypes dominate: heritage design houses with architect relationships, scale manufacturers with rapid fulfillment networks, and circular-economy-native leasing operators. Competitive moves center on geographic footprint expansion into Eastern European production bases and strategic portfolio diversification toward sensor-enabled product lines.
Within the heritage European tier, Vitra and Steelcase occupy positions anchored by manufacturing presence and specification relationships with commercial developers. Kinnarps represents the configuration-velocity archetype, competing through tools that reduce facility manager dependency on external planning consultants. These three names illustrate how competitive advantage is separating across design authority, production scale, and software-enabled service wrap.
| Leading Market Players |
|---|
| Nowy Styl |
| Vitra |
| Steelcase |
| Flokk |
| Bene |
| Herman Miller |
| Kinnarps |
| Sedus Stoll |
| Haworth |
| Others |
Supply Flow & Price Mechanics
Chemical assessment specialists concentrated in Germany's Bavarian manufacturing corridor drive labor-cost differentials that widen spreads between REACH-compliant premium tiers and flat-pack economy imports. Poland and Romania assembly operations compress mid-market pricing through nearshored production while AGEC law compliance costs in France sustain domestic premium positioning.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for standardized seating and storage categories. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified ergonomic systems from rapid-configuration coworking procurement. Price differentiation hinges on REACH certification tier and after-sales service bundling. Cost compression in particleboard-dependent desk categories is intensifying because of European timber harvest quota volatility. Small businesses exhibit highest price sensitivity; corporate headquarters with facility management software integration demands show lowest.
Supply Chain Analysis
Direct-to-landlord channels handle flexible workspace operator demand in Amsterdam and Berlin. Manufacturing concentrates in Germany, Poland, and Romania with steel tube framing and laminated particleboard surfaces as core inputs. Supply chain risk centers on single-source vulnerability for REACH-compliant flame retardant chemistries. Distribution runs through architect-specification networks for premium projects and property developer procurement platforms for subscription-based contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe office furniture functions as a stable compounder where regulatory compliance infrastructure creates durable moats protecting incumbent returns against import competition.
For Market Incumbents: Anticipate margin compression from Eastern European configurators by deepening in-house chemical assessment capabilities and securing decade-long component inventories for France's AGEC law repairability mandates. Prioritize backward integration into certified recycled material streams to defend positioning under EU Green Deal public procurement thresholds. For New Entrants and Emerging Players: Launch via furniture-as-a-service leasing models bundled into commercial lease agreements, targeting satellite office deployments in Amsterdam and Berlin where property developers concentrate purchasing authority. White-space exists in rapid-configuration software tools that reduce facility manager dependency on external planning consultants. For Investors and Strategic Acquirers: Property developers with captive workspace portfolios are the most active acquirer in this space, seeking vertical integration into furnishing procurement. Acquisition targets should display established reverse logistics networks for extended producer responsibility compliance. Monitor Digital Product Passport regulatory finalization as inflection indicator for data-transparent supply chain valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Infrastructure Investment | In-house chemical assessment capacity filters market access against flat-pack imports under ECHA enforcement. |
| Furniture-as-a-Service Platform Launch | Subscription contracts displace capital expenditure procurement in Amsterdam and Berlin flexible workspace rollouts. |
| Eastern European Manufacturing Footprint | Nearshoring to Poland and Romania reduces logistics costs for German and Austrian corporate headquarters markets. |
| Certified Recycled Material Sourcing | EU Green Deal public tender requirements create protected demand pools for domestic manufacturers. |
| Sensor-Enabled Product Integration | Occupancy-sensing desk systems compress replacement cycles through AI-driven space analytics adoption. |
Methodological Framework
Multiple input streams — facility management executives, procurement leads at flexible workspace operators, architect specification directors, and regulatory affairs managers at manufacturers — were reconciled against trade customs data, ECHA registration databases, EU tender documentation, and corporate sustainability disclosures. Bottom-up volume estimates triangulated with top-down market sizing across product type, material, end user, and design style dimensions.
Data-stream reconciliation anchored projections across the analysis window through segmentation modeling of workstations, seating, storage, and partitioning systems by certification tier, procurement channel, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating flexible workspace expansion rates, circular economy pilot adoption, and Digital Product Passport implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged particleboard cost volatility or accelerated REACH restriction amendments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Japan Office Furniture Market
Office Furniture
Office Furniture Edgebands Market
Office Furniture
Russia Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Institutional Furniture Market
Office Furniture
Office Seat Cushion Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
Desk Chairs Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Home Office Spending Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
US Office Furniture Market