
 Brazil Furniture Market | 2026-2036
Brazil Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Furniture Market Analysis
Apartment developer procurement is restructuring furniture sourcing across Brazil's major metropolitan corridors. SCA leverages its integrated pulp-to-furniture supply chain to control raw material costs in a volatile commodity environment. Herval anchors production capacity in Rio Grande do Sul's dense forestry belt, sustaining export competitiveness through proximity to pine and eucalyptus plantations. Todeschini differentiates via built-to-order kitchen and closet systems that compete with imports on customization speed.
Furniture encompasses movable objects engineered for human support, storage, and spatial organization, typically fabricated through CNC machining, veneer pressing, upholstery stapling, and powder-coat finishing to achieve dimensional stability and surface durability for residential, commercial, and institutional environments. Wood material categories dominate volume production due to Brazil's extensive reforestation asset base and established sawmill infrastructure, while metal frames represent the fastest-growing structural segment as urban consumers prioritize durability in compact living spaces. Modern and contemporary style segments capture expanding margin pools as younger buyers in São Paulo and Curitiba replace ornate traditional designs with minimalist, multifunctional pieces suited to smaller apartments.
ANVISA governs chemical emissions and surface treatment safety for furniture sold in Brazil, while INMETRO administers mandatory conformity assessment programs that restrict market access for non-compliant imports. The Brazilian Forestry Service and state-level environmental agencies enforce chain-of-custody documentation that shapes raw material sourcing decisions for exporters targeting European buyers. Stakeholders must monitor pending updates to ANVISA's formaldehyde emission thresholds and INMETRO's expanded certification scope for upholstered products to anticipate compliance cost shifts and competitive repositioning among domestic manufacturers.
Market Dynamics
ANVISA's tightening formaldehyde emission thresholds are forcing manufacturers to reformulate adhesives and surface treatments across Brazil's furniture production belt, compressing margins for non-compliant importers while rewarding domestic producers with certified supply chains.
Growth Catalysts
- Reforestation asset base:Brazil's extensive pine and eucalyptus plantations provide captive raw material access that insulates domestic manufacturers from global timber price volatility.
- INMETRO conformity assessment:Mandatory certification programs for upholstered products restrict low-cost import competition and protect market share for compliant domestic producers.
- Modular procurement restructuring:São Paulo apartment developers are consolidating vendor relationships around systems suppliers capable of delivering integrated kitchen, closet, and storage solutions.
Market Restraints
- Input cost volatility:Steel and aluminum frame components expose metal furniture producers to commodity price swings that compress gross margins during inflationary cycles.
- Supply concentration risk:Bento Gonçalves and Arapongas clusters dominate finished goods output, creating geographic vulnerability to regional logistics disruptions or labor actions.
- Regulatory friction:INMETRO's expanded certification scope for upholstered products extends time-to-market for new entrants and raises compliance capital requirements.
Strategic Opportunities
- Curitiba demand corridor:Younger buyers in Paraná's capital are replacing ornate traditional designs with minimalist multifunctional pieces, opening share capture for contemporary-focused manufacturers.
- Export chain-of-custody:Brazilian Forestry Service documentation requirements align with European buyer procurement standards, enabling premium positioning for certified producers.
- CNC-robotics convergence:Automated cutting and edge-banding systems reduce customization lead times for built-to-order kitchen and closet systems competing with imports.
Industry Challenges
- Skilled CNC programming gap:Furniture manufacturers in Rio Grande do Sul face recruitment difficulty for technicians capable of operating five-axis machining centers and automated nesting software.
- Compliance timeline compression:ANVISA's pending formaldehyde threshold updates require reformulation cycles that strain R&D bandwidth at mid-cap producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Furniture Market |
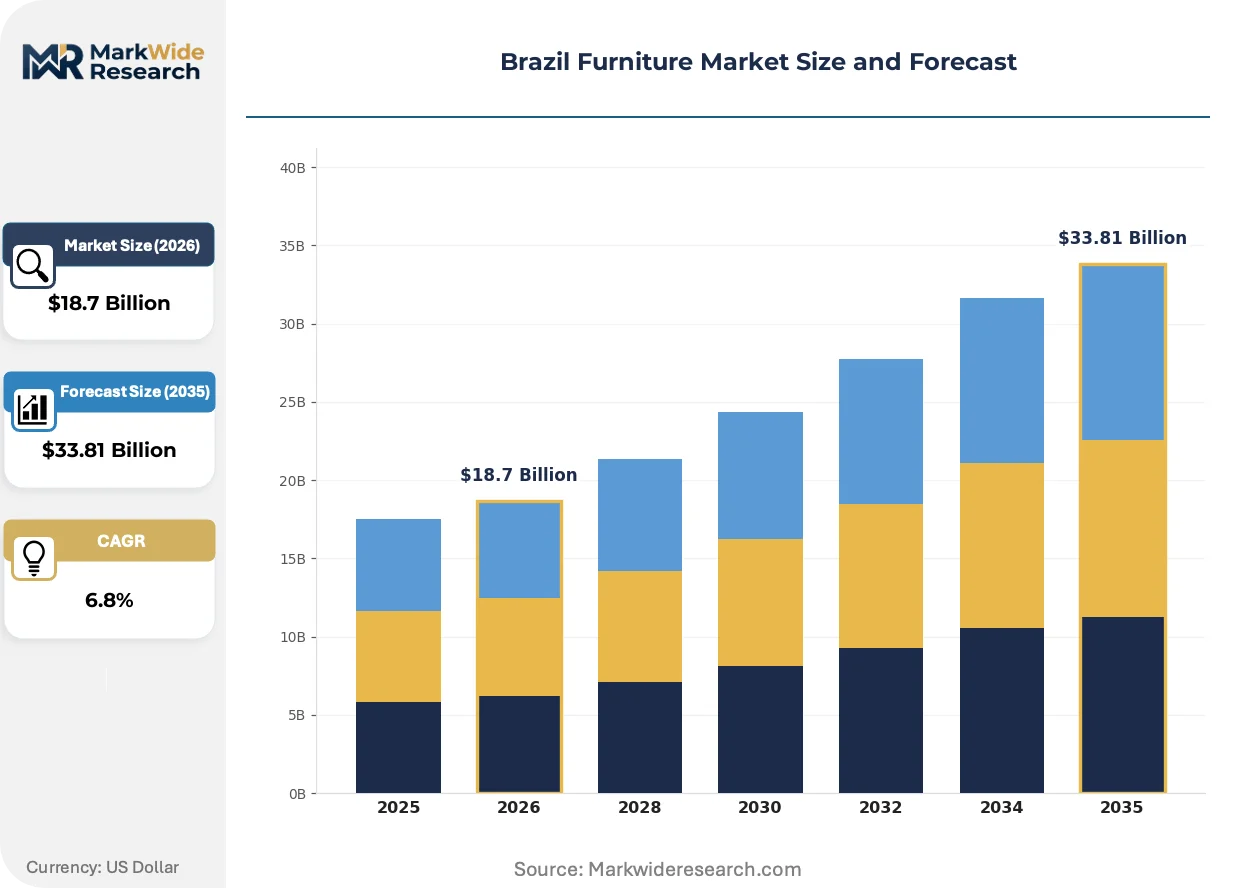
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Tables, Chairs Material: Wood, Metal, Glass, Plastic Style: Modern, Traditional, Rustic, Contemporary Distribution Channel: Online, Retail Stores, Showrooms, Wholesalers |
| Companies Covered | SCA, Simonetti Furniture, Herval, Henn, Italínea, Carraro Furniture, Todeschini, Itatiaia, TOTH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Furniture Market Emerging Trajectories
Digital fabrication and regulatory compliance are converging to reshape competitive advantage across Brazil's furniture production clusters, with automation and certification emerging as the primary axes of differentiation.
CNC nesting software paired with robotic edge-banders is automating batch-size-one production for customized closet and kitchen systems. São Paulo apartment developers are specifying these capabilities in vendor qualification criteria. The technology is compressing delivery timelines from six weeks to ten days for built-to-order configurations.
ANVISA's updated chemical emissions standards for indoor products are mandating low-formaldehyde adhesive formulations across upholstered and panel furniture categories. Domestic manufacturers with in-house resin blending capabilities are absorbing compliance costs more efficiently than import-dependent distributors. The regulatory pressure falls most heavily on Asian-origin upholstered goods entering through São Paulo's port complex.
Younger buyers in São Paulo and Curitiba are consolidating purchasing decisions around direct-to-developer furniture packages rather than post-occupancy retail selection. This channel shift is disintermediating traditional furniture retailers and concentrating volume with systems suppliers capable of BIM integration and construction-timeline coordination. The pattern is most visible in mid-rise residential towers where developer-specified finishes dominate unit configurations.
Brazil Furniture Market Segmentation
Furniture manufacturers in Brazil navigate divergent demand signals across living contexts, from developer-specified apartment packages to individual post-occupancy purchases. Segment boundaries determine which capabilities—modular engineering, CNC customization, or mass retail distribution—deliver competitive advantage in each revenue pool.
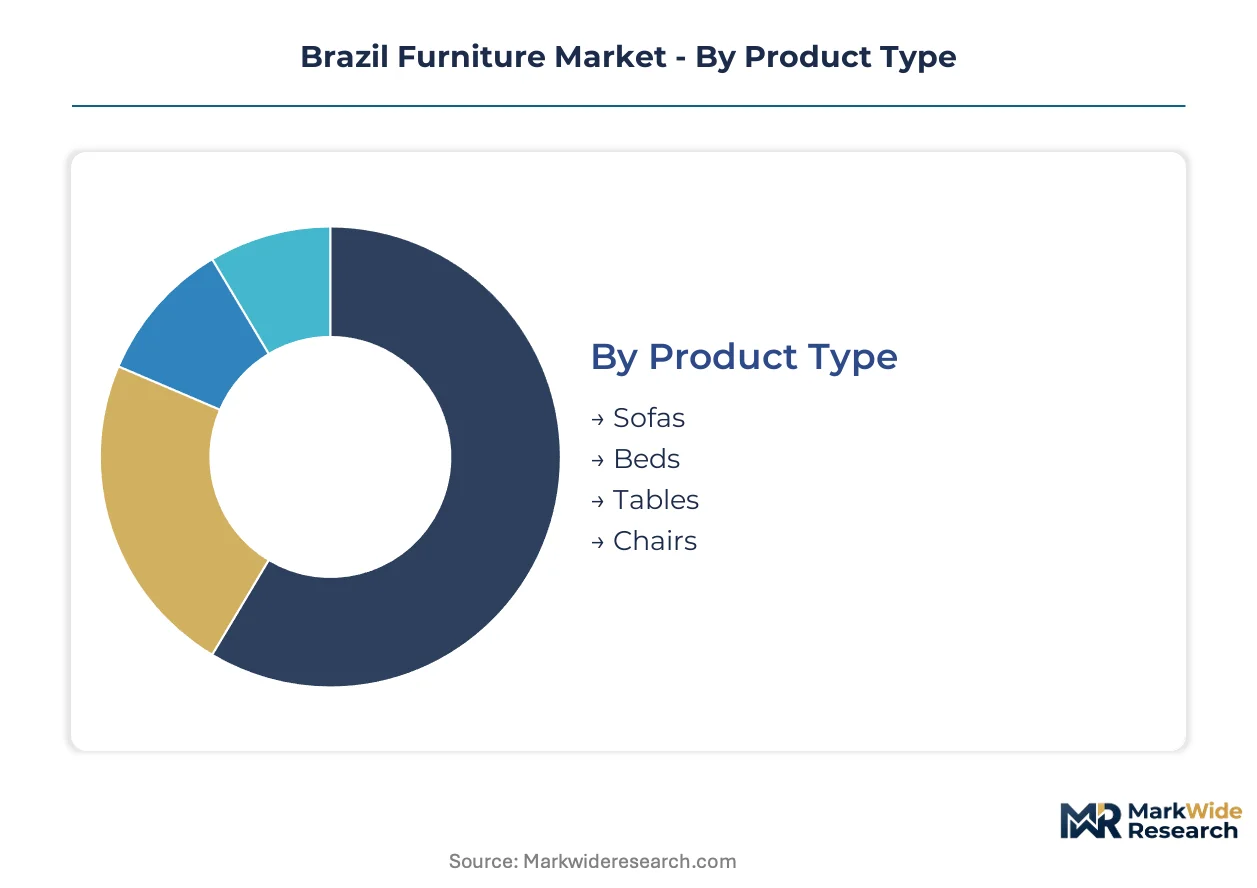
Product Type:
Sofas command the widest customization range from built-to-order upholstery to standard retail SKUs, while beds and tables sit at opposing ends of the standardization spectrum across São Paulo and Curitiba demand corridors.
- Sofas:Upholstered frames with variable density foam and fabric specifications dominate living room procurement. São Paulo apartment developers now specify modular sectional systems with integrated storage, compressing vendor qualification to suppliers with robotic cutting cells and ten-day delivery capability.
- Beds:Platform and storage-integrated designs fabricated from MDF cores with laminate surfacing represent the volume anchor. Demand concentrates in mid-rise residential towers where developer-specified packages disintermediate post-occupancy retail selection.
- Tables:Dining and occasional tables span CNC-machined solid wood to powder-coated metal frames for compact urban apartments.
- Chairs:Seating categories range from upholstered dining chairs to ergonomic office designs targeting home workspace conversion.
Leading the category by volume: Beds. Expanding most quickly: Sofas with integrated modular configurations.
Material:
Cost tiers separate captive-supply wood producers from import-dependent metal and glass fabricators exposed to commodity volatility.
- Wood:Pine and eucalyptus from Rio Grande do Sul plantations supply panel and solid-wood fabrication. Bento Gonçalves manufacturers leverage this captive raw material access to undercut import-dependent competitors on both cost and ANVISA compliance timelines.
- Metal:Steel and aluminum frames for outdoor and compact urban furniture expose producers to global commodity swings. Curitiba buyers prioritize metal durability in smaller apartments, driving fastest share gain despite margin compression during inflationary cycles.
- Glass:Tempered and laminated glass for tabletops and display units requires specialized tempering capacity concentrated in São Paulo state.
- Plastic:Polypropylene and polycarbonate molding serves outdoor and children's furniture segments with lower compliance thresholds.
Highest margin stability: Wood with certified plantation sourcing. Steepest expansion trajectory: Metal frames for urban durability requirements.
Style:
Customer age and geography determine style preference intensity, with younger buyers in southern cities driving contemporary share capture.
- Modern:Clean lines and minimal ornamentation characterize this segment. Curitiba's younger buyer cohort replaces inherited traditional pieces with multifunctional designs suited to 45-60 square meter apartments, opening share for manufacturers with CNC-robotics convergence capabilities.
- Contemporary:Evolving aesthetics blending global trends with Brazilian material expression. Todeschini and similar built-to-order specialists compete with Italian imports on customization speed through automated nesting software.
- Traditional:Ornate carved wood and rich upholstery persist in older demographic segments and interior São Paulo state markets.
- Rustic:Reclaimed wood and distressed finishes target vacation properties and boutique hospitality in Minas Gerais mountain regions.
Deepest volume penetration: Traditional in interior markets. Gaining share fastest: Modern in Curitiba and São Paulo metropolitan corridors.
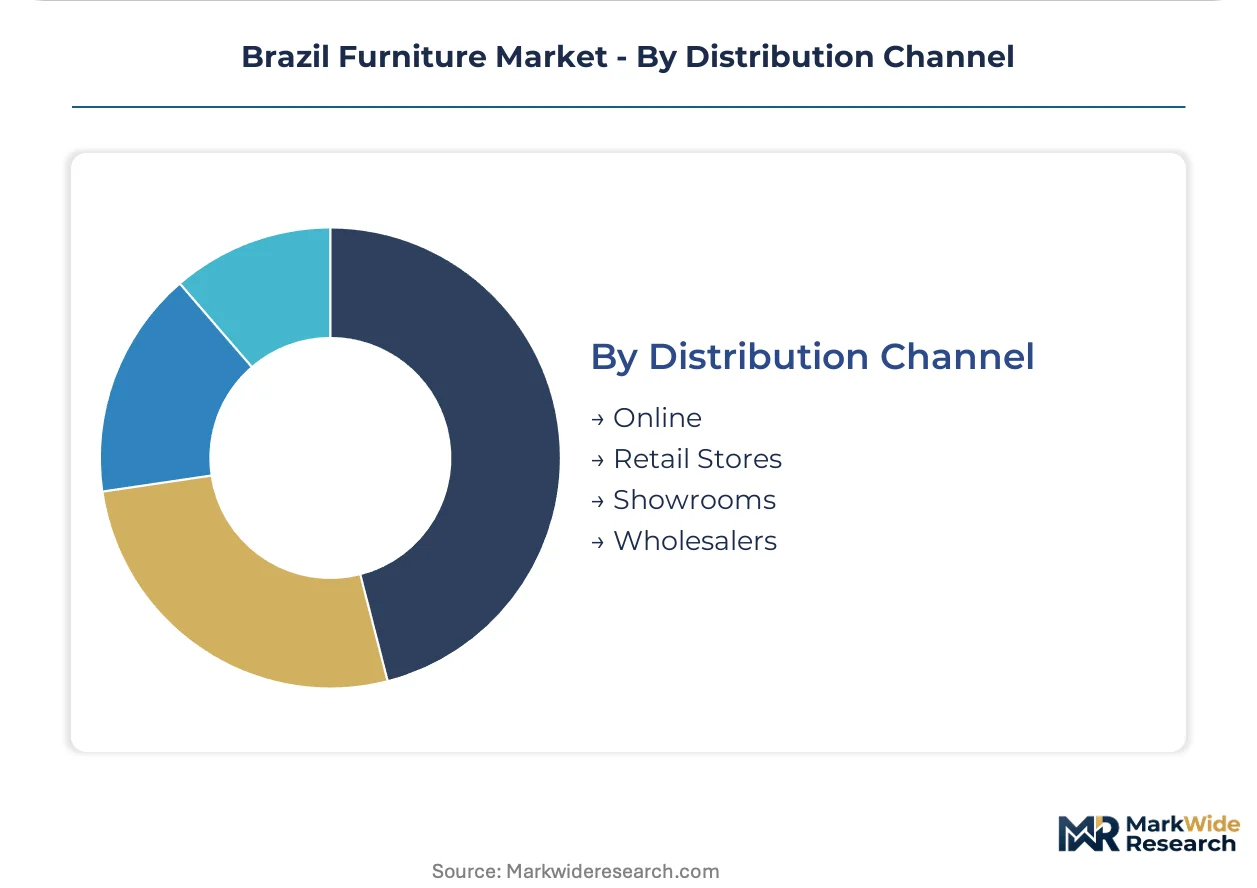
Distribution Channel:
Channel selection separates developer-direct volume from fragmented retail, with digital integration now mandatory for vendor qualification.
- Retail Stores:Multi-brand furniture retailers in São Paulo and Curitiba shopping centers carry inventory for immediate delivery. This channel faces disintermediation as apartment buyers consolidate purchasing around developer-direct packages.
- Online:E-commerce platforms with augmented reality visualization and BIM integration capture growing share among younger buyers. The channel rewards suppliers with configurable product logic and construction-timeline coordination capabilities.
- Showrooms:Manufacturer-direct display spaces in Bento Gonçalves and Arapongas clusters serve trade buyers and export procurement.
- Wholesalers:Regional distributors stock standardized SKUs for smaller retailers in secondary cities across Brazil's interior.
Highest transaction volume: Retail Stores. Climbing the fastest: Online with BIM-integrated developer procurement tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
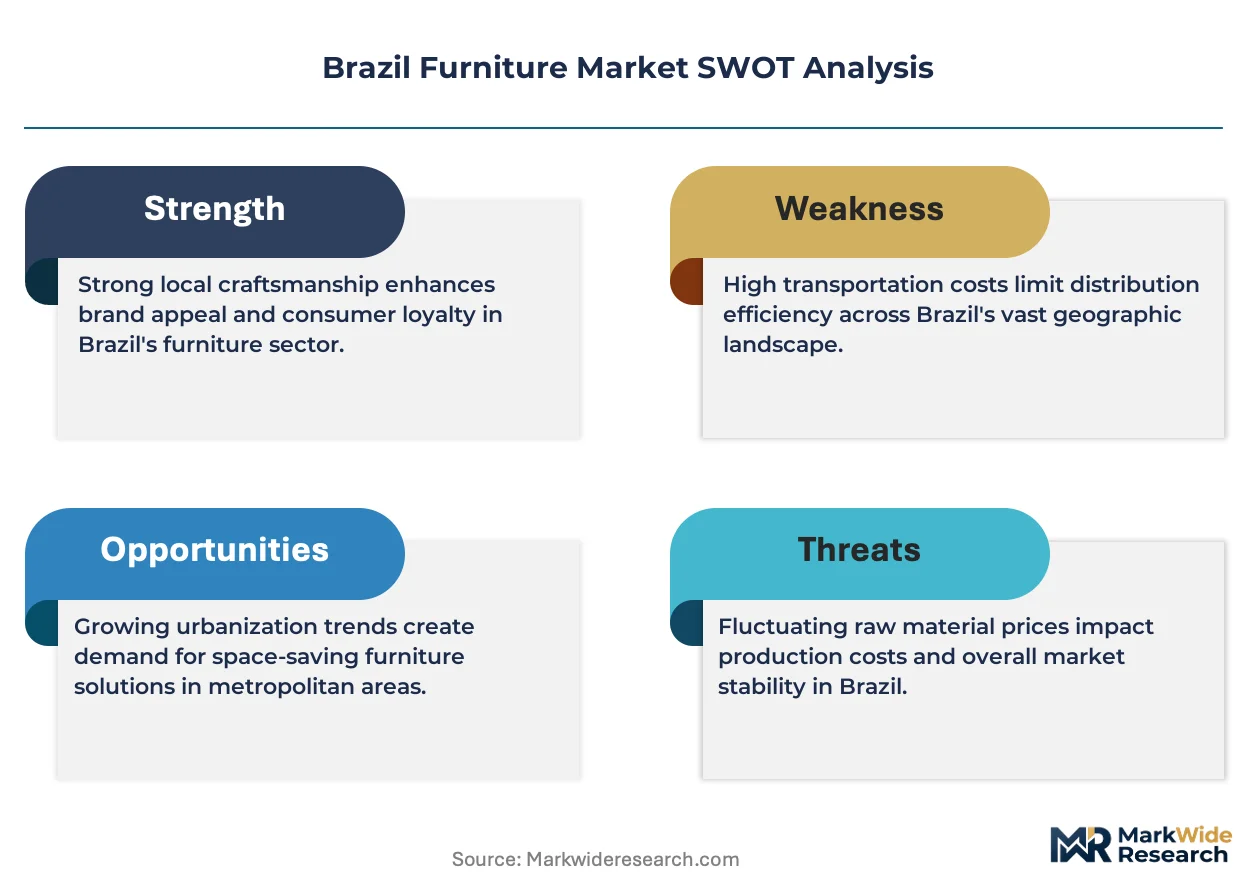
Rio Grande do Sul's pine and eucalyptus plantations anchor Brazil's furniture raw material base, feeding manufacturing clusters across five states with distinct demand profiles and regulatory exposures.
São Paulo
Apartment developers in São Paulo's metropolitan corridor are consolidating procurement around modular systems suppliers with BIM integration capabilities. ANVISA's chemical emissions standards enforce compliance timelines that disadvantage import-dependent distributors. The Bento Gonçalves manufacturing cluster dominates high-volume panel furniture production for developer-direct channels.
Rio Grande do Sul
Captive plantation access insulates producers from global timber volatility while sustaining export competitiveness. The Brazilian Forestry Service chain-of-custody documentation aligns with European procurement standards for certified producers. Herval anchors production capacity in this dense forestry belt, leveraging proximity to pine and eucalyptus feedstock.
Paraná
Curitiba's younger buyer cohort drives demand for minimalist multifunctional designs suited to compact urban apartments. INMETRO conformity assessment programs for upholstered products restrict low-cost import competition. Arapongas clusters finished goods output, creating geographic concentration in the state's northern manufacturing corridor.
Minas Gerais
Mountain region vacation properties and boutique hospitality sustain demand for rustic reclaimed wood finishes. State environmental agencies enforce documentation requirements that shape sourcing decisions for export-oriented fabricators. Belo Horizonte's metropolitan area anchors distribution connectivity to southeast consumer markets.
Brazil Furniture Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue CNC-robotics convergence and built-to-order customization. The vendor base spans integrated pulp-to-furniture supply chains, regional plantation-anchored fabricators, and specialized kitchen systems suppliers. Three archetypes dominate: captive raw material players, automation-enabled custom specialists, and import-dependent distributors facing regulatory compression. Competitive positioning hardens around M&A consolidation in Rio Grande do Sul and capacity expansion in Paraná's Arapongas corridor.
Among integrated supply chain operators, SCA exemplifies the pulp-to-furniture archetype with captive raw material control. Herval occupies a plantation-proximate position in Rio Grande do Sul's forestry belt. Todeschini represents the built-to-order specialist tier competing on customization speed through automated nesting capabilities.
| Leading Market Players |
|---|
| SCA |
| Simonetti Furniture |
| Herval |
| Henn |
| Italínea |
| Carraro Furniture |
| Todeschini |
| Itatiaia |
| TOTH |
| Others |
Supply Flow & Price Mechanics
Pine and eucalyptus feedstock costs cascade from Rio Grande do Sul plantations through three distinct pricing tiers, with ANVISA-compliant domestic producers commanding premium positioning against import-dependent distributors absorbing reformulation penalties.
Pricing Analysis
Warranty bundling separates certified domestic producers from unbundled import competitors, with ten-year structural guarantees now standard for plantation-sourced wood products. Pricing stratifies across premium certified tiers, mid-market compliant domestic production, and economy import channels exposed to INMETRO rejection risk. Cost compression in the economy tier is intensifying as Asian-origin upholstered goods face extended port inspection timelines. Developer-direct procurement shows lowest price sensitivity, while post-occupancy retail buyers in secondary cities exhibit highest elasticity.
Supply Chain Analysis
CNC programming talent scarcity in Bento Gonçalves and Arapongas clusters constrains automation deployment timelines for built-to-order specialists. Manufacturing concentrates in Brazil's southern states, with component sourcing drawing from São Paulo state glass tempering facilities and Minas Gerais hardware suppliers. Single-source vulnerability runs through the Arapongas finished goods corridor, where labor actions or logistics disruptions would ripple across Paraná's export pipeline. Distribution runs through developer-direct specification channels for volume, with retail and e-commerce capturing fragmented post-occupancy demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's formaldehyde threshold tightening constructs a compliance moat that rewards certified domestic producers while systematically disadvantaging import-dependent distributors lacking in-house resin blending capabilities.
For Market Incumbents: To counter CNC-robotics convergence by automation-enabled specialists, incumbents should acquire five-axis programming talent in Rio Grande do Sul's technical institutes and deepen backward integration into adhesive formulation to absorb ANVISA compliance costs internally. For New Entrants and Emerging Players: Curitiba's younger buyer cohort seeking minimalist multifunctional designs for compact apartments represents the most penetrable white-space target, with BIM-integrated developer procurement offering a direct go-to-market angle bypassing traditional retail disintermediation. For Investors and Strategic Acquirers: Distressed-cycle entries favor plantation-anchored fabricators in Rio Grande do Sul with captive raw material access and existing ANVISA certification infrastructure. Long-term viability across the projection horizon rests on regulatory compliance durability rather than cyclical margin recovery. The signal to monitor is INMETRO's expanded certification scope timeline for upholstered products.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | In-house resin blending absorbs ANVISA compliance costs faster than import-dependent competitors. |
| CNC-Robotics Convergence Investment | Automated nesting software compresses built-to-order delivery timelines from six weeks to ten days. |
| Chain-of-Custody Certification Program | Brazilian Forestry Service documentation aligns with European buyer procurement standards for premium positioning. |
| Developer-Direct Channel Expansion | BIM integration capabilities qualify vendors for São Paulo apartment procurement consolidation. |
| Skilled Technician Training Partnership | Rio Grande do Sul technical institute pipelines address five-axis machining center operator scarcity. |
Methodological Framework
Document review covered Brazilian Forestry Service chain-of-custody records, INMETRO conformity assessment databases, and ANVISA chemical emissions filings, complemented by interviews with plant managers at Bento Gonçalves panel furniture facilities, procurement leads at São Paulo apartment developers, and distribution channel partners in Curitiba's retail corridor. Secondary validation drew from customs trade data, state-level environmental agency documentation, and industry association production surveys. Bottom-up vendor capacity estimates were triangulated against top-down demand segmentation across the analysis window.
Market sizing outputs reflect consumption-based modeling across product type, material category, style segment, and distribution channel dimensions, with additional industry-specific stratification by developer-direct versus post-occupancy procurement patterns. CAGRs were derived from regression analysis of historical production volumes against macroeconomic drivers including residential construction permits and reforestation plantation expansion rates. Forecast inputs incorporated ANVISA regulatory timeline assumptions and INMETRO certification scope expansion parameters.
Revisions become necessary when ANVISA formaldehyde threshold implementation timelines accelerate, INMETRO expands upholstered product certification requirements ahead of schedule, or Rio Grande do Sul plantation harvest cycles deviate from projected feedstock availability. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
United States Luxury Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
Metal Furniture Market
Furniture
United States Upholstered Furniture Market
Furniture
North America School Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
Global Organic Furniture Market
Furniture
UK Sustainable Home Furniture Market
Furniture
United States Home Furniture Market
Furniture
United Arab Emirates Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
Eco-Friendly Furniture Market
Furniture
North America RTA Furniture Market
Furniture
Europe Sustainable Mattress Market
Furniture
US Multifunctional Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market