
 Germany Food Additives Market | 2026-2036
Germany Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Food Additives Market Foresight
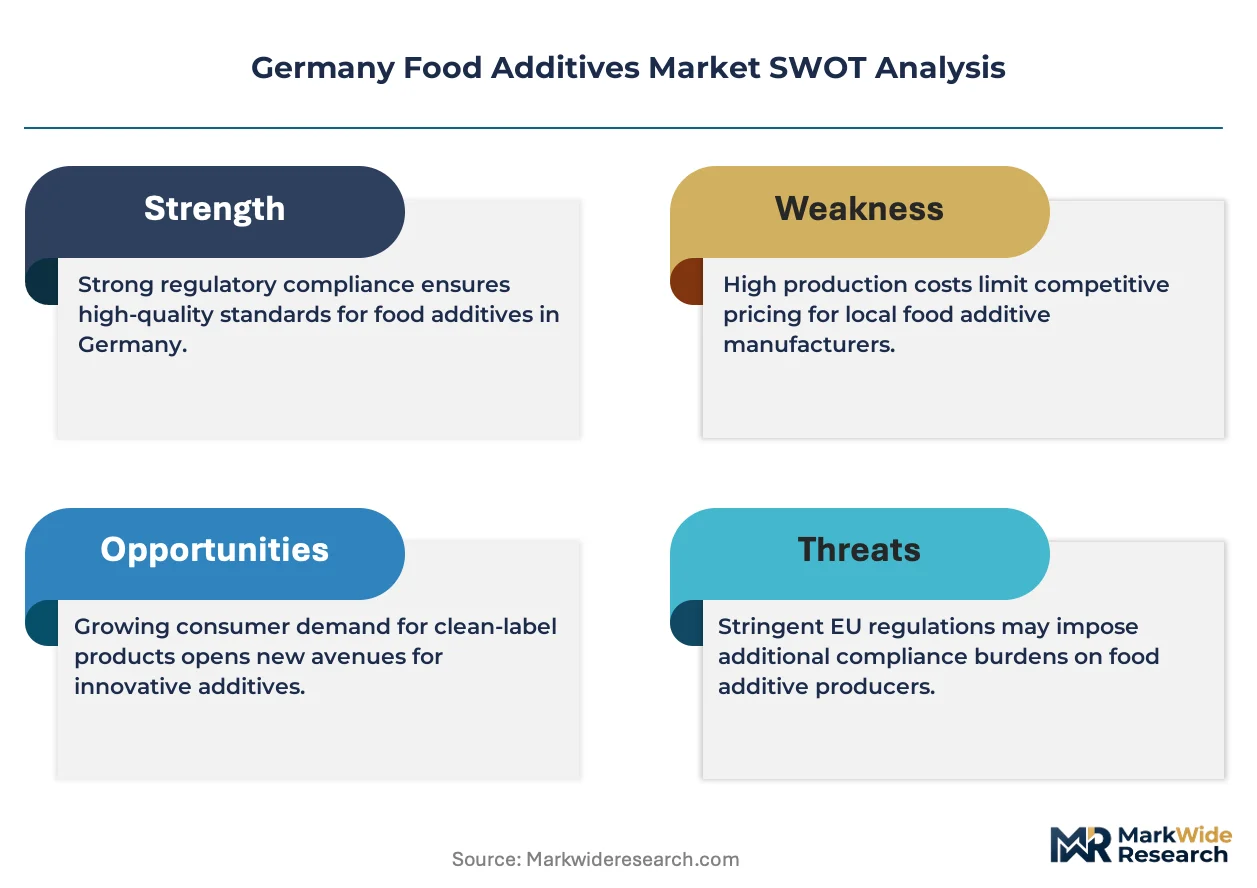
The EU Green Deal is repositioning German food additive procurement toward sustainably sourced and minimally processed inputs. Kerry Group plc leverages its enzyme and preservation expertise to anchor clean-label solutions for Central European bakery chains. BASF SE sustains dominant positions in synthetic vitamin and carotenoid production through backward integration into fermentation feedstocks. Chr. Hansen Holding A/S specializes in microbial cultures and natural colorants, competing on biosynthetic efficiency rather than petrochemical derivatives.
Food additives comprise functional substances—preservatives, emulsifiers, sweeteners, colorants, and flavor enhancers—incorporated at concentrations typically below one percent by weight to extend shelf stability, modify texture, or intensify sensory profiles. Powder and liquid forms dominate industrial handling due to metering precision in automated dosing systems. Preservatives occupy mature margin pools in baked goods and dairy, while sweeteners and flavor enhancers lead growth trajectories within meat alternatives and reduced-sugar beverages where reformulation intensity is highest. Emulsifiers command structural importance in plant-based analogs replicating animal-fat mouthfeel.
BfR risk assessments and EU REACH chemical registrations constrain novel additive introductions, forcing suppliers to navigate extensive toxicological dossiers before market authorization. The German Food and Feed Code enforces maximum usage levels and labeling transparency that directly shape formulation decisions by packaged food manufacturers. Stakeholders must monitor evolving EFSA opinions on enzymatic processing aids and novel protein hydrolysates to anticipate compliance burdens and first-mover advantages.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is forcing German food additive suppliers to requalify entire ingredient portfolios around sustainability metrics and clean-label positioning. This regulatory compression is accelerating R&D investment in biosynthetic alternatives while marginalizing petrochemical-derived inputs.
Growth Catalysts
- Plant-based meat analog demand:German food processors are intensifying additive procurement for texture replication and fat-mimicry in alternative proteins. Emulsifier and hydrocolloid volumes are tracking this reformulation wave.
- EU Green Deal alignment:The Farm to Fork strategy mandates pesticide reduction and sustainable sourcing, creating pull for natural preservatives and fermentation-derived colorants that satisfy EFSA clean-label criteria.
- Bavaria-North Rhine-Westphalia cluster density:Concentrated formulation R&D and production infrastructure in these Länder reduces supplier qualification cycles and accelerates pilot-to-scale transitions for novel additives.
Market Restraints
- EFSA authorization timelines:Novel additive dossiers face 18-36 month toxicological review cycles that delay commercialization and tie up capital in pre-revenue development phases.
- Fermentation feedstock volatility:Sugar and grain-derived substrates for biosynthetic production exhibit price swings that compress margins on natural colorants and microbial cultures versus synthetic alternatives.
- Clean-label cost premiums:Minimally processed ingredients command 15-40% unit cost premiums over conventional additives, constraining adoption in private-label and economy-tier packaged foods.
Strategic Opportunities
- Enzymatic processing aids:EFSA's evolving opinions on novel protein hydrolysates create first-mover windows for suppliers with validated enzymatic portfolios in dairy and bakery applications.
- Baden-Württemberg precision fermentation:Underutilized biotech infrastructure in this Land offers expansion capacity for specialty microbial cultures serving Central European markets.
- Reduced-sugar beverage reformulation:Stevia and monk fruit extract demand is outpacing supply in German bottling operations, opening white space for high-intensity sweetener innovators.
Industry Challenges
- Regulatory dossier expertise scarcity:Qualified toxicologists and EFSA submission specialists command premium compensation, constraining mid-tier suppliers' novel additive pipelines.
- Legacy equipment integration:Automated dosing systems in mature dairy and bakery plants require retrofitting for precision handling of heat-sensitive natural extracts versus stable synthetic powders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Food Additives Market |
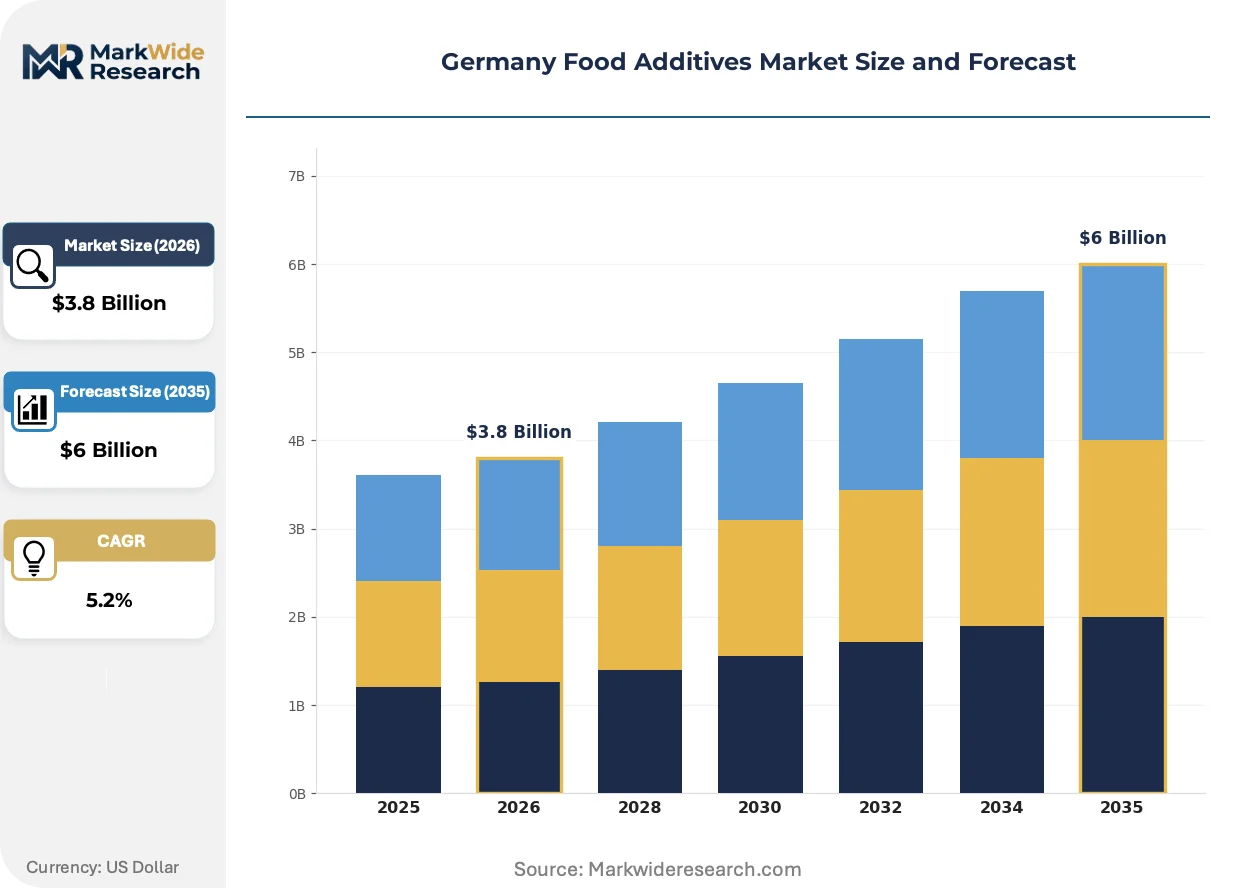
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Emulsifiers, Sweeteners, Colorants, Flavor Enhancers Application: Baked Goods, Beverages, Dairy Products, Confectionery, Meat Alternatives Form: Powder, Liquid, Granules, Crystals, Paste End User: Food Processing Companies, Packaged Food Manufacturers, Catering Services, Ingredient Suppliers |
| Companies Covered | DuPont de Nemours, Inc., Kerry Group plc, Archer Daniels Midland Company, Chr. Hansen Holding A/S, Koninklijke DSM N.V., BASF SE, Ingredion Incorporated, Tate & Lyle PLC, Cargill, Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Food Additives Market Shifts & Advancements
Precision fermentation and enzymatic bioprocessing are displacing chemical synthesis as the dominant production paradigm for high-value functional ingredients. German suppliers are repositioning around biosynthetic efficiency metrics rather than scale economies.
Cell-culture-derived proteins and lipids are modularizing the ingredient supply chain for plant-based meat alternatives. German alt-meat formulators are adopting these inputs to compress development cycles and achieve mouthfeel parity with animal products. This modularization is reducing reliance on multi-component additive blends and simplifying label declarations.
The EU Green Deal's chemical sustainability criteria are tightening REACH registration requirements for petrochemical-derived food contact substances. German manufacturers are preemptively substituting biosynthetic alternatives to avoid downstream reformulation mandates. Bakery chains and dairy processors are now requiring supplier certifications that document Farm to Fork alignment in additive sourcing.
Direct procurement relationships between additive suppliers and mid-sized German food processors are displacing traditional distributor intermediaries. Regional cooperatives and private-label manufacturers are consolidating volumes to negotiate formulation partnerships rather than commodity transactions. This disintermediation is most pronounced in Baden-Württemberg's organic food processing cluster, where traceability requirements favor transparent supplier relationships.
Germany Food Additives Market Segmentation
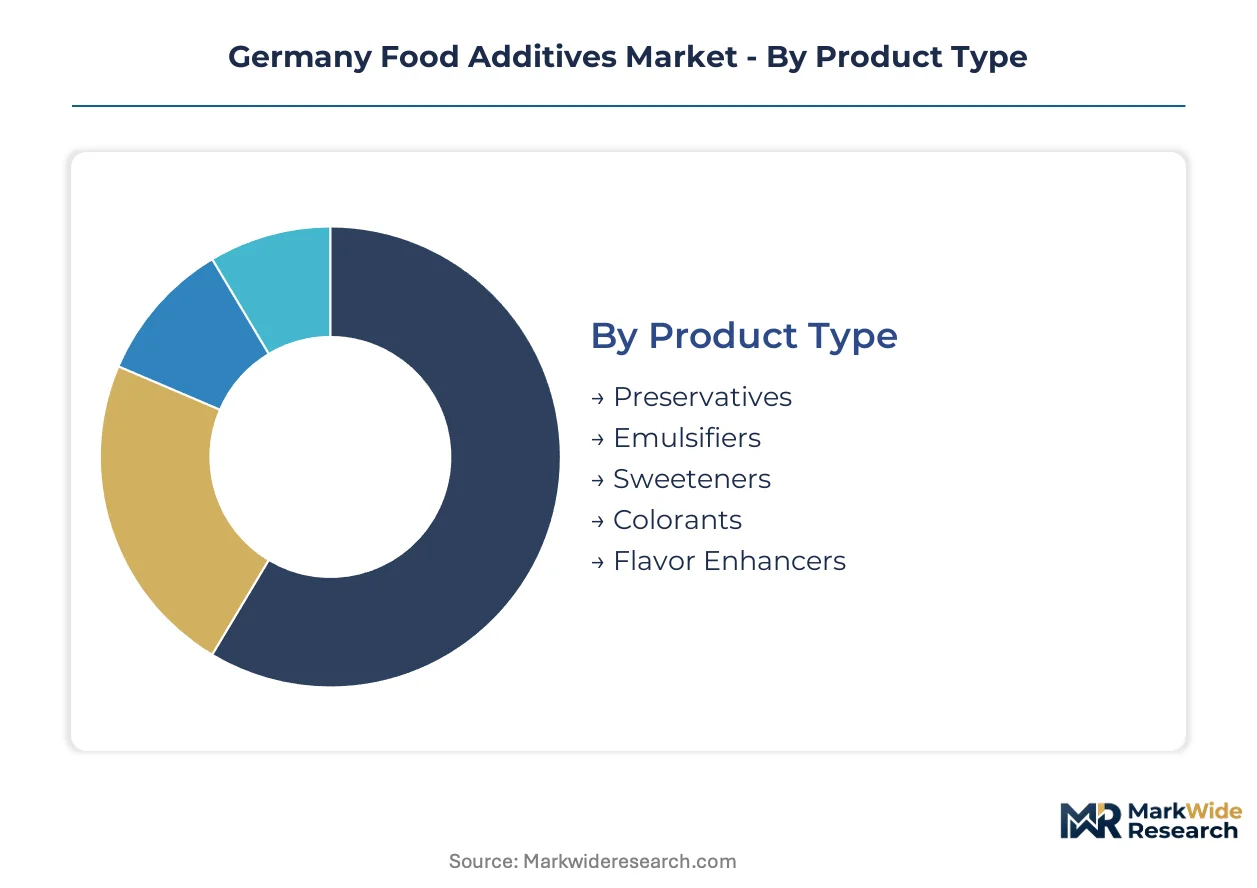
German food additive procurement patterns diverge sharply across product chemistry, application intensity, and handling requirements. Each segmentation axis reveals distinct margin pools and regulatory exposure profiles that shape supplier positioning strategies.
Product Type:
Buyers differentiate primarily by reformulation urgency and clean-label compatibility, with synthetic versus natural origin driving procurement committee composition and approval timelines.
- Preservatives:Benzoates, sorbates, and natural fermentation-derived solutions inhibit microbial spoilage in shelf-stable applications. Bavarian dairy processors and North Rhine-Westphalia bakery chains dominate procurement volumes, though EFSA clean-label opinions are accelerating natural alternative substitution timelines.
- Emulsifiers:Lecithins, mono- and diglycerides, and polysorbates stabilize oil-water interfaces in texture-critical formulations. Meat alternative manufacturers in Berlin and Hamburg are intensifying procurement for fat-mimicry applications where mouthfeel parity determines commercial success.
- Sweeteners:High-intensity and bulk variants reduce caloric density while maintaining sensory profiles.
- Colorants:Synthetic azo dyes and natural anthocyanin, carotenoid, and chlorophyll extracts provide visual differentiation.
- Flavor Enhancers:Glutamates, nucleotides, and yeast extracts intensify umami and savory perception.
Volume sits with Preservatives; growth tilts toward Emulsifiers.
Application:
Application selection correlates with processing temperature tolerance and label claim complexity, with thermal stability requirements filtering additive compatibility.
- Baked Goods:Emulsifiers and preservatives dominate procurement for crumb structure optimization and mold inhibition. Large industrial bakeries in Baden-Württemberg drive standardization around enzyme-based dough conditioners.
- Beverages:Acidulants, sweeteners, and colorants address pH stability and visual appeal in carbonated and still formats. Reduced-sugar reformulation in Bavarian bottling operations is expanding high-intensity sweetener volumes.
- Dairy Products:Stabilizers and cultures maintain texture through pasteurization and cold-chain distribution.
- Confectionery:Glazing agents and colorants support shelf appeal and manufacturing efficiency.
- Meat Alternatives:Hydrocolloids, emulsifiers, and flavor systems replicate animal-protein functionality. Berlin and Hamburg processors are consolidating additive specifications to compress supplier qualification cycles.
Revenue concentrates in Baked Goods; Meat Alternatives are expanding most quickly.
Form:
Physical state determines dosing equipment compatibility and dissolution kinetics, with automated handling systems favoring flowable formats over cohesive masses.
- Powder:Free-flowing particulates enable precise gravimetric dosing in high-throughput lines. North Rhine-Westphalia dairy powder processors specify this form for hygroscopic stability during pneumatic conveying.
- Liquid:Pumpable solutions integrate directly into continuous mixing operations without hydration delays. Beverage manufacturers in Bavaria prefer liquid colorants and acidulants for batch consistency.
- Granules:Intermediate particle size reduces dusting while maintaining rapid dissolution.
- Crystals:Defined geometry supports controlled release in specific pH environments.
- Paste:High-viscosity formats concentrate active ingredients for minimal inclusion rates.
Procurement weight rests with Powder; Liquid is gaining share fastest.
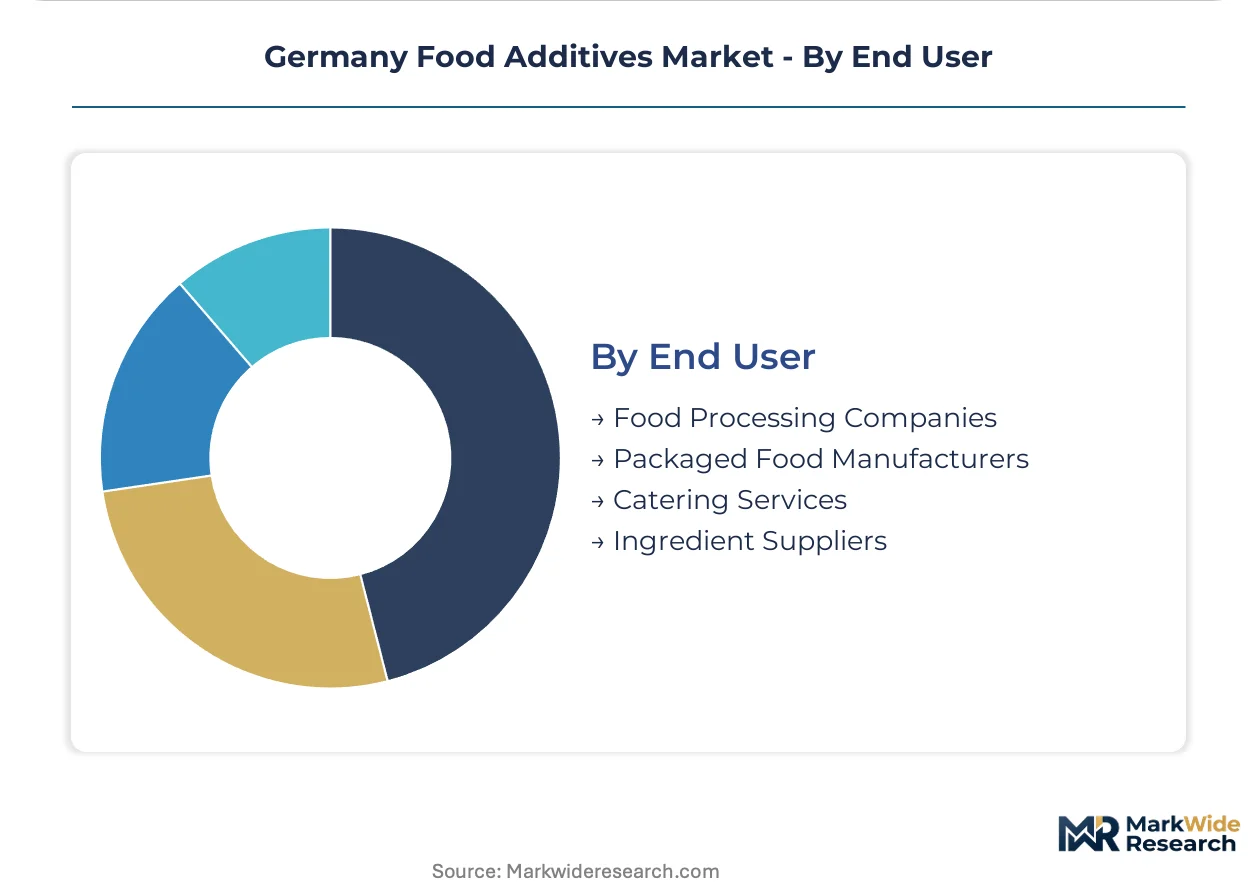
End User:
End-user category shapes technical service intensity and contract structure, with integrated processors demanding formulation partnership versus transactional supply.
- Food Processing Companies:Industrial-scale operators specify additives for yield optimization and process efficiency. Large meat processors in Lower Saxony are consolidating emulsifier procurement through direct supplier relationships.
- Packaged Food Manufacturers:Brand owners prioritize label-friendly ingredient declarations for retail differentiation. Private-label specialists in Baden-Württemberg's organic cluster require full Farm to Fork traceability documentation.
- Catering Services:Volume foodservice operators emphasize cost control and preparation consistency.
- Ingredient Suppliers:Blend houses and premix specialists aggregate single additives into functional systems for downstream formulation.
Spend aggregates with Food Processing Companies; growth tilts toward Packaged Food Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria and North Rhine-Westphalia anchor Germany's food additive demand through concentrated dairy, bakery, and beverage processing infrastructure. These industrial clusters generate procurement volumes that shape supplier qualification cycles and pilot-to-scale timelines for novel ingredients.
Bavaria
Dairy processors and reduced-sugar beverage bottlers in Bavaria intensify emulsifier and high-intensity sweetener procurement for reformulation projects. The German Food and Feed Code enforces maximum usage levels that directly constrain formulation flexibility in Munich's industrial dairy corridor. The Ingolstadt-Augsburg processing belt concentrates clean-label enzyme demand for baked goods and fermented dairy applications.
North Rhine-Westphalia
Industrial bakeries and confectionery manufacturers in North Rhine-Westphalia dominate preservative and dough conditioner volumes for shelf-stable applications. EFSA clean-label opinions accelerate natural fermentation-derived alternative substitution timelines in Cologne-Düsseldorf processing zones. The Lower Rhine chemical corridor sustains backward integration into fermentation feedstocks for biosynthetic colorant production.
Baden-Württemberg
Organic food processors and private-label specialists in Baden-Württemberg require full Farm to Fork traceability documentation for additive sourcing. The EU Green Deal's pesticide reduction mandates reshape procurement criteria in Stuttgart's organic processing cluster. Precision fermentation infrastructure in the Upper Rhine Valley offers underutilized expansion capacity for specialty microbial cultures.
Berlin-Brandenburg
Meat alternative manufacturers in Berlin and Hamburg intensify hydrocolloid and flavor system procurement for texture replication in plant-based analogs. BfR risk assessments constrain novel protein hydrolysate introductions in the capital region's alt-meat pilot facilities. The Berlin-Brandenburg food tech corridor consolidates additive specifications to compress supplier qualification cycles.
Lower Saxony
Large meat processors in Lower Saxony consolidate emulsifier procurement through direct supplier relationships rather than distributor intermediaries. EFSA authorization timelines delay commercialization of novel enzymatic processing aids in Bremen-Hanover industrial zones. The Oldenburg dairy cluster drives standardized dosing equipment for powder and liquid additive formats.
Germany Food Additives Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with captive fermentation capabilities and specialized bioscience firms competing on biosynthetic efficiency. Tiered positioning separates scale-driven ingredient suppliers from precision fermentation specialists and regional blend houses. Three archetypes dominate: backward-integrated chemical majors, microbial culture specialists, and application-focused formulation partners. Capacity expansion in precision fermentation infrastructure and strategic partnerships with mid-sized processors represent the dominant competitive moves.
Among diversified chemical conglomerates, BASF SE and Kerry Group plc occupy positions that exemplify contrasting strategic archetypes. BASF SE anchors synthetic vitamin and carotenoid production through in-house control over fermentation feedstocks. Kerry Group plc represents the application-focused tier, leveraging enzyme expertise to anchor clean-label solutions for Central European bakery chains. Chr. Hansen Holding A/S sits within the microbial culture specialist tier, competing on biosynthetic efficiency rather than petrochemical derivatives.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Kerry Group plc |
| Archer Daniels Midland Company |
| Chr. Hansen Holding A/S |
| Koninklijke DSM N.V. |
| BASF SE |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Cargill, Incorporated |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fermentation specialists in Baden-Württemberg and North Rhine-Westphalia anchor supply-side discipline through long-tenured management and patient capital, enabling pricing stability that resists spot-market volatility in sugar and grain feedstocks. Their captive relationships with Bavarian dairy processors and organic private-label manufacturers translate procurement loyalty into margin protection against commodity-driven price erosion.
Pricing Analysis
Yield-based pricing anchors additive procurement contracts, with German food processors paying premiums proportional to shelf-life extension or texture performance in finished goods. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified natural extracts from synthetic alternatives and unbranded commodity grades. Cost compression in economy-tier sweeteners and colorants is intensifying because private-label manufacturers consolidate volumes to negotiate formulation partnerships. Packaged food manufacturers in Baden-Württemberg's organic cluster demonstrate least price sensitivity, accepting 15-40% premiums for full Farm to Fork traceability documentation.
Supply Chain Analysis
Fermentation feedstock supply rests on German, Dutch, and Polish agricultural producers for sugar beet and grain substrates that biosynthetic colorant and microbial culture production requires. Specialty enzyme inputs and natural extract precursors draw from Danish and French biotech suppliers with precision fermentation capabilities. Single-source vulnerability concentrates in Bavarian dairy corridor dosing equipment retrofits, where legacy pneumatic conveying systems require precision handling upgrades for heat-sensitive natural extracts. Distribution runs through direct procurement relationships between additive suppliers and mid-sized processors, displacing traditional distributor intermediaries in regional cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EFSA authorization timeline compression and clean-label cost premiums force capital-constrained mid-tier suppliers toward acquisition or exit. Regulatory dossier expertise scarcity compounds competitive pressure on players lacking in-house toxicological capabilities.
For Market Incumbents: Hedge against biosynthetic disruption by securing captive fermentation capacity in underutilized Baden-Württemberg biotech infrastructure. BASF SE and Kerry Group plc exemplify divergent defensive paths—backward integration into fermentation feedstocks versus application-focused formulation partnerships with Central European bakery chains. Invest in enzymatic processing aid portfolios ahead of evolving EFSA opinions on novel protein hydrolysates to capture first-mover windows in dairy and bakery segments. For New Entrants and Emerging Players: Begin with reduced-sugar beverage reformulation white space where stevia and monk fruit extract demand outpaces supply in Bavarian bottling operations. Precision fermentation infrastructure in the Upper Rhine Valley offers expansion capacity for specialty microbial cultures with lower capital barriers than greenfield chemical synthesis. Target direct supplier relationships with Berlin-Brandenburg meat alternative manufacturers consolidating additive specifications to compress qualification cycles. For Investors and Strategic Acquirers: EFSA clean-label opinion acceleration is the leading indicator that natural preservative and colorant specialists will command valuation premiums over petrochemical-derived incumbents. Across a 5-10 year viability window, acquisition targets should exhibit validated enzymatic portfolios, existing direct procurement relationships with mid-sized processors, and documented Farm to Fork alignment certifications. Watch for BfR risk assessment expansion into novel protein hydrolysates as the signal that regulatory dossier capabilities will separate acquirable assets from stranded technology.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Baden-Württemberg biotech infrastructure enables biosynthetic efficiency advantages over petrochemical synthesis. |
| Direct Procurement Relationship Development | Bypassing distributor intermediaries captures margin from Baden-Württemberg organic private-label consolidation. |
| Enzymatic Processing Aid Portfolio Investment | EFSA opinion evolution on protein hydrolysates creates first-mover windows in dairy and bakery applications. |
| Farm to Fork Certification Program | EU Green Deal alignment documentation satisfies Bavarian processor traceability requirements for clean-label positioning. |
| Backward Integration into Fermentation Feedstocks | Captive sugar and grain substrate supply insulates margins from agricultural commodity price volatility. |
Research Methodology
Multi-period observation of EFSA opinion trajectories, BfR risk assessment schedules, and clean-label substitution timelines anchored the trend analysis, supplemented by interviews with formulation R&D directors at German food processors, procurement leads at Bavarian dairy cooperatives, technical service managers at enzyme suppliers, and regulatory affairs specialists navigating REACH registrations. Secondary validation drew from EU Green Deal implementation reports, German Food and Feed Code amendments, ECHA substance registrations, and customs data on fermentation feedstock trade flows. Bottom-up additive volume estimates triangulated against top-down packaged food production statistics.
Input-output matrix framing connected end-use application intensity—baked goods, beverages, dairy, meat alternatives—to product chemistry requirements across preservatives, emulsifiers, sweeteners, colorants, and flavor enhancers. Segmentation dimensions modeled included product type, application, physical form, and end-user category across the analysis window. CAGRs derived from trend extrapolation of reformulation project pipelines, regulatory substitution mandates, and regional production cluster expansion plans. Forecast inputs incorporated precision fermentation capacity buildout schedules and EFSA authorization timeline distributions for novel additives.
EFSA opinion delays, fermentation feedstock price spikes, and clean-label cost premium compression are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented regulatory schedules and disclosed capacity expansion intentions rather than speculative technology adoption curves. A small set of named triggers—BfR risk assessment scope expansion, EU Green Deal chemical sustainability criteria tightening, and Bavaria-North Rhine-Westphalia cluster infrastructure utilization rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
China Food Preservatives Market