
 Acidity Regulators Market | 2026-2036
Acidity Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Acidity Regulators Market Intelligence
Project finance for fermentation-based acid production is rewriting competitive entry barriers, allowing mid-scale biotech firms to challenge petrochemical-derived supply. Cargill Incorporated leverages its corn-processing backbone to sustain captive citric acid output across North American facilities. Jungbunzlauer Suisse AG anchors European supply through Swiss fermentation expertise, while Corbion N.V. differentiates via bio-based lactic acid platforms serving pharmaceutical-grade buyers.
Acidity regulators are pH-modifying food additives and industrial chemicals, typically organic acids such as citric, lactic, or acetic acid produced via fermentation or synthetic catalysis, with purity grades ranging from technical to food-grade and USP specifications. Their primary function spans preservation, flavor enhancement, and microbial stability control across processed goods and drug formulations. Citric acid dominates volume due to its versatility in beverages and confectionery, while lactic acid captures expanding margin pools from biodegradable polymer feedstock and pharmaceutical buffer applications. Phosphoric acid maintains entrenched positions in carbonated soft drinks despite flat growth, as acetic acid gains traction in clean-label vinegar-based preservation systems.
EFSA purity standards and REACH chemical registrations shape European formulation requirements, while FDA food additive regulations and USDA organic certification criteria govern North American market access and labeling claims. FSSAI standards in India and China's SAMR food safety protocols are tightening import specifications, forcing exporters to maintain multi-jurisdictional compliance documentation. Stakeholders must monitor evolving biotech-derived acid classifications, as regulatory bodies weigh novel production pathways against established petrochemical benchmarks.
Market Dynamics
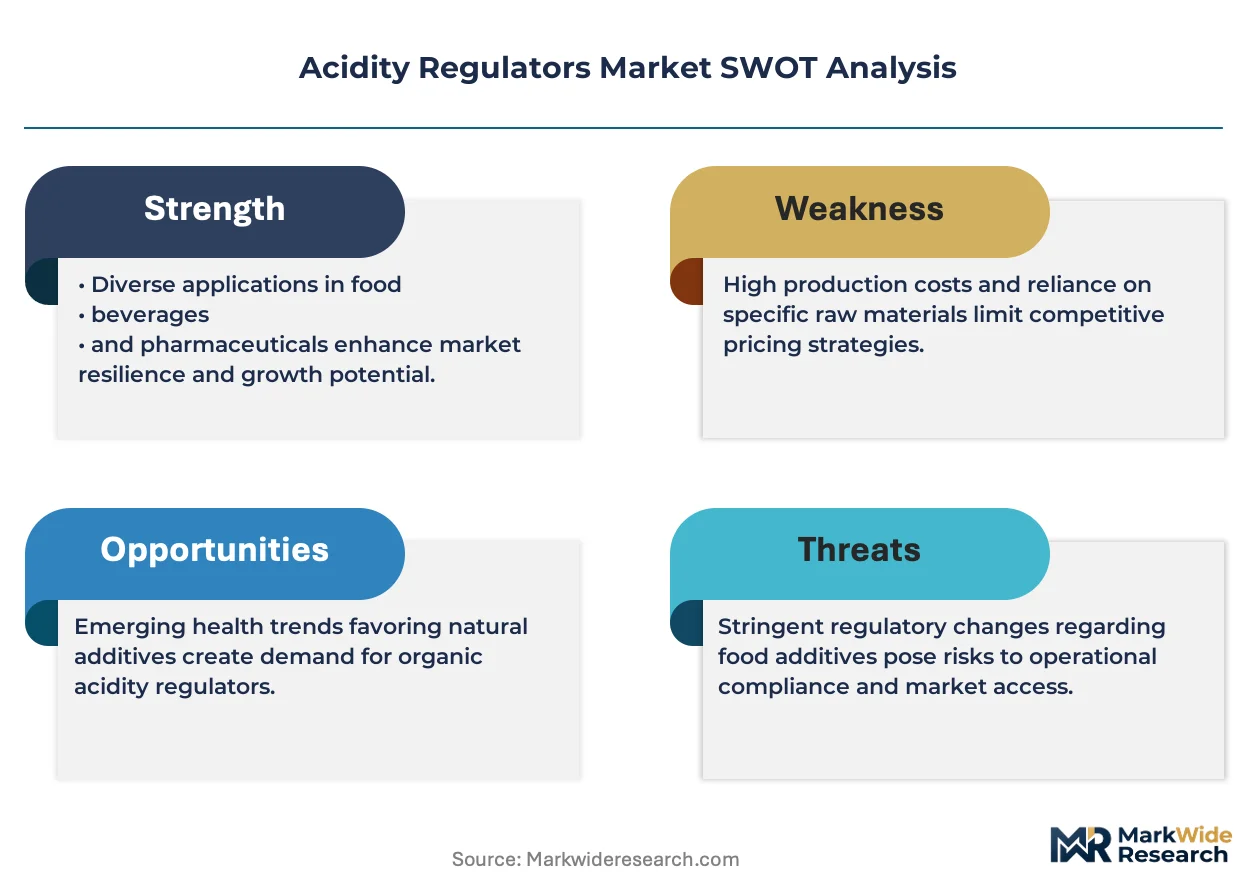
Fermentation-based production is eroding the cost advantage of petrochemical acid routes, as biotech platforms achieve parity on yield and purity metrics while bypassing volatile petroleum feedstock exposure.
Growth Catalysts
- Clean-label mandates:EFSA purity benchmarks and REACH registration requirements are compelling formulators to replace synthetic acidulants with fermentation-derived alternatives in beverage and confectionery applications.
- Biodegradable polymer feedstock:Lactic acid demand from polylactic acid manufacturers is expanding capacity utilization at fermentation facilities serving pharmaceutical-grade and industrial-grade buyers simultaneously.
- India's processed food corridor:FSSAI standard harmonization with Codex Alimentarius is accelerating acidulant adoption in domestic sauce, pickle, and ready-to-eat segments.
Market Restraints
- Molasses price volatility:Sugar crop fluctuations in Brazil and Thailand transmit directly to citric acid production economics, compressing margins for non-integrated fermentation operators.
- Chinese supply concentration:Technical-grade citric acid capacity clusters in Shandong and Jiangsu provinces, creating single-source vulnerability for European compounders lacking alternative qualified suppliers.
- Phosphoric acid substitution ceiling:Carbonated soft drink manufacturers face reformulation barriers when attempting to replace phosphoric acid with milder organic alternatives without altering taste profiles.
Strategic Opportunities
- Vinegar-based preservation systems:Acetic acid platforms are penetrating clean-label meat and seafood applications in Germany and the Netherlands where synthetic preservative bans are tightening.
- Dual-use fermentation infrastructure:Existing citric acid plants in Belgium and Switzerland can pivot output to high-margin gluconic acid for pharmaceutical buffer applications with minimal retooling.
- EU Green Deal bio-based quotas:Mandatory renewable content thresholds in packaging are channeling lactic acid demand toward polymer-grade specifications at premium pricing tiers.
Industry Challenges
- Multi-jurisdictional compliance documentation:Exporters must maintain parallel dossiers for FDA food additive petitions, EFSA novel food assessments, and SAMR import registrations, stretching regulatory affairs bandwidth.
- USP-grade certification timelines:Pharmaceutical acidulant qualification requires 18-24 month validation cycles that delay revenue recognition from new fermentation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acidity Regulators Market |
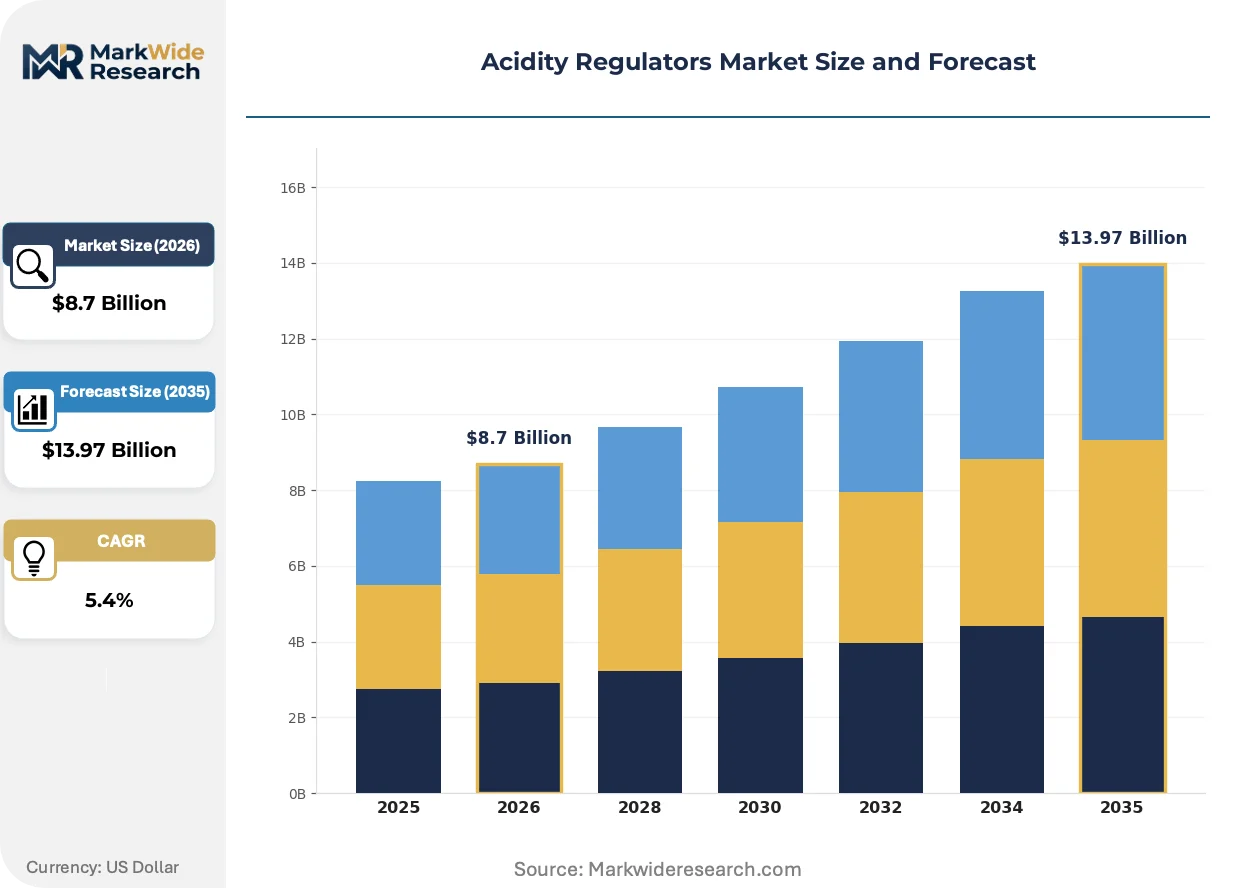
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Acetic Acid, Lactic Acid, Phosphoric Acid End User: Food & Beverage, Pharmaceuticals, Cosmetics, Agriculture Application: Preservative, Acidulant, Flavoring Agent, pH Control Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Jungbunzlauer Suisse AG, Tate & Lyle Plc, Corbion N.V., Bartek Ingredients Inc., ATP Group, Fuerst Day Lawson Ltd., Bertek Ingredient Incorporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acidity Regulators Market Strategic Shifts & Innovations
Digital process control and biosensor integration are compressing batch-to-batch variability in fermentation systems, enabling real-time purity adjustments that previously required post-hoc refining steps.
Continuous fermentation monitoring via Raman spectroscopy and machine-learning feedback loops is digitizing quality assurance workflows. Mid-scale biotech operators in the Benelux region are deploying these systems to achieve pharmaceutical-grade consistency without capital-intensive downstream purification. The technology is digitizing competitive entry barriers by allowing smaller fermenters to match the certificate-of-analysis reliability historically concentrated at integrated petrochemical-acid majors.
REACH chemical registration deadlines for existing acidulant substances are forcing reformulation audits across European processed food and beverage portfolios. Manufacturers must submit updated safety dossiers or face market withdrawal, with citric acid and its salts receiving particular scrutiny due to high-volume exposure scenarios. German and Dutch formulators are responding by dual-sourcing from ECHA-registered European fermentation facilities and maintaining buffer inventories against authorization delays.
Buyers are consolidating acidulant procurement through direct contracts with fermentation operators rather than distributed chemical distributors. Large beverage compounders in the United States and compound feed manufacturers in Spain are negotiating multi-year offtake agreements that embed volume commitments and price collars. This consolidation is most visible in the carbonated soft drink vertical, where two North American bottlers now account for a disproportionate share of domestic citric acid contract volume.
Acidity Regulators Market Segmentation
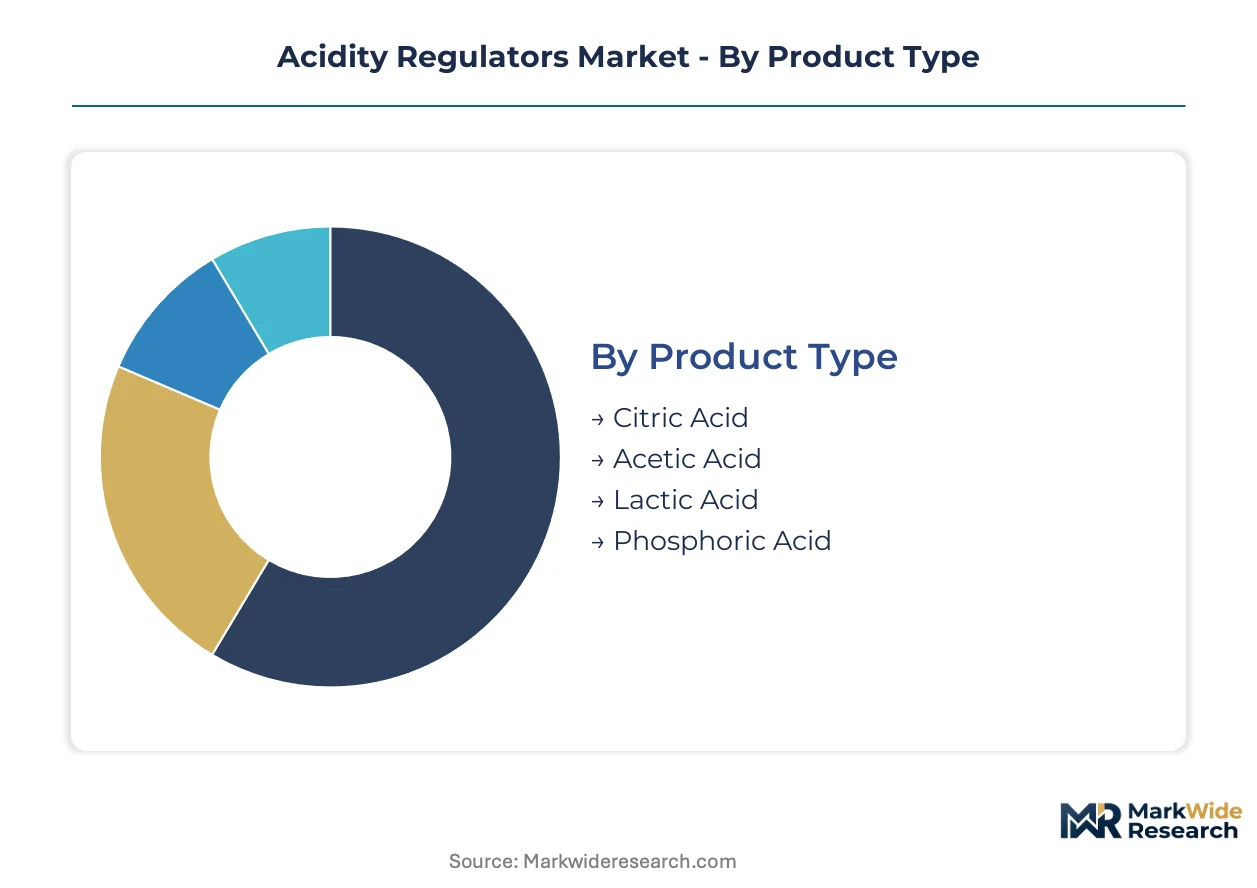
Acidity regulators serve divergent purity and functional requirements across food preservation, pharmaceutical buffering, and industrial polymer feedstock. Segmentation reveals how fermentation-derived organic acids compete against petrochemical alternatives on specification tiers rather than commodity pricing alone.
Product Type:
Cost tier stratification separates commodity-grade citric acid from premium lactic acid specifications serving biodegradable polymer manufacturers.
- Citric Acid:Fermentation-derived from Aspergillus niger on molasses substrate, this organic acid dominates beverage acidulation and confectionery preservation. German beverage compounders in the Rhineland corridor source heavily from Benelux fermentation clusters to satisfy EFSA purity dossier requirements.
- Lactic Acid:Bacterial fermentation of carbohydrate feedstocks yields this chiral acid in food-grade and polymer-grade specifications. Polylactic acid manufacturers in the Netherlands and Belgium are absorbing expanding fermentation capacity at premium pricing tiers under EU Green Deal bio-based quotas.
- Acetic Acid:Synthetic carbonylation and fermentation vinegar routes supply this C2 acid for clean-label preservation systems.
- Phosphoric Acid:Wet-process acid from phosphate rock maintains entrenched positions in carbonated soft drink acidulation despite flat volume trajectories.
Citric acid holds installed capacity. Lactic acid is rotating up the share rankings.
End User:
Application maturity varies sharply across end-use verticals, with pharmaceutical-grade qualification timelines stretching 18-24 months versus food-grade certification cycles.
- Food & Beverage:Beverage acidulation, sauce preservation, and confectionery pH modification constitute the largest consumption block. REACH registration deadlines are forcing European formulators to audit acidulant portfolios and dual-source from ECHA-registered fermentation facilities.
- Pharmaceuticals:USP-grade citric acid and lactic acid serve as buffering agents in injectable formulations and tablet excipients. Swissmedic and EMA quality standards mandate certificate-of-analysis consistency that only continuous fermentation monitoring systems can reliably deliver.
- Cosmetics:pH adjustment in skincare and haircare formulations drives demand for high-purity organic acids with low heavy-metal specifications.
- Agriculture:Acidulant use in feed preservation and silage treatment concentrates in compound feed manufacturing corridors across Spain and northern Germany.
Food & Beverage maintains volume concentration. Pharmaceuticals is climbing the fastest on margin contribution.
Application:
Functional role determines specification stringency, with preservative applications demanding antimicrobial efficacy documentation while flavoring applications prioritize sensory neutrality.
- Preservative:Acid-induced pH reduction inhibits microbial spoilage in sauces, pickles, and ready-to-eat meals. FSSAI standard harmonization with Codex Alimentarius is accelerating adoption in India's domestic processed food corridor.
- Acidulant:Tartness delivery in beverages and confectionery requires precise titratable acidity control. German and Dutch formulators are substituting synthetic acidulants with fermentation-derived alternatives under tightening EFSA purity benchmarks.
- Flavoring Agent:Vinegar-derived acetic acid contributes clean-label taste profiles in meat and seafood applications where synthetic preservative bans are tightening.
- pH Control:Buffering applications in pharmaceuticals and cosmetics demand narrow pH specification windows.
Preservative commands formulation expertise concentration. Acidulant is gaining share fastest on clean-label substitution.
Form:
Physical state selection hinges on dissolution kinetics, dust exposure regulations, and handling infrastructure at compounder facilities.
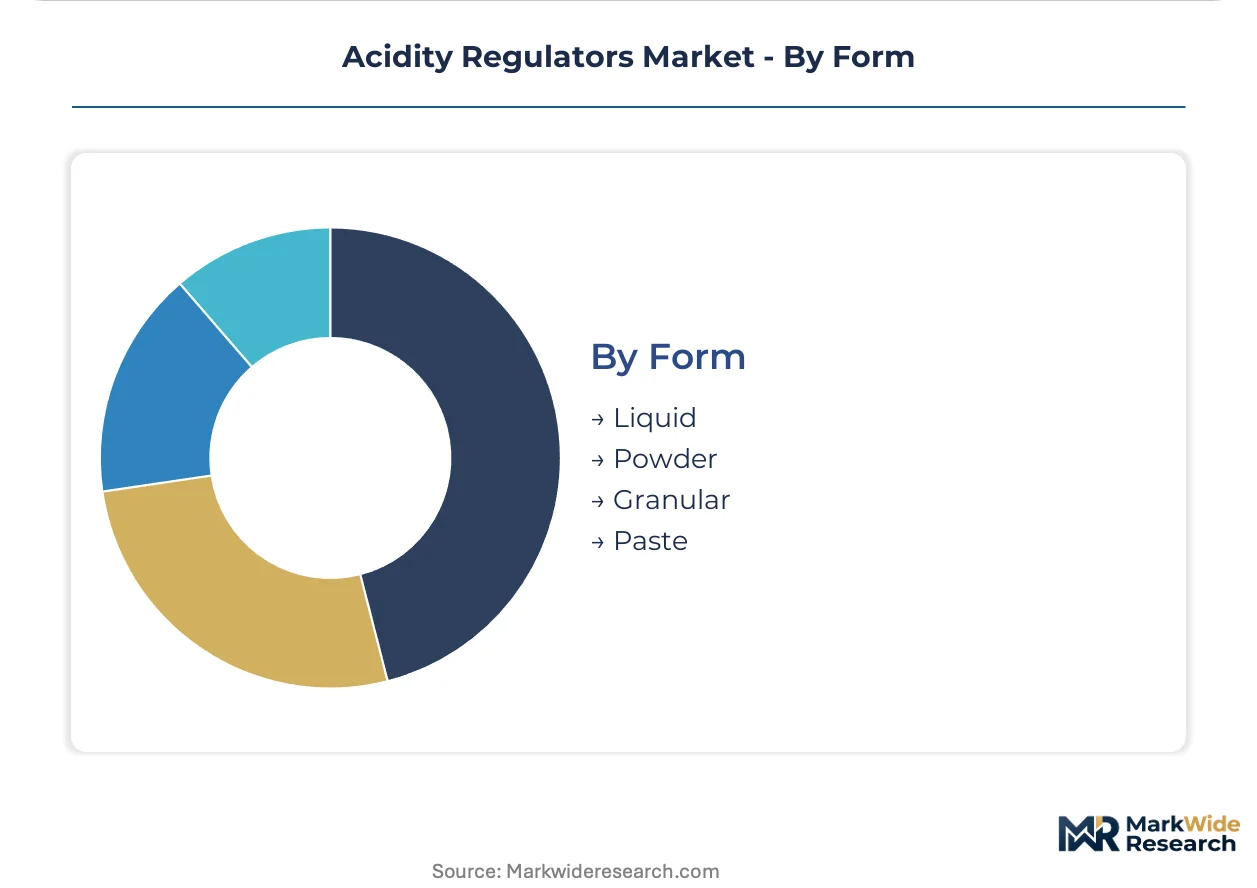
- Liquid:Pumpable acid solutions suit high-volume beverage manufacturing with automated dosing systems. Carbonated soft drink bottlers in the United States negotiate multi-year offtake agreements for liquid citric acid with embedded volume commitments.
- Powder:Spray-dried acid crystals offer storage stability and precise metering in dry blend applications. Powdered lactic acid serves pharmaceutical tablet compression where moisture sensitivity constrains liquid alternatives.
- Granular:Free-flowing granules reduce dust generation versus powders in feed manufacturing environments.
- Paste:High-concentration semi-solids address niche applications in confectionery and specialty food processing.
Liquid holds distribution infrastructure concentration. Powder is rotating up the share rankings on pharmaceutical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in citric acid and lactic acid are reshaping regional procurement strategies. Brazil and Thailand molasses supply disruptions transmit directly to European compounder margins. Chinese technical-grade capacity concentration creates single-source vulnerability for importers lacking qualified alternatives.
Germany
Beverage compounders in the Rhineland corridor drive fermentation-derived citric acid procurement for clean-label reformulations. EFSA purity dossier requirements and REACH registration deadlines compel dual-sourcing from ECHA-registered Benelux facilities. The processed food corridor spanning Cologne-Düsseldorf anchors acidulant demand from sauce and ready-to-eat manufacturers.
United States
Carbonated soft drink bottlers negotiate multi-year liquid citric acid offtake agreements with embedded volume commitments. FDA food additive regulations and USDA organic certification criteria govern market access for fermentation-derived alternatives. Corn-belt processing infrastructure in Iowa and Illinois sustains captive acid output for North American beverage manufacturing.
China
Technical-grade citric acid capacity clusters in Shandong and Jiangsu provinces supply global compounders at scale. SAMR food safety protocols and tightening import specifications force exporters to maintain parallel compliance documentation. Yangtze River Delta chemical processors face margin pressure from molasses price volatility transmitted through Brazilian supply chains.
India
FSSAI standard harmonization with Codex Alimentarius accelerates acidulant adoption in domestic sauce, pickle, and ready-to-eat segments. Processed food corridors in Maharashtra and Gujarat concentrate demand from emerging branded food manufacturers. National pharmaceutical regulator CDSCO mandates certificate-of-analysis consistency for USP-grade acid imports serving injectable formulation producers.
Netherlands
Polylactic acid manufacturers absorb expanding lactic acid fermentation capacity at premium pricing tiers under EU Green Deal bio-based quotas. Rotterdam-Antwerp chemical clusters host dual-use infrastructure pivoting between citric acid and high-margin gluconic acid output. ECHA registration maintenance requirements drive buffer inventory strategies among Benelux compounders.
Acidity Regulators Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on fermentation expertise and purity grades. The vendor base stratifies between integrated agribusiness operators with captive feedstock access and mid-scale biotech firms leveraging digital process control. Three archetypes dominate: corn-processing conglomerates with backward integration into organic acid output; Swiss and Dutch fermentation specialists serving pharmaceutical-grade buyers; and Chinese technical-grade producers competing on volume scale. Competitive moves concentrate on multi-year offtake agreement negotiation and dual-use fermentation infrastructure deployment.
Among North American agribusiness operators, Cargill Incorporated represents the integrated feedstock-to-acid archetype with corn-processing backbone advantages. Jungbunzlauer Suisse AG anchors the European fermentation specialist tier, while Corbion N.V. occupies a position within the bio-based platform segment serving polymer-grade and pharmaceutical-grade specifications simultaneously. Tate & Lyle Plc exemplifies the diversified ingredient house model with acidulant portfolios embedded within broader sweetener and texture agent offerings.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Jungbunzlauer Suisse AG |
| Tate & Lyle Plc |
| Corbion N.V. |
| Bartek Ingredients Inc. |
| ATP Group |
| Fuerst Day Lawson Ltd. |
| Bertek Ingredient Incorporation |
| Others |
Cost & Logistics Intelligence
Shandong province's technical-grade citric acid clusters transmit pricing power downstream through volume concentration, while European compounders absorb premium tiers for EFSA-registered fermentation output. Molasses cost volatility from Brazilian sugar crop cycles feeds directly into margin compression for non-integrated operators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures in the carbonated soft drink vertical. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade specifications reflects USP certification timelines and purity dossier completeness. Cost compression in commodity citric acid is intensifying because Chinese capacity expansion outpaces Western fermentation yield improvements. Compound feed manufacturers in Spain demonstrate highest price sensitivity, while Dutch polylactic acid producers accept premium tiers for EU Green Deal compliance.
Supply Chain Analysis
Contract manufacturing concentration rests with Jungbunzlauer's Swiss fermentation facilities, Corbion's Dutch bio-based platforms, and Cargill's North American corn-processing complexes. Geographic supply concentration centers on China, Belgium, and the United States for fermentation-derived output. Raw material dependencies draw from Brazilian molasses, North American corn starch, and Thai tapioca feedstocks. Single-source vulnerability from Shandong-Jiangsu capacity clusters threatens European compounders lacking qualified alternatives. Distribution runs through direct procurement contracts with fermentation operators rather than chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-based acid production is reshaping platform economics, as digital process control enables mid-scale biotech firms to achieve certificate-of-analysis reliability previously concentrated at integrated majors. Interoperability between food-grade and pharmaceutical-grade specifications creates ecosystem lock-in for dual-use infrastructure operators.
For Market Incumbents: Pre-empt margin erosion in commodity citric acid by deploying backward integration into captive molasses sourcing or corn-processing infrastructure. Cargill's captive feedstock model demonstrates defensive positioning against Brazilian supply volatility. Certification investment in USP-grade lactic acid buffers revenue recognition delays through multi-year pharmaceutical offtake agreements. For New Entrants and Emerging Players: Build out vinegar-based acetic acid capacity targeting Germany and Netherlands clean-label meat preservation segments where synthetic preservative bans are tightening. India's processed food corridor offers penetrable white-space for FSSAI-compliant acidulant supply, with sauce and ready-to-eat manufacturers lacking domestic fermentation alternatives. Go-to-market leverage rests on CDSCO certificate-of-analysis partnerships for pharmaceutical-grade qualification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation specialists with dual-use infrastructure pivoting between citric acid and gluconic acid output. Long-term viability across the projection horizon favors Swiss and Dutch operators with ECHA-registered capacity and digital process control deployment. Acquisition targets should demonstrate Raman spectroscopy integration and machine-learning feedback loops for batch consistency. The signal to watch is multi-year offtake agreement density from North American beverage bottlers and Benelux polymer manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Fermentation Infrastructure | Belgian and Swiss plants pivot output between citric acid and high-margin gluconic acid with minimal retooling. |
| Backward Integration into Feedstock | Corn-processing backbone secures captive molasses and starch supply against Brazilian price volatility. |
| USP-Grade Certification Investment | Swissmedic and EMA quality standards mandate 18-24 month validation cycles that delay competitor entry. |
| Direct Procurement Contracting | Large beverage compounders negotiate multi-year offtake agreements embedding volume commitments and price collars. |
| Digital Process Control Deployment | Raman spectroscopy and machine-learning feedback loops compress batch-to-batch variability for pharmaceutical-grade consistency. |
Research Approach
A spread of perspectives from fermentation plant managers, beverage compounder procurement leads, pharmaceutical regulatory affairs directors, and distribution channel partners converged on the working assumptions. Secondary validation drew from EFSA novel food assessments, REACH registration databases, FSSAI standard harmonization documents, and SEC 10-K filings from listed ingredient houses. Bottom-up capacity utilization data triangulated against top-down end-use consumption estimates across food, pharmaceutical, and polymer verticals.
Demand-supply-balance modeling anchored projections across the analysis window, with segmentation dimensions spanning acid type, purity grade, end-use industry, and regional production hub. CAGRs were derived from installed capacity expansion schedules, yield improvement trajectories from digital process control adoption, and substitution elasticity between fermentation-derived and petrochemical acid routes. Industry-specific inputs included molasses price forecasting from Brazilian crop cycle data and EU Green Deal bio-based quota implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese technical-grade producers or accelerated pharmaceutical-grade qualification by mid-scale biotech entrants would shift outcomes. Quarterly review of REACH registration deadline compliance, ECHA authorization delays, and multi-year offtake agreement signings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
France Food Enzymes Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Spain Food Emulsifiers Market