
 Biscuit Shortening Flakes Market | 2026-2036
Biscuit Shortening Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Biscuit Shortening Flakes Market Analytics
Buyer concentration among industrial biscuit manufacturers is hardening as regional bakery chains consolidate procurement and national snack producers expand in-house cracker operations. Bunge Global SA leverages its North American oilseed processing network to secure long-term supply agreements with major cookie brands. Fuji Oil Co. Ltd. sustains technical leadership in specialty fat structuring through its Japanese and Southeast Asian R&D facilities. Cargill Inc. anchors global availability with integrated oil refining and flake crystallization capacity across multiple continents.
Biscuit shortening flakes are engineered lipid products manufactured through controlled interesterification or fractionation of vegetable oils, designed to deliver specific plasticity ranges and melting profiles for laminated and rotary-molded dough systems. Their primary commercial purpose is to create discrete fat layers that interrupt gluten development, yielding the characteristic flaky, tender texture in crackers, cookies, and savory biscuits. Non-hydrogenated shortening flakes now lead product type demand as trans fat regulations eliminate legacy hydrogenated formulations across major markets. Commercial baking dominates application volume, though snack foods represent the fastest-growing segment as extruded and sheeted savory products expand in emerging markets.
The FDA governs shortening flake composition through its determination that partially hydrogenated oils are no longer generally recognized as safe, while the EFSA and EU Commission enforce parallel restrictions on industrial trans fats through the EU Green Deal's Farm to Fork strategy. These frameworks compel manufacturers to invest in enzymatic interesterification and palm oil fractionation as replacement technologies. Stakeholders must monitor evolving national trans fat limits and alternative crop oil availability to secure formulation flexibility and supply chain continuity.
Market Dynamics
Enzymatic interesterification is compressing production timelines for non-hydrogenated shortening flakes while palm oil fractionation investments reshape supplier economics across major biscuit-producing regions.
Growth Catalysts
- Clean-label mandates:The FDA's trans fat labeling requirements and subsequent PHO phase-out compel commercial bakeries to reformulate with non-hydrogenated alternatives, accelerating volume procurement of enzymatically processed shortening flakes.
- Rotary-molded cracker expansion:Large-scale cookie and cracker producers in the United States are consolidating procurement into multi-year supply agreements, concentrating demand among specialized flake manufacturers.
- Snack food diversification:Extruded and sheeted savory biscuit applications in emerging markets are creating new formulation specifications for high-melting-point shortening flakes with extended shelf stability.
Market Restraints
- Palm oil price volatility:Fractionated palm stearin constitutes the primary feedstock for non-hydrogenated flake production, exposing margins to Southeast Asian weather disruptions and biofuel policy shifts in Indonesia and Malaysia.
- Specialized equipment capex:Crystallization tunnel and scraped-surface heat exchanger systems require substantial capital outlay, limiting new entrant participation to established oil refiners with existing lipid processing infrastructure.
- Technical performance gaps:Enzymatically interesterified fats occasionally exhibit inferior oxidative stability compared to legacy hydrogenated formulations, constraining adoption in extended-distribution cracker applications.
Strategic Opportunities
- Shea butter fractionation:West African shea stearin offers a trans-fat-free, non-palm alternative for premium clean-label positioning, with European biscuit manufacturers piloting formulations ahead of anticipated EU Green Deal sourcing requirements.
- High-oleic sunflower integration:Blending high-oleic sunflower oil with palm fractions creates tailored melting profiles for laminated dough systems, opening technical differentiation in artisanal and specialty biscuit segments.
- Direct-to-bakery distribution:Regional shortening producers are bypassing traditional ingredient distributors to establish technical service relationships with mid-sized commercial bakeries, capturing margin and formulation influence.
Industry Challenges
- Lipid crystallization expertise shortage:The transition from hydrogenation to enzymatic interesterification and fractionation demands specialized knowledge in polymorphism control and tempering protocols that existing workforce development programs inadequately address.
- Reformulation timeline compression:Accelerated regulatory deadlines for trans fat elimination force simultaneous product redevelopment across multiple biscuit lines, straining R&D bandwidth and consumer acceptance testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biscuit Shortening Flakes Market |
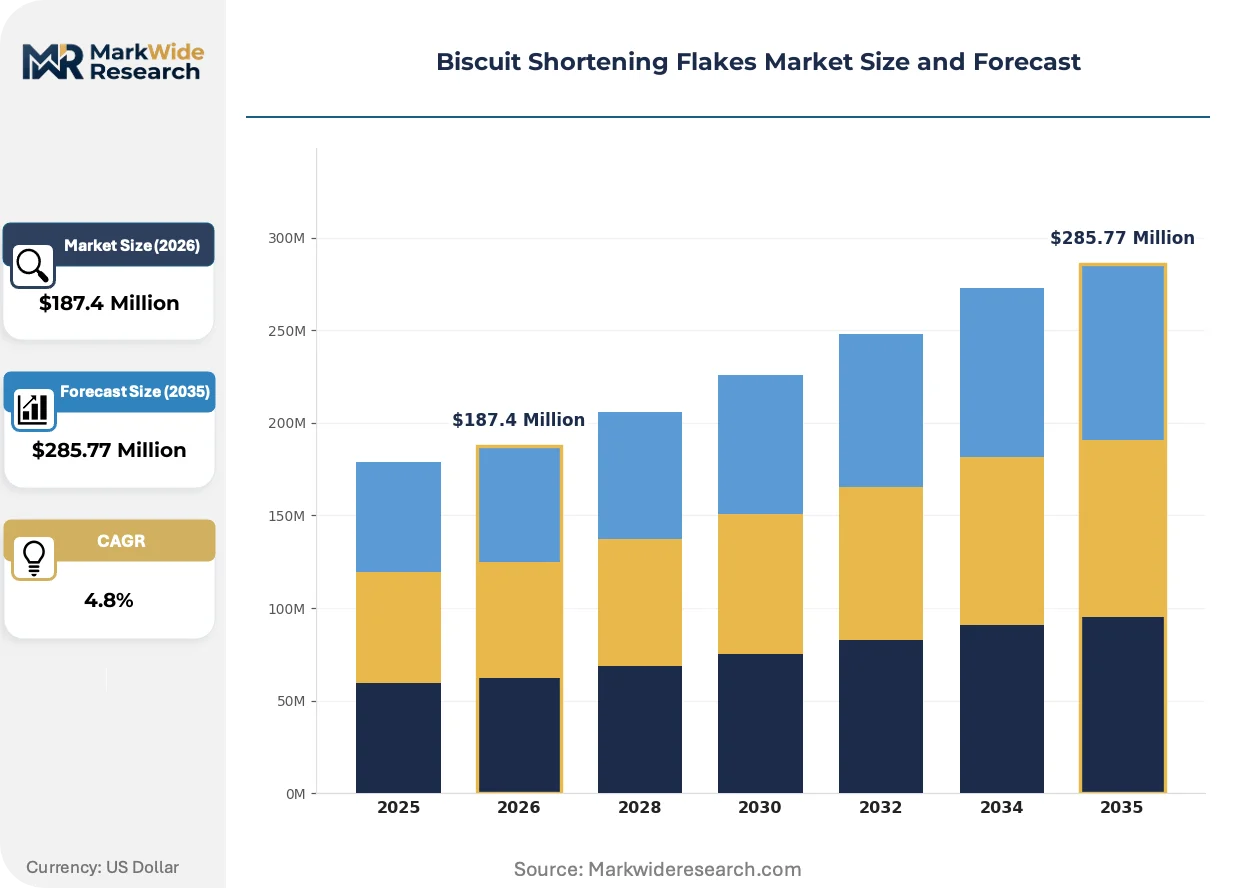
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogenated, Non-Hydrogenated, Organic, Conventional Application: Commercial Baking, Household Baking, Snack Foods, Confectionery Packaging Type: Bags, Boxes, Pails, Tubs Distribution Channel: Direct Sales, Retail Stores, E-commerce, Food Service |
| Companies Covered | Bunge Global SA, Fuji Oil Co. Ltd., AAK AB, Stratas Foods, Associated British Foods Plc, Cargill Inc., Wilmar International Ltd., Palsgaard AS, Archer Daniels Midland Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biscuit Shortening Flakes Market Evolving Landscape
Controlled crystallization technologies and alternative feedstock development are redefining shortening flake performance specifications while regulatory chemistry restrictions eliminate legacy formulation pathways.
Enzymatic interesterification using immobilized lipases is rewriting the economics of specialty fat structuring. Commercial bakeries in North America and Western Europe are adopting enzymatically modified shortening flakes at accelerating rates as technical performance parity with hydrogenated alternatives improves. This biocatalytic approach is compressing capital requirements for new production capacity while enabling precise manipulation of triglyceride positioning for targeted plasticity ranges.
The EFSA and EU Commission are enforcing industrial trans fat limits through the Farm to Fork strategy, with maximum thresholds tightening across member states. Biscuit manufacturers serving pan-European distribution networks must now validate non-hydrogenated formulations across multiple national enforcement contexts. Premium and private-label cracker producers are responding by securing dedicated supply chains for certified-trans-fat-free shortening flakes with full traceability documentation.
Buyer concentration among national snack producers is consolidating ingredient procurement into centralized technical purchasing functions. Regional bakery chains are displacing fragmented distributor relationships with direct supply agreements that bundle formulation support, technical service, and volume pricing. This behavioral shift is most visible in the United States, where top-ten cracker manufacturers now account for the majority of specialized shortening flake contracts and drive supplier qualification protocols.
Biscuit Shortening Flakes Market Segmentation
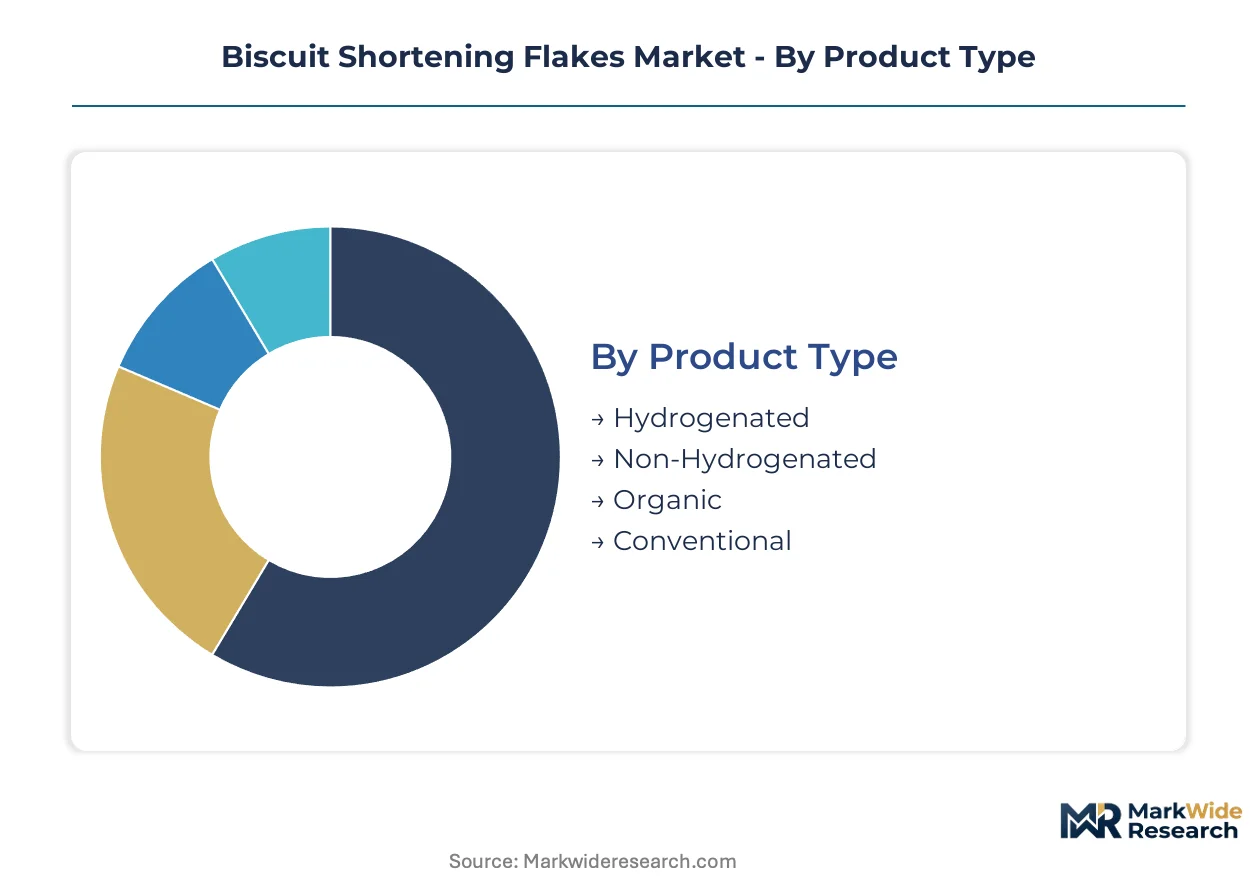
Segmentation in the Biscuit Shortening Flakes Market reveals distinct capital requirements and technical specifications across product formulations. Each category exposes divergent investment thresholds, from enzymatic processing infrastructure to cold-chain packaging systems, that reshape supplier economics and buyer procurement patterns.
Product Type:
Capital intensity varies sharply across product types, with enzymatic interesterification facilities demanding substantially higher upfront investment than legacy hydrogenation infrastructure.
- Non-Hydrogenated:Enzymatically interesterified or fractionated vegetable oil formulations eliminate trans fats through biocatalytic restructuring. Commercial bakeries in the United States are consolidating procurement into multi-year supply agreements as FDA trans fat regulations harden, though palm oil feedstock volatility constrains margin stability.
- Hydrogenated:Partially hydrogenated oil formulations face phased elimination under FDA determinations that PHOs are no longer generally recognized as safe. Remaining production concentrates in limited jurisdictions with delayed enforcement timelines, serving legacy equipment configurations in smaller regional bakeries.
- Organic:Certified organic shortening flakes command premium positioning through certified sustainable palm or shea butter feedstocks.
- Conventional:Standard fractionated palm stearin products serve cost-sensitive volume applications without organic certification requirements.
Non-Hydrogenated absorbs the bulk of installed capacity; Organic is expanding most quickly.
Application:
Application segmentation tracks divergent performance requirements, with laminated dough systems demanding precise plasticity control that rotary-molded products do not.
- Commercial Baking:Large-scale cracker and cookie manufacturers require specialized flake crystallization for consistent gluten interruption in high-speed production lines. United States-based national snack producers are driving the steepest expansion trajectory through centralized technical procurement functions that bundle formulation support with volume contracts.
- Snack Foods:Extruded and sheeted savory biscuits in emerging markets specify high-melting-point flakes with extended oxidative stability for tropical distribution. Reformulation timelines compress as multinational brands harmonize specifications across manufacturing footprints.
- Household Baking:Consumer-packaged shortening flakes in retail formats serve artisanal bakers and small-scale foodservice operations.
- Confectionery:Specialty fat applications for filled biscuits and enrobed products require tailored melting profiles distinct from standard cracker formulations.
Commercial Baking commands the dominant share of specialized flake procurement; Snack Foods is climbing the fastest as savory biscuit portfolios expand.
Packaging Type:
Packaging selection reflects handling automation levels and shelf-life requirements, with bulk formats minimizing unit costs for high-volume users.
- Pails:Rigid plastic pails with resealable lids protect flake integrity through multiple production cycles in mid-sized bakery operations. North American regional bakery chains favor pail formats for direct-to-bakery distribution models that bypass traditional ingredient distributors.
- Bags:Multi-wall paper or polymer bags serve high-throughput commercial facilities with automated dispensing systems and rapid inventory turnover.
- Boxes:Corrugated containers with inner liners accommodate palletized shipment for industrial-scale procurement.
- Tubs:Consumer-oriented tubs target household baking and small foodservice accounts with portion-controlled access.
Pails capture the largest installed base for intermediate-scale operations; Bags is gaining share fastest through automated commercial bakery expansion.
Distribution Channel:
Channel structure determines margin capture and technical service intensity, with direct relationships displacing fragmented distributor networks among sophisticated buyers.
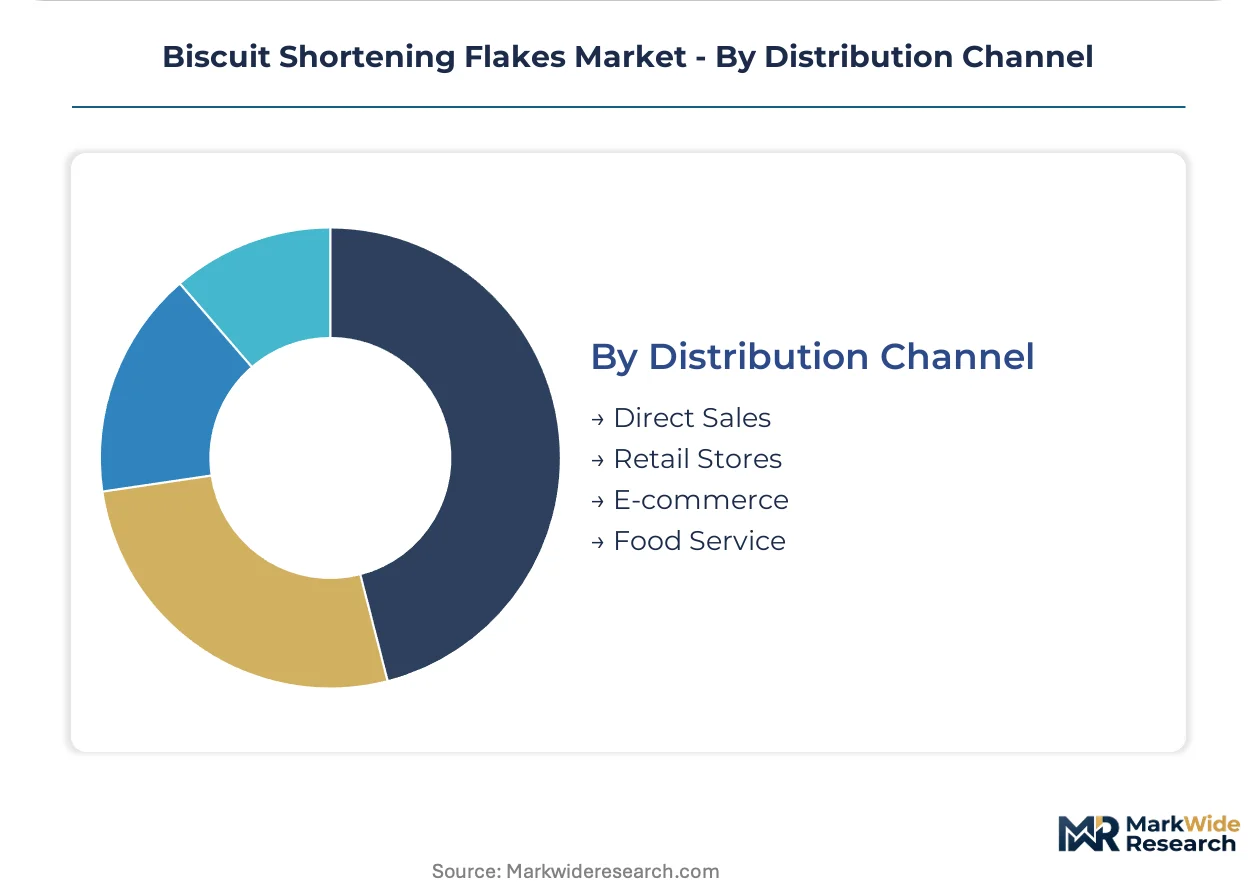
- Direct Sales:Manufacturer-to-bakery relationships bundle crystallization expertise, formulation support, and volume pricing for qualified accounts. Top-ten United States cracker manufacturers now source predominantly through direct technical purchasing functions that drive supplier qualification protocols.
- Food Service:Broadline distributors serve institutional bakeries and contract manufacturers with standardized flake specifications and consolidated delivery schedules.
- E-commerce:Digital procurement platforms facilitate spot purchasing and sample ordering for formulation development and small-batch production.
- Retail Stores:Traditional ingredient distributors maintain shelf presence for household baking and artisanal producer segments.
Direct Sales anchors procurement for industrial-scale users; Food Service is expanding most quickly through consolidated distributor relationships with regional bakery chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial bakeries in the United States concentrate procurement of non-hydrogenated shortening flakes as FDA trans fat regulations eliminate legacy hydrogenated formulations. Large-scale cracker and cookie producers drive multi-year supply agreements with specialized flake manufacturers. This demand-side concentration shapes regional supply chain configurations across major biscuit-producing markets.
United States
National snack producers in Chicago and Philadelphia consolidate procurement into centralized technical purchasing functions. The FDA's determination that partially hydrogenated oils are no longer generally recognized as safe compels reformulation timelines. North Carolina's Research Triangle hosts lipid crystallization R&D facilities serving major cookie brands.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia pilot shea butter fractionation for premium clean-label positioning. EFSA trans fat limits through the Farm to Fork strategy enforce maximum thresholds across member states. Hamburg anchors palm oil refining capacity supplying Northern European biscuit manufacturers.
China
Guangdong and Jiangsu provinces expand extruded savory biscuit production for domestic and export markets. SAMR enforces national food safety standards for edible oils and fats used in baked goods. Shanghai's Yangtze River Delta cluster concentrates shortening flake distribution infrastructure for East Asian markets.
India
Maharashtra and Gujarat host expanding commercial bakery operations serving urban snack food demand. FSSAI mandates trans fat limits in edible fats and oils through progressive regulatory tightening. Mumbai-Pune industrial corridor attracts fractionated palm stearin imports for regional shortening production.
Brazil
São Paulo state cracker manufacturers reformulate with non-hydrogenated alternatives as ANVISA trans fat regulations advance. Domestic palm oil processing investments in Pará state reduce import dependency for shortening feedstocks. Campinas hosts technical service operations for major South American biscuit producers.
Biscuit Shortening Flakes Market Competitive Landscape
North American producers anchor one tier; Japanese and Southeast Asian specialists hold technical leadership in enzymatic interesterification. The vendor base concentrates among integrated oilseed processors and specialty fat compounders with crystallization infrastructure. Three archetypes dominate: global agricultural conglomerates with captive oil refining, regional lipid specialists with formulation expertise, and diversified food ingredient houses with bakery technical service capabilities. Capacity expansion and direct-to-bakery distribution partnerships constitute the dominant competitive moves.
Within the integrated agricultural processor tier, Bunge Global SA and Cargill Inc. exemplify North American market anchoring through oilseed processing networks and multi-continental flake crystallization capacity. Fuji Oil Co. Ltd. occupies a position representing Japanese technical specialization in specialty fat structuring through regional R&D facilities. Wilmar International Ltd. anchors Southeast Asian supply chain integration with palm oil fractionation assets serving emerging market biscuit expansion.
| Leading Market Players |
|---|
| Bunge Global SA |
| Fuji Oil Co. Ltd. |
| AAK AB |
| Stratas Foods |
| Associated British Foods Plc |
| Cargill Inc. |
| Wilmar International Ltd. |
| Palsgaard AS |
| Archer Daniels Midland Co. |
| Others |
Value Network & Pricing Analysis
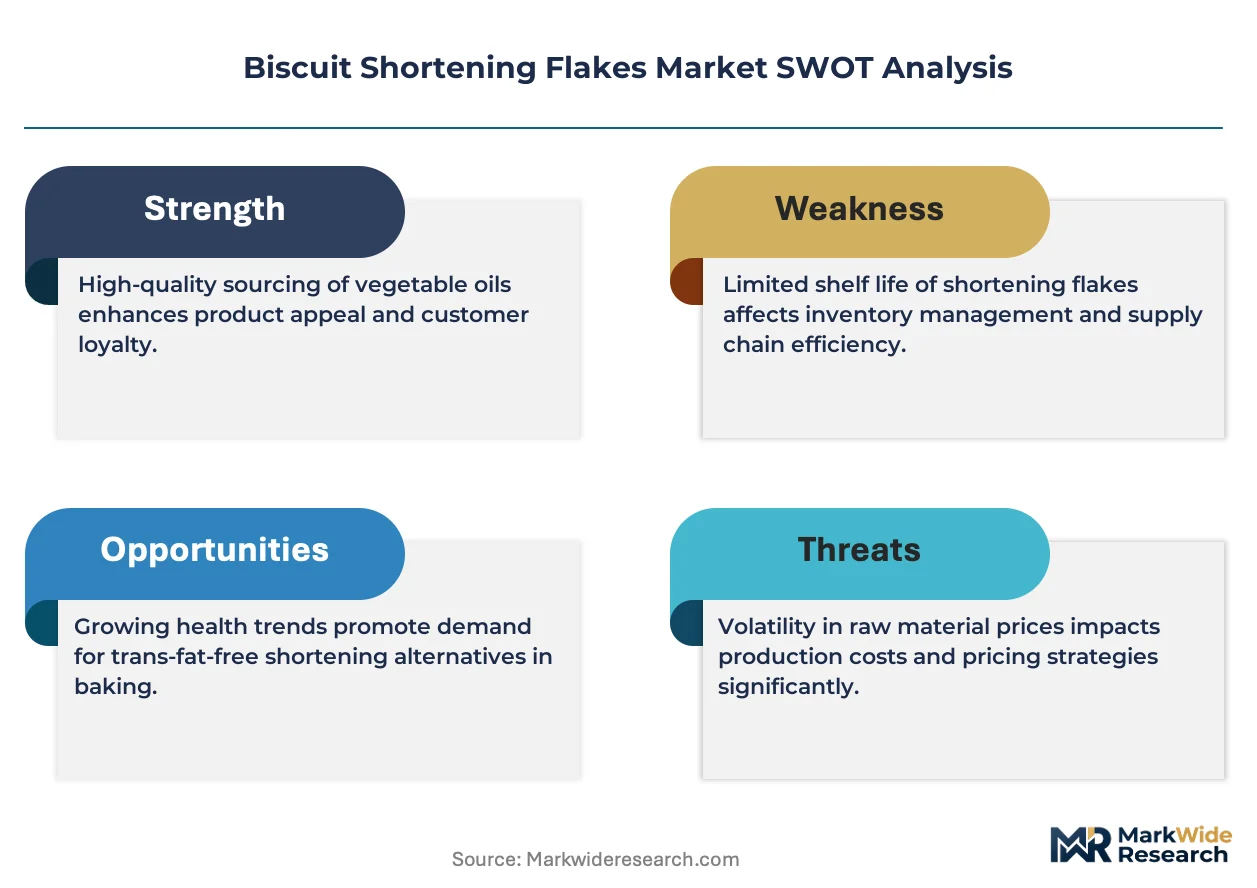
Family-owned Malaysian palm oil processors anchor feedstock supply for non-hydrogenated shortening flakes, concentrating pricing power in Southeast Asian fractionation hubs while compressing margins for European compounders facing EU Green Deal traceability costs.
Pricing Analysis
Volume contracts dominate procurement among United States cracker manufacturers, while specialty enzymatic interesterification flakes command margin premiums through technical service bundling. Price differentiation rests on certification tier and crystallization precision, with organic-shea blends carrying the steepest markups. Pricing pressure intensifies from palm stearin feedstock volatility driven by Indonesian biofuel policy shifts. Mid-sized commercial bakeries exhibit acute price sensitivity, whereas national snack producers prioritize formulation stability over unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for crystallization equipment refurbishment flows from European compounders back to Japanese and Southeast Asian OEM specialists, extending asset lifecycles for enzymatic processing lines. Geographic supply concentrates in Malaysia, Indonesia, and Germany, with fractionated palm stearin and high-oleic sunflower oil as critical inputs. Single-source vulnerability in Southeast Asian palm processing creates structural exposure to weather and export policy disruptions. Distribution runs through direct manufacturer-to-bakery relationships for industrial accounts, supplemented by broadline foodservice distributors for regional bakery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's trans fat phase-out erects a cost-of-compliance barrier that favors incumbents with enzymatic interesterification capacity, locking out capital-constrained regional refiners unable to fund crystallization tunnel infrastructure.
For Market Incumbents: Extend technical service relationships with mid-sized United States bakery chains to capture distributor-displaced margin, while accelerating shea butter fractionation partnerships ahead of anticipated EU Green Deal sourcing mandates. Biocatalytic patent expirations threaten formulation differentiation; defend through captive R&D in polymorphism control and tempering protocol optimization. For New Entrants and Emerging Players: Launch via direct-to-bakery distribution targeting artisanal and specialty biscuit segments in Germany and the United States, where premium clean-label positioning offsets scale disadvantages. High-oleic sunflower integration for laminated dough applications offers the most penetrable white-space, with formulation support bundling as the critical go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor Southeast Asian palm fractionation assets with idle crystallization capacity and established FDA compliance documentation. Long-term viability hinges on feedstock diversification beyond palm; monitor shea butter supply chain maturation in West Africa as the inflection signal for premium clean-label positioning viability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Capacity Expansion | Builds FDA-compliant production infrastructure ahead of hydrogenated flake elimination deadlines. |
| Shea Butter Fractionation Partnership | Secures non-palm feedstock for EU Green Deal-aligned clean-label positioning in premium segments. |
| Direct-to-Bakery Distribution Launch | Bypasses traditional ingredient distributors to capture margin and formulation influence with mid-sized commercial bakeries. |
| High-Oleic Sunflower Oil Integration | Creates tailored melting profiles for laminated dough systems in artisanal biscuit segments. |
| Crystallization Equipment Refurbishment Program | Extends asset lifecycles for enzymatic processing lines through Southeast Asian OEM technical partnerships. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving lipid crystallization engineers, commercial bakery procurement directors, specialty fat R&D leads, and palm oil trading desk analysts. Bottom-up volume modeling triangulated against top-down value estimates derived from SEC disclosures and industry production surveys. FDA trans fat enforcement timelines, EFSA Farm to Fork strategy implementation schedules, and FAO oilseed price indices supplied critical secondary validation layers.
Segmentation granularity operated at product type, application, and packaging format levels across the projection horizon, with enzymatic versus hydrogenated processing technology as an additional modeled dimension. CAGRs emerged from logistic adoption curves fitted to regulatory phase-out schedules and bakery reformulation timelines. Feedstock price volatility scenarios and alternative oil crop yield projections informed sensitivity boundaries.
The model assumes a particular technology adoption path; alternative pathways for shea butter fractionation at commercial scale would alter the outlook for premium clean-label supply security. Forecasts embed assumptions regarding palm oil policy stability in Indonesia and Malaysia, enzymatic catalyst cost trajectories, and FDA enforcement consistency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
South America Food Additives Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Mexico Food Additives Market