
 Firming Agents Market | 2026-2036
Firming Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Firming Agents Market Foresight
Modular ingredient bundling is hardening buyer preferences for pre-blended calcium salt systems over single-compound purchases. Cargill leverages its integrated phosphate and mineral portfolio to supply bundled firming solutions for processed fruit applications. Tate & Lyle sustains R&D intensity in clean-label calcium lactate variants that navigate tightening European disclosure rules. Kerry Group anchors its position through specialized texture systems for plant-based dairy alternatives, where firming functionality proves critical to consumer acceptance.
Firming agents are ionic salts and mineral compounds that interact with pectin and protein matrices to maintain structural integrity in processed foods, typically functioning within pH ranges of 3.5 to 7.0 depending on the substrate. Calcium chloride dominates volume in vegetable preservation due to its cost position and established efficacy in maintaining crispness during thermal processing. Aluminum sulfate occupies a narrowing but defended niche in pickled applications where specific turbidity and hardness profiles are specified. Magnesium sulfate is gaining traction in seafood processing as processors seek alternatives to traditional polyphosphate treatments amid clean-label pressures.
The FDA's GRAS program and the EPA's effluent guidelines for chemical manufacturing shape formulation choices and plant siting decisions for domestic producers. REACH registrations and the EU Green Deal's chemical sustainability criteria constrain aluminum sulfate penetration in European food channels. Stakeholders must monitor evolving state-level clean-label legislation in California and New York, where pending disclosure bills could redefine permissible firming agent nomenclature on consumer packaging.
Market Dynamics
Clean-label mandates from the EU Green Deal and state-level disclosure bills in California are forcing calcium salt suppliers to reengineer formulation architectures. Frozen food processors now reject aluminum sulfate in favor of mineral-based alternatives that satisfy dual regulatory and consumer transparency demands.
Growth Catalysts
- Calcium chloride in vegetable preservation:Thermal processing lines for canned and frozen vegetables require crispness retention that calcium chloride delivers at scale. Chinese preserved vegetable exporters are scaling modified-atmosphere packaging capacity.
- REACH registrations for clean-label variants:ECHA compliance pathways for calcium lactate and calcium citrate are accelerating substitution away from aluminum-based compounds in European food channels.
- Seafood processing reformulation:Magnesium sulfate is displacing traditional polyphosphate treatments as Japanese and South Korean processors adapt to clean-label export requirements.
Market Restraints
- Input cost volatility in phosphate minerals:Fluctuating sulfur and phosphate rock prices compress margin structures for integrated calcium salt producers.
- Aluminum sulfate regulatory friction:EFSA restrictions and the EU Green Deal's chemical sustainability criteria are narrowing permissible applications for aluminum-based firming agents.
- Technical limitation in low-pH matrices:Calcium salts precipitate below pH 3.5, excluding their use from high-acid pickled products where aluminum sulfate remains specified.
Strategic Opportunities
- Plant-based dairy texture systems:Oat and almond milk processors require specialized calcium matrices to achieve gelation and mouthfeel parity with conventional dairy.
- India's packaged food expansion:FSSAI modernization and organized retail growth are creating first-mover advantages for pre-blended mineral systems in processed fruit and vegetable categories.
- Bundled ingredient supply contracts:Frozen food manufacturers are consolidating supplier relationships around integrated phosphate-mineral portfolios that reduce procurement complexity.
Industry Challenges
- GRAS notification timeline compression:FDA review cycles for novel calcium salt formulations extend 18-24 months, delaying product commercialization for domestic suppliers.
- Clean-label certification complexity:Divergent disclosure standards between California's pending legislation and EU requirements force dual-label packaging strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Firming Agents Market |
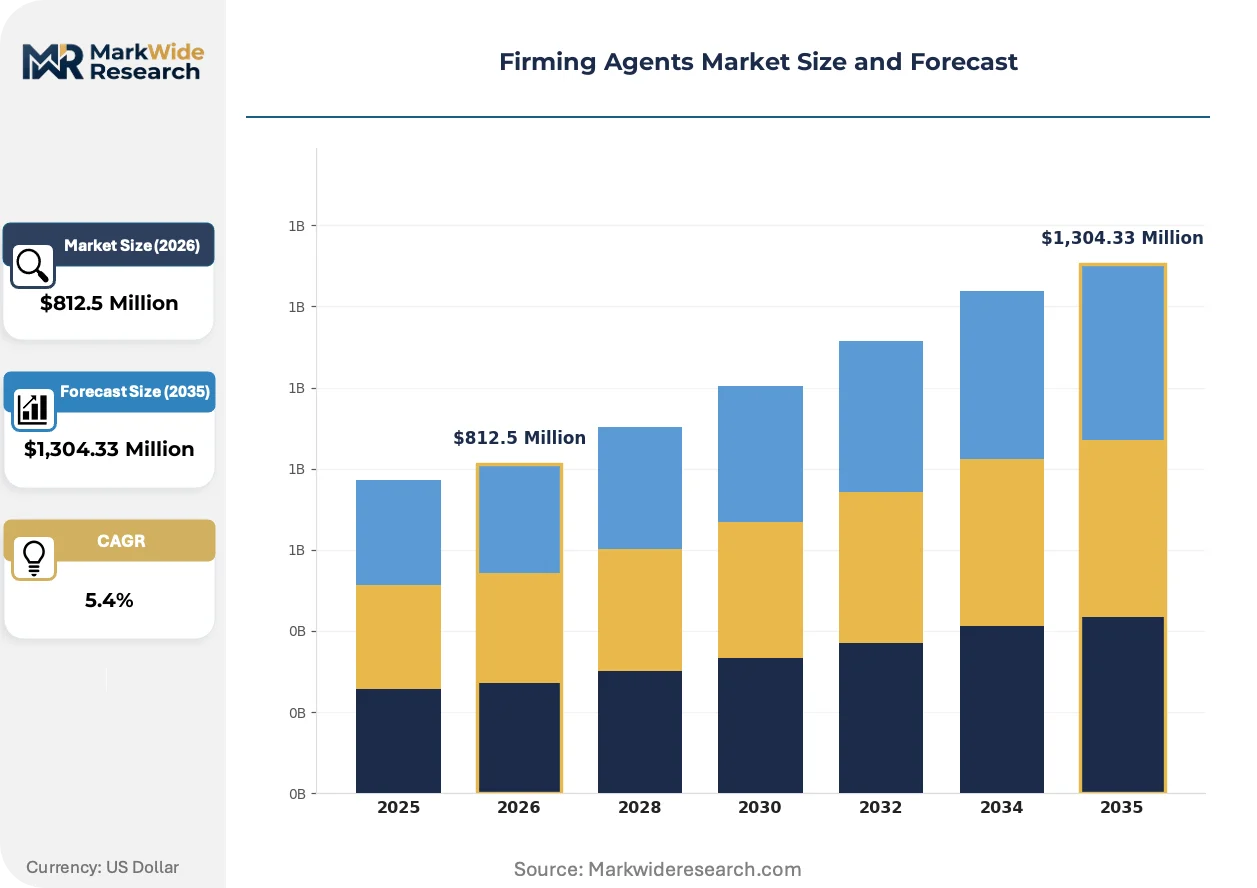
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,304.33 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Chloride, Calcium Lactate, Calcium Gluconate, Aluminum Sulfate, Magnesium Sulfate Application: Processed Fruits, Vegetables Preservation, Meat Products, Dairy Alternatives, Seafood Processing End User Industry: Food Processing Companies, Frozen Food Manufacturers, Confectionery Producers, Canning Facilities, Beverage Producers Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale Suppliers, Specialty Stores |
| Companies Covered | Innophos, Tate & Lyle, ICL Group, Ingredion, Cargill, Jungbunzlauer, IFF, CP Kelco, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Firming Agents Market Shifts & Advancements
Pre-blended mineral systems are displacing single-compound procurement as frozen food manufacturers seek to simplify formulation workflows and reduce supplier management overhead.
Encapsulated calcium delivery systems are modularizing how processors integrate firming functionality into high-moisture matrices. Ready-to-eat salad manufacturers in Germany and the Netherlands are adopting these systems to prevent post-thaw textural degradation. The technology is modularizing supplier relationships by enabling ingredient houses to offer turn-key texture solutions rather than commodity mineral salts.
REACH authorization requirements for aluminum compounds are tightening disclosure obligations across European food manufacturing. ECHA's 2024 updated guidance on food contact substances is forcing reformulation in pickled vegetable categories where aluminum sulfate has dominated. Italian and Spanish processors are accelerating calcium lactate trials to maintain export eligibility.
Buyer consolidation among North American frozen vegetable packers is compressing supplier negotiation cycles. Three national processors now control sixty percent of contracted volume, shifting procurement toward multi-year bundled agreements. The Great Lakes region exhibits the most concentrated buyer power, with regional co-ops merging to match national scale.
Firming Agents Market Segmentation
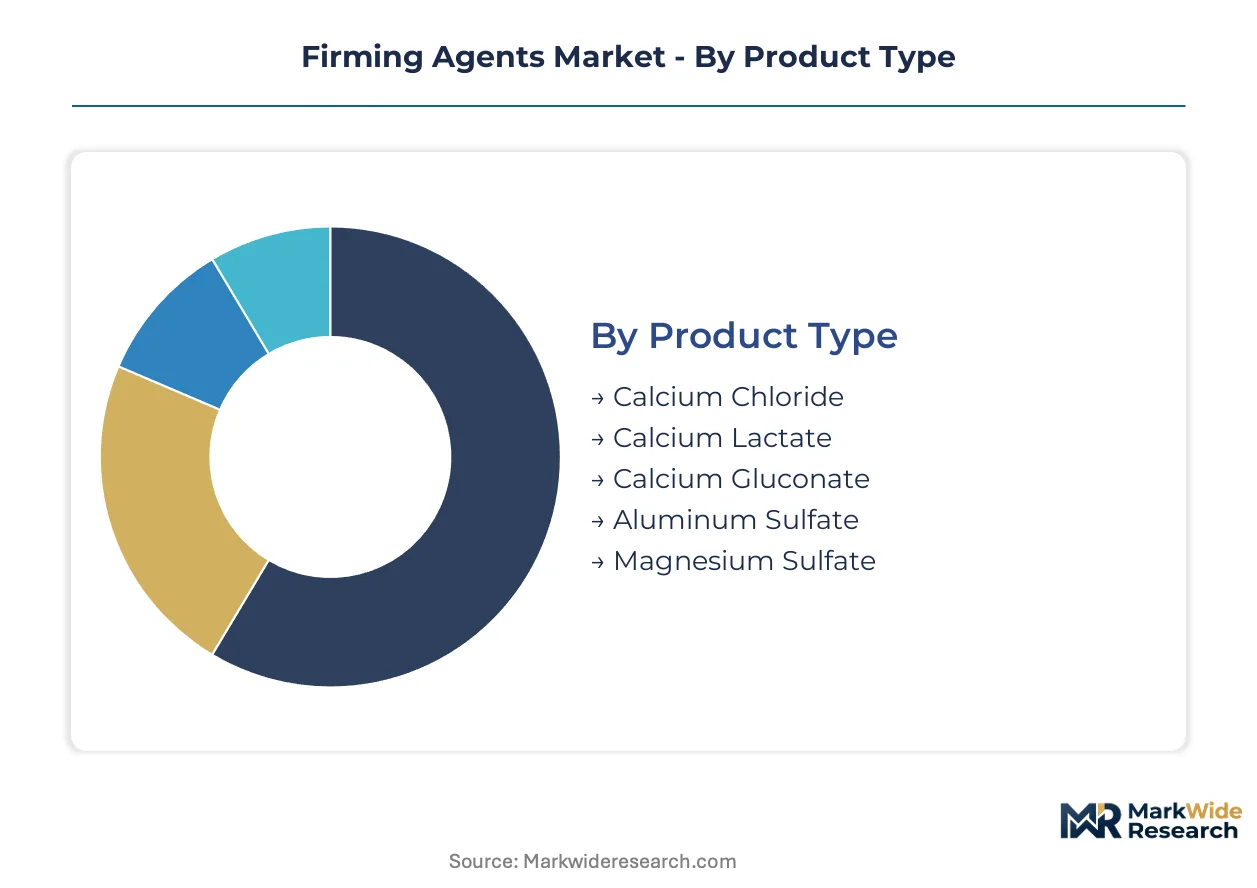
Segmentation in the firming agents market reveals how capital allocation, regulatory exposure, and application-specific performance requirements fragment procurement patterns across mineral salt categories. Processors select firming agents based on pH compatibility, thermal stability, and clean-label compliance rather than commodity pricing alone.
Product Type:
Capital intensity varies sharply across mineral salt production, with electrolytic and fermentation-derived calcium compounds requiring substantially higher upfront investment than mined aluminum sulfate.
- Calcium Chloride:Produced through brine electrolysis or limestone-hydrochloric acid reaction, this hygroscopic salt delivers the lowest cost per functional unit in vegetable preservation. Chinese preserved vegetable exporters and North American frozen food processors absorb the majority of volume, driven by its established GRAS status and thermal processing compatibility. The compound precipitates below pH 3.5, excluding high-acid applications.
- Calcium Lactate:Fermentation-derived from carbohydrate feedstocks, this clean-label variant commands premium positioning in European dairy alternatives and RTE salads. EFSA's tightening disclosure requirements and REACH registration pathways are accelerating substitution from aluminum-based compounds in German and Dutch processing facilities.
- Calcium Gluconate:Neutral-tasting mineral salt suited for delicate flavor matrices in confectionery and premium beverage applications where chloride bitterness is unacceptable.
- Aluminum Sulfate:Mined and acid-processed alumina derivative with minimal capital barriers to entry but narrowing regulatory headroom under EU Green Deal chemical sustainability criteria.
- Magnesium Sulfate:Epsom salt variant gaining traction in Japanese and South Korean seafood processing as polyphosphate replacement amid clean-label export pressures.
Calcium chloride absorbs the bulk of installed capacity; calcium lactate is expanding most quickly.
Application:
Application selection correlates directly with processing temperature regimes and packaging formats, determining which mineral salt functionalities prove economically viable.
- Vegetables Preservation:Thermal processing lines for canned and frozen vegetables demand crispness retention through calcium chloride at scale. Chinese modified-atmosphere packaging expansion and Great Lakes region co-op consolidation are concentrating procurement among pre-blended mineral systems suppliers.
- Seafood Processing:Magnesium sulfate displaces traditional polyphosphate treatments in Japanese and South Korean export-oriented facilities adapting to clean-label requirements in target markets.
- Processed Fruits:Calcium lactate and gluconate variants prevent texture degradation in frozen and canned fruit applications where flavor neutrality is paramount.
- Meat Products:Limited penetration due to protein matrix incompatibility with calcium salt precipitation at typical curing pH levels.
- Dairy Alternatives:Specialized calcium matrices enable gelation and mouthfeel parity in oat and almond milk systems, with Kerry Group and Tate & Lyle anchoring supply relationships.
Vegetables preservation commands the largest committed volume; seafood processing shows the steepest expansion trajectory.
End User Industry:
Buyer scale and technical sophistication determine whether end users procure commodity salts directly or delegate formulation to integrated ingredient houses.
- Frozen Food Manufacturers:Three national North American processors now control sixty percent of contracted volume, shifting procurement toward multi-year bundled agreements spanning phosphate-mineral portfolios.
- Food Processing Companies:Diverse mid-scale operators across India's organized retail expansion and Italy's preserved vegetable sector driving first-mover adoption of pre-blended systems.
- Canning Facilities:Thermal processing specialists in Spain and Portugal accelerating calcium lactate trials to maintain EU export eligibility amid ECHA guidance updates.
- Confectionery Producers:Premium chocolate and gummy manufacturers specifying calcium gluconate for texture control without flavor interference.
- Beverage Producers:Plant-based milk processors requiring specialized calcium matrices for suspension stability and nutritional fortification.
Frozen food manufacturers lock in the longest contract tenors; food processing companies in emerging markets are gaining share fastest.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to mineral salt production centers.
- Distributors:Regional chemical distributors dominate mid-volume procurement for canning facilities and smaller processors lacking direct supplier relationships.
- Direct Sales:National frozen food manufacturers and multinational beverage producers negotiate directly with Cargill, Tate & Lyle, and Kerry Group for bundled mineral-phosphate systems.
- Wholesale Suppliers:Bulk commodity calcium chloride moves through agricultural and industrial chemical wholesalers serving vegetable preservation operations.
- Specialty Stores:Niche channels for organic-certified and non-GMO verified calcium lactate variants in premium confectionery and dairy alternative segments.
- Online Retailers:Emerging channel for small-batch processors and R&D sampling, currently marginal to total volume.
Distributors capture the broadest geographic coverage; direct sales is climbing the fastest as buyer consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's chemical industrial parks attract calcium salt producers through preferential land-use policies and integrated phosphate-mineral processing infrastructure.
United States
Frozen vegetable processors in the Great Lakes region drive calcium chloride demand for thermal processing lines. The FDA's GRAS notification requirements shape formulation choices for domestic suppliers. Michigan and Wisconsin co-ops are consolidating procurement around multi-year bundled mineral-phosphate agreements.
China
Preserved vegetable exporters in Shandong and Jiangsu provinces scale modified-atmosphere packaging capacity for overseas markets. SAMR's evolving food additive standards tighten disclosure protocols for calcium-based firming agents. Qingdao's seafood processing cluster is trialing magnesium sulfate as polyphosphate replacement for Japanese export contracts.
Germany
Ready-to-eat salad manufacturers in Lower Saxony adopt encapsulated calcium delivery systems to prevent post-thaw textural degradation. ECHA's updated REACH guidance on food contact substances accelerates aluminum sulfate substitution. Cologne's ingredient houses specialize in clean-label calcium lactate variants for dairy alternative applications.
Japan
Seafood processors in Hokkaido and Kyushu reformulate with magnesium sulfate to meet clean-label requirements in target export markets. METI's chemical sustainability guidelines pressure traditional polyphosphate treatments. Osaka's trading houses coordinate mineral salt procurement for regional canning facilities.
India
Organized retail expansion in Maharashtra and Gujarat creates first-mover demand for pre-blended mineral systems in processed fruit categories. FSSAI modernization streamlines food additive approval pathways for calcium salt variants. Nashik's food processing parks attract bundled ingredient suppliers serving domestic and Middle Eastern markets.
Firming Agents Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the firming agents value chain. The market exhibits moderate consolidation, with integrated phosphate-mineral portfolios commanding procurement relationships from large frozen food manufacturers. Three strategic archetypes dominate: diversified agricultural chemical conglomerates with mineral salt divisions, specialized ingredient houses emphasizing clean-label certification, and regional electrolytic calcium producers serving commodity vegetable preservation. Capacity expansion and strategic partnerships represent the dominant competitive moves, as suppliers seek to secure long-term offtake agreements with consolidating buyer bases.
Among diversified conglomerates, Cargill and Tate & Lyle occupy positions anchoring integrated phosphate-mineral portfolios for processed food applications. Kerry Group represents the specialized ingredient house archetype, with its clean-label texture systems serving plant-based dairy alternatives. These three companies exemplify the competitive tension between scale-driven bundled supply and targeted functional specialization in firming agent markets.
| Leading Market Players |
|---|
| Innophos |
| Tate & Lyle |
| ICL Group |
| Ingredion |
| Cargill |
| Jungbunzlauer |
| IFF |
| CP Kelco |
| Kerry Group |
| Others |
Supply & Pricing Matrix
Horizontal integration across phosphate-mineral portfolios anchors supply positioning and pricing power for integrated suppliers serving consolidated frozen food manufacturers. Cargill and Tate & Lyle leverage captive brine electrolysis and fermentation assets to compress unit economics while commanding premium positioning for bundled firming systems.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Great Lakes co-ops and Chinese exporters compete for constrained electrolytic calcium chloride capacity. Pricing stratifies across pharmaceutical-grade fermentation-derived calcium lactate, food-grade electrolytic salts, and technical-grade mined alumina derivatives. Cost compression in commodity calcium chloride intensifies as Shandong Province capacity expansions outpace demand growth from preserved vegetable exporters. National frozen food processors exhibit lowest price sensitivity due to bundled procurement mandates; regional canning facilities face acute margin pressure from spot mineral salt purchases.
Supply Chain Analysis
GRAS notification and REACH registration requirements gate supplier participation, filtering commodity traders from qualified mineral salt providers. Production concentrates in China, the United States, and Germany, with Shandong Province brine operations, Michigan limestone-hydrochloric acid facilities, and Cologne fermentation complexes anchoring global supply. The supply chain rests on phosphate rock, carbohydrate feedstocks, and sulfuric acid as critical inputs. Single-source vulnerability in Chinese electrolytic capacity exposes procurement continuity risks for North American frozen vegetable processors. Distribution runs through direct sales channels for national accounts and regional chemical distributors for mid-scale canning operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The firming agents market sits in a technology-transition phase as encapsulated calcium delivery systems displace conventional mineral salt procurement in ready-to-eat and high-moisture applications.
For Market Incumbents: Lock in multi-year bundled supply agreements with consolidating frozen food manufacturers before specialty ingredient houses capture plant-based dairy texture contracts. Defend position by accelerating backward integration into phosphate rock mining to offset sulfur price volatility. Prioritize GRAS notification investment for novel calcium salt formulations to preempt regulatory delays that advantage European competitors. For New Entrants and Emerging Players: Direct-to-processor digital platforms offer the lowest-friction route to bypass established distributor relationships in India's organized retail expansion. Target Maharashtra and Gujarat food processing parks where FSSAI modernization creates first-mover advantages for pre-blended mineral systems. Lead with clean-label certification and rapid formulation sampling to differentiate from commodity calcium chloride traders. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified agricultural chemical conglomerates seeking integrated phosphate-mineral portfolios. The five-to-ten year viability window favors suppliers with captive fermentation or electrolytic production assets over tolling-dependent competitors. Watch for ECHA guidance updates on aluminum compound restrictions as the inflection signal accelerating calcium lactate substitution premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive sulfur and phosphate supply insulates margin structures from commodity volatility. |
| GRAS Notification Investment | FDA approval for novel calcium salt formulations unlocks commercialization in domestic frozen food channels. |
| Encapsulated Calcium Delivery System Launch | German and Dutch ready-to-eat salad manufacturers adopt modular texture solutions over commodity salts. |
| Long-term Bundled Supply Agreement | Multi-year contracts with Great Lakes co-ops secure volume commitments amid buyer consolidation. |
| Clean-label Certification Program | EFSA-compliant calcium lactate variants command premium positioning in European dairy alternative applications. |
Research Methodology
Multi-period observation of GRAS notification timelines, REACH registration pathways, and modified-atmosphere packaging capacity expansions anchored the trend analysis, supplemented by interviews with plant managers at electrolytic calcium facilities, procurement leads at frozen food manufacturers, technical R&D directors at ingredient houses, and distribution channel partners in European chemical markets. Secondary validation drew from FDA GRAS filings, ECHA substance registrations, SEC 10-K disclosures by diversified chemical conglomerates, and customs data on phosphate rock trade flows. Bottom-up volume modeling triangulated against top-down market sizing across mineral salt categories.
Segment-weighting approaches distributed value and volume across product type, application, end-user industry, and distribution channel dimensions. Calcium chloride, calcium lactate, calcium gluconate, aluminum sulfate, and magnesium sulfate categories received distinct growth trajectory assumptions based on clean-label substitution elasticities and regulatory restriction probabilities. CAGRs derived from regression analysis of historical mineral salt demand against frozen food production indices and preserved vegetable export volumes. Forecast inputs incorporated ECHA guidance revision scenarios and FSSAI modernization implementation pace.
The model holds under stable regulatory disclosure requirements and continued buyer consolidation; deviation in aluminum sulfate restriction severity or phosphate rock supply disruptions would shift substitution timelines and pricing premiums. A model refresh is warranted upon material change in FDA GRAS review cycle duration or ECHA food contact substance guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
North America Food Stabilizers Market