
 Africa Food Preservatives Market | 2026-2036
Africa Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Preservatives Market Outlook
Food chemist and formulation specialist availability is bifurcating the competitive landscape between multinational suppliers and local blenders. Cargill leverages its pan-African supply infrastructure to sustain bulk antioxidant distribution. Kerry Group anchors technical service capabilities in key processing hubs. BASF competes through synthetic preservative specialization for beverage applications.
Food preservatives encompass chemical substances and natural extracts added to food matrices to inhibit microbial proliferation, oxidative rancidity, and enzymatic degradation, typically dosed between 0.01% and 0.1% by weight depending on matrix pH and water activity. Their primary commercial purpose extends shelf-stable distribution across tropical climates with limited cold-chain reach. Synthetic preservatives dominate volume shipments due to cost efficiency in mass-market canned foods and beverages. Natural preservatives exhibit the fastest trajectory as bakery and dairy manufacturers reformulate for clean-label positioning. Margin pools concentrate in antioxidant blends for edible oils, where oxidation control commands technical premiums.
Nigeria's National Agency for Food and Drug Administration and Control, South Africa's Department of Health, and Egypt's Egyptian Organization for Standardization and Quality each enforce additive maximum residue limits and labeling mandates that determine product registration timelines. These frameworks elevate compliance costs for imported formulations while creating pathways for locally manufactured alternatives that secure faster domestic approvals. Stakeholders must monitor harmonization progress across the African Continental Free Trade Area for mutual recognition of preservative safety dossiers.
Market Dynamics
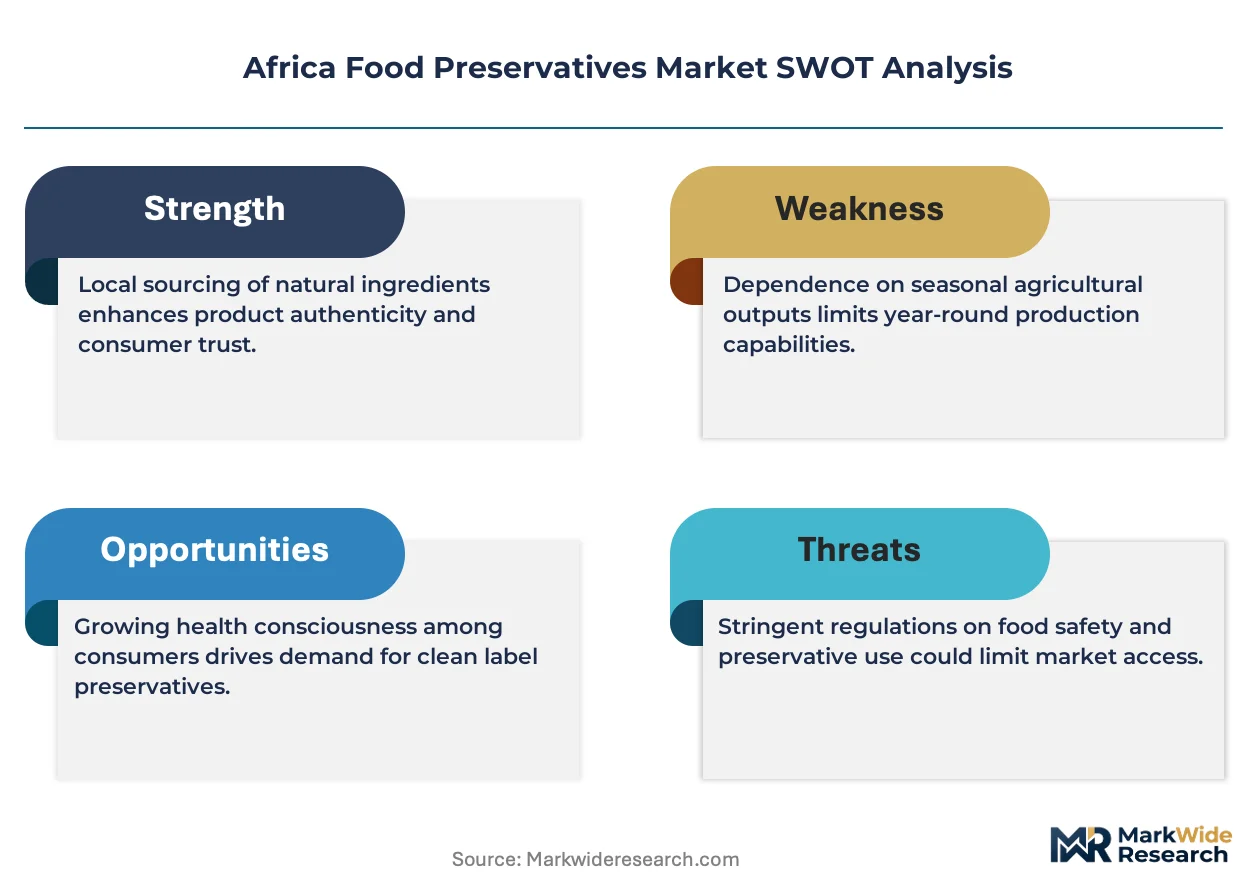
The Africa Food Preservatives Market is being fundamentally reshaped by the tension between FSSAI-aligned safety tightening in Nigeria and South Africa and the persistent cold-chain gaps that force processors toward higher-dose chemical preservation. This regulatory-compression-against-infrastructure reality is splitting formulation strategies across the continent.
Growth Catalysts
- Processed Dairy Expansion:Urban processing clusters in Nigeria, Egypt, and South Africa are pulling antioxidant and antimicrobial demand upward as UHT milk and yogurt production scales.
- NAFDAC Harmonization Pressure:Nigeria's alignment with FSSAI protocols is accelerating registration pathways for locally manufactured preservative blends that bypass import dossier complexity.
- Edible Oil Oxidation Control:Tropical storage conditions without refrigeration infrastructure are mandating technical-premium antioxidant deployment across West African palm oil processors.
Market Restraints
- Synthetic Input Cost Volatility:Petrochemical feedstock fluctuations directly compress margins for benzoate and sorbate manufacturers serving mass-market beverage canners.
- Import Concentration Risk:Bulk antioxidant shipments remain dominated by pan-African distributor networks with single-point-of-failure exposure at Mombasa and Lagos ports.
- Clean-Label Technical Ceiling:Natural rosemary extract and nisin alternatives face stability limitations in high-water-activity matrices that synthetic preservatives handle reliably.
Strategic Opportunities
- AfCFTA Mutual Recognition:Harmonized preservative safety dossier protocols across the African Continental Free Trade Area promise to slash multi-country registration costs for compliant blenders.
- Bakery Clean-Label Reformulation:Egyptian and Moroccan flatbread manufacturers present underpenetrated demand for cultured wheat starch and fermented flour preservatives that satisfy label-conscious urban consumers.
- Direct Processor Technical Service:Bypassing traditional distributor layers through in-plant formulation support captures margin pools currently held by Lagos and Cairo trading houses.
Industry Challenges
- Food Chemist Scarcity:Formulation specialists capable of pH-water-activity matrix optimization remain concentrated in Johannesburg and Cairo, constraining regional blender technical capabilities.
- Multi-Regulator Compliance Burden:Separate Egyptian Organization for Standardization and Quality, NAFDAC, and South African Department of Health approval timelines fragment product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Preservatives Market |
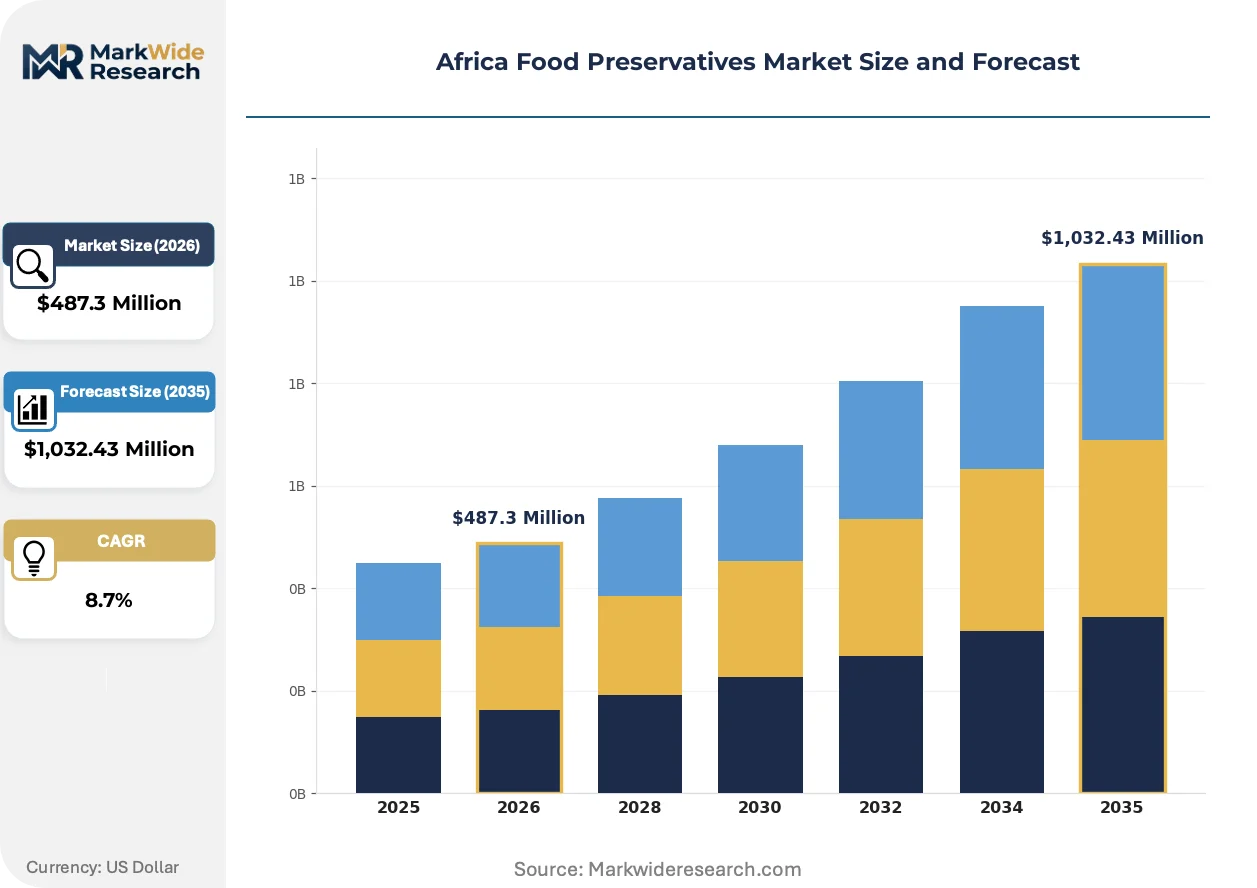
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Preservatives, Natural Preservatives, Synthetic Preservatives, Antioxidants Application: Canned Foods, Bakery Products, Dairy Products, Beverages Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale End User: Food Manufacturers, Restaurants, Retailers, Home Consumers |
| Companies Covered | Cargill, Kerry Group, Archer Daniels Midland Company, DuPont, Tate & Lyle, Koninklijke DSM, BASF, Kemin Industries, Jungbunzlauer, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Preservatives Market Strategic Shifts
Preservation technology across Africa is splitting between synthetic cost efficiency and natural positioning, with regulatory pressure and channel access determining which trajectory dominates in each national market.
Encapsulated antioxidant delivery systems are bifurcating the technical-service competitive landscape. These lipid-shell and cyclodextrin carriers protect sensitive natural extracts from thermal degradation during West African transport. Nigerian dairy processors are adopting them at pilot scale to replace synthetic BHA in premium yogurt lines. The technology is bifurcating margin pools between multinational suppliers with patented encapsulation IP and local blenders forced into royalty-bearing licensing arrangements.
Egypt's EOSQ implementation of FSSAI-aligned maximum residue limits is compressing import registration timelines for Asian preservative suppliers while creating accelerated domestic approval pathways for local manufacturers. Industrial consequence includes a shift toward Egyptian-sourced potassium sorbate in Cairo beverage production. North African canners are responding by dual-sourcing from domestic and Indian suppliers to hedge against single-origin compliance failures.
Urban supermarket procurement consolidation is displacing traditional open-market preservant purchasing in Lagos and Johannesburg. Retailer private-label dairy and bakery lines now specify preservative blends with full traceability documentation that informal channel suppliers cannot provide. This channel rotation is most visible in South Africa, where Shoprite and Pick n Pay technical specifications are becoming de facto national standards for antioxidant and antimicrobial dosing protocols.
Africa Food Preservatives Market Segmentation
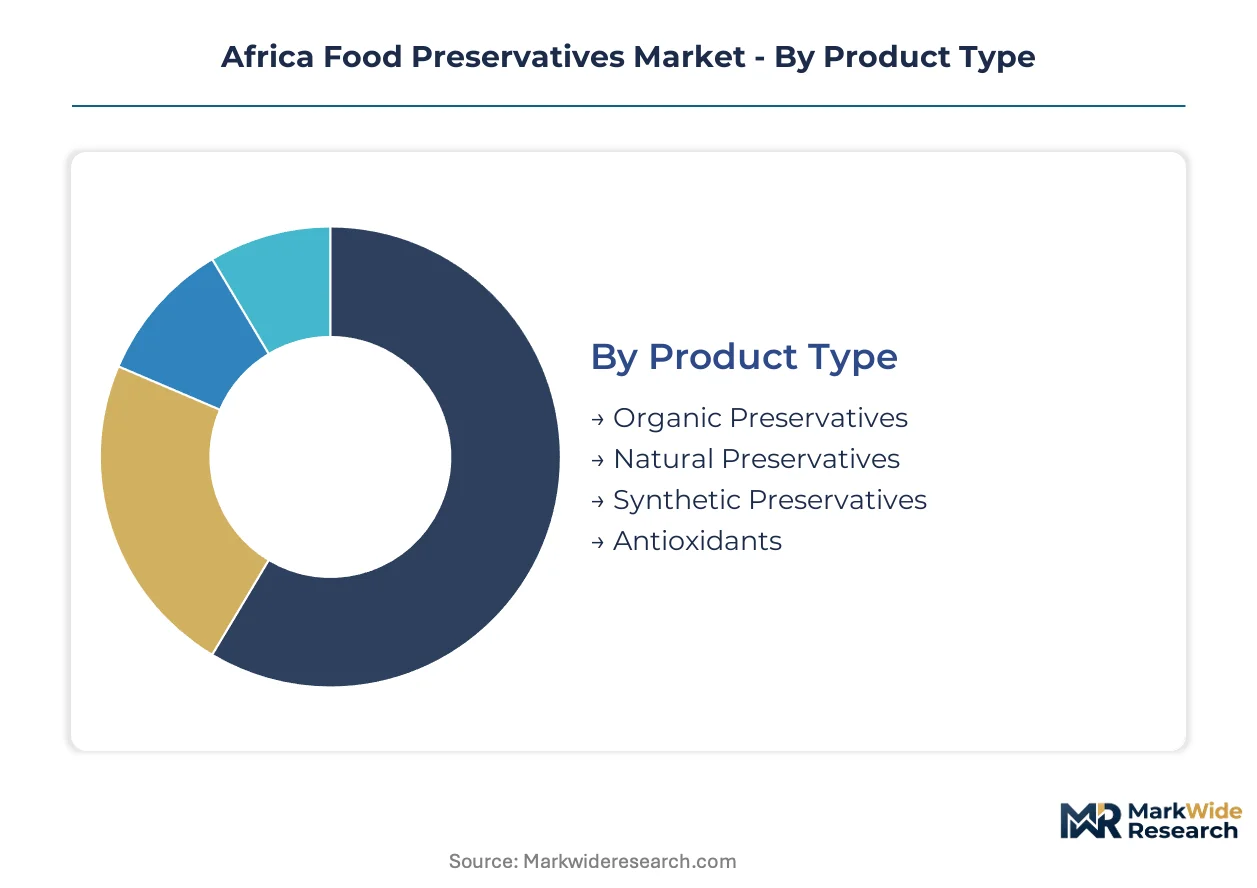
Preservative formulation strategies diverge sharply across Africa depending on end-use thermal processing requirements and channel cold-chain reliability. Segmentation reveals where technical premiums concentrate versus where commodity pricing dominates procurement decisions.
Product Type:
Margin pools concentrate in antioxidant blends for edible oils, where tropical storage conditions without refrigeration infrastructure command formulation expertise premiums.
- Antioxidants:Tocopherol and BHA/BHT blends prevent lipid oxidation in West African palm oil processors operating without climate-controlled warehousing. Nigerian and Ghanaian edible oil refiners absorb technical premiums for encapsulated delivery systems that survive ambient transport temperatures.
- Natural Preservatives:Rosemary extract, nisin, and cultured dextrose formulations serve clean-label bakery and dairy lines in South African supermarket private-label programs. Stability limitations in high-water-activity matrices constrain penetration beyond premium price tiers.
- Synthetic Preservatives:Benzoates and sorbates dominate mass-market beverage canning through cost-efficient microbial inhibition at pH ranges below 4.5.
- Organic Preservatives:Certified organic acids and botanical extracts target export-oriented processors serving European retail compliance requirements.
Antioxidants hold installed capacity. Natural preservatives are rotating up the share rankings.
Application:
Volume concentrates in beverage canning, but value per kilogram peaks in dairy where UHT processing demands precise antimicrobial dosing.
- Dairy Products:UHT milk and yogurt production in Nigeria, Egypt, and South Africa requires nisin and potassium sorbate blends that survive ultra-high temperature processing without thermal degradation. Urban processing clusters pull antioxidant demand upward as production scales.
- Beverages:Carbonated soft drink and juice canners across West Africa deploy benzoate-sorbate combinations for shelf-stable distribution through informal retail channels lacking refrigeration.
- Bakery Products:Egyptian and Moroccan flatbread manufacturers present reformulation opportunities for cultured wheat starch preservatives that satisfy label-conscious urban consumers.
- Canned Foods:Thermal processing reduces preservative dependency, though acidified vegetable canners in North Africa maintain sorbate dosing for secondary spoilage control.
Dairy applications command formulation premiums. Bakery is climbing fastest on clean-label reformulation.
Distribution Channel:
Channel selection determines documentation requirements and batch traceability standards that segment supplier capabilities.
- Wholesale:Bulk antioxidant shipments through Lagos and Mombasa port distributors serve informal processing sectors with minimal specification documentation.
- Supermarkets:Shoprite and Pick n Pay procurement consolidation in South Africa enforces full preservative traceability documentation that informal channel suppliers cannot provide.
- Convenience Stores:Small-format retail in Nigerian urban corridors sources pre-blended antimicrobial packs through local trading houses.
- Online Retail:E-commerce penetration remains nascent for industrial preservative procurement, though specialty natural extracts reach artisanal food producers through platform distribution.
Wholesale holds volume dominance. Supermarkets are rotating up the specification authority rankings.
End User:
Technical service intensity varies dramatically between industrial formulators requiring in-plant support versus retail channels accepting standard blends.
- Food Manufacturers:Industrial dairy and oil processors in Cairo and Johannesburg demand direct technical service for pH-water-activity matrix optimization, bypassing traditional distributor layers.
- Restaurants:Quick-service chains and catering operations source pre-mixed antimicrobial solutions for centralized kitchen operations.
- Retailers:Supermarket private-label programs specify preservative systems with full batch documentation and third-party certification.
- Home Consumers:Direct-to-consumer preservative sales remain negligible outside artisanal food producer segments.
Food manufacturers hold technical complexity requirements. Retailers are rotating up the compliance specification rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria, Egypt, and South Africa consume food preservatives through divergent matrices: West African processors favor synthetic antimicrobials for ambient beverage distribution, North African dairies deploy antioxidant blends for UHT stability, while South African supermarket chains drive clean-label natural extract procurement.
Nigeria
Lagos and Kano food processors pull benzoate and sorbate volumes upward for carbonated soft drink canning serving informal retail channels. NAFDAC's FSSAI-aligned additive registration protocols compress timelines for locally manufactured preservative blends. The Ogun State dairy cluster near Lagos is scaling UHT milk production and importing encapsulated antioxidant systems for premium yogurt lines.
Egypt
Cairo beverage manufacturers absorb potassium sorbate shipments for acidified juice shelf-stability under tropical storage conditions. The Egyptian Organization for Standardization and Quality enforces maximum residue limits that accelerate domestic approval pathways for local preservative manufacturers. Alexandria's edible oil refiners deploy technical-premium tocopherol blends to control palm oil oxidation in unconditioned warehouses.
South Africa
Johannesburg and Cape Town supermarket procurement consolidation drives demand for traceable natural preservative systems in private-label dairy and bakery lines. The Department of Health enforces additive labeling mandates that elevate compliance documentation requirements for imported formulations. The Gauteng dairy processing corridor is adopting nisin and cultured dextrose blends to replace synthetic sorbates in premium yogurt positioning.
Ghana
Tema port distributors serve Accra beverage canners with bulk benzoate shipments for mass-market juice production. The country's national food safety regulator maintains additive approval pathways that favor dossier-complete imports from established pan-African suppliers. The Kumasi food processing zone is piloting rosemary extract preservatives for export-oriented cocoa butter applications.
Kenya
Nairobi dairy processors deploy sorbate-nisin combinations for UHT milk distribution through supermarket channels lacking cold-chain reliability. The national standards body enforces preservative maximum limits aligned with Codex Alimentarius frameworks. Mombasa port handling concentration creates single-point-of-failure exposure for bulk antioxidant shipments serving East African edible oil refiners.
Africa Food Preservatives Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Africa's food preservative supply structure. Multinational suppliers with pan-African distribution infrastructure command bulk antioxidant and synthetic antimicrobial volumes through port-based logistics networks. Regional blenders compete on registration speed and local formulation adaptation. The dominant competitive moves involve direct technical service deployment to bypass distributor margins and strategic partnerships with dairy and oil processing clusters for captive supply arrangements.
Within the integrated multinational tier, Cargill and Kerry Group anchor supply infrastructure across West and Southern African processing hubs. BASF occupies a position exemplifying synthetic preservative specialization for beverage applications. These three entities represent the competitive archetypes of logistics-anchored bulk distribution, technical service-intensive formulation support, and petrochemical-derived antimicrobial specialization respectively.
| Leading Market Players |
|---|
| Cargill |
| Kerry Group |
| Archer Daniels Midland Company |
| DuPont |
| Tate & Lyle |
| Koninklijke DSM |
| BASF |
| Kemin Industries |
| Jungbunzlauer |
| Others |
Value Chain & Pricing Dynamics
Pan-African bulk antioxidant shipments through Mombasa and Lagos ports generate scale economies that compress per-kilogram logistics costs while simultaneously elevating price floors for smaller regional blenders lacking throughput volumes. These port-concentration dynamics concentrate pricing power among integrated distributors capable of absorbing petrochemical feedstock volatility through long-term offtake contracts.
Pricing Analysis
Long-term offtake agreements dominate synthetic preservative procurement between Nigerian beverage canners and pan-African distributors, insulating volume buyers from spot-market benzoate price swings. Price differentiation rests on certification grade—FSSAI-aligned dossiers command premiums over standard-grade imports—and volume scale, with UHT dairy processors securing tiered discounts unavailable to artisanal bakery operators. Cost compression in mass-market synthetic tiers is intensifying because Lagos trading houses face margin pressure from direct technical-service deployments by multinational suppliers. Small-format convenience stores in Nigerian urban corridors exhibit highest price sensitivity, while South African supermarket private-label programs absorb technical premiums for full traceability documentation.
Supply Chain Analysis
Strategic stockpiling of tocopherol and BHA/BHT blends characterizes West African edible oil processors operating without climate-controlled warehousing, contrasting with just-in-time rosemary extract procurement by South African clean-label dairy manufacturers. Supply concentrates in India, China, and domestic Egyptian manufacturing for potassium sorbate and benzoate feedstocks. Raw material dependencies rest on petrochemical derivatives for synthetic antimicrobials and botanical cultivation cycles for natural extracts. Single-source vulnerability at Mombasa and Lagos ports creates structural risk for bulk antioxidant shipments serving East and West African refiners. Distribution runs through port-based distributor networks with technical service bypass emerging as an alternative channel for large-scale dairy and oil processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and formulation support layers are expanding faster than commodity preservative volumes as African dairy and oil processors demand in-plant pH-water-activity optimization. This service-attach dynamic elevates margin pools beyond bulk ingredient sales.
For Market Incumbents: Compound technical service capabilities through direct deployment to Nigerian and Egyptian dairy clusters, bypassing Lagos and Cairo distributor margins that currently capture formulation premiums. Invest in encapsulated antioxidant delivery system IP to defend against royalty-bearing licensing pressure from natural extract suppliers. Capacity addition in Ogun State and Alexandria secures faster NAFDAC and EOSQ registration pathways than import-dependent competitors.
For New Entrants and Emerging Players: Technical service gaps in Ghana and Kenya—where food chemist concentration lags Nigeria and South Africa—present white-space targets for formulation-specialist entrants. Egyptian flatbread manufacturers represent the most penetrable clean-label segment, with cultured wheat starch preservatives underdeployed relative to Moroccan competitors. A direct-to-processor technical partnership model, anchored by in-plant matrix optimization support, circumvents entrenched port-distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional blenders with captive supply arrangements to UHT dairy clusters, where switching costs lock in multi-year technical service contracts. Long-term viability over the projection horizon favors acquisition targets with FSSAI-aligned dossier capabilities and established EOSQ or NAFDAC registration track records. Monitor AfCFTA mutual recognition protocol implementation as the inflection indicator for multi-country registration cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Encapsulation Technology | Patented lipid-shell systems protect natural extracts from West African thermal degradation during transport. |
| Direct Technical Service Deployment | In-plant formulation support captures margin pools currently held by Lagos and Cairo trading houses. |
| AfCFTA Registration Harmonization | Mutual recognition of preservative safety dossiers slashes multi-country compliance costs for compliant blenders. |
| Clean-Label Reformulation Partnerships | Egyptian and Moroccan flatbread manufacturers present underpenetrated demand for cultured wheat starch preservatives. |
| Captive Supply Arrangements with Dairy Clusters | UHT milk processors in Ogun State and Gauteng lock in multi-year antioxidant and antimicrobial procurement contracts. |
Study Parameters
The analysis maps synthetic antimicrobial, natural extract, antioxidant blend, and organic acid sub-sectors, each validated through formulation specialists at Nigerian and Egyptian dairy processors, procurement leads at West African beverage canners, and technical directors at pan-African distributor networks. Primary interview intelligence combined with secondary validation against NAFDAC registration databases, EOSQ additive approval records, and South African Department of Health labeling mandates. Bottom-up volume triangulation from processor consumption estimates and top-down value reconciliation against customs trade data ensure cross-verified outputs.
Consistency checks validated projection outputs against external benchmarks including Codex Alimentarius framework adoption timelines and AfCFTA harmonization progress indicators. The analytical framework segments by product type, application, distribution channel, and end user across the modeling period, with CAGRs derived from regression analysis of historical consumption patterns and forward-adjusted for regulatory alignment milestones. Industry-specific forecast inputs include UHT dairy capacity expansion schedules and encapsulated delivery system adoption curves in Nigerian premium yogurt lines.
Underlying assumptions cover FSSAI-aligned regulatory convergence, petrochemical feedstock price band stability, and cold-chain infrastructure gaps persisting across the analysis window, with deviation risk concentrated in NAFDAC-EOSQ harmonization delays or synthetic input cost spikes. Revision becomes warranted when AfCFTA mutual recognition protocol implementation crosses enforcement thresholds or when encapsulated natural extract stability breakthroughs displace synthetic antioxidant demand in high-water-activity matrices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Middle East and Africa Food Starch Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
South America Food Additives Market
Food Additives and Ingredients
Olestra Market