
 Germany Organic Food Market | 2026-2036
Germany Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Organic Food Market Insights
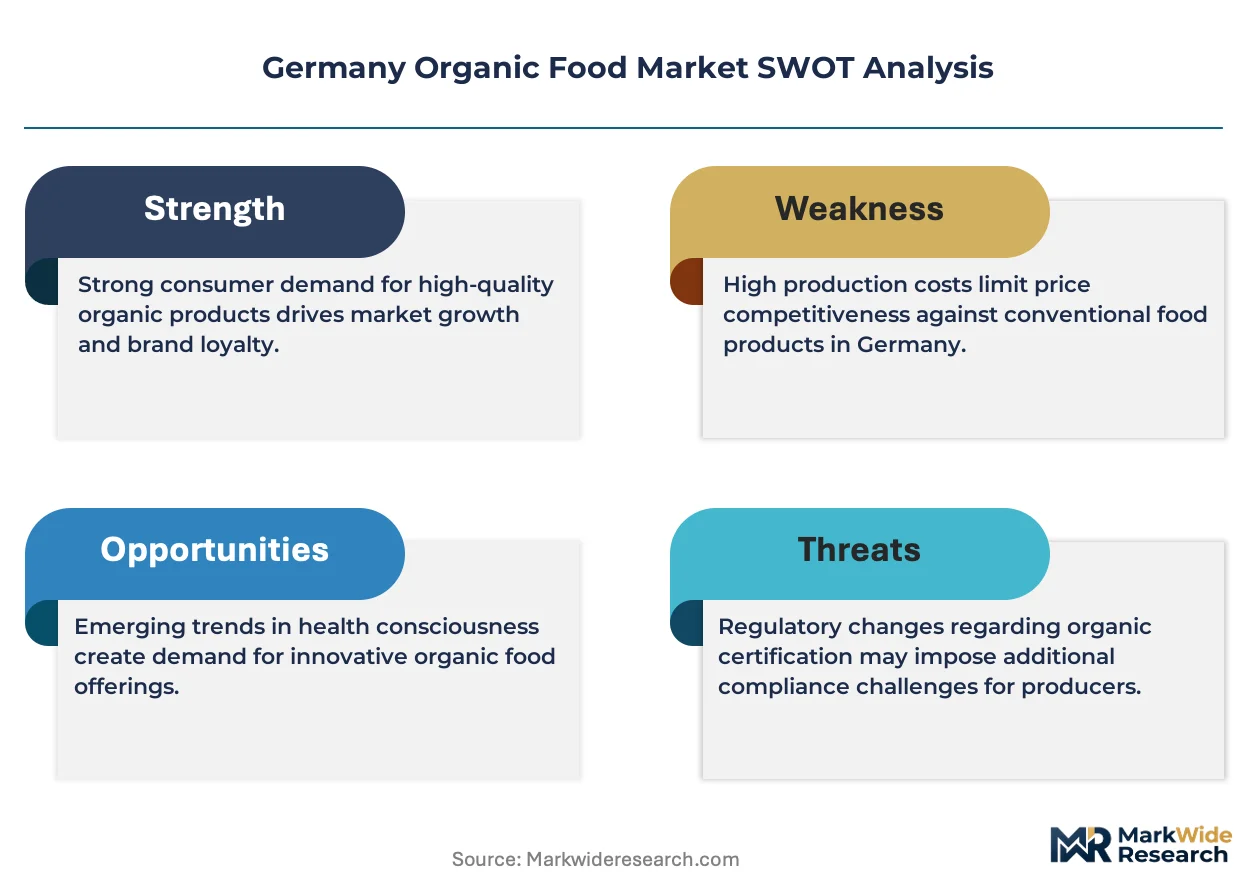
Premium organic certification is shifting away from conventional private-label positioning as German retailers pursue distinct tier strategies. EDEKA leverages its regional cooperative structure to sustain localized organic sourcing across northern Germany. Alnatura differentiates through dedicated shelf-space partnerships and vertical control over its processing network. Lidl competes aggressively on price-point entry SKUs while occupying the mass-market organic segment with streamlined assortments.
Organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, meeting EU Regulation 2018/848 standards for production, labeling, and control. The primary commercial purpose centers on delivering verified environmental and health attributes to consumers willing to pay certification premiums. Dairy products and fresh produce dominate volume flows through supermarkets, where REWE and EDEKA control the principal retail infrastructure. Specialty stores capture margin-rich consumer segments seeking artisanal provenance and direct farm transparency. Online retail channels are expanding fastest among millennial households in urban clusters, though last-mile cold-chain costs constrain rural penetration depth.
The Federal Ministry of Food and Agriculture enforces the German national organic seal, while EU Regulation 2018/848 harmonizes cross-border certification and inspection protocols. KBA-aligned transport emissions standards and the EU Green Deal's Farm to Fork strategy are tightening carbon-accounting requirements for organic supply chains. Stakeholders must monitor evolving compostable packaging mandates under Germany's Packaging Act and decide whether to absorb certification cost escalations or pass them through shelf-price adjustments.
Market Dynamics
The Federal Ministry of Food and Agriculture's tightening certification standards under EU Regulation 2018/848 are compressing supplier margins while accelerating acreage conversion subsidies. Bavarian and Baden-Württemberg consumers are pulling volume southward, forcing northern retailers to reconfigure sourcing networks around regional cooperative structures.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Carbon-accounting mandates are creating certified premium tiers that reward early adopters with shelf-space advantages in REWE and EDEKA stores.
- Millennial household clustering:Urban Berlin and Munich consumers are expanding online retail penetration despite last-mile cold-chain constraints.
- Compostable packaging mandates:Germany's Packaging Act is pushing converters to develop bio-based barrier films that meet organic seal requirements.
Market Restraints
- Input cost volatility:Organic feed grain prices swing with weather-dependent harvests in Eastern European supplier regions.
- Supply concentration risk:Dairy processing capacity clusters in southern German states, creating bottlenecks for northern farm-gate volumes.
- Technical limitation:Seven-year conversion timelines for conventional farmland lock acreage expansion below demand growth rates.
Strategic Opportunities
- Underpenetrated rural online retail:Last-mile cold-chain partnerships with regional logistics networks could unlock eastern German households outside Berlin-Munich corridors.
- Direct-to-restaurant channels:Bavarian gastronomy clusters are seeking farm-transparent sourcing bypassing supermarket markups.
- KBA-aligned transport subsidies:Emissions-compliant fleet upgrades offer cost-offset pathways for organic distributors serving urban clusters.
Industry Challenges
- Certification timeline compression:EU Regulation 2018/848 inspection backlogs are delaying product launches during peak seasonal windows.
- Skill scarcity in organic agronomy:Conversion advisors are concentrated in established southern farming regions, leaving northern advisory gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Organic Food Market |
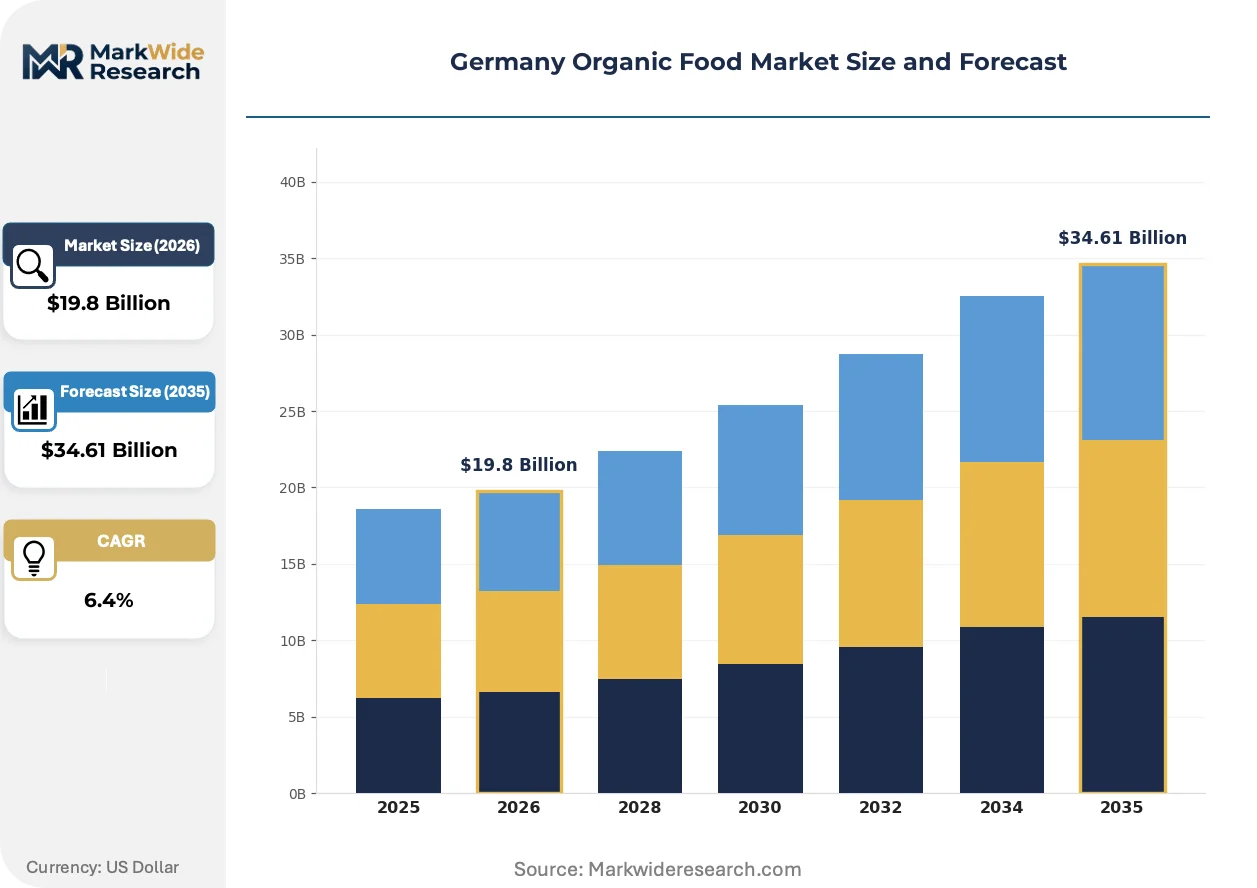
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy Products, Grains Sales Channel: Supermarkets, Specialty Stores, Online Retail, Farmers' Markets Consumer Type: Health-Conscious Shoppers, Eco-Friendly Consumers, Families, Millennials Packaging Type: Recyclable Packaging, Bulk Packaging, Compostable Packaging, Glass Containers |
| Companies Covered | EDEKA, Lidl, Denn's, Ebl Naturkost, Bio Company, Alnatura, ALDI, Superbiomarkt, REWE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Organic Food Market Trends and Innovations
Digital traceability systems are penetrating German organic supply chains as retailers demand farm-to-shelf transparency. Certification bodies are integrating blockchain verification to reduce audit friction. These shifts are compressing the information asymmetry that previously separated specialty stores from mass-market channels.
Blockchain-based provenance tracking is unifying batch records across cooperative dairy networks and independent produce farms. EDEKA's regional sourcing divisions are piloting these systems fastest in northern Germany. The technology is unifying previously fragmented audit trails into single-source verification that satisfies both EU Regulation 2018/848 inspectors and consumer-facing apps.
Germany's Packaging Act amendments are mandating compostable barriers for organic-labeled products by tightening disposal-route requirements. Converters must certify home-compostable performance under DIN standards or face shelf-exclusion from certified assortments. Dairy and fresh produce categories bear the highest compliance burden as moisture-sensitive formats dominate their packaging mix.
Subscription-based organic box services are fragmenting traditional supermarket purchase patterns among dual-income households in Hamburg and Cologne. These platforms bypass retailer markups while capturing margin through curated assortments and direct farm relationships. The shift is most visible in millennial cohorts prioritizing time convenience over in-store browsing.
Germany Organic Food Market Segmentation
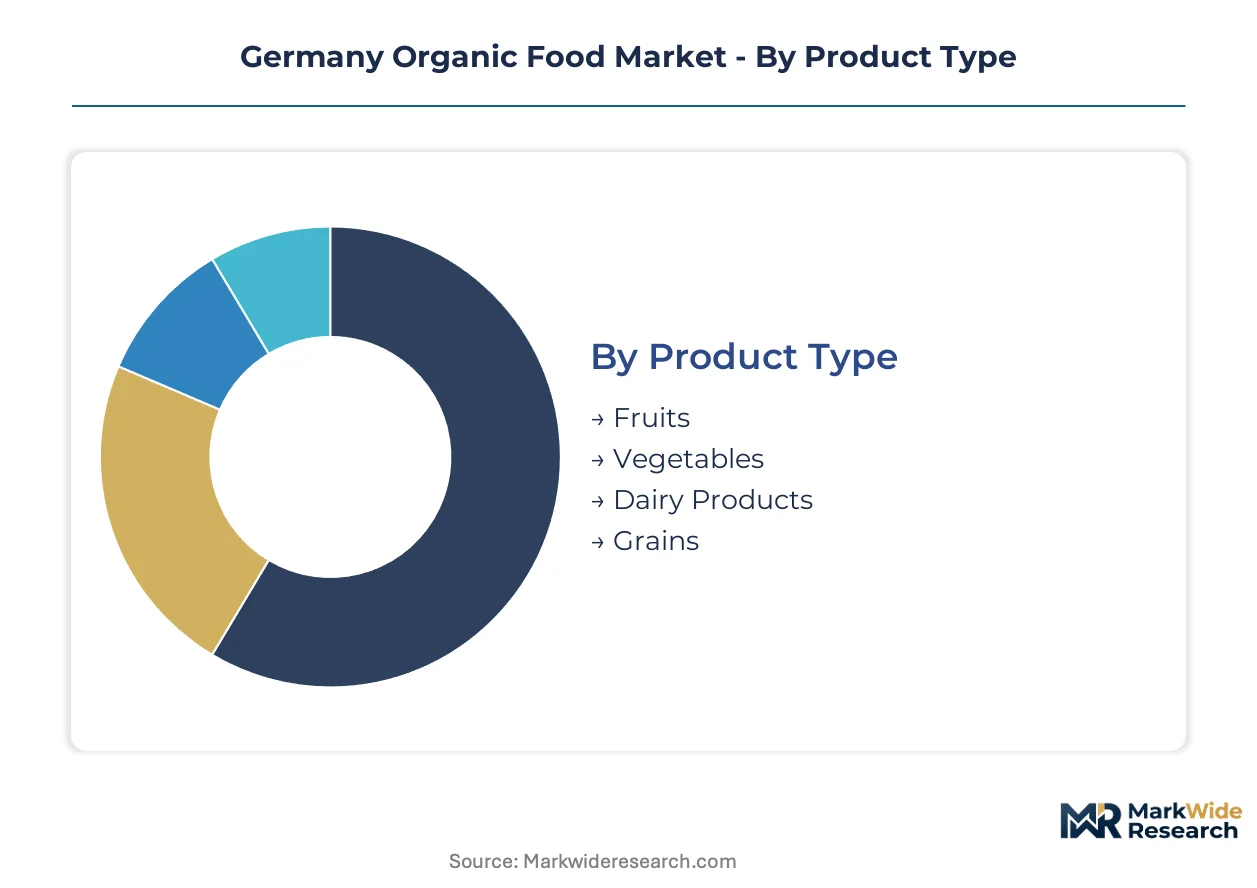
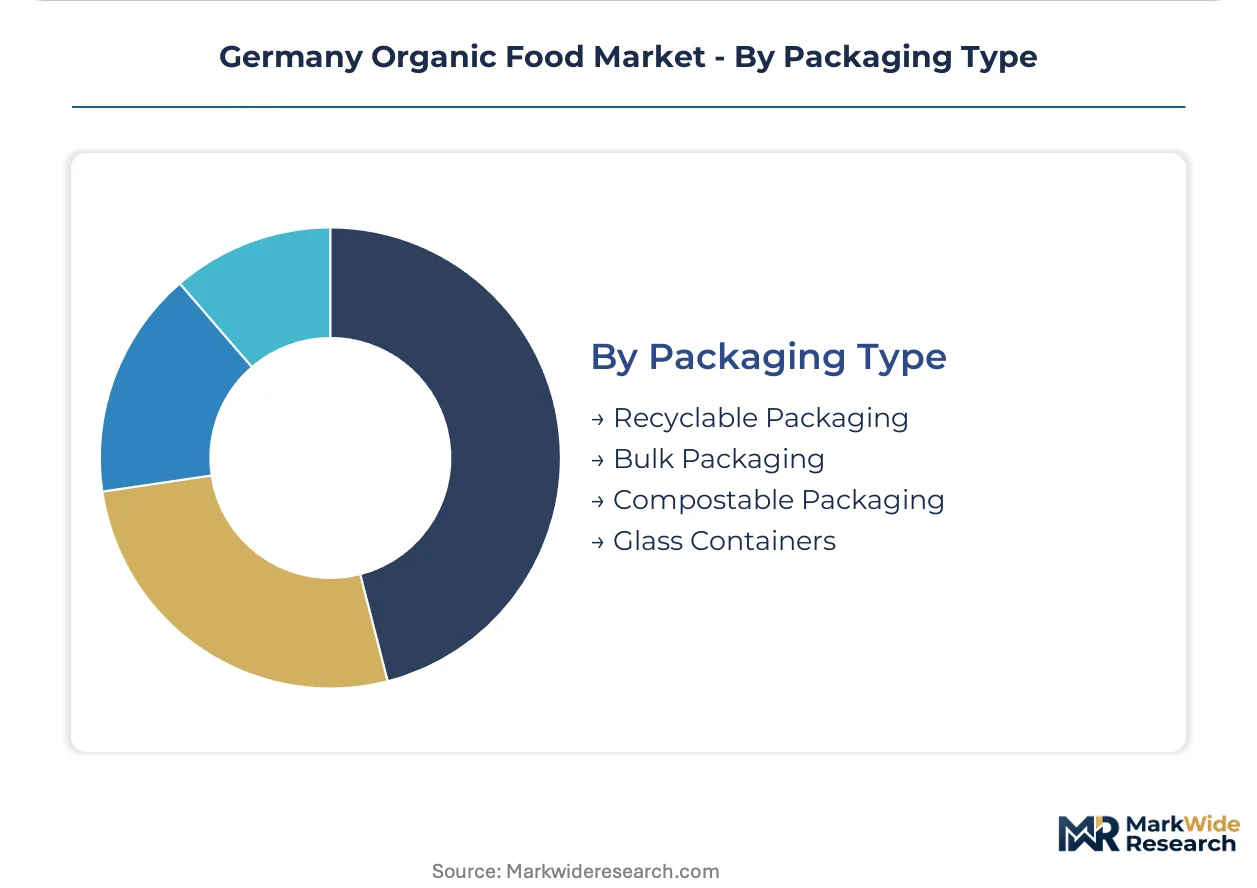
German organic food segmentation reveals distinct demand patterns across product categories and purchase occasions. Channel preferences diverge sharply between urban convenience seekers and rural provenance-focused buyers. Packaging compliance under the Packaging Act now filters which segments access certified shelf space.
Product Type:
Integration depth varies: dairy and produce dominate embedded retail assortments while grains operate more in standalone specialty formats.
- Dairy Products:Milk, cheese, and yogurt SKUs carry the highest certification premiums due to extended cold-chain requirements. Bavarian cooperatives supply REWE and EDEKA networks where per-capita organic spending peaks. EU Regulation 2018/848 traceability mandates compress margins but lock in shelf-space advantages.
- Fruits:Fresh and processed fruit lines anchor seasonal promotional cycles in supermarket organic aisles. Southern German states pull disproportionate volume given established farm-gate relationships. Weather-dependent Eastern European supply creates recurring price volatility.
- Vegetables:Leafy greens and root vegetables dominate farmers' market transactions.
- Grains:Bread cereals and pasta ingredients concentrate in bulk formats for eco-friendly consumer segments.
Dairy leads volumes today; fruits are gaining share fastest.
Sales Channel:
Cost tier stratification separates premium-capture specialty stores from mass-market supermarket efficiency plays.
- Supermarkets:REWE and EDEKA control principal organic infrastructure with regional cooperative sourcing. KBA-aligned transport subsidies offset emissions-compliant fleet investments. Cold-chain density advantages favor urban cluster penetration.
- Online Retail:Subscription box services fragment traditional purchase patterns among Hamburg and Cologne dual-income households. Last-mile logistics partnerships with regional networks could unlock eastern German rural households.
- Specialty Stores:Artisanal provenance and direct farm transparency command margin-rich positioning.
- Farmers' Markets:Seasonal proximity sourcing bypasses supermarket markups for local produce.
Supermarkets lead volumes today; online retail is expanding most quickly.
Consumer Type:
Application context distinguishes household purchase triggers: health claims versus environmental alignment versus family convenience.
- Health-Conscious Shoppers:Berlin and Munich consumers prioritize verified nutritional attributes and synthetic pesticide avoidance. Medical wellness narratives drive repeat purchase loyalty. Certification seal recognition exceeds national averages.
- Millennials:Urban clustering in Hamburg and Cologne favors time-convenience platforms over in-store browsing. Digital-native cohorts show highest subscription box adoption rates. Curated assortment curation captures margin through direct farm relationships.
- Eco-Friendly Consumers:Carbon-accounting transparency requirements shape purchase decisions.
- Families:Volume purchasing and child-focused nutritional positioning dominate basket composition.
Health-conscious shoppers lead volumes today; millennials are climbing the fastest.
Packaging Type:
Supply concentration in compostable barrier film converters creates compliance bottlenecks for moisture-sensitive formats.
- Compostable Packaging:Bio-based barrier films must certify home-compostable performance under DIN standards. Dairy and fresh produce bear highest compliance burden given moisture sensitivity. Shelf-exclusion risk faces non-compliant assortments.
- Recyclable Packaging:Mono-material structures satisfy Germany's Packaging Act disposal-route requirements. Supermarket private-label lines convert fastest given volume scale. REWE regional divisions pilot deposit-return integration.
- Bulk Packaging:Refill infrastructure concentrates in specialty store and cooperative retail formats.
- Glass Containers:Premium dairy and preserve categories retain traditional packaging for provenance signaling.
Recyclable packaging leads volumes today; compostable packaging shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic agronomy specialists cluster in southern German farming regions, creating advisory capacity gaps that constrain northern acreage conversion timelines.
Bavaria
Per-capita organic spending peaks here among health-conscious Munich households demanding verified farm transparency. The Federal Ministry of Food and Agriculture channels conversion subsidies toward Bavarian dairy cooperatives. Alpine foothill processing clusters near Rosenheim concentrate cheese and yogurt capacity serving REWE regional networks.
Baden-Württemberg
Stuttgart metropolitan consumers pull disproportionate fresh produce volume through specialty store channels. EU Regulation 2018/848 harmonized inspection protocols accelerate cross-border sourcing from neighboring French Alsace farms. Black Forest artisanal dairies anchor provenance-focused supply relationships with Berlin gastronomy buyers.
North Rhine-Westphalia
Cologne and Düsseldorf millennial households drive subscription box adoption fastest among western German urban clusters. KBA-aligned transport subsidies offset emissions-compliant fleet investments for distributors serving the Rhine-Ruhr corridor. Regional logistics partnerships with DHL and Hermes unlock last-mile cold-chain penetration into eastern rural households.
Lower Saxony
Conventional grain farming dominance creates seven-year conversion bottlenecks despite federal subsidy availability. The EU Green Deal Farm to Fork strategy tightens carbon-accounting requirements for livestock feed supply chains. Emsland cooperative structures pilot blockchain traceability integration linking farm-gate production to EDEKA northern divisions.
Berlin-Brandenburg
Digital-native consumer density supports online retail expansion despite cold-chain infrastructure gaps in surrounding rural Brandenburg. Germany's Packaging Act compostable mandates face compliance challenges for moisture-sensitive dairy formats. Urban farming ventures in Berlin's Tempelhof and Spandau districts experiment with vertical production bypassing traditional acreage constraints.
Germany Organic Food Market Competitive Landscape
Top-tier vendors anchor mass-market supermarket channels, while regional cooperatives and specialty operators capture margin-rich provenance segments. The vendor base stratifies across three functional tiers: national supermarket chains controlling principal infrastructure, dedicated organic specialists leveraging vertical processing control, and price-point discounters streamlining assortments for entry-level conversion. Strategic archetypes include cooperative-structured regional sourcers, shelf-space partnership specialists, and private-label scale players. Competitive moves concentrate on blockchain traceability deployment and compostable packaging compliance acceleration.
Within the cooperative-structured tier, EDEKA exemplifies regional sourcing fragmentation through its federated northern divisions. Alnatura occupies a specialist position through dedicated shelf-space partnerships and captive processing network control. Lidl anchors the price-point vector with streamlined organic assortments targeting mass-market entry conversion. These three entities represent divergent strategic responses to EU Regulation 2018/848 certification compression and KBA-aligned transport subsidy capture.
| Leading Market Players |
|---|
| EDEKA |
| Lidl |
| Denn's |
| Ebl Naturkost |
| Bio Company |
| Alnatura |
| ALDI |
| Superbiomarkt |
| REWE |
| Others |
Pricing and Supply Chain Analysis
Captive processing networks at Alnatura and EDEKA's regional cooperatives anchor both supply security and premium pricing power across the German organic food sector. This backward integration into dairy processing and produce sourcing insulates shelf-price positioning from raw input volatility while locking in EU Regulation 2018/848 compliance advantages.
Pricing Analysis
Bundled subscription services fragment traditional supermarket pricing while unbundled per-unit transactions dominate in-store assortments. Three-tier pricing structure across premium, standard, and economy levels separates Alnatura's provenance-marked SKUs from REWE's mid-tier private-label lines and Lidl's entry-price conversion SKUs. Certification premiums under the German national organic seal compress margins for non-integrated processors. Price-conscious rural households in eastern German states exhibit highest sensitivity, while Munich health-conscious shoppers absorb certification markups with minimal elasticity.
Supply Chain Analysis
Direct-to-specialty-store channels handle artisanal provenance demand while supermarket distribution runs through REWE and EDEKA's regional cooperative structures. Geographic supply concentrates in Bavaria and Baden-Württemberg for dairy processing, with fresh produce drawing from French Alsace cross-border flows and Eastern European grain suppliers. Raw material dependencies center on organic feed grains, bio-based barrier films, and cold-chain logistics capacity. Single-source vulnerability in southern German dairy processing clusters creates bottleneck risk for northern farm-gate volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany organic food market functions as a stable compounder, with EU Green Deal carbon-accounting mandates and Federal Ministry of Food and Agriculture subsidy programs sustaining acreage conversion momentum through the projection horizon.
For Market Incumbents: Deepen blockchain traceability deployment across cooperative dairy networks to defend shelf-space positioning against subscription box disintermediation. Prioritize captive supply of compostable barrier films to preempt Packaging Act compliance exclusions. For New Entrants and Emerging Players: Launch via direct-to-restaurant channels targeting Bavarian gastronomy clusters seeking farm-transparent sourcing outside supermarket markups. Eastern German rural online retail presents the most penetrable white space, accessible through regional logistics partnerships with DHL and Hermes. For Investors and Strategic Acquirers: Roll-up economics work for regional organic cooperatives because seven-year conversion timelines and skill scarcity in northern advisory regions constrain new entrant supply response. Monitor KBA-aligned transport subsidy allocation rates as the inflection signal for distributor margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | EDEKA's northern divisions pilot farm-to-shelf verification satisfying EU Regulation 2018/848 inspectors. |
| Compostable Packaging Transition | DIN-certified home-compostable films prevent shelf-exclusion under Germany's Packaging Act amendments. |
| Regional Cooperative Expansion | EDEKA's federated structure sustains localized organic sourcing across northern German states. |
| Subscription Box Platform Launch | Hamburg and Cologne millennial households fragment traditional supermarket purchase patterns fastest. |
| KBA-Aligned Fleet Upgrade | Emissions-compliant transport subsidies offset cold-chain logistics investments serving urban clusters. |
Research Methodology
Coverage spans Bavaria, Baden-Württemberg, North Rhine-Westphalia, Lower Saxony, and Berlin-Brandenburg, with primary inputs from each region's organic farming cooperatives. The analysis combines interviews with Federal Ministry of Food and Agriculture officials, EDEKA regional sourcing directors, Alnatura processing network managers, and KBA transport compliance officers with secondary validation from EU Regulation 2018/848 certification databases, Germany's Packaging Act enforcement records, and agricultural subsidy disbursement filings. Bottom-up acreage conversion estimates and top-down retail channel revenue triangulation anchor volume and value outputs.
Granularity-level modeling disaggregates projections by product type, sales channel, consumer archetype, and packaging compliance tier across the analysis window. CAGRs derive from segment-level growth rate reconciliation against macroeconomic consumption elasticity assumptions. Forecast inputs include organic feed grain price indices, compostable film converter capacity expansion timelines, and cold-chain logistics density metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU Green Deal subsidy revision scenarios or extended EU Regulation 2018/848 inspection backlogs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Organic Juice Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
Organic Food and Beverages Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Canada Organic Food Market