
 Monoglyceride Market | 2026-2036
Monoglyceride Market Size, Share, and Industry Trends Forecast 2026-2036
Monoglyceride Market Foresight
Specialized lipid chemistry expertise is reorganizing competitive dynamics as manufacturers struggle to source technologists fluent in enzymatic esterification and high-purity distillation. Palsgaard A/S leverages its integrated emulsifier portfolio to anchor premium positioning across European bakery chains. Kerry Group sustains formulation partnerships with multinational food manufacturers seeking customized monoglyceride blends. Wilmar International dominates upstream vegetable oil supply, securing cost-advantaged feedstock access for glycerol monostearate production.
Monoglycerides are single fatty acid esters of glycerol, typically produced via glycerolysis of triglycerides or direct esterification using food-grade fatty acids, with hydrophilic-lipophilic balance values between 3 and 5 determining emulsification performance in oil-water systems. These compounds function primarily as emulsifiers, stabilizers, and texture modifiers in processed foods, pharmaceuticals, and personal care formulations. Glycerol monostearate occupies the largest volume share due to its versatility in baking and dairy applications where aeration stability and fat crystallization control command premium pricing. Glycerol monolaurate exhibits the fastest trajectory within the antimicrobial preservation niche, particularly in clean-label confectionery where manufacturers substitute synthetic preservatives. The pharmaceutical sector generates concentrated margin pools as compendial-grade monoglycerides for lipid-based drug delivery systems require stringent purity certifications and dedicated manufacturing lines.
FDA food additive regulations under 21 CFR 184.1505 govern glycerol monostearate usage levels and labeling requirements, while REACH registration mandates in Europe enforce comprehensive toxicological dossiers for imported emulsifier substances. EFSA evaluations of refined vegetable oil contaminants indirectly shape monoglyceride feedstock specifications and supplier qualification protocols. Stakeholders must monitor evolving clean-label certification schemes and enzyme-specific processing claims as these criteria increasingly determine procurement decisions and premium access across retail and foodservice channels.
Market Dynamics
Enzymatic esterification is displacing chemical glycerolysis as the dominant production pathway, concentrating technical capability among manufacturers with dedicated biocatalysis infrastructure and compendial-grade purification assets.
Growth Catalysts
- Clean-label bakery demand:European consumers through EFSA-influenced retail standards are rejecting synthetic emulsifiers, pulling distilled monoglycerides into premium bread and pastry formulations.
- REACH registration completion:Full dossier compliance for glycerol monostearate under ECHA mandates has clarified import pathways, reducing regulatory uncertainty for compounders sourcing from Asian suppliers.
- Lipid-based drug delivery expansion:Pharmaceutical formulators are adopting high-purity glycerol monooleate for self-emulsifying drug delivery systems, creating concentrated demand for compendial certification.
Market Restraints
- Palm oil price volatility:Feedstock cost swings for Malaysian and Indonesian crude palm oil directly compress glycerol monostearate margins, forcing hedging costs onto mid-scale producers.
- Specialized technologist scarcity:Lipid chemistry expertise in enzymatic processing and molecular distillation concentrates in German and Dutch processing clusters, creating recruitment bottlenecks elsewhere.
- Polyglycerol ester substitution:Food manufacturers in cost-sensitive applications are substituting polyglycerol polyricinoleate for monoglycerides in chocolate coatings, eroding volume in confectionery.
Strategic Opportunities
- Antimicrobial preservation niche:Glycerol monolaurate is penetrating clean-label confectionery as manufacturers replace sorbates and benzoates under retailer-driven formulation mandates.
- India FSSAI alignment:Domestic emulsifier producers are qualifying for Food Safety and Standards Authority of India certifications to supply bakery chains expanding in tier-two cities.
- Continuous processing adoption:Fixed-bed enzyme reactor technology is converging with inline analytics to enable real-time quality control, reducing batch-to-batch variation for pharmaceutical-grade output.
Industry Challenges
- Compendial certification timelines:USP-NF and Ph.Eur. qualification for pharmaceutical-grade monoglycerides requires 18-24 month validation cycles, locking working capital in pipeline inventory.
- Legacy equipment retrofit costs:Chemical glycerolysis plants face stranded asset risk as enzymatic capacity requirements demand stainless-steel reactor replacement and dedicated water removal systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monoglyceride Market |
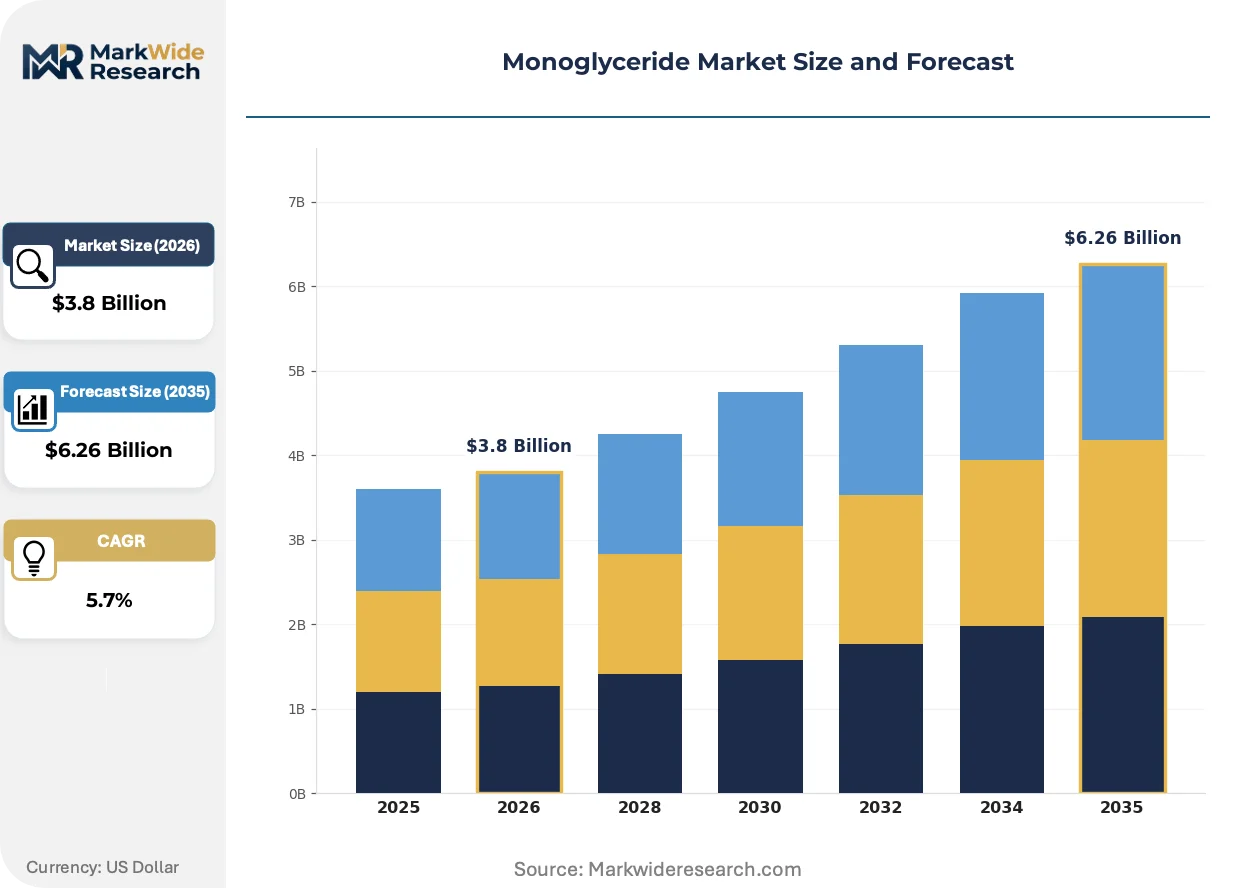
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
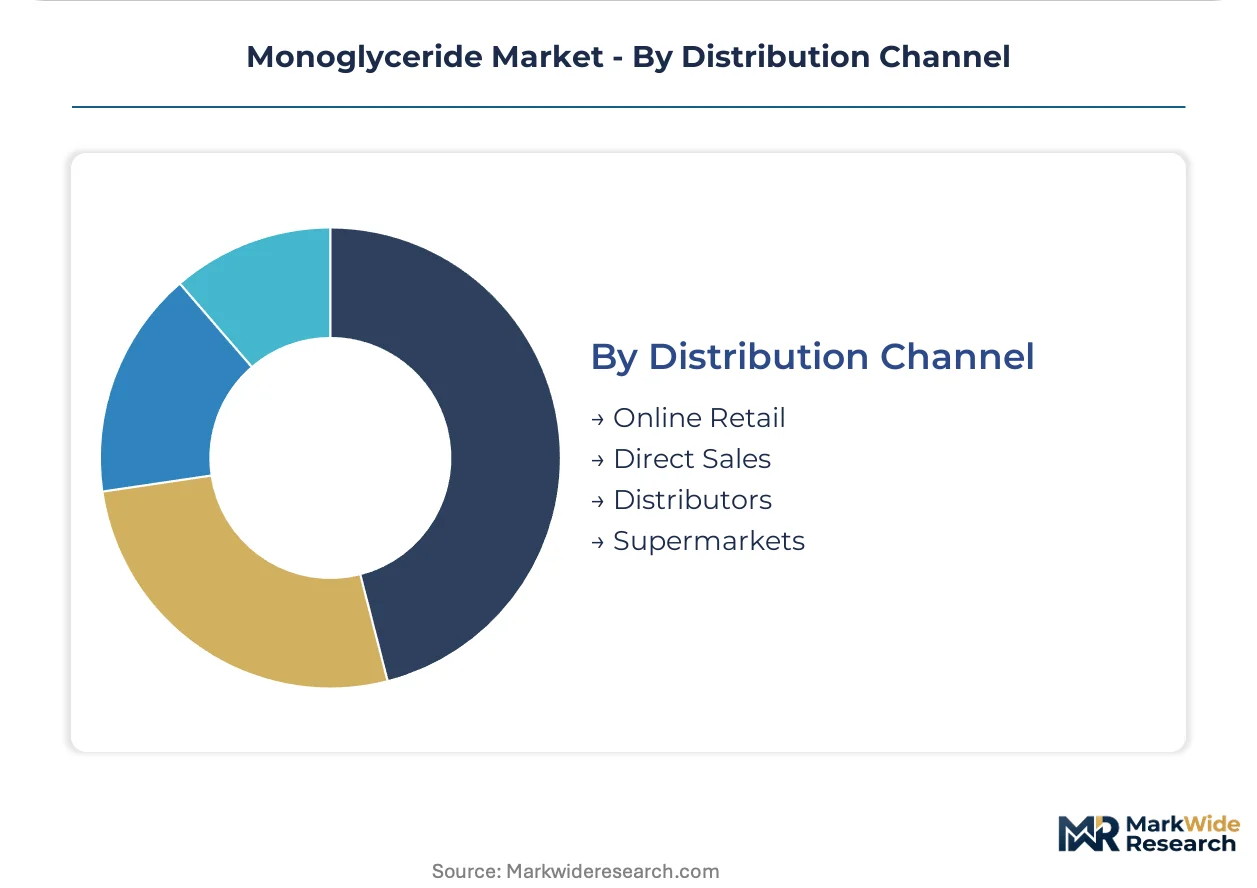
| Segmentation | Product Type: Glycerol Monostearate, Glycerol Monolaurate, Glycerol Monooleate, Glycerol Monopalmitate Application: Baking, Dairy Products, Confectionery, Dressings End User: Food Industry, Pharmaceutical Sector, Cosmetics, Nutraceuticals Distribution Channel: Online Retail, Direct Sales, Distributors, Supermarkets |
| Companies Covered | Palsgaard A/S, Kerry Group, Wilmar International Limited, Riken Vitamin, Danisco, Cargill, Inc., Corbion N.V., Olam International, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monoglyceride Market Shifts & Advancements
Processing technology and regulatory stringency are jointly compressing the viable supplier base while opening premium niches for manufacturers with biocatalysis and purification capabilities.
Enzymatic glycerolysis using immobilized lipase enzymes is bifurcating the supply base between dedicated biocatalysis operators and legacy chemical processors. Pharmaceutical formulators and premium bakery chains are specifying enzyme-derived monoglycerides for label claims and purity advantages. This technology is compressing margins for chemical-route producers while enabling 40-60% energy reduction and cleaner effluent profiles at scale.
EFSA evaluations of 3-MCPD and glycidyl ester contaminants in refined vegetable oils are tightening feedstock qualification protocols for European compounders. Importers must now demonstrate supply chain traceability to specific refinery deodorization parameters, increasing documentation burdens. Bakery and dairy manufacturers in Germany and France are responding by consolidating supplier lists to vertically integrated oil processors with certified contaminant controls.
Direct sourcing contracts between bakery chains and monoglyceride manufacturers are fragmenting traditional distribution through regional chemical distributors. Large European retail cooperatives are negotiating specification-controlled supply agreements that bypass compounder intermediaries. This pattern is most visible in German and Dutch markets where centralized procurement functions at retail headquarters command formulation transparency.
Monoglyceride Market Segmentation
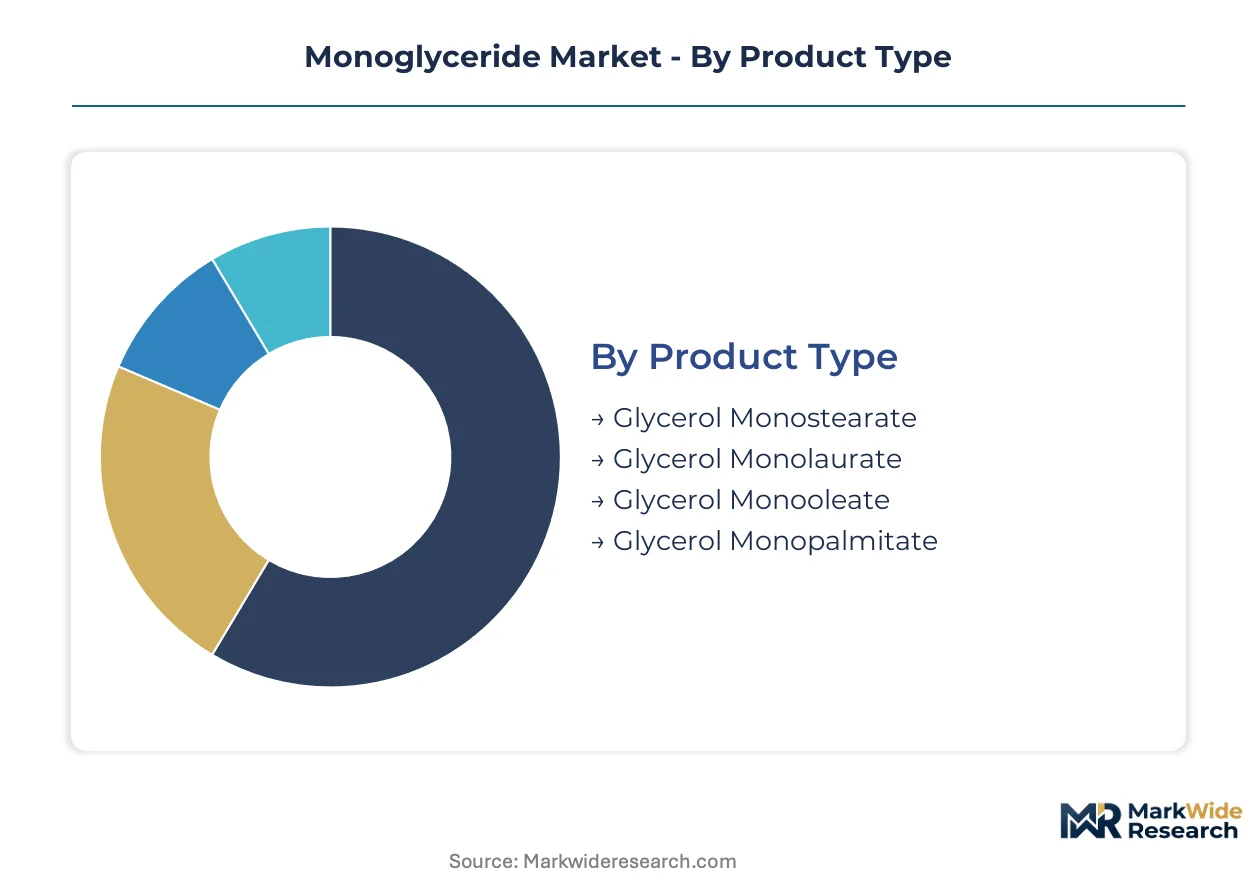
Monoglyceride procurement patterns diverge sharply across product grades and end-use specifications. Pharmaceutical formulators demand compendial certification that food manufacturers bypass, while enzymatic processing claims now determine channel access in premium bakery segments.
Product Type:
Channel mix varies by purity grade: pharmaceutical distributors handle compendial-certified glycerol monooleate, while commodity glycerol monostearate flows through regional chemical distributors to industrial bakeries.
- Glycerol Monostearate:Saturated C18 fatty acid ester with HLB values near 3.8, commanding the largest production volumes across European and North American bakery chains. German retail cooperatives specify distilled grades for clean-label bread formulations under EFSA-influenced procurement standards.
- Glycerol Monolaurate:Medium-chain C12 ester exhibiting pronounced antimicrobial activity against gram-positive bacteria. Clean-label confectionery manufacturers in France and the Netherlands substitute this for synthetic preservatives under retailer-driven formulation mandates, representing the steepest expansion trajectory within the product matrix.
- Glycerol Monooleate:Unsaturated C18:1 ester preferred for lipid-based drug delivery systems requiring USP-NF or Ph.Eur. certification.
- Glycerol Monopalmitate:Saturated C16 variant used in specialized dairy fat crystallization applications.
By volume, glycerol monostearate leads. By growth pace, glycerol monolaurate is ahead.
Application:
Cost tier stratification separates premium enzymatic grades for artisan bakery chains from standard chemical-route material in mass-market confectionery.
- Baking:Aeration stability and crumb structure control in yeast-raised products. Distilled monoglycerides specified by German and Dutch retail cooperatives for clean-label claims.
- Dairy Products:Fat crystallization modification in ice cream and whipped toppings. Premium grades command pricing premiums in Scandinavian markets.
- Confectionery:Chocolate bloom inhibition and texture modification. Polyglycerol ester substitution eroding monoglyceride share in cost-sensitive coatings.
- Dressings:Emulsion stability in oil-in-water systems. Standard-grade material sufficient for most foodservice applications.
Baking consumes the largest volume share. Confectionery faces the strongest substitution pressure.
End User:
Customer type determines specification stringency: pharmaceutical formulators require 18-24 month compendial validation cycles that food manufacturers avoid.
- Food Industry:Largest demand pool spanning bakery, dairy, and processed food manufacturing. Clean-label certification increasingly gates access to European retail chains.
- Pharmaceutical Sector:Compendial-grade glycerol monooleate for self-emulsifying drug delivery systems. Concentrated margins offset lengthy qualification timelines.
- Cosmetics:Emollient and emulsifier functions in personal care formulations. Moderate volume with premium pricing for vegetable-derived claims.
- Nutraceuticals:Bioavailability enhancement in lipid-soluble vitamin delivery. Emerging demand from supplement manufacturers seeking GRAS alternatives.
Food industry leads by volume. Pharmaceutical sector leads by margin per kilogram.
Distribution Channel:
Supply concentration shapes channel structure: direct contracts fragment traditional distributor relationships as large buyers seek formulation transparency.
- Direct Sales:Preferred by multinational food manufacturers and pharmaceutical formulators requiring specification-controlled supply agreements. German bakery chains negotiate directly with lipid processors.
- Distributors:Regional chemical distributors serve mid-scale compounders lacking volume for direct contracts. Margin compression from manufacturer bypass strategies.
- Online Retail:Niche channel for small-scale cosmetic and nutraceutical formulators seeking sample quantities. Limited to non-compendial grades.
- Supermarkets:Minimal penetration; consumer-facing monoglyceride products rare except in specialty baking supply sections.
Direct sales capture the highest-value transactions. Distributors retain volume dominance in fragmented geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance under ECHA anchors European demand patterns, with regulatory stringency rippling through supplier qualification protocols across multiple jurisdictions. Distinct national markets exhibit divergent procurement behaviors shaped by local food safety frameworks and industrial clustering.
Germany
Clean-label bakery chains in Bavaria and North Rhine-Westphalia specify distilled monoglycerides for bread formulations. EFSA-influenced retail standards mandate contaminant documentation from feedstock refineries. The Hamburg-Bremen corridor hosts specialized lipid processing clusters exporting premium-grade output to Scandinavian markets.
United States
FDA food additive regulations under 21 CFR 184.1505 govern usage levels in commercial baking and dairy applications. Midwestern food manufacturers seek GRAS-certified emulsifiers for processed cheese and whipped topping production. Chicago-area distribution hubs channel material to both coasts via direct procurement contracts.
France
Confectionery manufacturers in Île-de-France substitute glycerol monolaurate for synthetic preservatives under retailer-driven mandates. ANSM oversight of food contact materials indirectly shapes emulsifier purity specifications. Lyon-based dairy processors command premium pricing for fat crystallization control in ice cream applications.
China
SAMR implementation of GB standards for food emulsifiers is tightening import documentation requirements for glycerol monostearate. Yangtze River Delta baking conglomerates are qualifying domestic enzymatic producers to reduce reliance on Malaysian feedstock. Shanghai port logistics handle the largest regional import volumes.
India
FSSAI certification requirements are accelerating domestic emulsifier production for bakery chains expanding in tier-two cities. Gujarat-based vegetable oil processors are backward integrating into monoglyceride output to capture margin from imported substitutes. Mumbai-Pune industrial corridors concentrate formulation expertise for Western India food manufacturing.
Monoglyceride Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enzymatic processing capability concentrating among European and Asian specialists while palm oil traders dominate feedstock economics. The market structure bifurcates between compendial-grade pharmaceutical suppliers and commodity food-grade compounders. Three archetypes define competitive positioning: integrated vegetable oil processors with captive glycerol supply, dedicated emulsifier specialists with biocatalysis assets, and diversified food ingredient conglomerates with formulation partnerships. Capacity expansion and direct contracting with retail chains represent the dominant competitive moves, displacing traditional distributor relationships.
Within the integrated processor tier, Wilmar International Limited exemplifies upstream control over Malaysian and Indonesian palm oil supply chains. Among emulsifier specialists, Palsgaard A/S and Kerry Group occupy positions anchored to European bakery and dairy formulation partnerships. These three entities represent distinct strategic approaches: feedstock integration, premium positioning through integrated portfolios, and customized blend capabilities for multinational food manufacturers.
| Leading Market Players |
|---|
| Palsgaard A/S |
| Kerry Group |
| Wilmar International Limited |
| Riken Vitamin |
| Danisco |
| Cargill, Inc. |
| Corbion N.V. |
| Olam International |
| BASF SE |
| Others |
Supply & Pricing Matrix
Polyglycerol ester substitution in chocolate coatings is redrawing supply geography toward Southeast Asian polyol producers while compressing monoglyceride pricing power in European confectionery tiers. This displacement dynamic simultaneously elevates enzyme-derived premium grades and erodes commodity chemical-route margins across distributor networks.
Pricing Analysis
Geographic price spreads of 15-25% separate German pharmaceutical-grade glycerol monooleate from Southeast Asian food-standard glycerol monostearate. Three-tier pricing structure across compendial-certified, enzymatic food-grade, and chemical-route commodity levels dominates transaction structures. Cost compression in standard grades is intensifying because palm oil feedstock volatility transfers directly to compounder margins. Mass-market confectionery manufacturers exhibit highest price sensitivity, while pharmaceutical formulators absorb premiums for USP-NF certification.
Supply Chain Analysis
Malaysia and Indonesia anchor crude palm oil supply, while Germany and the Netherlands concentrate enzymatic processing and molecular distillation capabilities. Downstream production draws from vegetable oil refineries, glycerol recovery systems, and immobilized lipase enzyme suppliers. Single-source vulnerability runs through Malaysian palm oil estates exposed to El Niño precipitation patterns. Distribution runs through direct contracts between bakery chains and lipid processors, bypassing traditional regional chemical distributors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyglycerol ester substitution in cost-sensitive confectionery applications threatens volume retention, forcing incumbents to defend premium positioning through certification barriers and enzymatic processing claims.
For Market Incumbents: Compound biocatalysis capacity in German and Dutch processing clusters to anchor clean-label supply agreements with retail cooperatives. Secure backward integration into vegetable oil refining with certified contaminant controls to defend against feedstock volatility. Prioritize USP-NF and Ph.Eur. certification investments to maintain pharmaceutical margin pools against Asian cost competition. For New Entrants and Emerging Players: Anchor in India's FSSAI qualification pathway for domestic bakery chains expanding in tier-two cities. Target antimicrobial preservation niches where glycerol monolaurate substitutes sorbates under retailer mandates. Pursue continuous processing technology partnerships to bypass legacy batch equipment barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European emulsifier specialists holding enzymatic infrastructure but lacking feedstock integration. Five-to-ten-year viability hinges on compendial certification depth and direct retail contracting penetration. Watch for FSSAI enforcement acceleration in India as inflection signal for domestic production viability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Capacity Expansion | Immobilized lipase reactor investments enable clean-label claims for EFSA-influenced European retail procurement. |
| Backward Integration into Refining | Captive vegetable oil processing secures contaminant documentation for REACH-registered glycerol monostearate exports. |
| Compendial Certification Investment | USP-NF qualification opens pharmaceutical lipid-based drug delivery system supply with concentrated margin profiles. |
| Direct Contracting with Retail Chains | Bypassing regional distributors captures formulation transparency premiums in German and Dutch centralized procurement. |
| Continuous Processing Adoption | Fixed-bed enzyme reactors with inline analytics reduce batch variation for pharmaceutical-grade output quality. |
Research Methodology
Initial hypotheses were tested against primary input from lipid processing plant managers, bakery procurement leads at European retail cooperatives, pharmaceutical formulation scientists, and regional chemical distribution channel partners and refined through secondary validation against ECHA REACH registration databases, FDA 21 CFR food additive filings, FSSAI certification records, and Malaysian Palm Oil Board trade statistics. Bottom-up capacity estimates and top-down demand segmentation were triangulated to resolve variance.
Variance decomposition across product grade, end-use application, enzymatic versus chemical processing route, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated palm oil price elasticity coefficients and pharmaceutical compendial certification pipeline durations.
Decision-makers should treat outputs as directional under sustained EFSA contaminant scrutiny and enzymatic technology diffusion assumptions; material deviation in polyglycerol ester substitution rates or palm oil supply disruptions would warrant model refresh. Recalibration cycles align with material shifts in REACH enforcement patterns and FSSAI implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Agar Agar Gum Market