
 Germany Data Center Power Market | 2026-2036
Germany Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Power Market Insights
VDE-AR-E 2510-50 certification for battery storage systems in data centers is rotating supplier eligibility, forcing vendors to recertify against updated electrochemical safety benchmarks. Schneider Electric SE leverages its European manufacturing footprint to anchor large-scale uninterruptible power supply deployments. Siemens AG competes through integrated power distribution architectures that combine medium-voltage switchgear with digital twin monitoring.
Germany data center power encompasses electrical infrastructure engineered to deliver conditioned, redundant electricity at voltages from 400V to 33kV with availability targets exceeding 99.999%. This infrastructure converts, distributes, and protects power for server racks, cooling systems, and networking equipment across mission-critical digital facilities. Hyper-scale facilities command the dominant investment share as cloud operators build multi-hundred-megawatt campuses near renewable generation clusters. Edge data centers represent the fastest-expanding infrastructure type, driven by latency-sensitive manufacturing automation and autonomous vehicle data processing in Bavaria and Baden-Württemberg. Liquid cooling solutions capture expanding margin pools as power densities exceed 50kW per rack and conventional air systems reach thermal limits.
The Federal Network Agency (Bundesnetzagentur) enforces grid connection standards that shape backup generator runtime limits and renewable power purchase obligations for new data center approvals. Germany's Energy Efficiency Act mandates waste heat recovery above 1MW capacity, redirecting thermal output to district heating networks in Frankfurt, Berlin, and Munich. KBA and state building codes impose fire suppression and seismic resilience requirements on power infrastructure installations. Stakeholders must weigh stranded asset risk against certification timelines as efficiency thresholds tighten and carbon border adjustments reshape energy sourcing economics.
Market Dynamics
Power density thresholds above 50kW per rack are forcing wholesale infrastructure replacement across Frankfurt and Berlin corridors, as legacy air-cooled facilities face thermal hard limits before reaching design capacity.
Growth Catalysts
- Energy Efficiency Act mandates:Waste heat recovery obligations above 1MW capacity are redirecting thermal output to district heating networks in Frankfurt, Berlin, and Munich, creating dual-revenue streams for facility operators.
- Financial services clustering:Frankfurt's banking sector is driving sovereign cloud construction with availability targets exceeding 99.999%, requiring redundant 33kV distribution architectures.
- Liquid cooling adoption:Direct-to-chip and immersion systems are capturing margin pools as conventional air systems reach thermal limits in Bavaria and Baden-Württemberg manufacturing automation facilities.
Market Restraints
- Copper and silicon carbide supply concentration:Power electronics sourcing faces bottlenecks from concentrated Asian substrate suppliers, inflating lead times for medium-voltage switchgear deployments.
- VDE-AR-E 2510-50 recertification cycles:Updated electrochemical safety benchmarks for battery storage systems are rotating supplier eligibility and compressing vendor qualification windows.
- Grid connection queuing:Bundesnetzagentur approval timelines for multi-hundred-megawatt campus connections are extending project commissioning by 18-24 months in renewable generation clusters.
Strategic Opportunities
- Edge facility penetration in Saxony and Thuringia:Latency-sensitive autonomous vehicle data processing is driving modular power infrastructure deployment outside established Frankfurt-Berlin corridors.
- Hydrogen-ready backup generation:KBA fire suppression codes are being adapted to accommodate fuel cell substitution for diesel generators in new Munich approvals.
- Digital twin convergence with power distribution:Integrated architectures combining medium-voltage switchgear with real-time monitoring are opening service revenue streams beyond equipment sales.
Industry Challenges
- Medium-voltage technician scarcity:Specialized commissioning expertise for 33kV distribution is concentrated among aging utility workforces, constraining deployment velocity.
- Stranded asset risk from efficiency threshold compression:Facilities designed to current Energy Efficiency Act standards face premature obsolescence as carbon border adjustments reshape energy sourcing economics.
- Seismic resilience compliance:State building codes in Baden-Württemberg and Bavaria are imposing structural reinforcement costs on power infrastructure installations in earthquake zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Power Market |
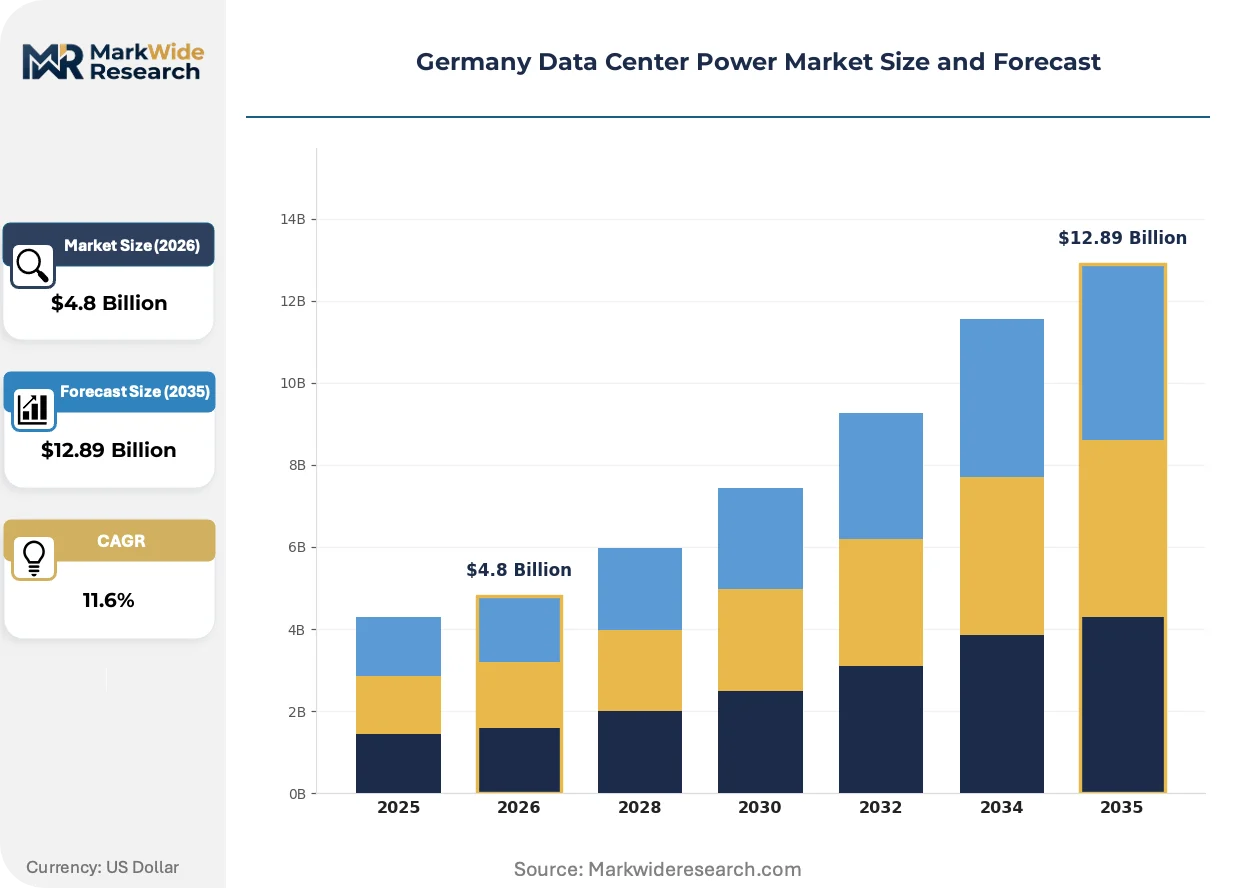
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Diesel Generators, Grid Power, Backup Systems Infrastructure Type: Modular Data Centers, Traditional Data Centers, Edge Data Centers, Hyper-scale Facilities Cooling Solution: Liquid Cooling, Air Cooling, Hybrid Cooling, Immersion Cooling End User: Telecommunications, Cloud Service Providers, Enterprises, Managed Service Providers |
| Companies Covered | Schneider Electric SE, ABB Ltd, Eaton Corporation, Vertiv Group Corp, Siemens AG, Legrand SA, Delta Electronics, Generac Holdings Inc, Huawei Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Power Market Trends and Innovations
Liquid cooling architectures and renewable integration mandates are restructuring capital allocation across German data center power infrastructure, with technology choices locking in operational trajectories for fifteen-year asset lifecycles.
Immersion cooling using synthetic dielectric fluids is bifurcating the thermal management market. Hyperscale operators in Frankfurt are deploying single-phase tanks for GPU-dense AI training clusters, while financial services facilities retain air-cooled redundancy for legacy transaction processing. The technology is bifurcating supplier ecosystems into fluid chemistry specialists versus integrated mechanical contractors.
Germany's Energy Efficiency Act is mandating waste heat recovery above 1MW capacity, redirecting thermal output to municipal district heating networks. This industrial obligation is forcing power infrastructure designers to spec heat exchanger integration at the substation level. Colocation providers in Berlin are responding by securing long-term heat offtake agreements with municipal utilities before breaking ground.
Buyers are consolidating vendor relationships around integrated power distribution architectures that combine medium-voltage switchgear with digital twin monitoring. Equipment procurement is compressing from multi-vendor assemblies to single-source accountability for availability guarantees. Financial services operators in Frankfurt are driving this consolidation, demanding unified liability for 99.999% uptime across electrical and mechanical systems.
Germany Data Center Power Market Segmentation
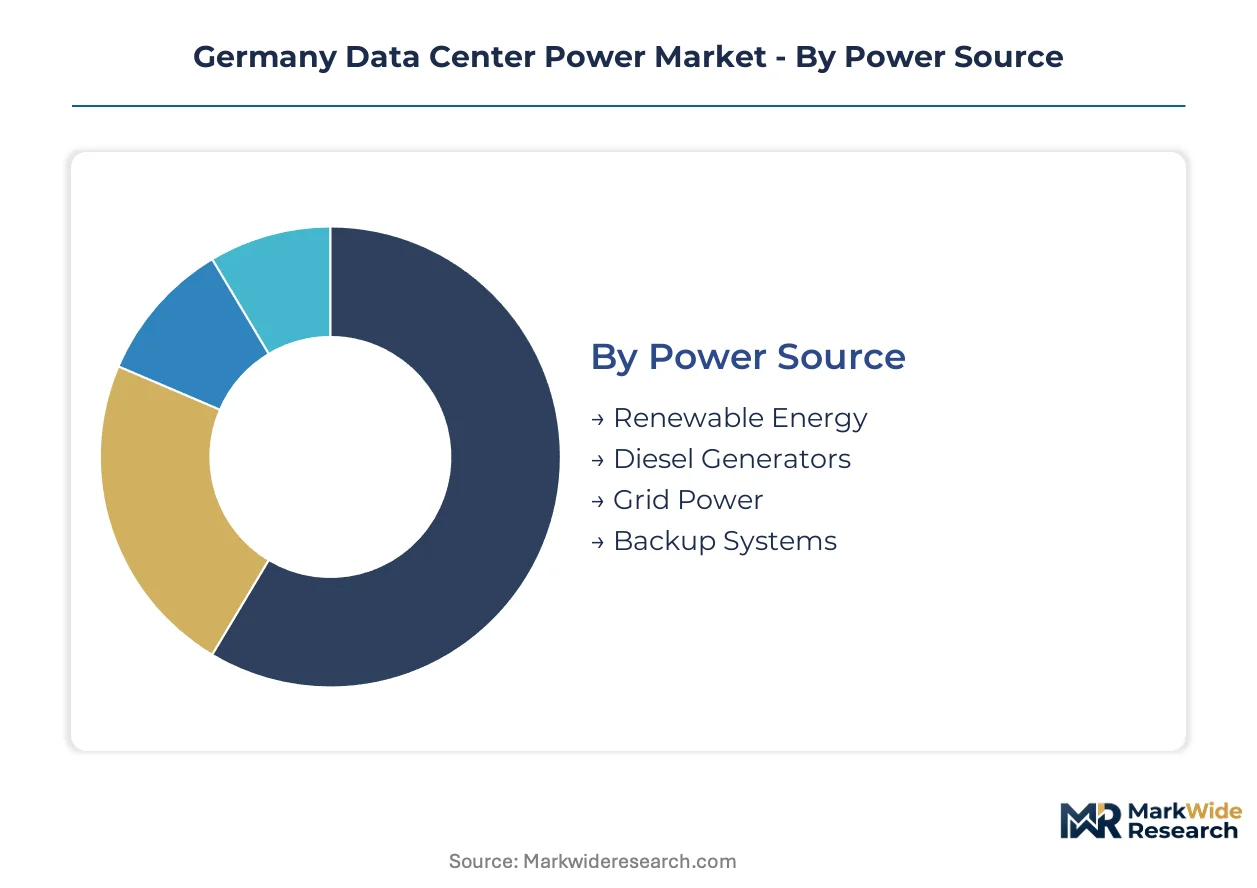
Power infrastructure procurement in Germany fragments across competing technical philosophies, with efficiency mandates and density thresholds forcing operators into irreversible technology commitments. Each segmentation dimension carries distinct regulatory exposure and capital intensity profiles that shape fifteen-year asset trajectories.
Power Source:
Grid Power faces the most acute substitution pressure as renewable integration mandates and carbon border adjustments erode its cost advantage against on-site generation alternatives.
- Renewable Energy:Direct power purchase agreements with wind and solar clusters near Frankfurt, Berlin, and Munich corridors satisfy EU Green Deal compliance while locking in long-term price visibility. Hyperscale operators are anchoring multi-hundred-megawatt campuses within transmission distance of renewable generation to meet Bundesnetzagentur connection standards.
- Diesel Generators:KBA fire suppression codes and Munich's hydrogen-ready backup generation pilots are compressing deployment windows for conventional fossil backup. Financial services facilities in Frankfurt retain diesel redundancy for 99.999% availability guarantees despite tightening runtime limits.
- Grid Power:Bundesnetzagentur queuing timelines extend commissioning by 18-24 months for large campus connections, inflating project risk.
- Backup Systems:Battery storage deployments face VDE-AR-E 2510-50 recertification cycles that rotate supplier eligibility against updated electrochemical safety benchmarks.
Grid Power retains volume leadership; Renewable Energy holds the steepest expansion curve.
Infrastructure Type:
Cost tier stratification separates capital-intensive hyperscale construction from modular edge deployments, with each tier serving distinct latency and availability requirements.
- Hyper-scale Facilities:Multi-hundred-megawatt campuses command dominant investment share as cloud operators cluster near renewable generation. These facilities spec 33kV distribution architectures with waste heat recovery integration mandated above 1MW capacity under Germany's Energy Efficiency Act.
- Edge Data Centers:Latency-sensitive manufacturing automation in Bavaria and Baden-Württemberg drives fastest-expanding infrastructure demand. Autonomous vehicle data processing requirements are pulling modular power deployment into Saxony and Thuringia outside established corridors.
- Modular Data Centers:Prefabricated electrical skids reduce field commissioning time where medium-voltage technician scarcity constrains traditional buildouts.
- Traditional Data Centers:Legacy air-cooled facilities in Frankfurt face thermal hard limits before reaching design capacity, forcing wholesale infrastructure replacement.
Hyper-scale Facilities anchor capital deployment; Edge Data Centers are climbing the fastest.
Cooling Solution:
Application-specific thermal loads are bifurcating supplier ecosystems between fluid chemistry specialists and integrated mechanical contractors.
- Liquid Cooling:Direct-to-chip systems capture expanding margin pools as rack densities exceed 50kW and conventional air systems reach thermal limits. GPU-dense AI training clusters in Frankfurt deploy single-phase tanks while financial services retain air-cooled redundancy for legacy transaction processing.
- Immersion Cooling:Synthetic dielectric fluid tanks serve hyperscale AI workloads with superior heat rejection capacity. The technology demands specialized fire suppression adaptation under evolving KBA codes.
- Air Cooling:Dominant legacy share faces displacement above 50kW per rack thresholds across Frankfurt and Berlin corridors.
- Hybrid Cooling:Combined architectures bridge thermal management during facility transition periods or mixed workload environments.
Air Cooling retains installed base dominance; Liquid Cooling is gaining share fastest.
End User:
Customer type concentration varies sharply by availability requirements, with sovereign cloud mandates creating distinct procurement patterns from commercial colocation.
- Cloud Service Providers:Hyperscale operators drive capacity expansion across Frankfurt and Berlin corridors with renewable power purchase obligations and waste heat recovery integration. These buyers consolidate vendor relationships around integrated power distribution architectures with unified availability liability.
- Enterprises:Financial services clustering in Frankfurt demands redundant 33kV distribution for sovereign cloud construction with 99.999% uptime targets. Banking sector procurement compresses multi-vendor assemblies into single-source accountability.
- Telecommunications:5G edge infrastructure and low-latency content delivery networks pull power deployment into secondary markets.
- Managed Service Providers:Colocation operators in Berlin secure long-term heat offtake agreements with municipal utilities before breaking ground to satisfy Energy Efficiency Act mandates.
Cloud Service Providers command capacity investment; Enterprises show the steepest sovereign cloud expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud service providers and financial institutions concentrate procurement decisions across German metropolitan corridors, with hyperscale operators anchoring capacity expansion near renewable generation clusters.
Frankfurt Rhine-Main
Financial services clustering drives sovereign cloud construction with 99.999% availability mandates requiring redundant 33kV distribution architectures. The Energy Efficiency Act mandates waste heat recovery above 1MW capacity, redirecting thermal output to municipal district heating networks. Banking sector procurement compresses multi-vendor assemblies into single-source accountability for uptime guarantees.
Berlin-Brandenburg
Colocation providers secure long-term heat offtake agreements with municipal utilities before breaking ground to satisfy regulatory mandates. Bundesnetzagentur grid connection standards shape backup generator runtime limits and renewable power purchase obligations. Edge data center deployment accelerates for latency-sensitive content delivery networks and public sector cloud migration.
Bavaria
Manufacturing automation and autonomous vehicle data processing pull modular power infrastructure into latency-sensitive industrial zones. KBA fire suppression codes are being adapted to accommodate hydrogen-ready backup generation pilots in new Munich approvals. Liquid cooling adoption captures margin pools as rack densities exceed 50kW in GPU-dense AI training facilities.
Baden-Württemberg
State building codes impose seismic resilience requirements on power infrastructure installations in earthquake zones, inflating structural reinforcement costs. Edge facility penetration expands for automotive sector data processing and industrial IoT applications. Medium-voltage technician scarcity constrains deployment velocity for 33kV distribution commissioning.
North Rhine-Westphalia
Legacy air-cooled facilities face thermal hard limits before reaching design capacity, forcing wholesale infrastructure replacement across established corridors. Renewable power purchase agreements with regional wind clusters satisfy EU Green Deal compliance while locking in long-term price visibility. Copper and silicon carbide supply concentration inflates lead times for medium-voltage switchgear deployments.
Germany Data Center Power Market Competitive Landscape
Player mix skews toward integrated electrical infrastructure specialists with European manufacturing footprints and digital service capabilities. Market structure concentrates around multinational industrial conglomerates with captive distribution networks and certified battery storage portfolios. Three archetypes dominate: full-stack power distribution architects, modular UPS and cooling integrators, and renewable-coupled microgrid specialists. Competitive moves center on vendor consolidation for unified availability liability and geographic expansion into secondary edge markets.
Among France-based electrical specialists, Schneider Electric SE and Legrand SA occupy positions within the integrated power distribution tier, exemplifying European manufacturing footprint strategies for large-scale deployments. Siemens AG anchors the German industrial conglomerate archetype, representing integrated architectures that combine medium-voltage switchgear with digital monitoring capabilities. Vertiv Group Corp sits within the mission-critical infrastructure specialist tier, reflecting the vendor consolidation pattern as buyers compress procurement from multi-vendor assemblies toward single-source accountability.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Eaton Corporation |
| Vertiv Group Corp |
| Siemens AG |
| Legrand SA |
| Delta Electronics |
| Generac Holdings Inc |
| Huawei Technologies |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate substitution for conventional silicon IGBTs is redrawing procurement geography toward Asian wafer foundries while compressing margin structures for European switchgear assemblers facing input cost volatility. This materials transition simultaneously elevates capital intensity for power electronics and fragments vendor pricing power across the value chain.
Pricing Analysis
Cost-plus contracts indexed to copper and rare earth oxide benchmarks dominate procurement for medium-voltage switchgear and transformer assemblies. Three-tier pricing structure across premium-certified, standard-compliant, and economy-specification levels separates VDE-AR-E 2510-50 validated battery systems from uncertified alternatives. Price erosion runs through economy-tier UPS modules as Chinese manufacturers expand European distribution. Cloud service providers demonstrate lowest price sensitivity due to unified availability liability requirements, while colocation operators in secondary markets drive hardest bargain compression.
Supply Chain Analysis
Taiwan Strait transit vulnerability underwrites concentrated exposure for silicon carbide wafer and power semiconductor shipments. German switchgear production draws from Chinese rare earth processing, Japanese ceramic substrate manufacturing, and Malaysian copper refining operations. Single-source vulnerability concentrates in 33kV vacuum interrupter assemblies where two Asian suppliers control global capacity. Distribution runs through authorized electrical distributors with certified technician networks rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's data center power market functions as a regulatory-moat arena where VDE certification entrenchment and Bundesnetzagentur grid queuing create switching-cost barriers for facility operators.
For Market Incumbents: Shield installed base relationships through captive medium-voltage technician training programs that address scarcity constraints constraining competitor deployment velocity. Deepen backward integration into battery cell assembly to secure VDE-AR-E 2510-50 certification continuity against rotating supplier eligibility rules. Hydrogen-ready backup generation pilots in Munich represent the priority capability gap to close before regulatory mandates harden. For New Entrants and Emerging Players: Anchor in Saxony and Thuringia edge facility corridors where latency-sensitive autonomous vehicle processing demand outstrips established vendor coverage. Modular power skids for sub-10MW deployments face softer incumbent saturation than Frankfurt hyperscale corridors. Lead with digital twin monitoring bundles that reduce field commissioning dependence where technician scarcity bites hardest. For Investors and Strategic Acquirers: Germany's Energy Efficiency Act waste heat recovery mandates reshape the acquisition landscape toward district heating integration capabilities. Five-to-ten-year viability favors targets with secured municipal offtake agreements in Berlin and Munich regulatory zones. Monitor KBA fire suppression code evolution for hydrogen fuel cell backup as inflection signal for stranded diesel generator asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| VDE-AR-E 2510-50 Certification Investment | Battery storage supplier eligibility rotation makes certification continuity a survival threshold for vendor retention. |
| District Heating Integration Partnership | Energy Efficiency Act mandates above 1MW capacity lock in dual-revenue streams with municipal utilities. |
| Hydrogen-Ready Backup Generation Pilot | KBA code adaptation in Munich approvals signals regulatory trajectory away from diesel redundancy. |
| Digital Twin Platform Development | Integrated monitoring architectures capture service revenue beyond equipment sale commoditization. |
| Edge Corridor Geographic Expansion | Saxony and Thuringia latency demand outpaces incumbent coverage for modular power deployment. |
Research Methodology
Operator-level perspectives from data center facility directors, electrical infrastructure procurement leads, Bundesnetzagentur grid connection officers, and medium-voltage commissioning technicians anchored the qualitative base. Secondary validation drew from EU Green Deal implementation documents, VDE certification registry updates, German Energy Efficiency Act regulatory filings, and hyperscaler capital expenditure disclosures. Bottom-up equipment shipment tallies and top-down facility investment tracking were triangulated against grid interconnection queue data.
Sensitivity analysis tested deployment velocity assumptions across copper price volatility, silicon carbide supply disruption scenarios, and technician labor availability constraints. Segmentation dimensions modeled include power source type, infrastructure scale tier, cooling technology architecture, and end-user vertical across the projection horizon. CAGRs were derived from facility pipeline tracking and equipment order book analysis. Forecast inputs incorporated renewable power purchase agreement pricing trends and waste heat recovery infrastructure cost curves.
Material uncertainties — Bundesnetzagentur queue timeline extensions, VDE recertification cycle disruptions, and carbon border adjustment implementation — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and supply chain continuity. Practitioners should keep alternative scenarios live as hydrogen backup code evolution and rare earth export restriction risks materialize.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Sweden Data Center Rack Market