
 New Zealand Data Center Networking Market | 2026-2036
New Zealand Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Data Center Networking Market Insights
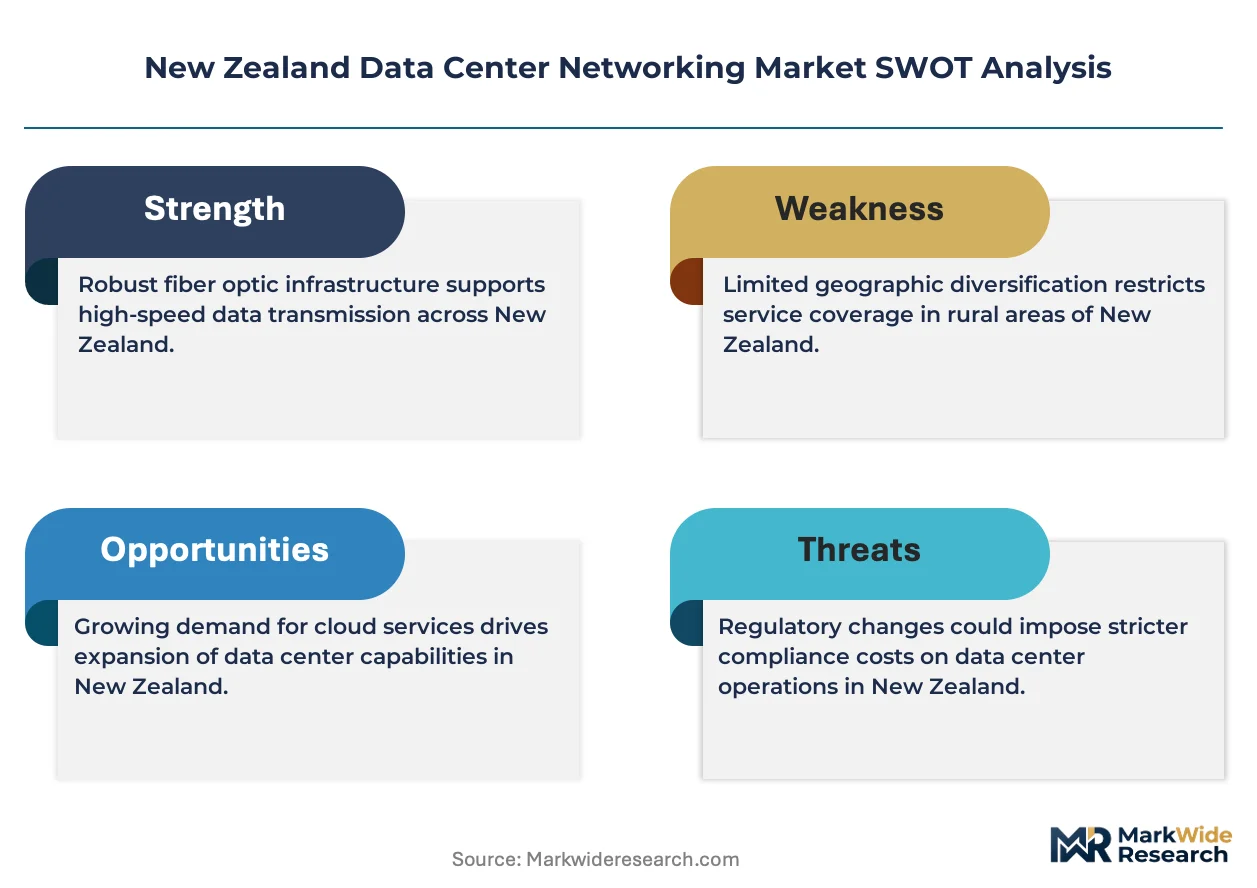
The split between premium spine-leaf architectures and commodity top-of-rack switching is hardening across New Zealand facilities. Cisco Systems Inc. anchors the enterprise segment through deep channel relationships with local systems integrators. Arista Networks Inc. differentiates in cloud-adjacent deployments where low-latency Ethernet fabrics matter most. Huawei Technologies Co. Ltd. competes aggressively on price in the colocation tier despite geopolitical procurement scrutiny.
Data center networking encompasses the switching, routing, and security infrastructure that interconnects servers, storage arrays, and external connectivity within a facility, typically operating at 100 Gbps to 400 Gbps port speeds with sub-microsecond latency requirements. Its primary purpose is to maintain reliable, high-bandwidth data flow for cloud computing, artificial intelligence training clusters, and enterprise application hosting. Ethernet dominates the technology dimension as InfiniBand remains confined to niche high-performance computing environments at the margin. Cloud service providers represent the fastest-expanding end-user category, while colocation facilities harbor mature replacement-cycle demand with thinner margin pools.
The country's national telecommunications regulator and the national cybersecurity agency jointly enforce baseline resilience requirements for operators of nationally significant infrastructure. The Privacy Act and mandatory breach-notification rules shape how networking vendors architect logging, segmentation, and access-control features for local deployment. Stakeholders must weigh the pace of submarine cable capacity expansion against power-grid constraints when sizing network investments for new facility developments.
Market Dynamics
Hyperscale cloud providers are compressing procurement cycles across New Zealand's data center networking sector, forcing incumbent vendors to restructure channel economics and accelerate 400 Gbps migration roadmaps to retain anchor tenancy in Auckland and Christchurch facilities.
Growth Catalysts
- Privacy Act breach-notification mandates:The Privacy Commissioner enforces strict data-handling protocols that drive segmentation and zero-trust architecture investments across financial services and government data centers.
- Submarine cable landings:Capacity expansions at Whenuapai and Takapuna anchor points concentrate interconnection demand in Auckland's northern corridor, pulling fiber and switching infrastructure toward these nodes.
- AI training clusters:GPU-intensive workloads at cloud facilities are forcing spine-leaf fabric upgrades to support east-west traffic patterns that traditional hierarchical designs cannot accommodate.
Market Restraints
- Power-grid constraints:Transpower's transmission bottlenecks in upper North Island limit facility expansion regardless of network equipment availability, capping addressable demand.
- Geopolitical procurement scrutiny:Government and critical infrastructure buyers face political pressure to exclude certain Chinese-origin equipment, narrowing vendor choice and inflating replacement costs.
- Copper and silicon supply volatility:Raw material price swings for high-speed interconnects compress margins on commodity switching hardware, particularly affecting colocation providers with thin capex cycles.
Strategic Opportunities
- Canterbury expansion corridor:Christchurch's emerging hyperscale cluster offers first-mover positioning for vendors willing to pre-position inventory ahead of confirmed facility commitments.
- Renewable energy co-location:Access to Manapouri and Clyde hydro generation creates carbon-neutral hosting propositions that command premium pricing from sustainability-conscious enterprise buyers.
- Network function virtualization convergence:Software-defined networking and security appliance consolidation enable single-vendor stack opportunities that displace discrete hardware procurement.
Industry Challenges
- Sub-microsecond latency engineering:Specialized skill scarcity in RDMA and RoCE protocol optimization constrains deployment velocity for AI-optimized fabrics at cloud facilities.
- Critical infrastructure certification timelines:The national cybersecurity agency's baseline resilience assessments add 4-6 month approval windows that delay revenue recognition on major projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Data Center Networking Market |
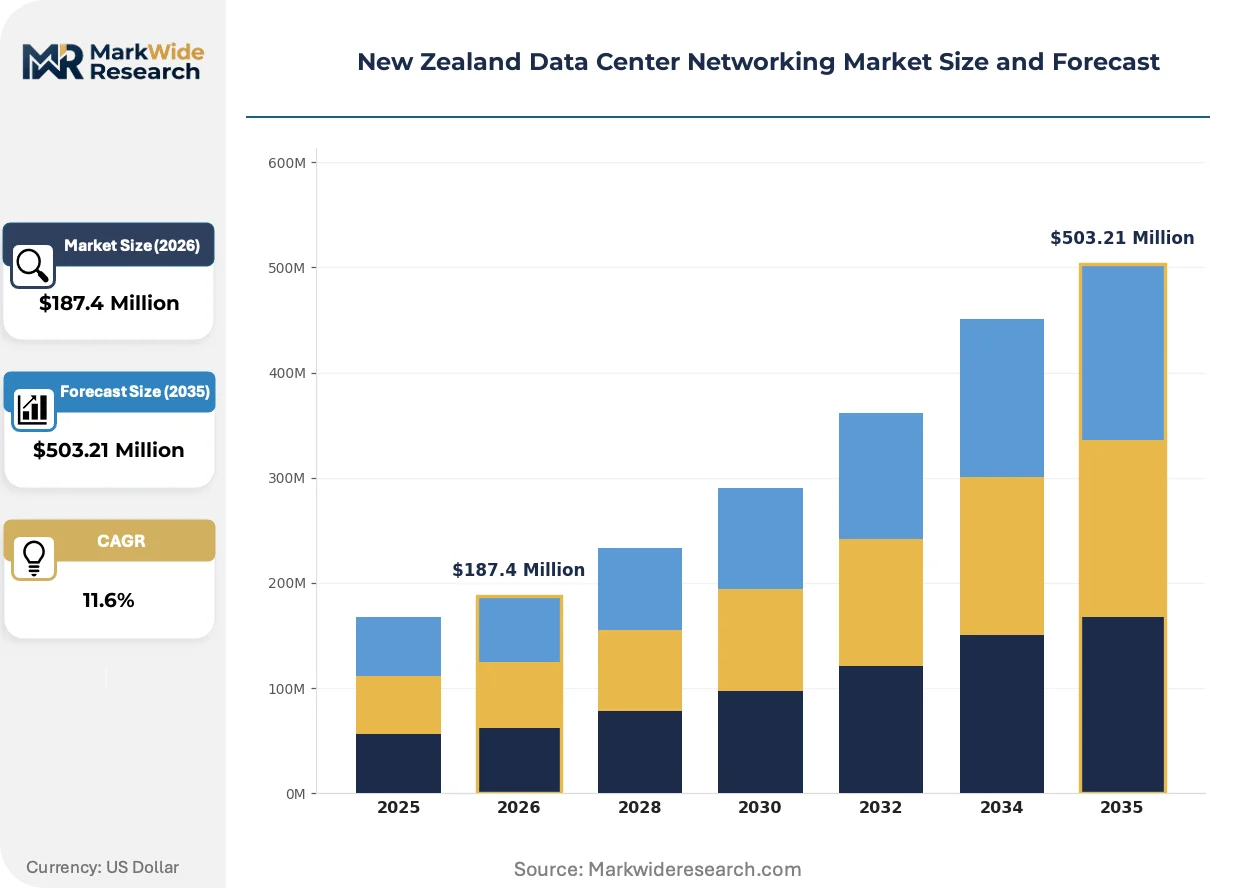
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers Technology: Ethernet, Fiber Channel, InfiniBand, MPLS End User: Cloud Service Providers, Enterprises, Telecom Operators, Colocation Facilities Deployment: On-Premises, Hybrid, Multi-Cloud, Private Cloud |
| Companies Covered | Cisco Systems Inc., Arista Networks Inc., VMware Inc., Huawei Technologies Co. Ltd., Dell Inc., Juniper Networks Inc., Hewlett Packard Enterprise, Broadcom Inc., Fujitsu Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Data Center Networking Market Trends and Innovations
Silicon photonics is rewriting inter-rack economics across New Zealand facilities, while regulatory pressure on operational resilience is hardening procurement specifications and compressing vendor qualification periods.
Co-packaged optics is absorbing the power and density constraints that previously limited 400 Gbps port deployment in edge facilities. Cloud providers in Auckland are adopting this technology faster than enterprise colocation operators, drawn by its 30% reduction in per-bit energy consumption. The structural consequence is a bifurcation in vendor competitiveness, as only suppliers with in-house silicon capabilities can meet the cost and thermal specifications that cloud buyers now demand.
The Privacy Act's mandatory breach-notification framework is forcing logging and segmentation architecture into every network design. Equipment vendors must now pre-integrate telemetry and access-control features that satisfy the Privacy Commissioner's audit protocols. Financial services data centers bear the heaviest compliance burden, with procurement teams requiring documented evidence of native support for these capabilities before vendor shortlisting.
Enterprise buyers are consolidating procurement authority into dedicated infrastructure teams that bypass traditional systems integrator relationships. This disintermediation compresses channel margins and forces direct engagement models on vendors previously reliant on local partners. The shift is most visible among Wellington-based government agencies and crown entities, where centralized procurement functions now issue framework agreements that specify technical standards rather than brand preferences.
New Zealand Data Center Networking Market Segmentation
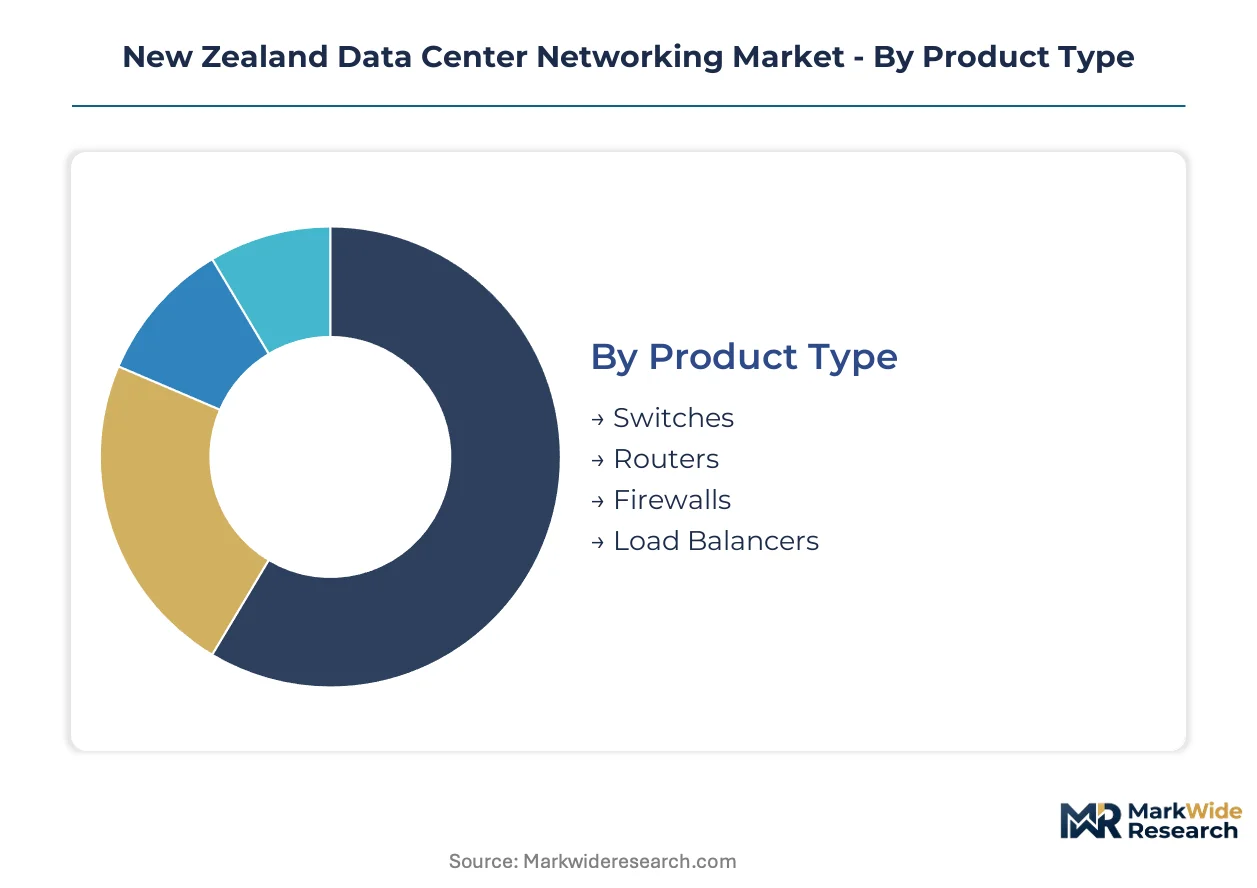
Data center networking procurement in New Zealand fragments across four distinct dimensions. Equipment type, transport protocol, buyer category, and infrastructure ownership model each create separate competitive arenas with divergent margin structures and qualification requirements.
Product Type:
Buyers in this category separate by traffic volume intensity and security posture rather than facility scale alone.
- Switches:Spine-leaf architectures dominate hyperscale deployments in Auckland's northern corridor, where 400 Gbps port densities accommodate GPU cluster east-west traffic. Cloud providers at Whenuapai cable landing points drive demand for low-latency Ethernet fabrics with sub-microsecond switching latency.
- Routers:Border gateway infrastructure at submarine cable termination points requires carrier-grade forwarding capacity. Telecom operators and large enterprises in Christchurch's emerging cluster prioritize programmable routing platforms that support segment routing and traffic engineering for multi-tenant environments.
- Firewalls:Next-generation platforms with integrated intrusion prevention address Privacy Act compliance mandates for financial services data centers in Wellington.
- Load Balancers:Application delivery controllers with container-aware orchestration support microservices architectures at cloud-adjacent colocation facilities.
Switches lead volumes today; firewalls are gaining share fastest.
Technology:
Protocol selection tracks workload type, with AI training clusters forcing divergence from traditional enterprise transport.
- Ethernet:Dominates general-purpose connectivity with 100 Gbps to 400 Gbps port speeds standard across Auckland and Christchurch facilities. RoCEv2 implementations enable RDMA for storage and AI workloads without InfiniBand complexity.
- InfiniBand:Confined to niche high-performance computing environments at research institutions and specialized AI training clusters. The country's small scale limits deployment economics for this premium interconnect technology.
- Fiber Channel:Persists in legacy enterprise storage networks undergoing gradual Ethernet consolidation.
- MPLS:Supports managed WAN services for distributed enterprises with hybrid cloud requirements.
Ethernet leads volumes today; InfiniBand is expanding most quickly at the margin.
End User:
Procurement authority and replacement cycle timing differentiate buyers more than absolute spending power.
- Cloud Service Providers:Hyperscale operators compress hardware refresh cycles to 18-24 months, demanding 400 Gbps readiness and co-packaged optics for power efficiency. Their Auckland and Christchurch facility commitments anchor vendor revenue recognition.
- Colocation Facilities:Mature replacement demand with thinner margins concentrates in Auckland's established northern corridor. These buyers prioritize interoperability and multi-vendor support to avoid tenant lock-in.
- Enterprises:Crown entities and Wellington-based government agencies centralize procurement through framework agreements specifying technical standards over brand preferences.
- Telecom Operators:National carriers invest in core and edge routing to support 5G backhaul and submarine cable termination capacity.
Colocation facilities lead volumes today; cloud service providers are climbing the fastest.
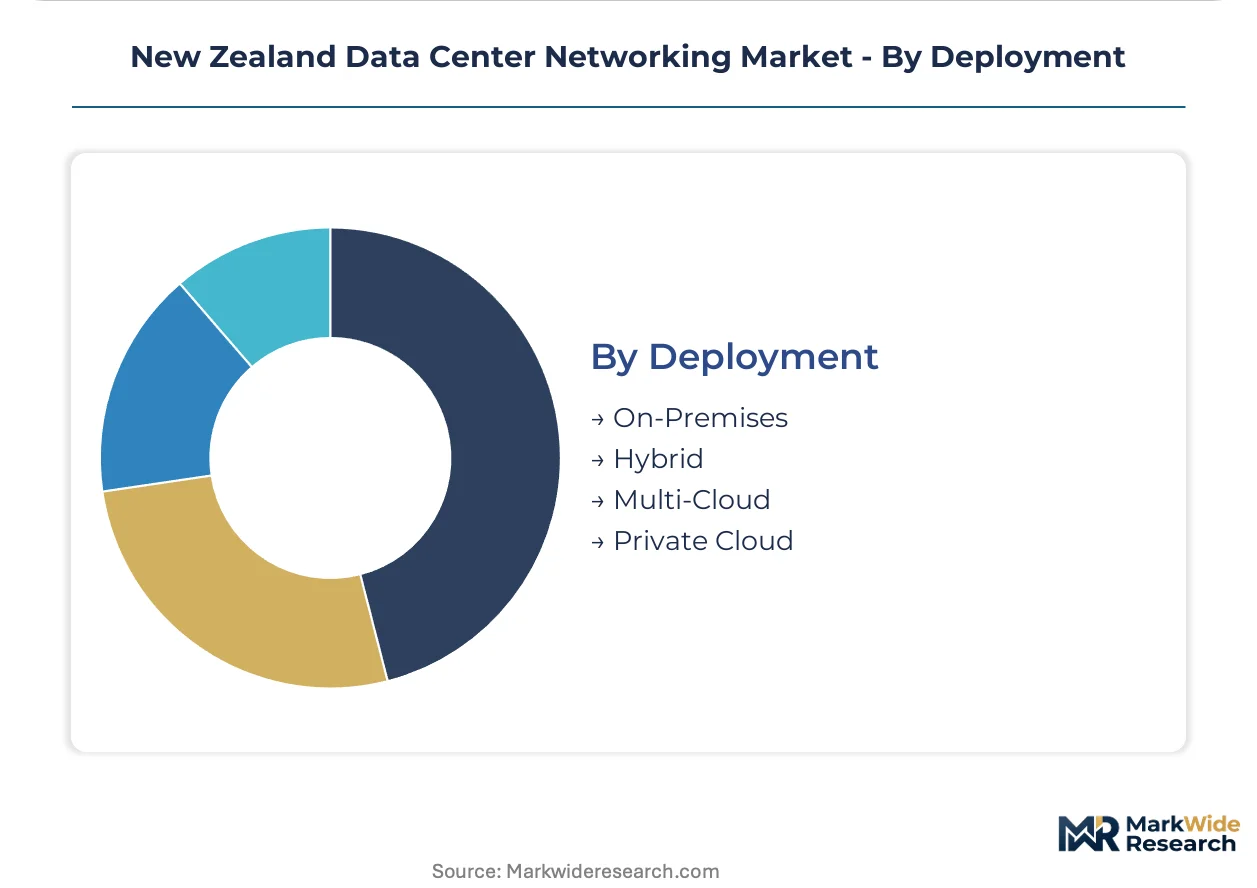
Deployment:
Infrastructure ownership models reflect data sovereignty requirements and capital availability constraints.
- On-Premises:Financial services and government agencies in Wellington maintain captive facilities to satisfy Privacy Act data residency mandates. These deployments require on-site networking hardware with comprehensive logging and segmentation capabilities.
- Hybrid:Enterprises split workloads between owned infrastructure and cloud platforms, demanding consistent networking policies across boundaries. This model dominates mid-market buyers seeking flexibility without full cloud commitment.
- Private Cloud:Single-tenant dedicated environments appeal to regulated industries requiring isolation without capital expenditure.
- Multi-Cloud:Advanced buyers distribute across multiple hyperscale platforms, requiring sophisticated interconnection and orchestration layers.
On-premises leads volumes today; hybrid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Network engineering talent concentrates in Auckland's northern corridor, where submarine cable landings and hyperscale facility construction create specialized labor demand. This workforce distribution shapes procurement patterns and vendor engagement models across New Zealand's data center networking sector.
Auckland Northern Corridor
Hyperscale cloud providers at Whenuapai and Takapuna cable landing points drive 400 Gbps spine-leaf fabric demand. The Privacy Act's breach-notification mandates enforce segmentation and zero-trust investments at financial services facilities. Auckland's northern corridor anchors the country's densest interconnection ecosystem.
Christchurch
Christchurch's emerging hyperscale cluster attracts first-mover vendors pre-positioning inventory ahead of confirmed facility commitments. Transpower's transmission infrastructure in Canterbury offers more headroom than upper North Island constraints. The city's renewable energy access supports carbon-neutral hosting propositions.
Wellington
Crown entities and government agencies centralize procurement through framework agreements specifying technical standards over brand preferences. The Privacy Commissioner enforces strict data-handling protocols across public sector data centers. Wellington maintains captive on-premises facilities to satisfy data residency mandates.
Waikato
Hamilton's proximity to Auckland creates secondary demand for edge networking infrastructure serving distributed enterprise workloads. Power-grid constraints are less severe than in upper North Island transmission bottlenecks. Regional colocation facilities prioritize interoperability to serve multi-tenant hybrid cloud deployments.
New Zealand Data Center Networking Market Competitive Landscape
Top-tier vendors anchor hyperscale cloud deployments, while mid-tier specialists serve colocation and enterprise replacement cycles. The market structure reflects procurement authority consolidation and compressed hardware refresh timelines. Three archetypes dominate: full-stack infrastructure providers, Ethernet fabric specialists, and security-integrated networking vendors. Competitive moves center on channel restructuring and 400 Gbps migration acceleration.
Within the full-stack infrastructure tier, Cisco Systems Inc. and Dell Inc. occupy positions shaped by deep channel relationships with local systems integrators. Arista Networks Inc. exemplifies the Ethernet fabric specialist archetype in cloud-adjacent deployments where low-latency requirements matter most. Huawei Technologies Co. Ltd. represents price-competitive positioning in the colocation tier despite geopolitical procurement scrutiny affecting government and critical infrastructure buyers.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Arista Networks Inc. |
| VMware Inc. |
| Huawei Technologies Co. Ltd. |
| Dell Inc. |
| Juniper Networks Inc. |
| Hewlett Packard Enterprise |
| Broadcom Inc. |
| Fujitsu Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud provider concentration in Auckland's northern corridor anchors contract-based procurement with volume-scaled unit economics. Their 18-24 month refresh cycles compress margin pools for switching hardware vendors while privileging suppliers with captive silicon capabilities.
Pricing Analysis
Bundled hardware-software support contracts dominate hyperscale procurement, while unbundled component sourcing persists in colocation and enterprise tiers. Three-tier pricing structure across premium spine-leaf fabrics, standard top-of-rack switching, and economy-grade edge deployments tracks port density and latency specifications. Cost compression in the commodity switching tier intensifies because copper and silicon supply volatility compresses hardware margins. Colocation providers exhibit highest price sensitivity due to thin capex cycles and multi-vendor interoperability requirements, while cloud providers prioritize performance-per-watt metrics over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced switching ASICs, while China dominates passive component and optical transceiver manufacturing. New Zealand facilities draw from these geographies for spine-leaf fabrics, power-efficient silicon, and co-packaged optics modules. Tariff exposure on Chinese-origin equipment creates procurement friction for government and critical infrastructure buyers. Distribution runs through Auckland-based systems integrators and direct vendor engagement with hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Privacy Act's mandatory breach-notification framework compounds demand for segmentation-capable networking infrastructure, creating sustained procurement tailwinds across financial services and government verticals.
For Market Incumbents: Deepen channel control through exclusive framework agreements with Wellington-based crown entities and centralized procurement functions. Accelerate 400 Gbps co-packaged optics roadmaps to defend against Arista's cloud-adjacent positioning. Invest in native telemetry and zero-trust architecture pre-integration to satisfy Privacy Commissioner audit protocols and extend replacement cycle capture. For New Entrants and Emerging Players: The price-point gap between Arista's premium Ethernet fabrics and Huawei's economy colocation offerings creates white-space positioning for mid-tier specialists. Target Christchurch's emerging hyperscale cluster with pre-positioned inventory ahead of confirmed facility commitments. Pursue direct engagement models with Canterbury-based renewable energy co-location providers seeking carbon-neutral networking propositions. For Investors and Strategic Acquirers: Cloud service providers are the most active acquirer in this space, seeking vertical integration into networking silicon and software-defined orchestration layers. Target acquisition archetypes include RDMA protocol optimization specialists and security-integrated networking vendors with Privacy Act compliance toolkits. Watch Transpower's transmission infrastructure expansion timelines as the critical inflection signal for addressable demand ceiling adjustments.| Strategic Initiative | Industry Significance |
|---|---|
| 400 Gbps Spine-Leaf Migration | Co-packaged optics adoption at Whenuapai hyperscale facilities reduces per-bit energy consumption for GPU cluster workloads. |
| Zero-Trust Architecture Integration | Native segmentation capabilities satisfy Privacy Commissioner mandates across Wellington financial services data centers. |
| Christchurch Pre-Positioning | Inventory staging ahead of confirmed facility commitments captures first-mover advantage in Canterbury's emerging cluster. |
| Renewable Energy Co-Location | Manapouri and Clyde hydro access enables carbon-neutral hosting premiums from sustainability-conscious enterprise buyers. |
| Channel Disintermediation | Direct hyperscale engagement models compress systems integrator margins and accelerate vendor revenue recognition. |
Research Methodology
Multiple input streams — hyperscaler capex disclosures, submarine cable landing authority filings, and Privacy Commissioner enforcement records — were reconciled against primary interviews with data center engineering directors, network procurement leads at crown entities, and channel sales heads at Auckland-based systems integrators. Secondary validation drew from Transpower infrastructure planning documents, national cybersecurity agency baseline resilience assessments, and customs records for networking equipment imports. Bottom-up facility-level capacity estimates and top-down telecommunications infrastructure spending aggregates were triangulated to anchor market sizing.
Data-stream reconciliation across equipment type, transport protocol, buyer category, and infrastructure ownership model enabled segmented growth trajectory modeling over the projection horizon. Analytical frameworks incorporated port speed migration curves, AI workload penetration rates, and regulatory compliance investment cycles as industry-specific forecast inputs. CAGRs were derived from facility commitment timelines and replacement cycle compression patterns observed across Auckland and Christchurch deployments.
Caveats apply where Transpower transmission bottlenecks, geopolitical procurement restrictions, or silicon supply disruptions could materially shift the outlook for addressable demand. Forecasts reflect assumptions about hyperscale facility completion schedules and Privacy Act enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
Hong Kong Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
Europe Subscriber Data Management Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Managed DNS Services Market
Data Center and Networking
Japan Data Center Server Market