
 Mobile Data Traffic Market | 2026-2036
Mobile Data Traffic Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Data Traffic Market Foresight
Platform licensing revenue from edge computing and content delivery networks is reshaping how carriers monetize infrastructure. AT&T Inc. leverages its fiber-wireless convergence to capture enterprise workloads that require guaranteed latency. China Mobile Ltd. anchors the largest subscriber base globally, sustaining capital intensity through government-backed 5G deployment timelines. Verizon Communications Inc. differentiates in millimeter-wave spectrum depth, competing for fixed wireless access substitution in broadband markets.
Mobile data traffic encompasses all digital information transmitted over cellular and wireless wide-area networks, measured in bytes per second across radio access interfaces, backhaul links, and core packet gateways; it serves the primary commercial purpose of enabling real-time communication, entertainment, and machine-to-machine coordination at scale. Video Streaming within the Application dimension dominates bandwidth consumption, with margin pools concentrating at content delivery nodes rather than transport layers. 5G within the Technology dimension captures the fastest infrastructure investment trajectory, while Wi-Fi 6 competes for indoor offload in enterprise and residential environments.
The Federal Communications Commission in the United States auctions mid-band spectrum to accelerate 5G densification, while the European Commission enforces the EU Electronic Communications Code to harmonize wholesale access terms across member states. India's Telecom Regulatory Authority mandates floor pricing and interconnect charges that directly shape carrier revenue models and network investment cycles. Stakeholders must monitor spectrum allocation calendars and net neutrality rulemaking across jurisdictions to anticipate capacity cost curves and service pricing flexibility.
Market Dynamics
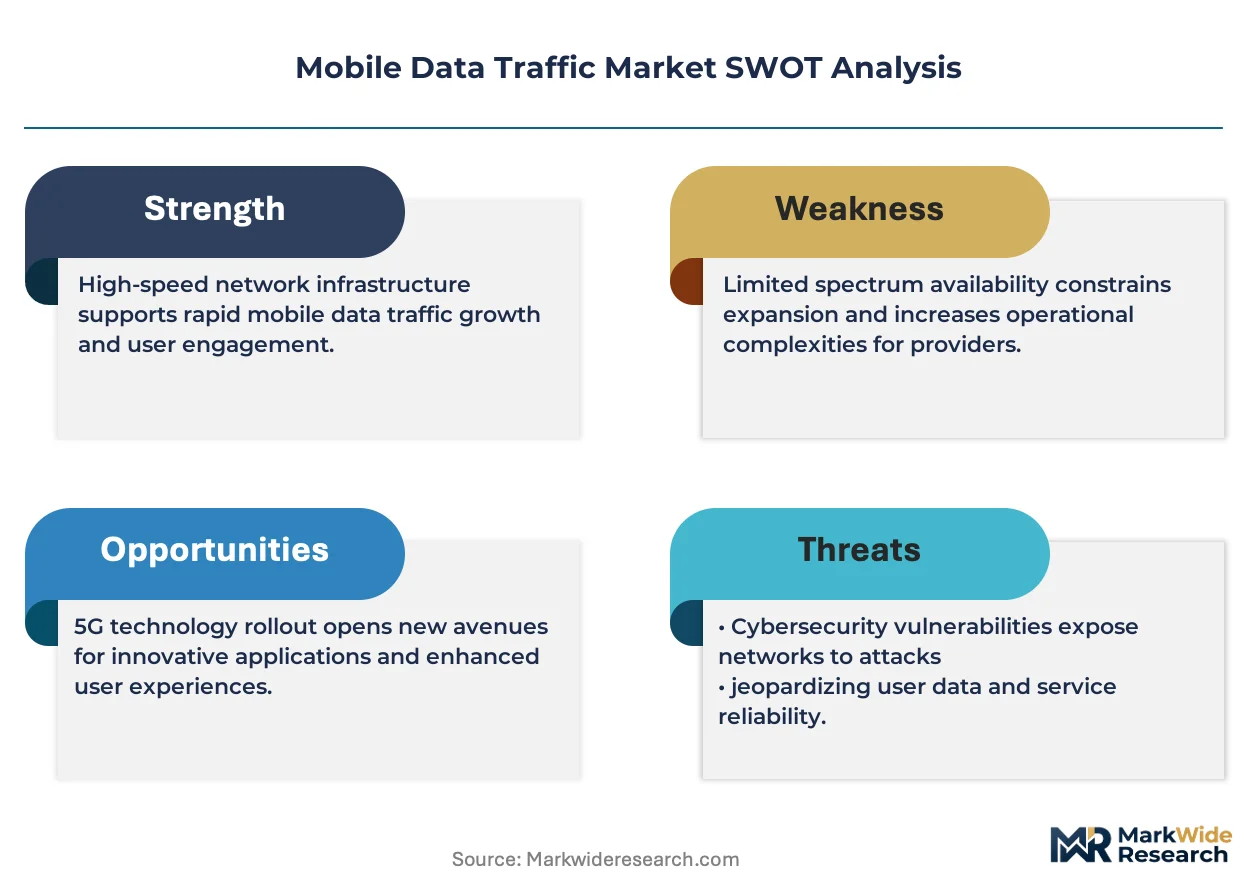
5G network densification is compressing latency thresholds below 10 milliseconds, forcing carriers to rearchitect backhaul and core networks while spectrum auctions in multiple jurisdictions accelerate capital deployment cycles.
Growth Catalysts
- Mid-band spectrum allocation:The Federal Communications Commission's C-band auctions in the United States unlocked 280 MHz of contiguous spectrum, enabling nationwide 5G coverage expansion and enterprise service penetration.
- Video streaming infrastructure:Content delivery networks now absorb the majority of mobile bandwidth, driving continuous investment in edge computing nodes and caching layers closer to radio access networks.
- Fixed wireless access substitution:Millimeter-wave deployments in suburban broadband markets displace copper and coaxial last-mile infrastructure, opening new subscriber acquisition channels for mobile operators.
Market Restraints
- Site acquisition friction:Municipal zoning and historical preservation restrictions in dense urban centers delay small cell deployment timelines and inflate permitting costs for network densification.
- Semiconductor supply concentration:Baseband processor and radio frequency front-end module production concentrates among a limited supplier base, creating vulnerability to foundry capacity constraints and export control disruptions.
- Power consumption thresholds:Massive MIMO antenna arrays and edge data centers face escalating electricity costs and grid interconnection delays that constrain network expansion economics.
Strategic Opportunities
- Private 5G networks:Manufacturing facilities and port logistics hubs in Germany and Japan are deploying non-public networks for deterministic machine control, creating new vertical service revenue streams.
- Network slicing monetization:3GPP Release 16 capabilities enable guaranteed bandwidth contracts for autonomous vehicle telemetry and remote surgery applications with strict quality-of-service requirements.
- Spectrum sharing frameworks:India's dynamic spectrum access regulations permit unlicensed industrial IoT deployments in guard bands, lowering entry barriers for agricultural and mining automation.
Industry Challenges
- Radio frequency engineering talent scarcity:The specialized skill set for millimeter-wave propagation modeling and beamforming algorithm development faces acute shortage across carrier engineering organizations.
- Interoperability certification complexity:Multi-vendor open RAN deployments require extended integration testing across disaggregated radio units, distributed units, and centralized units before commercial launch.
- Legacy 4G core migration:Carriers must maintain parallel operations during the transition to 5G standalone architecture, duplicating operational expenses and complicating subscriber management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Data Traffic Market |
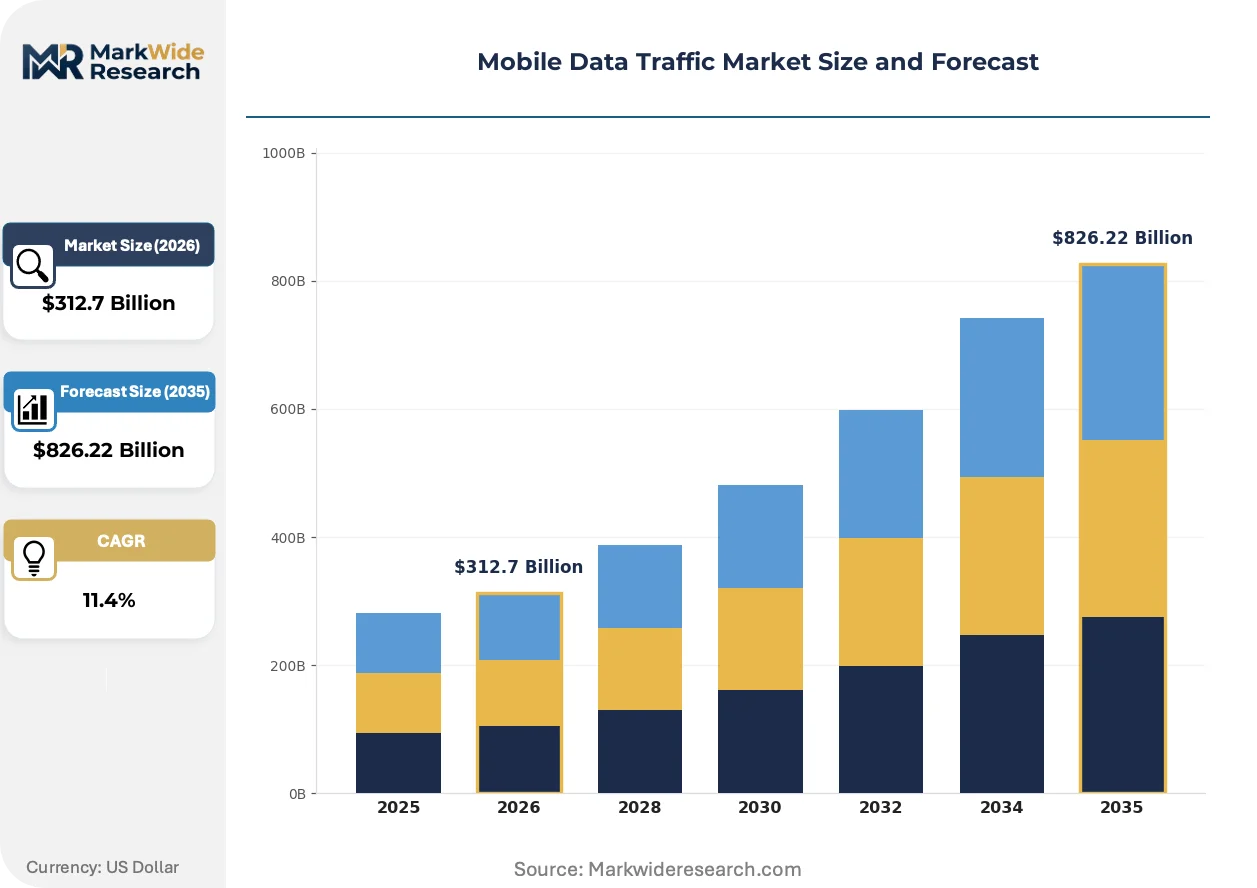
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 3G, 4G, 5G, Wi-Fi 6 End User: Smartphone Users, Tablet Users, IoT Devices, Wearable Devices Application: Video Streaming, Online Gaming, Social Media, Web Browsing Service Type: Data Plans, Prepaid Services, Postpaid Services, Unlimited Packages |
| Companies Covered | AT&T Inc., China Mobile Ltd., Verizon Communications Inc., China Telecom Corp., Ltd., Deutsche Telekom AG, Vodafone Group Plc, Reliance Jio Infocomm Limited, Nippon Telegraph and Telephone Corporation, Telefonica SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Data Traffic Market Shifts & Advancements
Network function virtualization is dissolving the boundary between hardware-centric and software-defined infrastructure, enabling programmable service chains that adapt to traffic patterns in real time.
Open RAN architectures are virtualizing baseband processing functions that previously ran on proprietary hardware, allowing mobile operators to mix radio vendors and reduce supplier lock-in. Tier-one carriers in Japan and the United States are piloting multi-vendor deployments for urban macro sites. This shift is virtualizing capital allocation models, transforming network builds from equipment purchases to software license and integration service contracts.
The European Commission's Gigabit Infrastructure Act mandates fiber backhaul for all new 5G sites receiving public funding, accelerating convergence between fixed and wireless network investments. Member states must transpose these rules by mid-2026, tightening construction timelines for rural coverage obligations. Wholesale access obligations under the EU Electronic Communications Code are forcing incumbent carriers to open dark fiber to mobile network operators at regulated rates.
Enterprise buyers now demand consumption-based pricing for private network deployments rather than capital-intensive build-transfer-operate models. System integrators and hyperscale cloud providers are capturing this transition, bundling connectivity with edge computing and security stacks. Manufacturing verticals in South Korea and automotive facilities in Germany show the fastest migration toward subscription-based network service contracts.
Mobile Data Traffic Market Segmentation
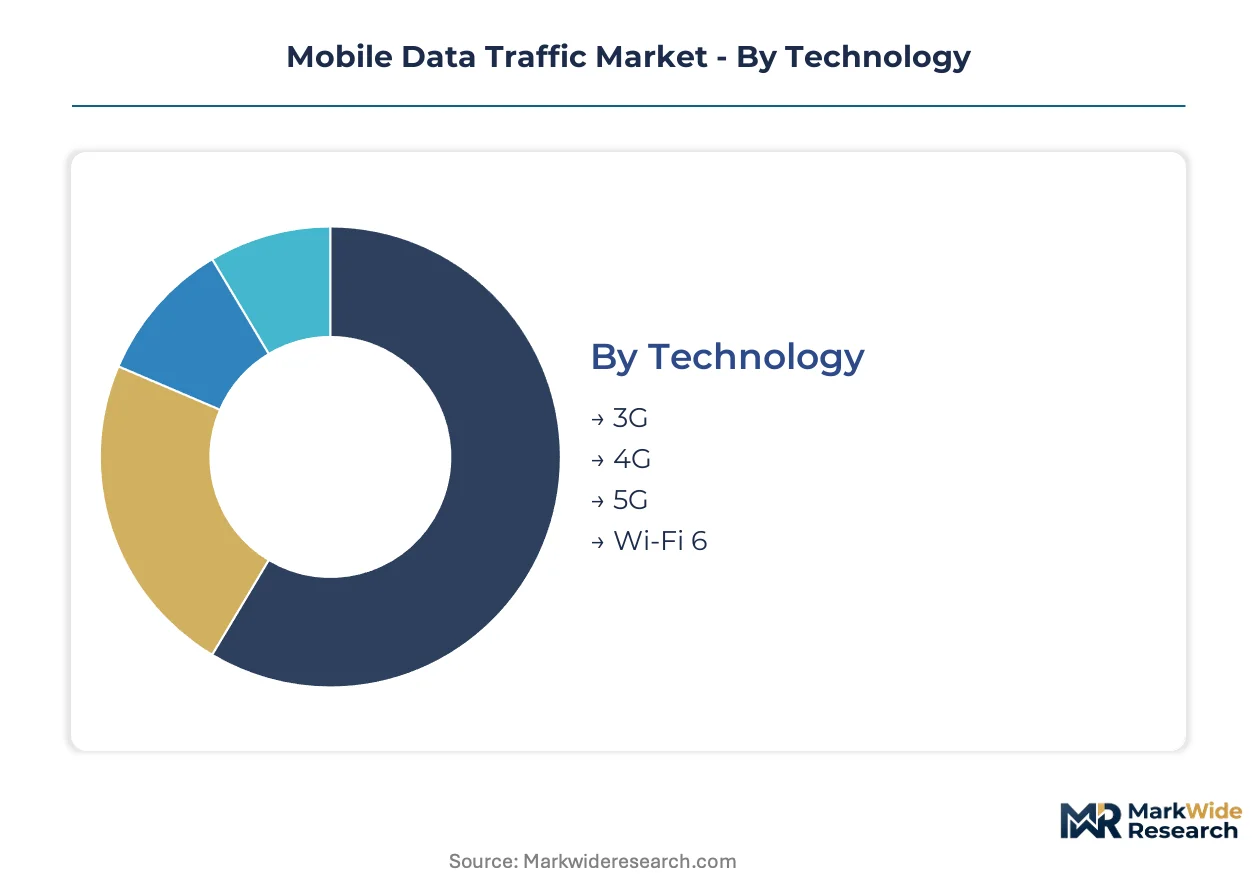
Segmentation reveals how infrastructure investments, device ecosystems, and monetization models diverge across technical and commercial dimensions. Understanding these splits enables carriers to allocate spectrum resources and engineer service tiers that match actual consumption patterns rather than assumed averages.
Technology:
After-sales service intensity varies sharply across generations, with 5G deployments demanding continuous optimization of beamforming algorithms and edge node management that 4G never required.
- 5G:Massive MIMO arrays and millimeter-wave propagation require real-time network tuning and software-defined radio updates. Demand concentrates in South Korea and Germany for industrial automation and fixed wireless access substitution, driven by manufacturing verticals seeking deterministic latency below 10 milliseconds.
- 4G:Mature LTE-Advanced infrastructure continues carrying the majority of subscriber volume through carrier aggregation and small cell densification. India and Indonesia anchor sustained investment here, where spectrum refarming and VoLTE migration extend asset life cycles amid delayed 5G standalone transitions.
- 3G:Legacy WCDMA networks remain operational for machine-to-machine telemetry and rural voice fallback in Sub-Saharan Africa and parts of Southeast Asia.
- Wi-Fi 6:Orthogonal frequency-division multiple access and target wake time protocols enable dense indoor deployments for enterprise campuses and stadium venues.
By volume, 4G leads. By growth pace, 5G is ahead.
End User:
Device refresh cycles and power constraints create distinct traffic signatures that shape core network dimensioning and caching strategies.
- Smartphone Users:Handheld devices generate bursty, location-aware traffic patterns with high video pre-buffering ratios. Urban corridors in Brazil and Vietnam show the steepest per-capita consumption curves, propelled by short-form video platforms and super-app ecosystems.
- IoT Devices:Sensors and actuators transmit small-packet, latency-tolerant telemetry at massive scale. Logistics hubs in the Netherlands and agricultural monitoring networks in Australia concentrate deployment, driven by supply chain traceability mandates and precision irrigation economics.
- Tablet Users:Larger screens sustain longer session durations with higher resolution video streams, particularly in education and field service workflows.
- Wearable Devices:Low-power wide-area connectivity supports health telemetry and navigation assistance with strict battery life constraints.
Smartphone Users dominate absolute traffic volume. IoT Devices are expanding most quickly.
Application:
Content encoding efficiency and peak-to-average ratios determine where edge computing investments deliver measurable quality-of-service improvements.
- Video Streaming:Adaptive bitrate algorithms consume disproportionate bandwidth during evening peak hours. Metropolitan clusters in Mexico and the Philippines drive infrastructure strain, fueled by over-the-top platform competition and mobile-first entertainment consumption.
- Online Gaming:Real-time multiplayer and cloud gaming services demand consistent sub-50 millisecond latency with minimal jitter. Esports venues in Sweden and mobile gaming arcades in Japan anchor specialized network slicing pilots, pressured by tournament-grade reliability requirements.
- Social Media:Asymmetric upload patterns from user-generated content stress uplink capacity in ways downlink-heavy video does not.
- Web Browsing:Lightweight transactional traffic remains significant in absolute volume despite shrinking per-session data intensity.
Video Streaming leads by volume. Online Gaming shows the steepest expansion trajectory.
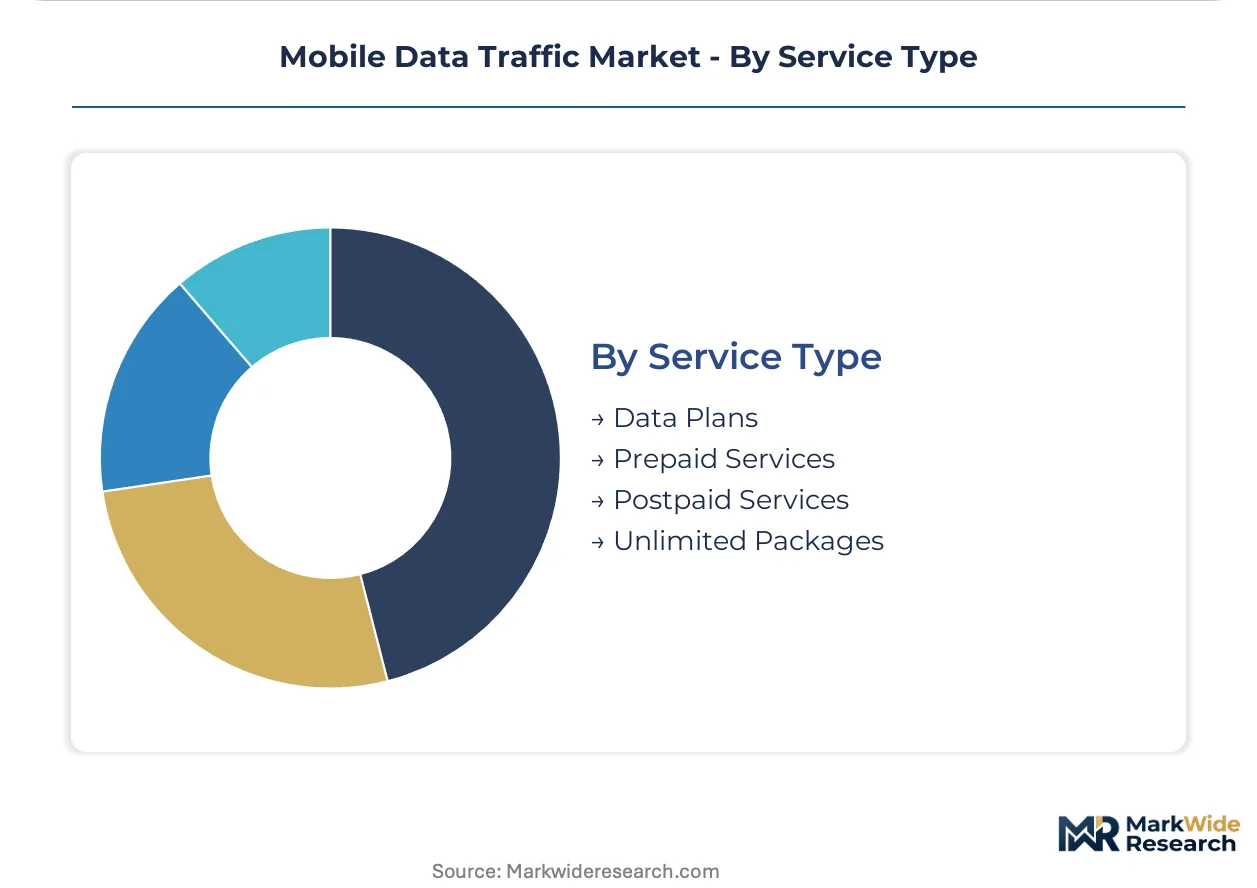
Service Type:
Pricing architecture and billing flexibility separate markets with mature postpaid penetration from those where prepaid dominates.
- Unlimited Packages:Flat-rate data allowances eliminate overage anxiety and encourage unconstrained consumption. Competitive markets in Finland and Chile show the fastest migration toward these tiers, pressured by operator differentiation strategies and subscriber churn reduction targets.
- Prepaid Services:Pay-as-you-go models dominate in cash-based economies with thin credit infrastructure. Nigeria and Bangladesh concentrate activation volume, driven by informal employment patterns and minimal documentation requirements for SIM registration.
- Postpaid Services:Contractual commitments bundle device financing with service plans in mature markets with established credit bureaus.
- Data Plans:Tiered allowances with overage charges persist in enterprise and machine-to-machine segments where predictability outweighs flexibility.
Unlimited Packages lead by subscriber growth. Prepaid Services retain the largest absolute user base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian subscribers consume the world's highest per-capita data volumes at rock-bottom tariffs, while German industrial buyers pay premiums for guaranteed latency. Brazilian urban corridors show price-sensitive volume growth, and South Korean manufacturing verticals prioritize reliability over cost.
United States
Fixed wireless access substitution and enterprise edge computing drive carrier investment. The FCC's C-band auctions released 280 MHz of mid-band spectrum for nationwide 5G coverage. Dallas-Fort Worth and Atlanta metro clusters anchor millimeter-wave densification for suburban broadband competition.
India
Reliance Jio's price disruption pushed per-capita consumption past developed-market levels. TRAI mandates floor pricing and interconnect charges that reshape carrier revenue models. Mumbai and Bangalore concentrate 5G standalone deployment amid spectrum refarming from 2G and 3G legacy bands.
Germany
Industrial automation and private 5G networks for manufacturing facilities dominate demand. The Gigabit Infrastructure Act mandates fiber backhaul for publicly funded 5G sites by mid-2026. Hamburg and Ruhr Valley logistics hubs deploy non-public networks for deterministic machine control.
South Korea
Cloud gaming and esports venues require sub-10 millisecond latency with tournament-grade reliability. METI-aligned spectrum policy accelerates 28 GHz millimeter-wave allocation for indoor enterprise coverage. Seoul Capital Area and Busan-Ulsan corridor lead network slicing pilots for automotive and semiconductor fabs.
Brazil
Short-form video platforms and super-app ecosystems fuel bursty traffic in urban corridors. ANATEL's 5G spectrum auctions in 2021 unlocked 3.5 GHz bands for major metro coverage. São Paulo and Rio de Janeiro concentrate infrastructure strain from evening peak video consumption.
Mobile Data Traffic Market Competitive Landscape
Integrated national carriers and specialist wholesale operators split the market along infrastructure ownership lines. The structure consolidates around spectrum depth and fiber backhaul density rather than subscriber scale alone. Three archetypes dominate: vertically integrated incumbents with converged fixed-wireless assets, mobile-first challengers with aggressive pricing and digital distribution, and state-backed operators with guaranteed deployment timelines. Competitive moves center on spectrum auction participation and edge computing partnership structures with hyperscale cloud providers.
Within the state-backed tier, China Mobile Ltd. and China Telecom Corp., Ltd. occupy positions shaped by government-directed 5G deployment schedules. Among integrated incumbents, AT&T Inc. and Verizon Communications Inc. exemplify fiber-wireless convergence strategies targeting enterprise workloads. Deutsche Telekom AG sits within the European multinational archetype, balancing domestic market density against cross-border infrastructure sharing agreements.
| Leading Market Players |
|---|
| AT&T Inc. |
| China Mobile Ltd. |
| Verizon Communications Inc. |
| China Telecom Corp., Ltd. |
| Deutsche Telekom AG |
| Vodafone Group Plc |
| Reliance Jio Infocomm Limited |
| Nippon Telegraph and Telephone Corporation |
| Telefonica SA |
| Others |
Supply & Pricing Matrix
Underutilization of millimeter-wave spectrum assets in suburban United States markets is compressing carrier pricing power while forcing equipment vendors to extend financing terms for baseband processor procurement. This utilization gap simultaneously softens service pricing in fixed wireless access tiers and stretches supplier payment cycles as network densification timelines slip.
Pricing Analysis
After-sales service revenue from edge computing node management and network optimization contracts now drives lifetime value for infrastructure vendors. Three-tier pricing structure across premium, standard, and economy levels separates carriers with guaranteed latency commitments from best-effort consumer tiers. Cost compression in mid-band spectrum leases is intensifying because FCC auction clearing timelines remain uncertain. Prepaid subscribers in cash-based economies exhibit the highest price sensitivity, while enterprise buyers with deterministic latency requirements show minimal elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement relationships for massive MIMO antenna arrays, reflecting carrier cash flow pressures post-spectrum auction. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with radio frequency front-end module assembly anchored in Vietnam and Mexico. Supply chain risk centers on single-source vulnerability for 5-nanometer baseband processors. Distribution runs through carrier-direct procurement for macro sites and systems integrator channels for private network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of radio frequency engineering talent capable of millimeter-wave propagation modeling is constraining deployment velocity and inflating compensation costs for specialized beamforming algorithm developers. This capability gap limits how quickly carriers can monetize spectrum depth.
For Market Incumbents: Pre-empt Open RAN vendor fragmentation by certifying multi-vendor radio unit combinations before competitors complete integration testing. Lock fiber backhaul density in suburban corridors where millimeter-wave fixed wireless access threatens copper displacement. Vertical integration into edge data center real estate protects margin pools as hyperscale cloud providers encroach on network slicing revenue. For New Entrants and Emerging Players: Agricultural IoT networks in India's guard-band spectrum allocations represent the most penetrable entry point for unlicensed industrial automation deployments. Private 5G networks for German automotive suppliers offer second-mover advantages as incumbent carriers struggle with legacy 4G core migration complexity. Partner with systems integrators bundling connectivity with precision agriculture sensors to bypass direct carrier competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across standalone 5G core infrastructure as parallel operations with legacy networks duplicate operational expenditure. Target acquisition candidates with proven Open RAN integration capabilities and existing fiber backhaul rights-of-way in metropolitan clusters. Monitor FCC spectrum auction clearing timelines as the signal indicating when carrier free cash flow inflects toward network densification or shareholder returns.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Portfolio Deepening | Mid-band acquisition in C-band and 3.5 GHz ranges determines nationwide 5G coverage competitiveness against Verizon's millimeter-wave depth. |
| Fiber-Backhaul Convergence | AT&T's fiber-wireless integration model captures enterprise workloads requiring sub-10 millisecond latency guarantees. |
| Private Network Verticalization | Non-public 5G deployments for German manufacturing facilities create recurring revenue streams detached from consumer price wars. |
| Open RAN Certification | Multi-vendor radio unit integration reduces supplier lock-in but demands extended testing cycles before commercial launch. |
| Edge Computing Partnership | Hyperscale cloud provider alliances transform carrier revenue from transport pipes to platform licensing and managed services. |
Research Methodology
Operator-level perspectives from network engineering directors, spectrum strategy leads, infrastructure procurement managers, and regulatory affairs officers anchored the qualitative base. Primary interviews triangulated with secondary validation from FCC auction results, TRAI tariff orders, EU Electronic Communications Code implementation reports, and carrier capital expenditure disclosures. Bottom-up traffic volume modeling across smartphone, IoT, and enterprise segments converged with top-down market sizing from spectrum allocation calendars and device shipment forecasts.
Scenario-bracketing around low, base, and high 5G adoption cases structured the analytical framework across the projection horizon. Segmentation dimensions modeled include technology generation, end-user device category, application type, and service pricing architecture. CAGRs derived from subscriber growth curves, per-capita consumption trajectories, and average revenue per user trends. Industry-specific inputs incorporated beamforming equipment cost curves and edge node deployment densities.
Macroeconomic conditions sit as an overlay; deviation in carrier debt financing costs, semiconductor foundry capacity utilization, or electricity grid interconnection timelines would shift the trajectory. Forecasts reflect documented assumptions about spectrum clearing schedules, Open RAN interoperability timelines, and net neutrality rulemaking stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Application Delivery Network (ADN) Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
United Kingdom Data Center Networking Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Network Connectivity Tester Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Graph Database Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Global Data Management Platform Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
South Korea Data Center Networking Market