
 Global Cloud Content Delivery Network Market | 2026-2036
Global Cloud Content Delivery Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Content Delivery Network Market Foresight
Edge computing integration with serverless architectures is reconfiguring how cloud CDNs cache, process, and deliver dynamic content at the network periphery. Akamai Technologies anchors its position through one of the world's most distributed edge platforms, spanning thousands of global points of presence. Cloudflare differentiates by embedding zero-trust security directly into its CDN fabric, reducing latency for enterprise workloads. Google Cloud CDN leverages its private fiber backbone to sustain sub-second delivery benchmarks for video and API traffic.
A cloud content delivery network constitutes a geographically distributed server infrastructure that caches web content—HTML pages, images, video streams, and API responses—at edge nodes positioned within 10-50 milliseconds of end users, thereby reducing origin server load and improving transfer speeds. Its primary commercial purpose is to guarantee consistent application performance regardless of user location or traffic spikes. Cloud-native deployment leads the infrastructure mix because hyperscale providers have abstracted provisioning into API-driven workflows that eliminate hardware procurement cycles. Video streaming acceleration captures the fastest growth trajectory within the solution layer, driven by 4K and live event broadcasting requirements that demand sub-two-second latency thresholds.
The EU GDPR and the EU AI Act impose strict data residency and algorithmic transparency mandates that shape how CDN providers architect European node networks and logging practices. The US FCC maintains net neutrality oversight that influences interconnection agreements between CDN operators and last-mile internet service providers. India's TRAI and BIS standards for cloud infrastructure certification create additional compliance thresholds for foreign providers seeking direct presence in the subcontinent. Stakeholders must monitor evolving data localization statutes and edge sovereignty requirements as determinants of infrastructure capex allocation and partnership strategy.
Market Dynamics
Edge-integrated serverless architectures are compressing the distance between compute and consumption, forcing CDN providers to rebuild infrastructure around sub-50-millisecond latency guarantees rather than simple cache proximity.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency and data residency requirements under the EU AI Act are compelling providers to deploy sovereign edge nodes within European borders, expanding addressable infrastructure spend.
- Live video streaming protocols:Low-latency streaming standards for 4K broadcast and interactive gaming are pulling compute to the network periphery, accelerating serverless edge adoption across media distribution networks.
- India's digital infrastructure push:TRAI-mandated cloud certification and government broadband initiatives in tier-two cities are opening new CDN deployment corridors previously unreachable by hyperscale backbones.
Market Restraints
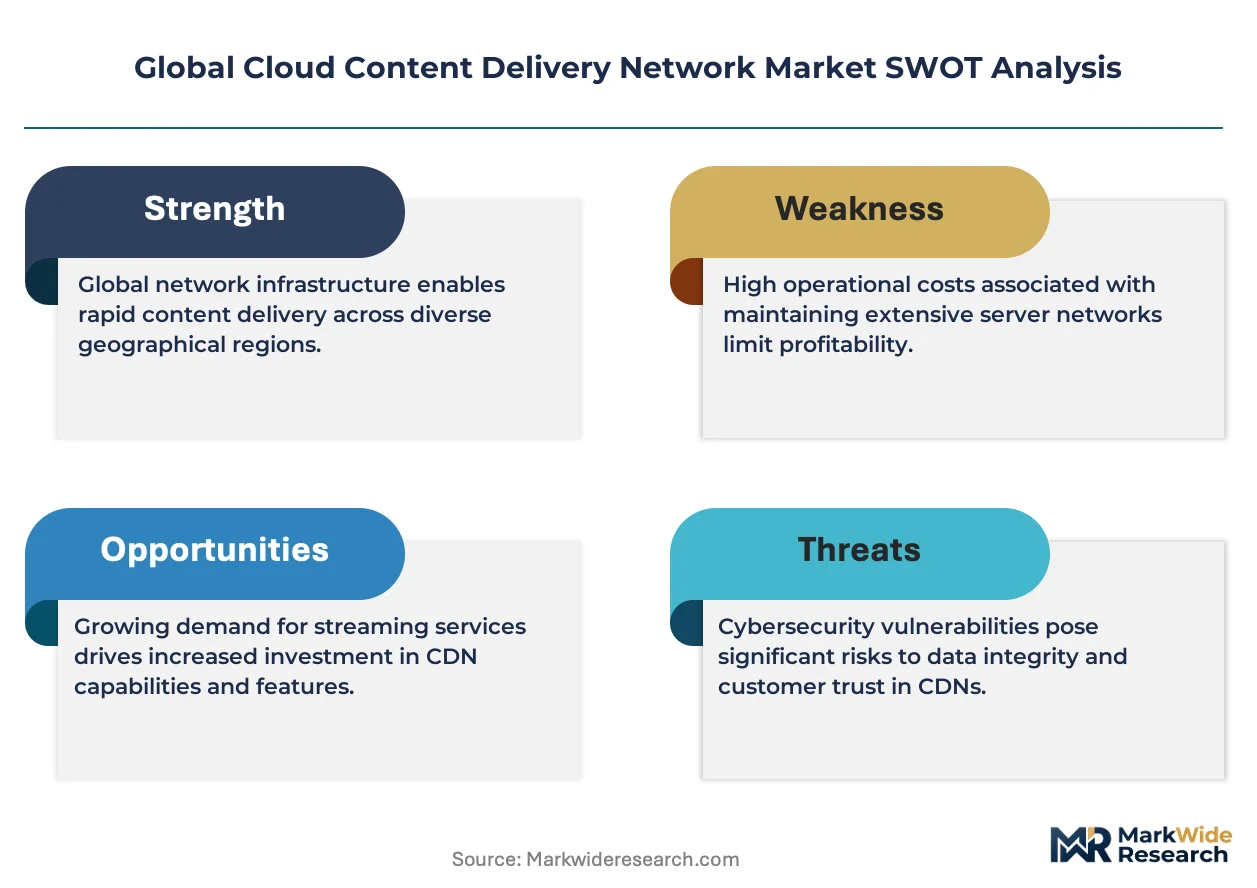
- Energy input cost volatility:Power-intensive edge data centers face margin compression from fluctuating electricity tariffs in Germany and California, two primary node concentration zones.
- Supply concentration in custom ASICs:Video encoding acceleration chips rely on a limited foundry base in Taiwan, creating chokepoint vulnerability for latency-optimized hardware procurement.
- GDPR logging restrictions:The EU GDPR's data minimization principles constrain real-time analytics granularity, limiting optimization visibility for dynamic content routing algorithms.
Strategic Opportunities
- Brazil's underpenetrated OTT corridor:ANVISA-aligned data localization precedents and rising streaming penetration create first-mover advantage for edge node buildout in São Paulo and Rio de Janeiro metro clusters.
- 5G network slicing convergence:Integration between CDN edge fabrics and telco-defined quality-of-service slices is virtualizing dedicated bandwidth lanes for enterprise API traffic.
- Japan's METI edge computing subsidies:National industrial digitization incentives are subsidizing private CDN deployments for manufacturing IoT and predictive maintenance workloads.
Industry Challenges
- Embedded systems firmware expertise gap:The shift to SmartNIC and DPU-based edge nodes requires rare talent pools versed in kernel-bypass networking and hardware-offload programming.
- Multi-cloud orchestration complexity:Enterprise buyers demand unified management across AWS CloudFront, Azure CDN, and independent provider stacks, forcing abstraction layer investments that dilute margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Content Delivery Network Market |
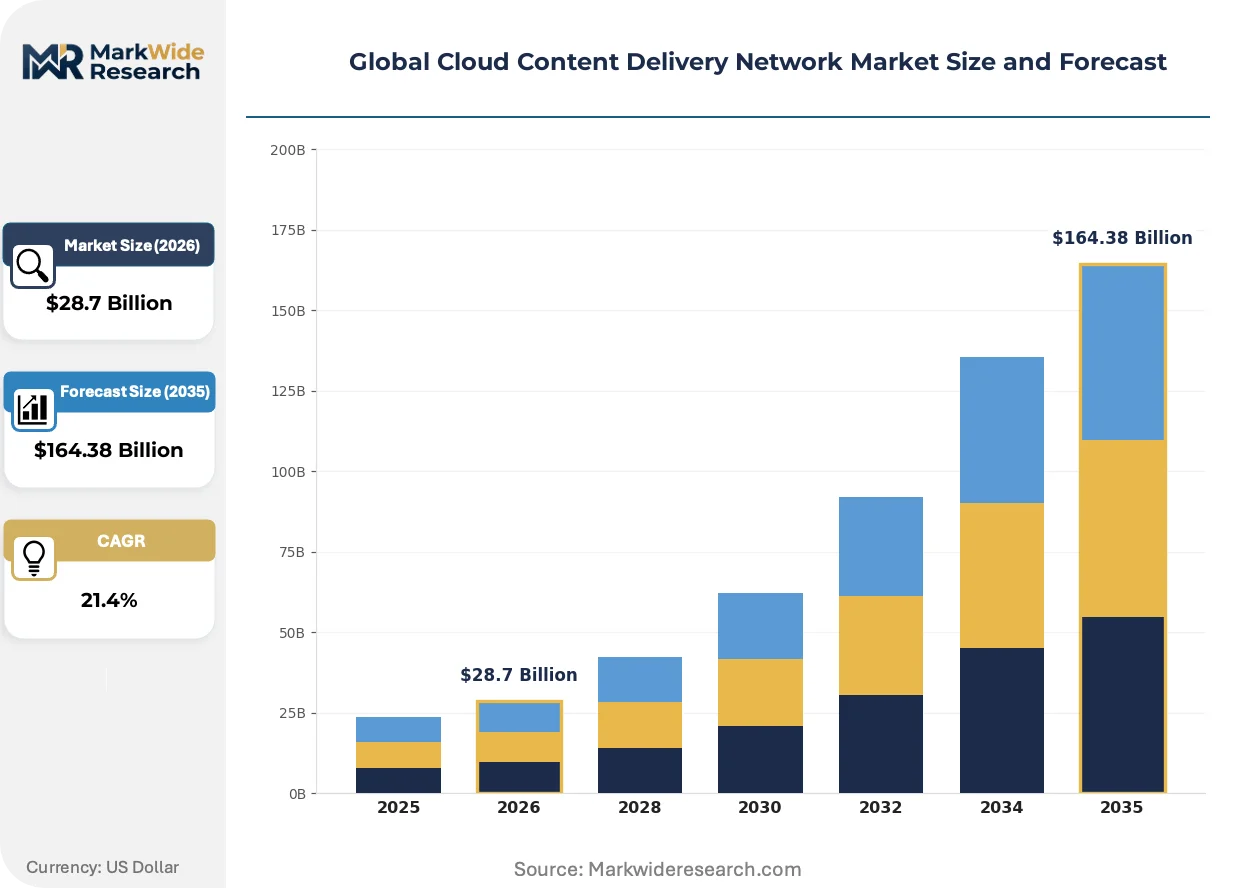
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $164.38 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Native, Hybrid Cloud, Multi-Cloud, On-Premises Solution: Video Streaming Acceleration, Web Content Delivery, Software Distribution, API Acceleration, Edge Computing Use Case: Live Broadcasting, Online Gaming, E-Learning Platforms, Social Media, OTT Platforms, E-Commerce End User: Media & Entertainment Firms, Financial Institutions, Technology Corporations, Government Agencies, Telecommunications Providers |
| Companies Covered | Fastly, Google Cloud CDN, Cloudflare, Bunny.net, Microsoft Azure CDN, Amazon CloudFront, Purvaco Cloud CDN, OVH Cloud, Akamai Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Content Delivery Network Market Shifts & Advancements
Serverless edge computing is collapsing the traditional separation between content delivery and application logic, enabling dynamic personalization at points of presence previously limited to static cache serving.
SmartNIC-based packet processing is virtualizing network function execution directly on edge server hardware. Telecom operators and large streaming platforms are deploying these programmable interfaces at scale to eliminate host CPU bottlenecks for TLS termination and video transcoding. This hardware shift is virtualizing the traditional software-defined perimeter, compressing security and delivery into single-layer edge silicon.
GDPR and the EU AI Act are mandating algorithmic audit trails and data residency boundaries that reshape logging architectures. Providers must now maintain geographically isolated telemetry stores with automated deletion protocols, increasing operational overhead but creating compliance differentiation. European financial services and healthcare verticals are responding by demanding sovereign node deployments with certified data processing agreements.
Consumption-based billing models are displacing committed-use contracts for mid-market CDN buyers. Subscription tiers tied to actual request volume and egress bandwidth are replacing flat-rate annual agreements, particularly among SaaS companies with unpredictable traffic patterns. This shift is most visible in North American and Western European markets where procurement teams prioritize cash-flow flexibility over volume discounts.
Global Cloud Content Delivery Network Market Segmentation
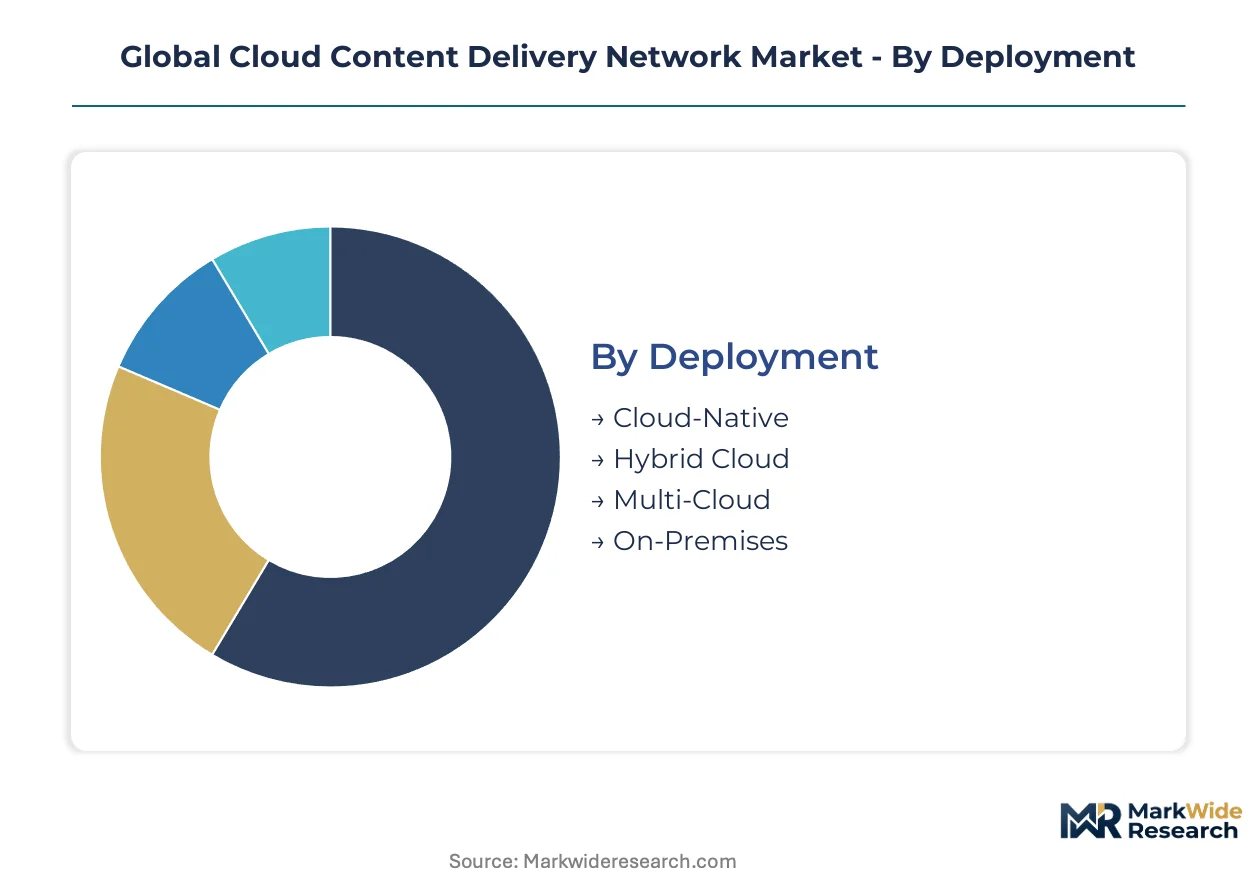
Cloud CDN segmentation reveals how infrastructure choices, solution architectures, and use-case intensity drive procurement patterns. Deployment models determine operational overhead and compliance posture. Solution types align with latency tolerance and compute requirements. End-user verticals impose distinct security, scale, and sovereignty demands.
Deployment:
After-sales-service intensity varies sharply across deployment modes, with cloud-native requiring minimal hands-on support while hybrid and on-premises demand sustained engineering engagement.
- Cloud-Native:Fully API-driven provisioning through hyperscale backbones eliminates hardware procurement cycles. Media & entertainment firms in India concentrate demand here, driven by TRAI-mandated cloud certification and government broadband initiatives in tier-two cities.
- Hybrid Cloud:Combines hyperscale edge nodes with private origin infrastructure for workload-specific optimization. Financial institutions in Germany favor this model to satisfy GDPR data residency mandates while retaining on-premise transaction processing.
- Multi-Cloud:Distributes traffic across AWS CloudFront, Azure CDN, and independent provider stacks to avoid vendor lock-in. Technology corporations deploy this for API traffic resilience.
- On-Premises:Self-managed edge nodes within enterprise data centers for maximum control. Government agencies with classified content requirements represent the core demand pool.
Cloud-native holds the largest share; momentum sits with hybrid cloud as regulatory complexity deepens.
Solution:
Cost tier stratification separates premium video acceleration from commoditized web delivery, with edge computing commanding the highest per-request pricing.
- Video Streaming Acceleration:Sub-two-second latency optimization for 4K broadcast and live events through serverless edge processing. OTT platforms expanding across Brazil's São Paulo and Rio de Janeiro metro clusters are pulling investment toward this solution.
- Edge Computing:Serverless function execution at points of presence, collapsing content delivery and application logic. Japan's METI subsidies for manufacturing IoT are accelerating private deployments for predictive maintenance workloads.
- Web Content Delivery:Static asset caching and TLS termination for standard web applications. E-commerce platforms with seasonal traffic spikes drive volume here.
- Software Distribution:Binary package delivery and update propagation for client applications. Gaming publishers with frequent patch cycles concentrate demand.
- API Acceleration:Low-latency routing for machine-to-machine communication. 5G network slicing convergence with telco quality-of-service lanes is expanding this segment.
Video streaming acceleration commands the highest revenue per node; edge computing is expanding most quickly as compute migrates to the network periphery.
Use Case:
Volume concentration follows live event broadcasting schedules, creating demand spikes that strain infrastructure planning.
- Live Broadcasting:Real-time video distribution with sub-second latency requirements for sports and news. India's OTT penetration surge is accelerating deployment corridors previously unreachable by hyperscale backbones.
- Online Gaming:Interactive multiplayer sessions demanding sub-50-millisecond round-trip times. Cloudflare's zero-trust-embedded fabric reduces latency for enterprise game server workloads.
- OTT Platforms:On-demand video libraries with adaptive bitrate streaming. Akamai's distributed edge platform spans thousands of global points of presence serving this use case.
- E-Commerce:Dynamic product catalogs and checkout acceleration. Google's private fiber backbone sustains sub-second delivery benchmarks for API traffic here.
- Social Media:User-generated content ingestion and viral content distribution. SmartNIC-based packet processing eliminates host CPU bottlenecks for TLS termination.
- E-Learning Platforms:Scalable video delivery for remote education. EU AI Act compliance mandates are compelling sovereign edge node deployment within European borders.
Live broadcasting holds the largest share; online gaming is gaining share fastest as interactive workloads proliferate.
End User:
Customer type determines procurement complexity, with government agencies imposing certification requirements that extend sales cycles.
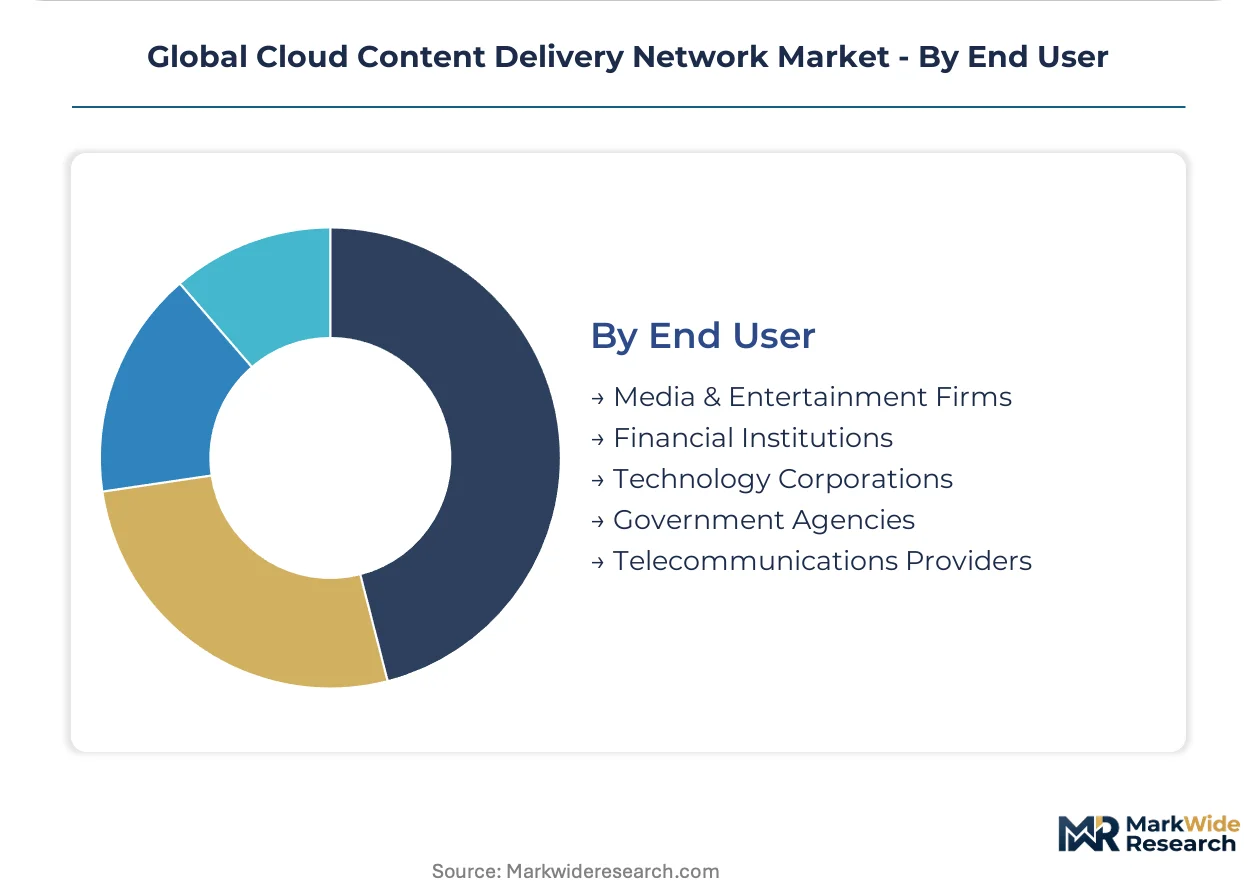
- Media & Entertainment Firms:Primary adopters of video streaming acceleration with unpredictable traffic patterns. Consumption-based billing models are displacing committed-use contracts for this segment in North American markets.
- Financial Institutions:Security-sensitive buyers requiring zero-trust architectures and audit trails. GDPR logging restrictions constrain real-time analytics granularity for dynamic content routing.
- Technology Corporations:Engineering-savvy adopters of multi-cloud orchestration and serverless edge. Multi-cloud abstraction layer investments dilute provider margins here.
- Government Agencies:Sovereignty-focused buyers mandating data residency and algorithmic transparency. EU AI Act and GDPR compliance requirements push providers toward data-sovereign infrastructure designs.
- Telecommunications Providers:Infrastructure owners integrating CDN edge fabrics with 5G network slicing. Energy input cost volatility in Germany and California creates margin pressure for power-intensive edge data centers.
Media & entertainment firms hold the largest share; telecommunications providers are climbing the fastest as network slicing virtualizes dedicated bandwidth lanes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers cluster in jurisdictions with strict data sovereignty mandates. Government cloud certification programs and streaming platform expansion are redrawing infrastructure investment maps.
United States
Hyperscale cloud providers and OTT platforms drive node density. The FCC maintains net neutrality oversight affecting interconnection agreements between CDN operators and last-mile ISPs. Northern Virginia's data center corridor hosts the densest concentration of edge compute facilities serving federal and commercial workloads.
Germany
Industrial IoT and automotive telemetry workloads demand sub-50-millisecond latency. The EU GDPR and EU AI Act impose strict data residency and algorithmic transparency mandates shaping European node architectures. Frankfurt's financial district anchors sovereign edge deployments for compliance-sensitive banking clients.
India
OTT penetration and government digital initiatives accelerate deployment across tier-two cities. TRAI-mandated cloud certification and BIS standards create compliance thresholds for foreign providers. Bangalore and Hyderabad metro clusters attract hyperscale edge buildouts previously unreachable by backbone networks.
Brazil
Rising streaming penetration and data localization precedents create first-mover opportunities. ANVISA-aligned regulatory frameworks establish data governance benchmarks for health and financial verticals. São Paulo and Rio de Janeiro metro clusters concentrate private CDN investment for media distribution.
Japan
Manufacturing IoT and predictive maintenance workloads subsidize private edge deployments. METI edge computing subsidies support industrial digitization incentives for captive infrastructure. The Nagoya industrial corridor hosts specialized nodes serving automotive supply chain telemetry.
Global Cloud Content Delivery Network Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Hyperscale cloud providers leverage integrated billing and identity systems to capture enterprise procurement workflows. Independent specialists differentiate through developer experience and edge compute granularity. Strategic moves center on serverless function deployment and sovereign node certification rather than raw bandwidth commoditization.
Within the independent specialist tier, Fastly and Cloudflare exemplify edge-native architectures built for programmable traffic manipulation. Akamai Technologies anchors the legacy-distributed camp with the most geographically extensive point-of-presence footprint. Google Cloud CDN occupies a position bridging hyperscale infrastructure with media-optimized delivery stacks.
| Leading Market Players |
|---|
| Fastly |
| Google Cloud CDN |
| Cloudflare |
| Bunny.net |
| Microsoft Azure CDN |
| Amazon CloudFront |
| Purvaco Cloud CDN |
| OVH Cloud |
| Akamai Technologies |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber corridor cost volatility directly compresses margins for edge node hardware procurement while amplifying price differentiation between sovereign-certified and standard CDN tiers. Hyperscale providers leverage volume scale to absorb freight fluctuations; independent specialists pass through logistics premiums to enterprise buyers demanding GDPR-compliant node architectures.
Pricing Analysis
Cost-plus contracts indexed to Taiwan Semiconductor Manufacturing capacity utilization dominate custom ASIC procurement for video encoding hardware. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-certified edge nodes with EU AI Act audit trails from commodity cache-only deployments. Pricing pressure stems from energy input cost volatility in Germany and California node concentration zones. SaaS companies with unpredictable traffic patterns exhibit highest price sensitivity; financial institutions with GDPR mandates show lowest sensitivity to per-request premiums.
Supply Chain Analysis
Upstream feedstock for SmartNIC and DPU silicon draws from Taiwan, South Korea, and USA foundry capacity. Video encoding acceleration chips, kernel-bypass networking components, and programmable logic devices constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan's limited custom ASIC foundry base for latency-optimized hardware. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales channels with API-driven provisioning workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloud CDN market sits in early-cycle expansion as edge computing workloads displace centralized cloud architectures. Live video streaming protocols and EU regulatory mandates are accelerating infrastructure deployment velocity beyond historical hyperscale buildout patterns.
For Market Incumbents: Harden sovereign node certification portfolios against EU AI Act compliance mandates by embedding algorithmic audit trails directly into edge silicon. Acquire kernel-bypass networking talent pools in Germany and Japan to close the embedded systems firmware expertise gap. Vertical integration into custom ASIC design reduces exposure to Taiwan foundry chokepoints.
For New Entrants and Emerging Players: Build out Brazil's underpenetrated OTT corridor through ANVISA-aligned data localization partnerships in São Paulo metro clusters. Target India's tier-two city deployment corridors where TRAI-mandated cloud certification creates compliance moats against hyperscale incumbents. Lead with consumption-based billing models to capture SaaS mid-market buyers prioritizing cash-flow flexibility.
For Investors and Strategic Acquirers: Edge-native specialists with programmable traffic manipulation capabilities represent the highest-conviction acquisition archetype for platform consolidation plays. Sovereign node operators with certified data processing agreements command scarcity premiums in European financial services verticals. Monitor 5G network slicing convergence milestones as the inflection signal for enterprise API traffic virtualization demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Node Certification | EU AI Act compliance mandates expand addressable infrastructure spend for certified European deployments. |
| Serverless Edge Platform Launch | Sub-50-millisecond latency guarantees differentiate against commodity cache-only CDN providers. |
| SmartNIC Hardware Integration | Kernel-bypass networking eliminates host CPU bottlenecks for TLS termination and video transcoding. |
| Multi-Cloud Orchestration Partnership | Unified management across AWS CloudFront and Azure CDN reduces enterprise buyer switching costs. |
| 5G Network Slicing Collaboration | Telco-defined quality-of-service lanes virtualize dedicated bandwidth for enterprise API traffic. |
Research Methodology
The analysis maps cloud-native, hybrid, and on-premises deployment modes, each validated through platform engineering directors, IT procurement officers at media firms, CDN operations leads, and hyperscaler partnership managers. Primary fieldwork combined with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie streaming platform data, and TRAI regulatory circulars established segment boundaries. Bottom-up node deployment counts triangulated against top-down infrastructure spend estimates.
Assumptions held fixed include EU GDPR and AI Act compliance timelines, Taiwan foundry capacity allocation patterns, and India TRAI certification thresholds; varied assumptions encompass 5G network slicing adoption velocity and live streaming protocol standardization outcomes. Segmentation modeled deployment model, solution type, use case intensity, and end-user vertical across the projection horizon. CAGRs derived from edge node buildout trajectories, video streaming bandwidth growth curves, and sovereign infrastructure spend patterns.
Stress conditions across energy tariff volatility in Germany and California, Taiwan foundry disruption scenarios, and India cloud certification timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumption sets alongside regulatory implementation risks and hardware procurement chokepoints. Cross-checking against hyperscaler public capex guidance and OTT platform subscriber growth benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
South Korea Data Center Networking Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
Computer Servers Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Austria Data Center Networking Market