
 Content Delivery Network (CDN) Market | 2026-2036
Content Delivery Network (CDN) Market Size, Share, and Industry Trends Forecast 2026-2036
Content Delivery Network (CDN) Market Analysis
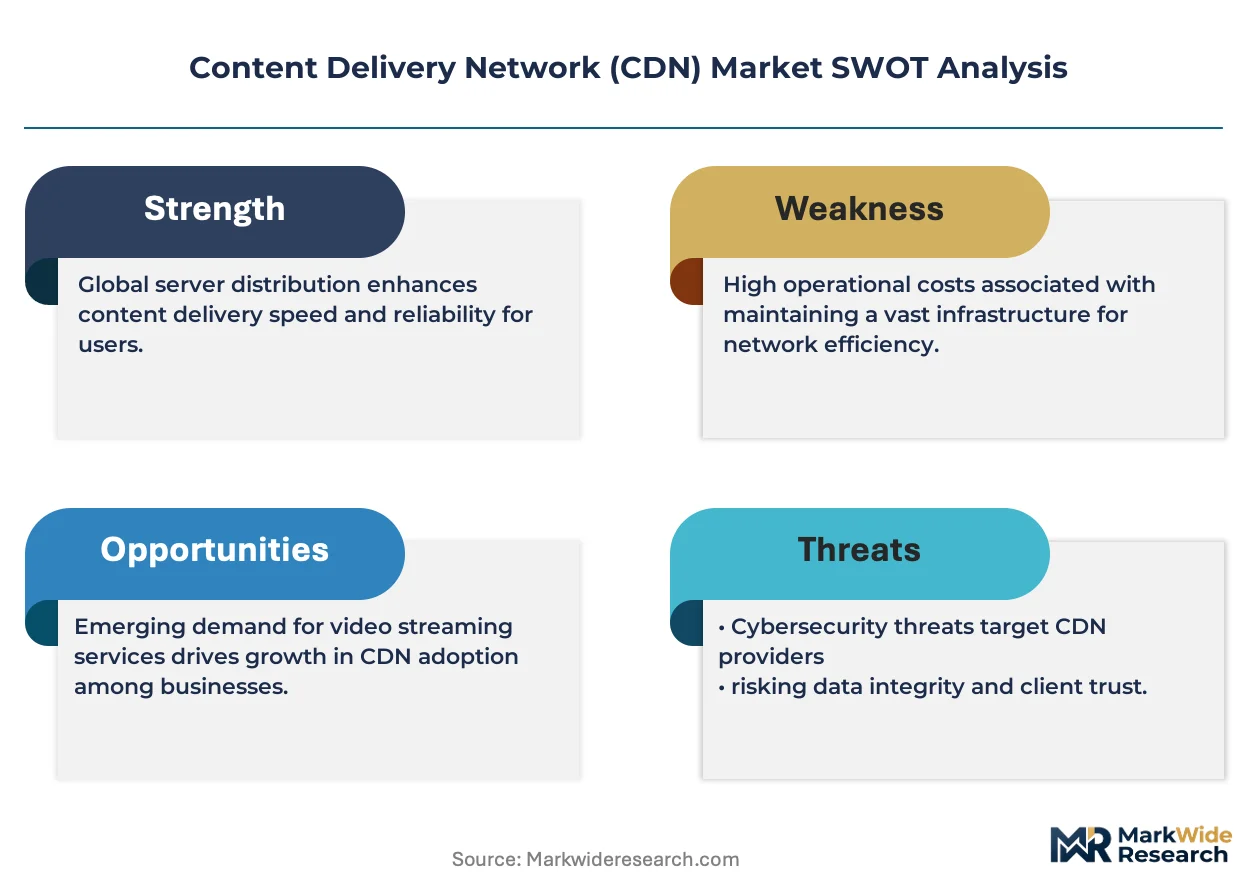
The edge server distribution channel is fragmenting as cloud hyperscalers and specialized providers compete for latency-sensitive workloads. Akamai Technologies anchors its position through one of the most geographically dispersed server networks. Cloudflare differentiates via integrated security and performance stacks that reduce vendor sprawl. Amazon CloudFront leverages its parent cloud ecosystem to sustain pricing pressure on standalone CDN vendors.
A content delivery network constitutes a geographically distributed server infrastructure that caches and delivers web content from edge locations typically within 50 milliseconds of end users, employing TCP optimization and anycast routing to minimize latency. Its primary commercial purpose is to accelerate website load times, absorb traffic spikes, and ensure content availability during origin server failures. Video Streaming commands the largest service type segment as over-the-top platforms expand 4K and live event delivery. Edge Computing deployments represent the fastest-growing deployment model as enterprises push compute closer to users for real-time applications. Web Performance services retain mature margin pools in e-commerce and SaaS verticals where conversion rates tie directly to page speed.
The FCC in the United States enforces net neutrality principles that shape interconnection agreements between ISPs and CDN providers, while the EU AI Act and GDPR impose data sovereignty requirements affecting European edge node placement. China's MIIT mandates ICP licensing and domestic data storage that constrain foreign CDN operators while accelerating local infrastructure buildout. Stakeholders must monitor how divergent data localization regimes fragment global CDN architectures and force region-specific partnership strategies.
Market Dynamics
Edge computing workloads are compressing latency requirements below 10 milliseconds, forcing CDN architectures to migrate compute functions from regional data centers toward metropolitan edge nodes. This spatial compression of infrastructure is redrawing competitive boundaries between network operators, cloud hyperscalers, and specialized edge providers.
Growth Catalysts
- India's Data Localization Mandates:The Digital Personal Data Protection Act requires domestic storage and processing of citizen data, compelling OTT platforms and e-commerce operators to deploy local edge infrastructure.
- 4K and Live Video Streaming:Sports broadcasters and entertainment platforms are expanding real-time content delivery, driving demand for low-latency caching and adaptive bitrate optimization at the network edge.
- Brazil's Digital Transformation Agenda:Federal investments in connectivity infrastructure and cloud-first government policies are accelerating enterprise migration to distributed content delivery architectures.
Market Restraints
- Energy Cost Volatility:Edge server farms in Germany and South Korea face escalating electricity expenses that compress operating margins for high-density caching operations.
- Supply Concentration in Taiwan:Advanced networking silicon and high-performance server components depend heavily on concentrated semiconductor fabrication capacity, creating vulnerability to geopolitical disruption.
- Technical Limitation of Last-Mile Interconnection:Peering agreement fragmentation between ISPs and CDN providers introduces unpredictable latency spikes that degrade quality-of-service guarantees.
Strategic Opportunities
- Underpenetrated German Industrial IoT:Manufacturing automation and predictive maintenance applications remain underserved by existing CDN edge coverage, creating whitespace for latency-critical compute services.
- Convergence of AI Inference and Content Delivery:Machine learning model serving at the edge is merging with traditional caching workloads, enabling unified infrastructure platforms for real-time personalization.
- South Korea's Smart City Mandates:National urban digitization programs are mandating municipal edge deployments for traffic management and public safety video analytics.
Industry Challenges
- Edge Infrastructure Talent Scarcity:Network engineering and distributed systems architecture expertise remains concentrated among legacy telecom operators, constraining deployment velocity for newer entrants.
- Multi-Cloud Integration Complexity:Enterprise buyers demand seamless interoperability across AWS, Azure, and Google Cloud origin environments, forcing CDN providers to maintain costly API compatibility layers.
- Certification Timeline for Government Contracts:FedRAMP and equivalent national security clearances require 12-18 month validation cycles that delay revenue recognition in public sector verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Delivery Network (CDN) Market |
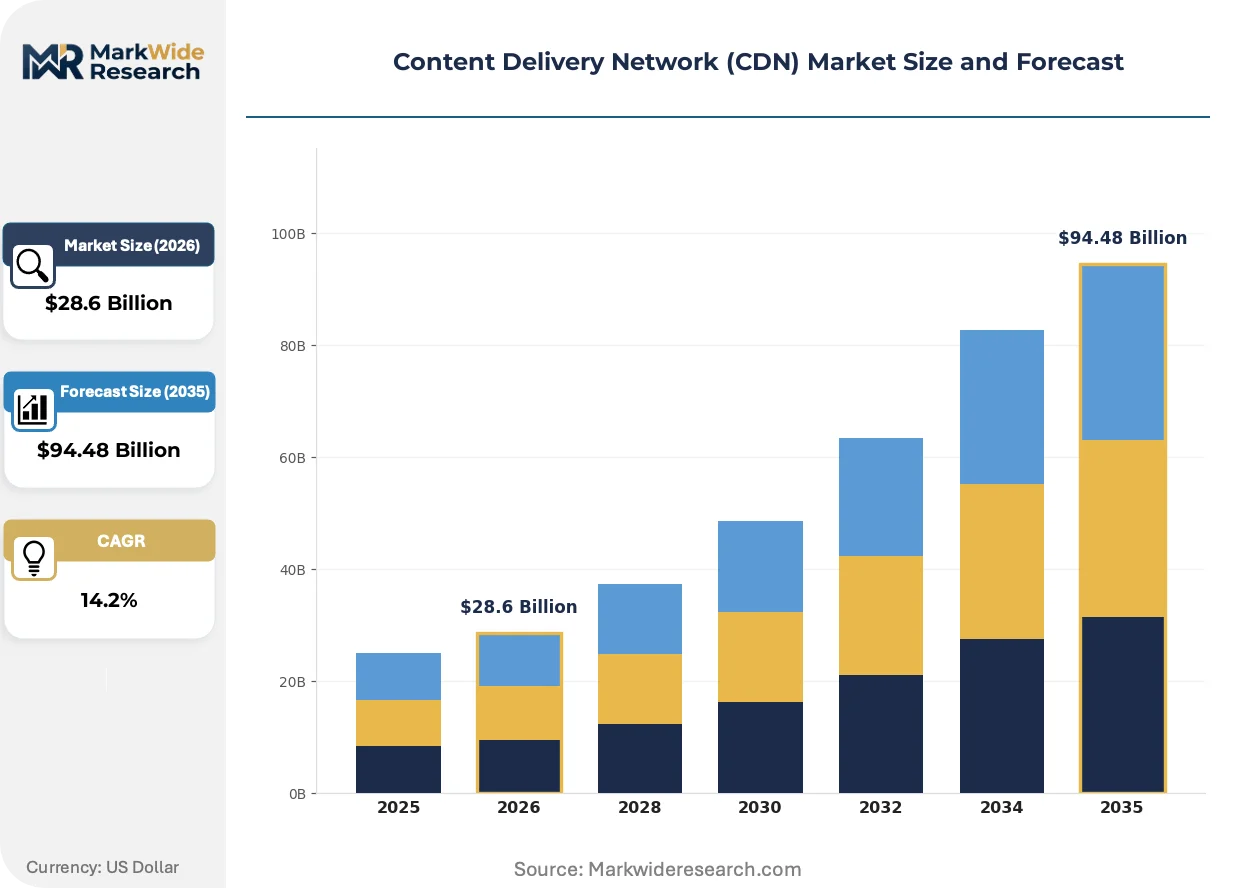
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Streaming, Web Performance, Cloud Security, Load Balancing Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing End User: Media & Entertainment, E-Commerce, Education, Gaming Pricing Model: Pay-as-you-go, Subscription, Tiered Pricing, Free Trial |
| Companies Covered | Google Cloud CDN, Fastly, Akamai Technologies, Limelight Networks, Alibaba Cloud, Cloudflare, Microsoft Azure CDN, Edgio, Amazon CloudFront, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Delivery Network (CDN) Market Emerging Trajectories
Serverless edge computing architectures are dissolving the boundary between content delivery and application execution, transforming CDN nodes from passive caching layers into active compute endpoints. This functional expansion is attracting new buyer segments and compressing traditional infrastructure procurement cycles.
WebAssembly runtime environments are collapsing the distinction between edge caching and application logic execution. Media streaming platforms and SaaS providers are deploying portable compute modules to edge nodes at accelerating velocity. This technology compression is eliminating the need for separate origin infrastructure and edge orchestration layers, consolidating vendor relationships.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on content recommendation systems deployed at European edge nodes. Platforms must now maintain audit trails for inference operations processed outside centralized data centers. Video streaming services and social media operators are restructuring their European architectures to isolate high-risk AI workloads.
Enterprise procurement of CDN services is consolidating around integrated security-performance bundles rather than standalone bandwidth contracts. Financial services and healthcare buyers are displacing point-solution vendors with unified platforms that combine DDoS mitigation, bot management, and application acceleration. This bundling preference is most pronounced in US and UK markets where cybersecurity insurance underwriters are mandating consolidated threat surface management.
Content Delivery Network (CDN) Market Segmentation
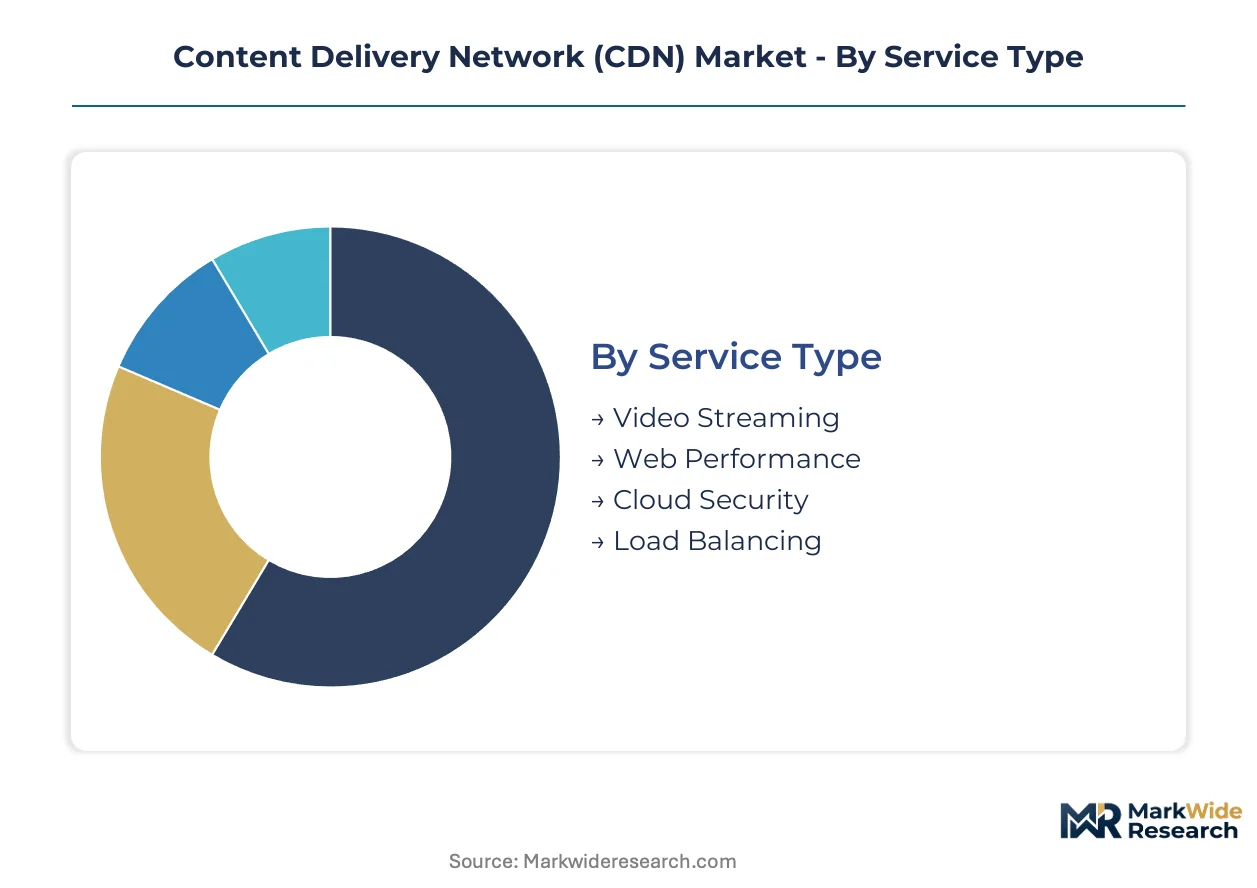
CDN procurement patterns diverge sharply across service architectures and buyer economics. Deployment choices reflect latency requirements, data sovereignty obligations, and workload predictability. Understanding these segment boundaries clarifies where infrastructure investments concentrate and which pricing mechanisms capture expanding demand.
Service Type:
Application function determines infrastructure topology and margin structure across CDN service tiers.
- Video Streaming:Adaptive bitrate delivery and live event caching dominate bandwidth consumption. OTT platforms in India and sports broadcasters in Brazil drive capacity expansion as 4K streams compress latency tolerances below 50 milliseconds.
- Web Performance:TCP optimization and dynamic content acceleration serve e-commerce conversion optimization. SaaS providers and online retailers in Germany prioritize sub-second page loads to reduce cart abandonment.
- Cloud Security:DDoS mitigation and bot management integrate at the edge. Financial services buyers mandate WAF deployment alongside caching.
- Load Balancing:Traffic distribution across origin servers ensures failover resilience. Enterprise hybrid cloud architectures require intelligent request routing.
Video Streaming commands the established base. The steepest expansion runs through Cloud Security as cyber insurance mandates consolidate procurement.
Deployment Model:
Infrastructure location relative to end users shapes capital intensity and operational control tradeoffs.
- Edge Computing:Compute functions migrate to metropolitan nodes within 10 milliseconds of users. South Korea's smart city mandates and German industrial IoT applications push real-time inference workloads to distributed edge infrastructure.
- Public Cloud:Shared multi-tenant infrastructure delivers elastic scaling without capital commitment. Startups and seasonal businesses favor this model.
- Private Cloud:Dedicated edge nodes serve regulated industries with data residency requirements. Healthcare and government buyers mandate isolated infrastructure.
- Hybrid Cloud:Workload portability across public and private environments. Enterprises with variable compliance needs adopt this architecture.
Public Cloud retains volume leadership. Edge Computing climbs the fastest as latency requirements compress below traditional data center reach.
End User:
Industry-specific performance requirements and regulatory exposure differentiate buyer priorities.
- Media & Entertainment:Live sports and gaming streams demand burst capacity and geographic redundancy. Platform competition in India accelerates edge node deployment.
- E-Commerce:Page speed directly correlates with conversion rates. Flash sales and holiday traffic spikes necessitate elastic caching.
- Education:Video lecture delivery and interactive learning platforms require consistent throughput. Remote examination proctoring adds security layer requirements.
- Gaming:Multiplayer latency tolerances below 20 milliseconds drive edge node proximity. Cloud gaming services expand addressable hardware markets.
E-Commerce anchors current revenue. Gaming gains share fastest as cloud-native titles displace console distribution.
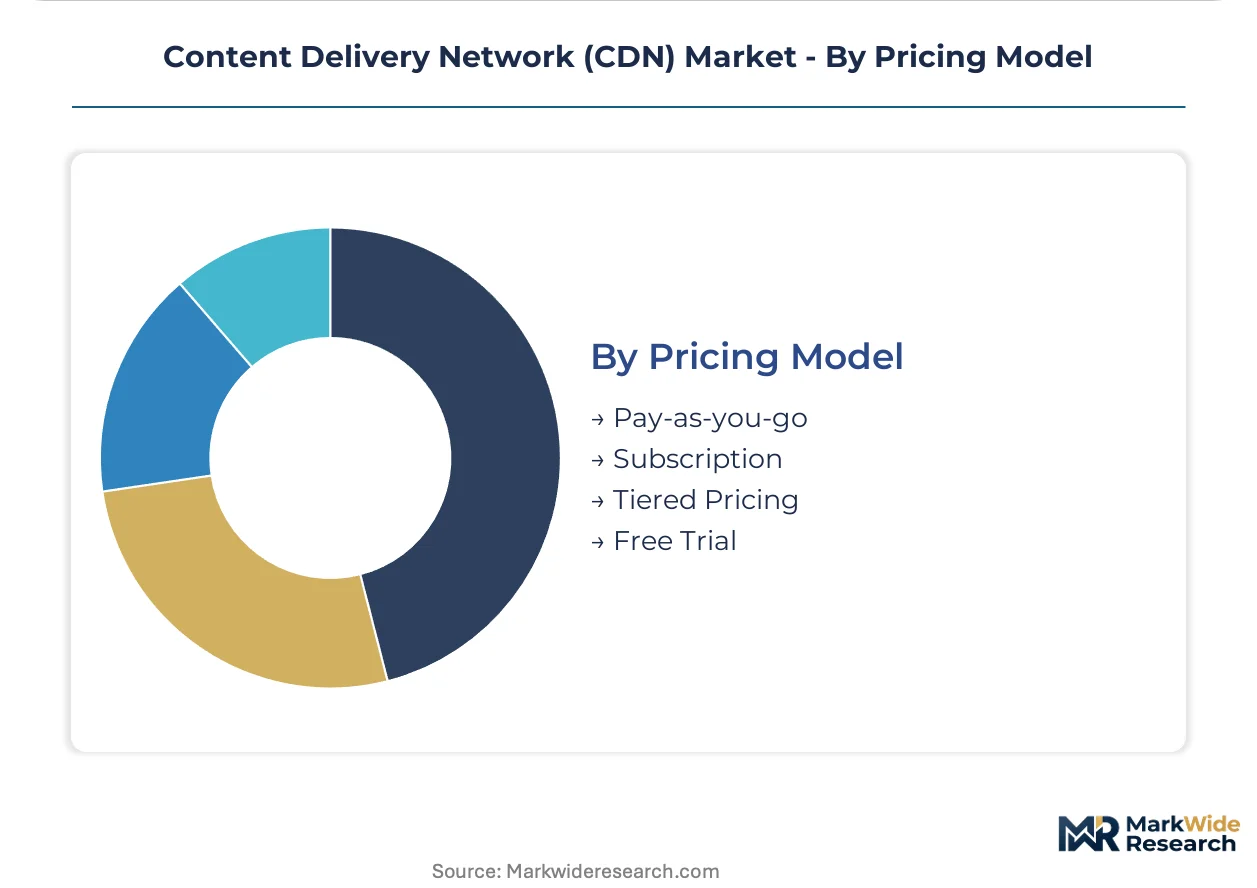
Pricing Model:
Customer scale and demand predictability determine commercial structure preferences.
- Pay-as-you-go:Metered bandwidth and request volume billing aligns cost with actual consumption. Unpredictable traffic patterns favor this structure.
- Subscription:Fixed monthly fees with committed usage tiers. Predictable workloads and budget certainty drive enterprise adoption.
- Tiered Pricing:Performance and support levels stratify across premium, standard, and economy bands. SLA guarantees differentiate tiers.
- Free Trial:Limited-duration evaluation access converts prospects to paid tiers. Developer-centric platforms deploy this mechanism.
Subscription models dominate enterprise accounts. Pay-as-you-go expands most quickly among mid-market digital natives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Chennai submarine cable corridor anchors India's accelerating edge infrastructure buildout, while Frankfurt's DE-CIX internet exchange underwrites European interconnection density for latency-sensitive workloads.
United States
FCC net neutrality enforcement shapes ISP interconnection terms for CDN operators, while hyperscaler cloud regions in Ashburn and San Jose concentrate edge node deployment. Financial services buyers in New York mandate integrated security-performance bundles that consolidate vendor relationships around unified platforms.
Germany
Industrial IoT automation and predictive maintenance applications drive demand for sub-10 millisecond compute at metropolitan edge nodes. The EU AI Act and GDPR impose data sovereignty requirements affecting algorithmic transparency for content recommendation systems processed outside centralized facilities. Manufacturing clusters in Bavaria and Baden-Württemberg are deploying latency-critical edge services for shop-floor analytics.
India
OTT platform expansion and 4K live sports streaming compress latency tolerances below 50 milliseconds for video delivery. The Digital Personal Data Protection Act mandates domestic storage and processing of citizen data, compelling edge infrastructure localization. Data center corridors in Maharashtra and Telangana are absorbing the majority of new CDN capacity investments.
Brazil
Federal cloud-first policies and connectivity infrastructure investments accelerate enterprise migration to distributed architectures. ANVISA data residency requirements affect healthcare content delivery configurations. São Paulo's financial district and Rio de Janeiro's media production clusters anchor regional edge node concentration for Latin American traffic.
South Korea
National smart city mandates require municipal edge deployments for traffic management and public safety video analytics. MFDS medical data regulations influence healthcare CDN architecture choices. The Seoul Capital Area and Busan-Ulsan corridor concentrate gaming and cloud streaming infrastructure where multiplayer latency tolerances sit below 20 milliseconds.
Content Delivery Network (CDN) Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The CDN market structures around three tiers: cloud hyperscalers with captive infrastructure, specialized edge providers with security-performance integration, and legacy network operators with geographic density. Strategic archetypes include latency-optimized pure-plays, security-centric bundles, and ecosystem-leveraged cloud extensions. Competitive moves concentrate on M&A for edge node density and strategic partnerships for last-mile interconnection.
Within the hyperscaler tier, Amazon CloudFront and Microsoft Azure CDN exemplify ecosystem-leveraged positioning that sustains pricing pressure through bundled cloud consumption. Akamai Technologies anchors the geographic dispersion archetype through server network breadth. Cloudflare occupies a position exemplifying the security-performance convergence that reduces vendor sprawl for enterprise buyers.
| Leading Market Players |
|---|
| Google Cloud CDN |
| Fastly |
| Akamai Technologies |
| Limelight Networks |
| Alibaba Cloud |
| Cloudflare |
| Microsoft Azure CDN |
| Edgio |
| Amazon CloudFront |
| Others |
Supply Flow & Price Mechanics
Taiwanese semiconductor fabrication concentration anchors CDN infrastructure cost structures, compressing margin flexibility across premium edge-computing tiers while forcing supply chain redundancy investments into secondary geographies.
Pricing Analysis
Volume-discount tiering structures dominate enterprise CDN procurement, with hyperscaler bundled offerings undercutting standalone vendors on per-gigabyte rates. Price differentiation rests on latency guarantees and security certification tiers, with FedRAMP-authorized deployments commanding substantial premiums. Pricing pressure intensifies as Amazon CloudFront and Microsoft Azure CDN leverage cloud ecosystem lock-in to sustain below-cost bandwidth pricing. Mid-market digital natives exhibit highest price sensitivity, while financial services buyers prioritize SLA certainty over unit economics.
Supply Chain Analysis
Contract-manufacturing concentration for edge servers sits with Foxconn, Quanta, and Wistron facilities across Taiwan and China, with assembly capacity expanding into Mexico and Vietnam. Advanced networking silicon draws from TSMC foundries in Taiwan and Samsung foundries in South Korea. Memory components and power management ICs rest on concentrated East Asian supply bases. Single-source vulnerability in 7nm and below networking processors creates geopolitical exposure. Distribution runs through direct hyperscaler procurement channels and specialized IT distributors serving enterprise buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge infrastructure engineering expertise scarcity constrains deployment velocity, with distributed systems architecture talent concentrated among legacy telecom operators and cloud hyperscalers.
For Market Incumbents: Pre-empt hyperscaler bundling strategies by deepening security-performance integration and securing FedRAMP authorization ahead of 12-18 month validation cycles. Anchor geographic dispersion advantages through targeted edge node acquisitions in underpenetrated German industrial corridors and South Korean smart city zones. For New Entrants and Emerging Players: Establish a beachhead in WebAssembly-based serverless edge computing, where portable compute modules dissolve traditional infrastructure procurement cycles. Target mid-market SaaS providers in Brazil and India seeking to displace separate origin infrastructure and edge orchestration layers with unified platforms. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized edge providers with security-performance integration capabilities over pure bandwidth plays. Acquisition targets should demonstrate proprietary anycast routing networks and established last-mile ISP peering relationships. Monitor hyperscaler capex allocation shifts as inflection indicator for pricing pressure intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Density Expansion | Metropolitan node deployment within 10 milliseconds of users captures latency-critical gaming and industrial IoT workloads in Germany and South Korea. |
| Security-Performance Bundle Integration | Unified DDoS mitigation and bot management platforms reduce vendor sprawl for financial services buyers in New York and London. |
| FedRAMP Authorization Investment | 12-18 month certification cycles create competitive moats for public sector verticals with sustained contract visibility. |
| WebAssembly Runtime Deployment | Portable compute modules at edge nodes eliminate separate origin infrastructure for SaaS providers and media streaming platforms. |
| ISP Peering Agreement Deepening | Direct interconnection with last-mile providers in India and Brazil reduces unpredictable latency spikes degrading quality-of-service guarantees. |
Methodological Framework
A standing panel of CDN platform engineers, enterprise IT procurement officers, ISP interconnection managers, and edge infrastructure architects provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and telecommunications regulatory filings from the FCC, TRAI, and MIIT. Bottom-up deployment capacity modeling and top-down bandwidth consumption estimates were triangulated to anchor volume projections.
Scenario-bracketing framed demand trajectories across conservative, baseline, and accelerated edge computing adoption paths. Segmentation dimensions modeled included service type, deployment model, end-use vertical, and regional data sovereignty cluster. CAGRs were derived from unit economics analysis of bandwidth pricing trends and infrastructure deployment velocity. Forecast inputs incorporated OTT platform expansion rates, data localization mandate implementation timelines, and smart city program funding commitments.
Stress conditions across semiconductor supply disruption, energy cost volatility, and regulatory approval timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscaler pricing discipline and enterprise cloud migration continuity. Quarterly review of hyperscaler edge capex announcements, ISP peering dispute filings, and data localization enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Brazil Servers Market
Data Center and Networking
Network Function Virtualization (NFV) Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Germany Data Center Server Market
Data Center and Networking
5G Edge Cloud Network and Services Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Data Center Services Market
Data Center and Networking
India Data Center Networking Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Spain Data Center Networking Market
Data Center and Networking
Saudi Arabia Data Center Networking Market