
 Canada Data Center Networking Market | 2026-2036
Canada Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Center Networking Market Insights
A chronic shortage of fiber optic technicians and network engineers is unwinding capacity expansion timelines for Canadian operators. Cisco Systems Inc. leverages its entrenched channel relationships with major telecommunications carriers to sustain hardware refresh cycles. Arista Networks Inc. differentiates through high-density switching platforms purpose-built for cloud-scale environments.
Canada data center networking encompasses the switching, routing, security, and physical layer infrastructure that interconnects compute and storage resources within facilities operating at latencies below 10 microseconds. These systems enable workload orchestration across distributed architectures serving cloud, colocation, and enterprise deployments. Switches occupy the largest product category as spine-leaf architectures displace legacy three-tier designs. Cloud Computing applications generate the fastest growth within the application dimension, driven by AI training clusters and real-time analytics pipelines. Financial Services end users anchor premium spending, where sub-millisecond latency and deterministic performance command sustained investment in specialized fabrics.
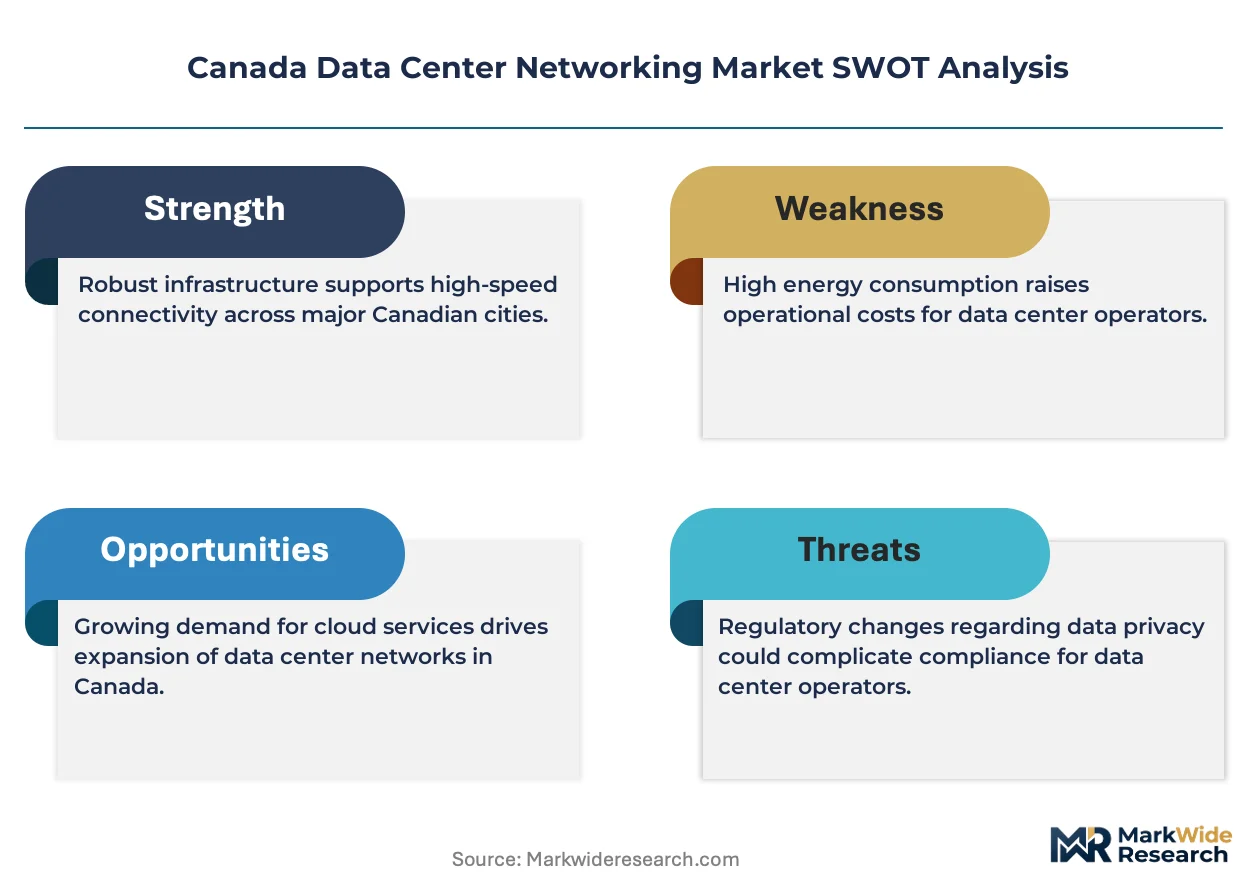
Health Canada, the Office of the Privacy Commissioner under PIPEDA, and provincial utilities regulators collectively enforce data sovereignty, energy efficiency, and cybersecurity standards that dictate equipment procurement and facility design. Compliance with these frameworks elevates total cost of ownership while creating qualified vendor lists that filter market access. Stakeholders must weigh sovereign cloud mandates against the capital intensity of domestic capacity buildouts when calibrating partnership and investment timelines.
Market Dynamics
Spine-leaf architecture migration is compressing refresh cycles across Canadian facilities, forcing incumbent three-tier infrastructure into accelerated replacement timelines while hyperscale operators demand sub-microsecond latency guarantees.
Growth Catalysts
- PIPEDA compliance mandates:Health Canada data residency requirements compel domestic infrastructure buildouts, creating captive demand for sovereign cloud networking equipment.
- AI training clusters:Financial services and research institutions deploy specialized fabrics to support distributed GPU workloads across Ontario and Quebec.
- Hyperscale expansion:Cloud operators concentrate new facility investments in Toronto, Montreal, and Vancouver, driving contiguous switching and routing procurement.
Market Restraints
- Fiber optic technician scarcity:Chronic labor shortages in specialized trades unwind capacity expansion timelines for operators building in secondary markets.
- Energy efficiency standards:Provincial utilities regulators enforce escalating power usage effectiveness thresholds that elevate total cost of ownership for legacy equipment.
- Optical component concentration:Supply bottlenecks in coherent DSP and silicon photonics modules create procurement risk for 400G and 800G port deployments.
Strategic Opportunities
- Western Canada buildouts:Vancouver and Calgary sub-markets remain underpenetrated relative to Ontario and Quebec, offering first-mover positioning for greenfield developments.
- SmartNIC and DPU convergence:Computational offload integration with switching fabrics creates premium pricing potential for workload-optimized platforms.
- Carbon-neutral mandates:Federal and provincial sustainability incentives reward facilities achieving net-zero operational status through renewable energy procurement.
Industry Challenges
- Network engineering talent pipeline:Canadian universities produce insufficient graduates with cloud-scale automation and intent-based networking skills.
- Multi-vendor interoperability certification:Health Canada cybersecurity frameworks require extended validation timelines that delay production deployments.
- Legacy mainframe integration:Financial services incumbents face complex migration paths from proprietary channel extension protocols to standard Ethernet fabrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Center Networking Market |
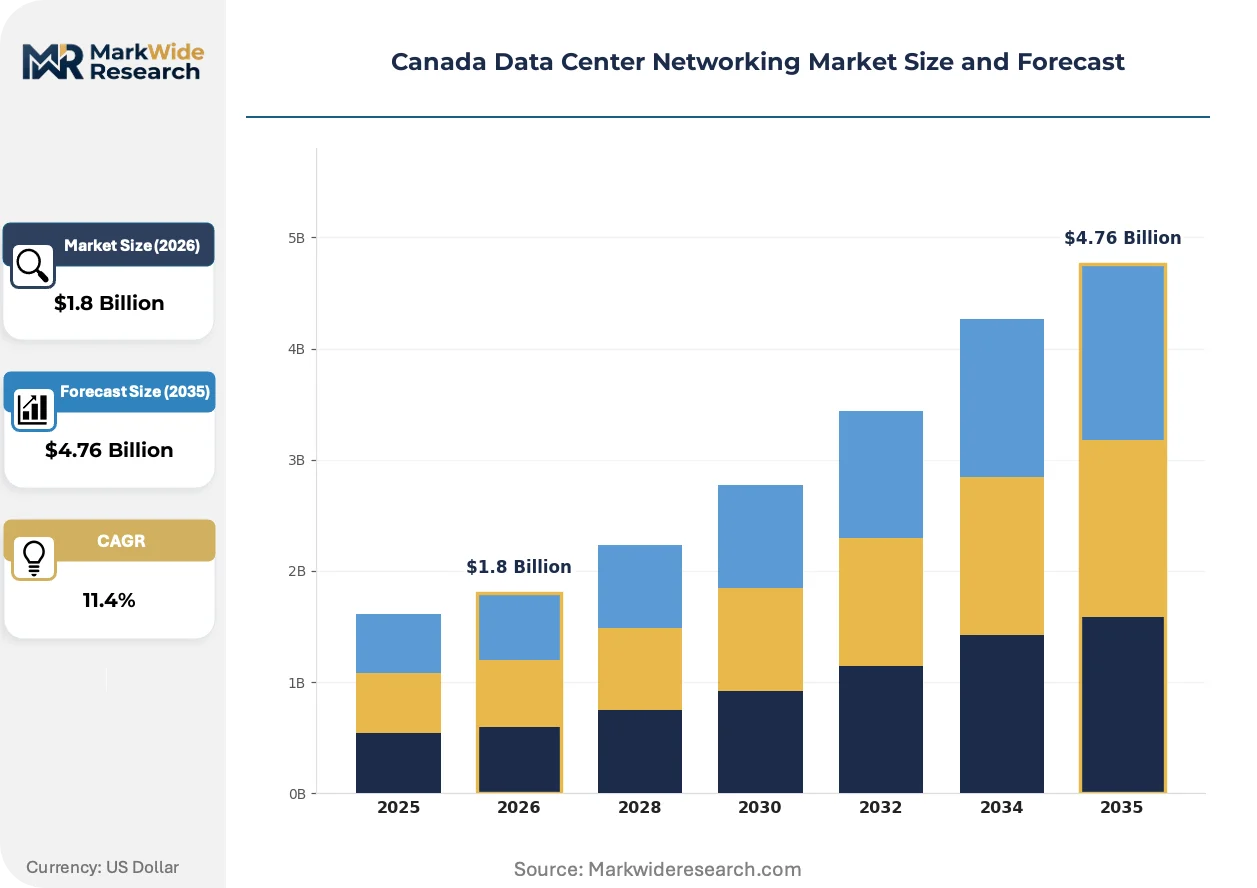
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Cables Application: Cloud Computing, Storage Solutions, Virtualization, Disaster Recovery End User: Telecommunications, Financial Services, Healthcare, Media Deployment: On-Premises, Hybrid Cloud, Public Cloud, Colocation |
| Companies Covered | Cisco Systems Inc., Arista Networks Inc., NVIDIA (Cumulus Networks), Huawei Technologies Co. Ltd., VMware Inc., Dell Technologies, Hewlett Packard Enterprise, IBM Corporation, Broadcom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Center Networking Market Trends and Innovations
Automation and disaggregation are reconfiguring procurement patterns across Canadian data centers, compressing traditional hardware refresh timelines while elevating software-defined control plane investments.
Silicon photonics switching is bifurcating the high-density interconnect market. Coherent optical engines embedded directly into switch ASICs enable 51.2Tbps aggregate capacity in single rack units. Hyperscale operators in Toronto and Montreal are adopting these platforms for AI cluster backbones. The technology is bifurcating vendor strategies between merchant silicon integrators and captive ASIC developers.
Health Canada cybersecurity guidance for medical device data infrastructure is tightening equipment qualification requirements. The Office of the Privacy Commissioner under PIPEDA now mandates encryption-at-rest and encryption-in-transit for all personal health information traversing data center networks. Colocation providers serving healthcare verticals are retrofitting existing facilities with certified hardware, absorbing compliance costs into long-term lease structures.
Consumption-based networking procurement is displacing traditional capital acquisition models. Enterprises in Vancouver and Calgary increasingly procure switching capacity as operational expenditure through managed service overlays. Channel partners are consolidating around full-stack lifecycle contracts that bundle hardware, software licensing, and remote operations. This shift is most pronounced among mid-market financial services firms seeking to defer data center specialization investments.
Canada Data Center Networking Market Segmentation
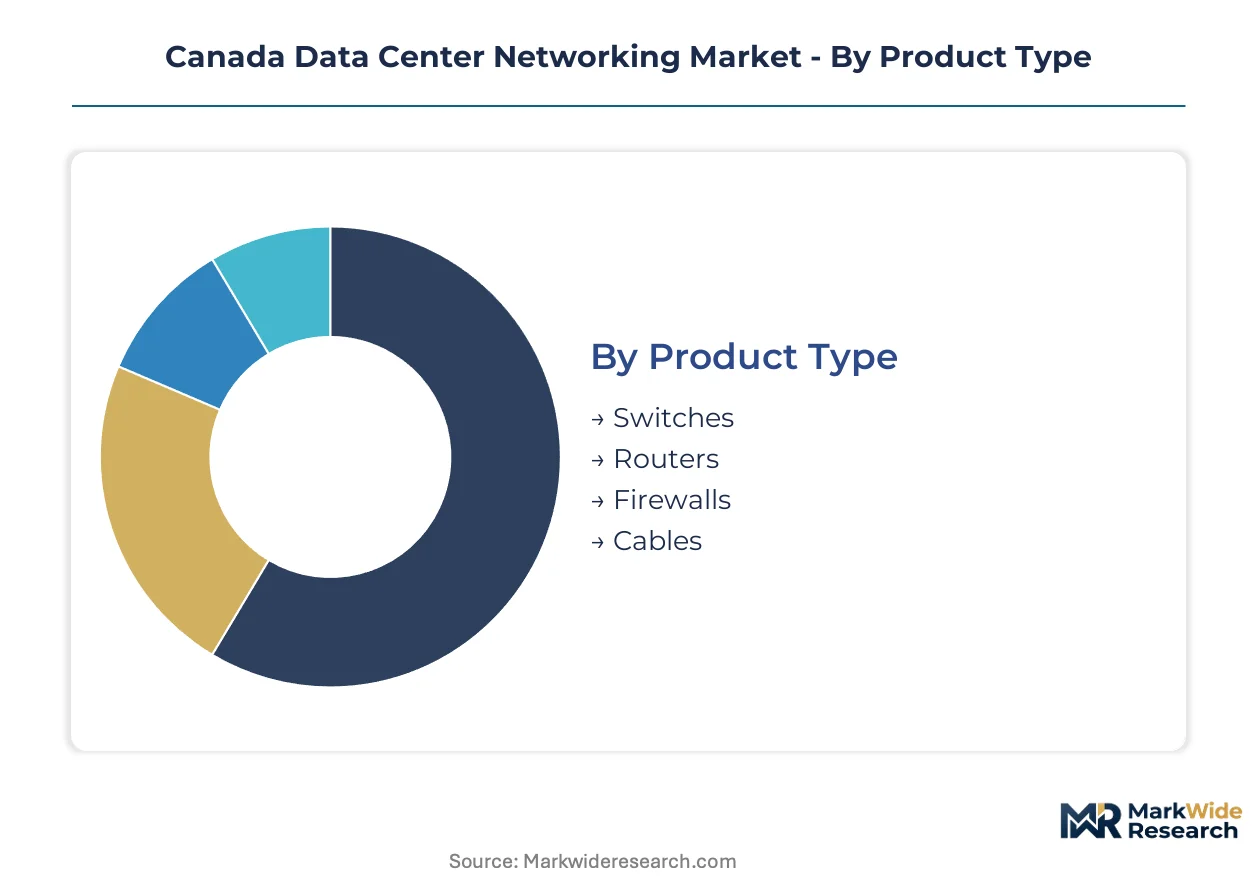
Segmentation reveals how procurement patterns diverge across Canadian data center networking. Health Canada data residency mandates and PIPEDA compliance requirements reshape equipment selection criteria by vertical. Hyperscale operators in Toronto and Montreal drive distinct purchasing rhythms compared to enterprise colocation tenants in secondary markets.
Product Type:
Domestic demand concentrates on switching and routing hardware serving sovereign cloud buildouts, while cable and firewall procurement increasingly sources through managed service overlays in Vancouver and Calgary.
- Switches:Spine-leaf architectures displace legacy three-tier designs across Ontario and Quebec facilities. Toronto hyperscale campuses absorb high-density 400G and 800G platforms for AI cluster backbones, constrained by optical component bottlenecks in coherent DSP modules.
- Routers:Border and core routing platforms handle inter-facility traffic across distributed cloud regions. Montreal financial services hubs demand sub-microsecond latency guarantees, compressing refresh cycles for specialized fabric deployments.
- Firewalls:Health Canada cybersecurity frameworks mandate certified hardware for medical data infrastructure, extending validation timelines for healthcare verticals.
- Cables:Fiber optic technician scarcity in secondary markets unwinds deployment schedules for physical layer infrastructure.
Switches command the established base. The steepest expansion runs through Routers.
Application:
Cost tier differentiation separates capital-intensive AI training workloads from operational expenditure models gaining traction among mid-market enterprises.
- Cloud Computing:Distributed GPU clusters for AI training and real-time analytics pipelines generate premium fabric demand. Ontario and Quebec hyperscale operators deploy specialized networks supporting trillion-parameter model training across contiguous rack deployments.
- Virtualization:Software-defined compute orchestration requires low-latency east-west traffic patterns. Financial services incumbents in Toronto retrofit legacy mainframe interconnects toward standard Ethernet fabrics.
- Storage Solutions:NVMe-oF and distributed object storage networks concentrate in Vancouver greenfield developments.
- Disaster Recovery:Cross-provincial replication mandates drive procurement of encrypted wide-area interconnects for PIPEDA compliance.
Cloud Computing absorbs the dominant share of specialized fabric investment. Storage Solutions climb fastest as western buildouts accelerate.
End User:
Customer type segmentation shows financial services anchoring premium pricing while healthcare compliance costs reshape vendor selection.
- Financial Services:Sub-millisecond latency requirements and deterministic performance command sustained investment in specialized low-latency fabrics. Toronto banking clusters maintain captive engineering teams for network optimization.
- Healthcare:Health Canada data residency requirements and PIPEDA encryption mandates elevate total cost of ownership. Colocation providers absorb compliance investments into long-term lease structures for hospital system tenants.
- Telecommunications:Incumbent carriers leverage entrenched channel relationships for hardware refresh cycles across enterprise and wholesale segments.
- Media:Content delivery and streaming infrastructure concentrates in Vancouver proximity to transpacific cable landing points.
Financial Services retains the premium spending base. Healthcare expands most quickly as sovereign cloud mandates deepen.
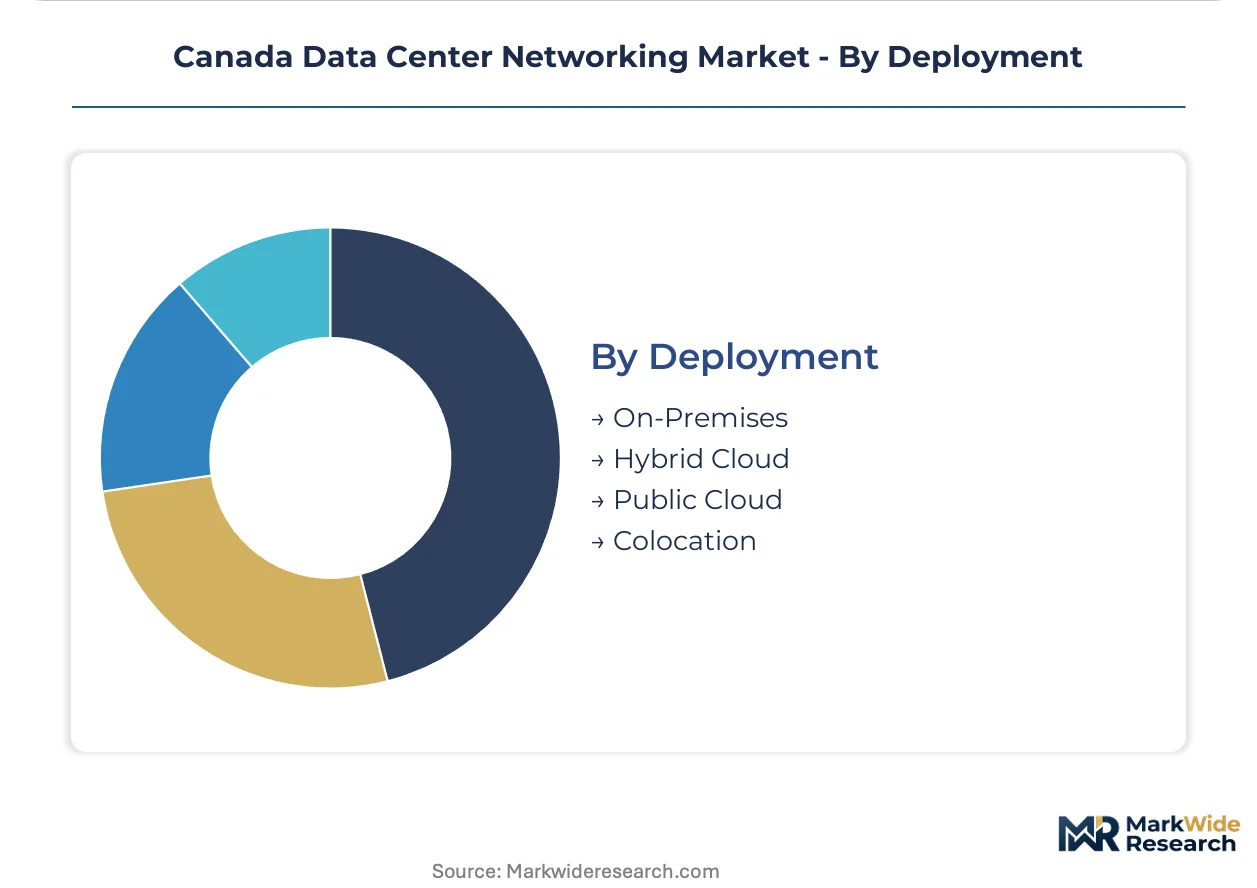
Deployment:
Maturity gradients separate established on-premises financial services infrastructure from emerging consumption-based models in western sub-markets.
- On-Premises:Enterprise-owned facilities in Toronto and Montreal maintain direct control over specialized low-latency fabrics. Legacy three-tier architectures face accelerated replacement timelines under spine-leaf migration pressure.
- Colocation:Multi-tenant facilities absorb Health Canada compliance costs into certified hardware retrofits for healthcare verticals. Vancouver and Calgary markets remain underpenetrated relative to Ontario and Quebec concentration.
- Hybrid Cloud:Workload portability requirements drive intent-based networking and automation investments across distributed architectures.
- Public Cloud:Hyperscale operator procurement concentrates switching and routing demand in contiguous facility clusters.
On-Premises retains the installed base dominance. Colocation gains share fastest as managed service overlays displace capital acquisition models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada data residency mandates and PIPEDA privacy frameworks anchor procurement decisions across Canadian provinces, concentrating hyperscale investments in Ontario and Quebec while western sub-markets absorb carbon-neutral incentives.
Ontario
AI training clusters and financial services hubs drive specialized fabric demand in Toronto. The provincial utilities regulator enforces escalating power usage effectiveness thresholds. Toronto hyperscale campuses deploy high-density 400G and 800G platforms for GPU workloads.
Quebec
Low-cost hydroelectric power attracts cloud operators building sovereign cloud infrastructure. Health Canada cybersecurity guidance mandates encryption-at-rest for medical data networks. Montreal financial services clusters maintain captive engineering teams for sub-microsecond latency optimization.
British Columbia
Vancouver proximity to transpacific cable landing points concentrates content delivery infrastructure. Federal sustainability incentives reward facilities achieving net-zero operational status. Metro Vancouver greenfield developments absorb NVMe-oF and distributed storage network investments.
Alberta
Calgary sub-markets remain underpenetrated relative to central Canada concentration. Provincial carbon pricing mechanisms reshape total cost of ownership calculations for legacy equipment. Calgary enterprise tenants increasingly procure switching capacity through managed service overlays.
Atlantic Canada
Disaster recovery and cross-provincial replication mandates drive encrypted wide-area interconnect procurement. PIPEDA compliance requirements elevate encryption-in-transit standards for personal health information. Halifax and Moncton facilities serve as secondary sites for Ontario and Quebec primary workloads.
Canada Data Center Networking Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Canadian data center networking market. The vendor base concentrates around established networking hardware specialists, cloud-scale platform providers, and diversified IT infrastructure conglomerates. Three strategic archetypes dominate: merchant silicon integrators pursuing high-density switching platforms, captive ASIC developers optimizing for AI cluster backbones, and full-stack lifecycle providers bundling hardware with managed services. Competitive moves center on strategic partnerships with hyperscale operators and portfolio diversification into computational offload technologies.
Among the established networking specialists, Cisco Systems Inc., Arista Networks Inc., and NVIDIA (Cumulus Networks) exemplify distinct strategic positions. Cisco Systems Inc. represents the entrenched channel relationship archetype, leveraging long-standing telecommunications carrier partnerships. Arista Networks Inc. occupies the cloud-scale specialization tier, with its company name signaling focus on high-performance environments. NVIDIA (Cumulus Networks) anchors the computational convergence archetype, reflecting industry-wide integration of networking with AI infrastructure.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Arista Networks Inc. |
| NVIDIA (Cumulus Networks) |
| Huawei Technologies Co. Ltd. |
| VMware Inc. |
| Dell Technologies |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Broadcom |
| Others |
Pricing and Supply Chain Analysis
Hyperscale facility utilization rates above 85 percent in Toronto and Montreal compress procurement timelines while elevating price floors for specialized 400G and 800G switching platforms. This capacity tightness concentrates vendor pricing power among merchant silicon integrators serving sovereign cloud buildouts, forcing mid-market enterprises toward managed service overlays that absorb hardware costs into operational expenditure structures.
Pricing Analysis
Ontario commands 15-20 percent premiums over Vancouver and Calgary sub-markets for equivalent spine-leaf switching platforms, reflecting fiber optic technician scarcity and accelerated deployment schedules. Three-tier pricing structure across premium, standard, and economy levels separates Health Canada-certified hardware from uncertified alternatives, with encryption-at-rest mandates elevating total cost of ownership for healthcare verticals. Pricing pressure stems from hyperscale operators consolidating procurement volumes around captive ASIC developers, compressing margins for merchant silicon vendors. Mid-market financial services firms in western Canada exhibit highest price sensitivity, deferring capital investments through consumption-based managed service contracts.
Supply Chain Analysis
Port congestion at Vancouver and Prince Rupert elevates inbound logistics costs for optical transceivers and silicon photonics modules sourced through transpacific trade lanes. Manufacturing concentration rests on Taiwan, South Korea, and the United States for coherent DSP chips, switch ASICs, and advanced optical engines. Raw material dependencies center on germanium substrates, indium phosphide wafers, and rare earth elements for laser components. Single-source vulnerability in 51.2Tbps merchant silicon creates procurement risk for AI cluster backbone deployments. Distribution runs through authorized channel partners with Health Canada certification credentials, filtering market access for uncertified vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada data center networking sits in early-cycle expansion as sovereign cloud mandates and AI training cluster deployments accelerate facility investments across Ontario and Quebec. Spine-leaf architecture migration and sub-microsecond latency requirements create durable tailwinds for specialized fabric vendors.
For Market Incumbents: Secure channel control through exclusive partnerships with telecommunications carriers building sovereign cloud infrastructure in Montreal and Toronto. Deepen captive ASIC development capabilities to defend margin position against merchant silicon price erosion from NVIDIA and Broadcom. Health Canada cybersecurity framework extensions threaten extended validation timelines—invest in pre-certified hardware portfolios to compress deployment schedules for healthcare verticals. For New Entrants and Emerging Players: Anchor in Calgary and Vancouver sub-markets where fiber optic technician scarcity has unwound incumbent expansion timelines, creating first-mover windows for greenfield developments. Target mid-market financial services firms seeking consumption-based procurement models as the most penetrable segment. Lead with SmartNIC and DPU convergence platforms that bundle computational offload with switching fabrics, differentiating against hardware-only incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-stack lifecycle providers with managed service overlays, as operational expenditure models displace capital acquisition across western Canada. Long-term viability hinges on software-defined control plane investments and intent-based networking automation capabilities. Acquisition target archetype: regional colocation operators with Health Canada certification credentials and renewable energy procurement contracts. Watch hyperscale operator capex allocation shifts between Ontario and Quebec as the primary inflection indicator for vendor market share rotation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Silicon photonics switching with embedded coherent optical engines enables 51.2Tbps AI cluster backbones for Toronto hyperscale campuses. |
| Strategic Partnership | Channel alliances with telecommunications carriers filter market access through Health Canada certification requirements for healthcare verticals. |
| Acquisition of Specialist Firm | SmartNIC and DPU developers add computational offload capabilities that command premium pricing in workload-optimized platforms. |
| Geographic Expansion | Calgary and Vancouver greenfield developments capture carbon-neutral incentives while Ontario and Quebec face power usage effectiveness constraints. |
| Product Launch | Pre-certified encryption-at-rest hardware compresses validation timelines under PIPEDA mandates for medical data infrastructure. |
Research Methodology
Cross-validation between executive interviews with data center operators and secondary analysis of hyperscaler capex disclosures anchors the qualitative findings in this study. Primary fieldwork engaged network engineering directors at financial services institutions, procurement leads at colocation providers, channel partner managers, and provincial utilities regulators. Secondary sources include Health Canada cybersecurity guidance documents, PIPEDA compliance frameworks, Office of the Privacy Commissioner rulings, and facility permitting records from Ontario and Quebec regulators. Bottom-up equipment procurement estimates triangulate against top-down infrastructure investment forecasts.
Sensitivity analysis around fiber optic technician availability and optical component lead times shapes the projection framework. Segmentation dimensions span product type, application workload, end-user vertical, and deployment model across the analysis window. CAGRs derive from equipment refresh cycle compression rates and hyperscale facility buildout schedules. Industry-specific inputs include AI training cluster density requirements and Health Canada validation timeline distributions for certified hardware.
Underlying assumptions cover sustained PIPEDA enforcement intensity and stable hydroelectric power cost advantages in Quebec, with deviation risk concentrated in provincial utilities regulator threshold adjustments and transpacific logistics disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
5G Edge Cloud Network and Services Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
South Africa Data Center Server Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
GPU Database Market
Data Center and Networking
North America Data Center Networking Market
Data Center and Networking
Chile Data Center Networking Market