
 Europe Construction Chemicals Market | 2026-2036
Europe Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Construction Chemicals Market Analysis
Performance-based maintenance contracts and software-defined coating warranties is shifting how European construction chemical value gets captured and renewed. Sika AG anchors this transition through its integrated service platforms across Swiss and German infrastructure corridors. BASF differentiates via R&D intensity in polyurethane sealants and reactive adhesives for commercial facades. Mapei dominates Southern European distribution through specialized grout and mortar formulations tailored to seismic retrofit codes.
Construction chemicals encompass admixtures, sealants, coatings, and grouts formulated to modify cementitious systems, protect structural substrates, or restore deteriorated concrete. These formulations typically incorporate polymers, surfactants, and corrosion inhibitors to achieve specified compressive strength gains, permeability reduction, or chloride ion resistance thresholds in finished structures. Admixtures and waterproofing systems command the deepest margin pools, driven by specification-driven procurement in infrastructure and commercial end-use segments. Concrete repair applications are expanding fastest, reflecting aging bridge and tunnel inventories across the continent. Sealants and surface protection categories remain mature, with growth tethered to new-build residential cycles.
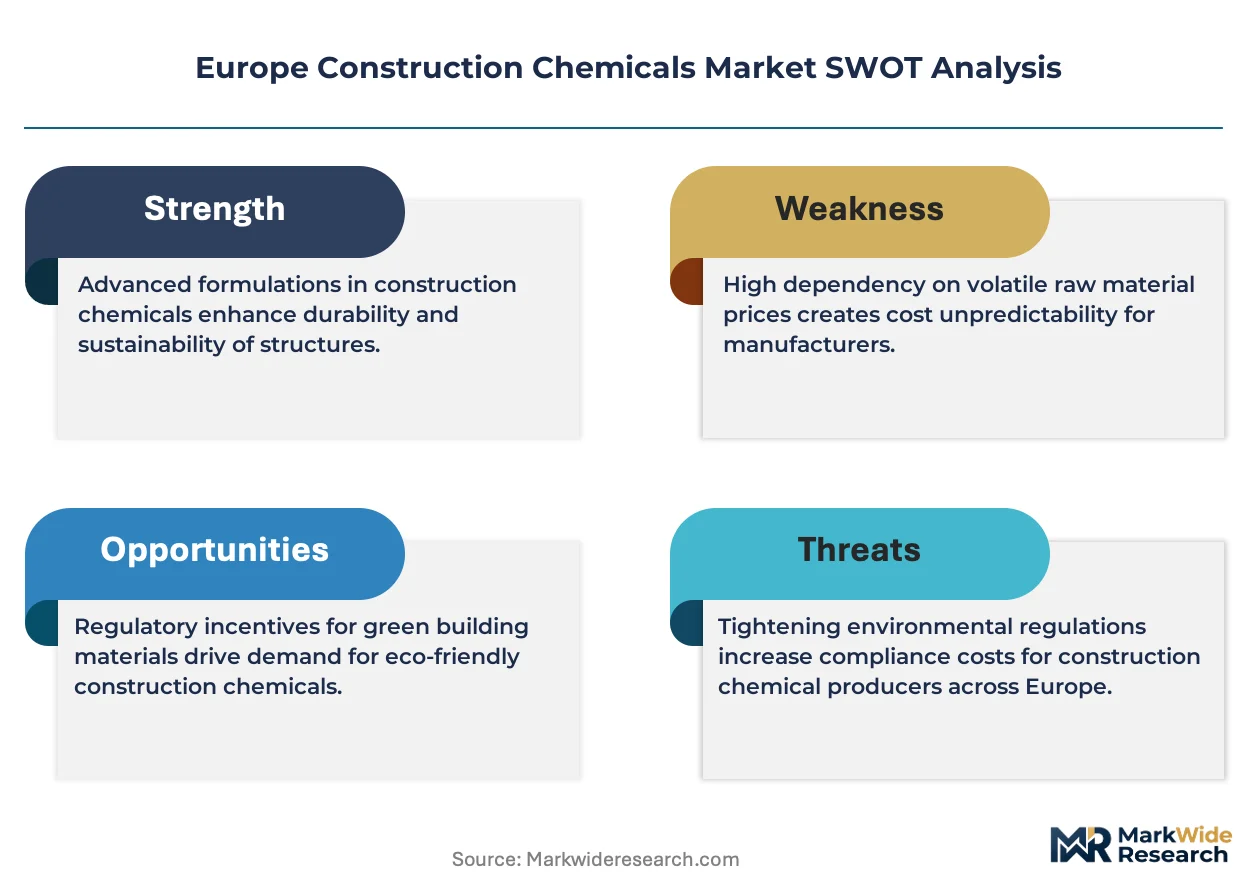
REACH compliance and the EU Green Deal's carbon disclosure requirements are tightening feedstock traceability and VOC thresholds for coating formulations sold across member states. CE marking under the Construction Products Regulation and national building codes in Germany and France govern market access for structural repair mortars and injection resins. ECHA substance evaluations are accelerating substitution timelines for certain biocidal film preservatives. Stakeholders must monitor evolving embodied carbon benchmarks and national transpositions of the Energy Performance of Buildings Directive to align product portfolios with specification criteria that will govern procurement decisions.
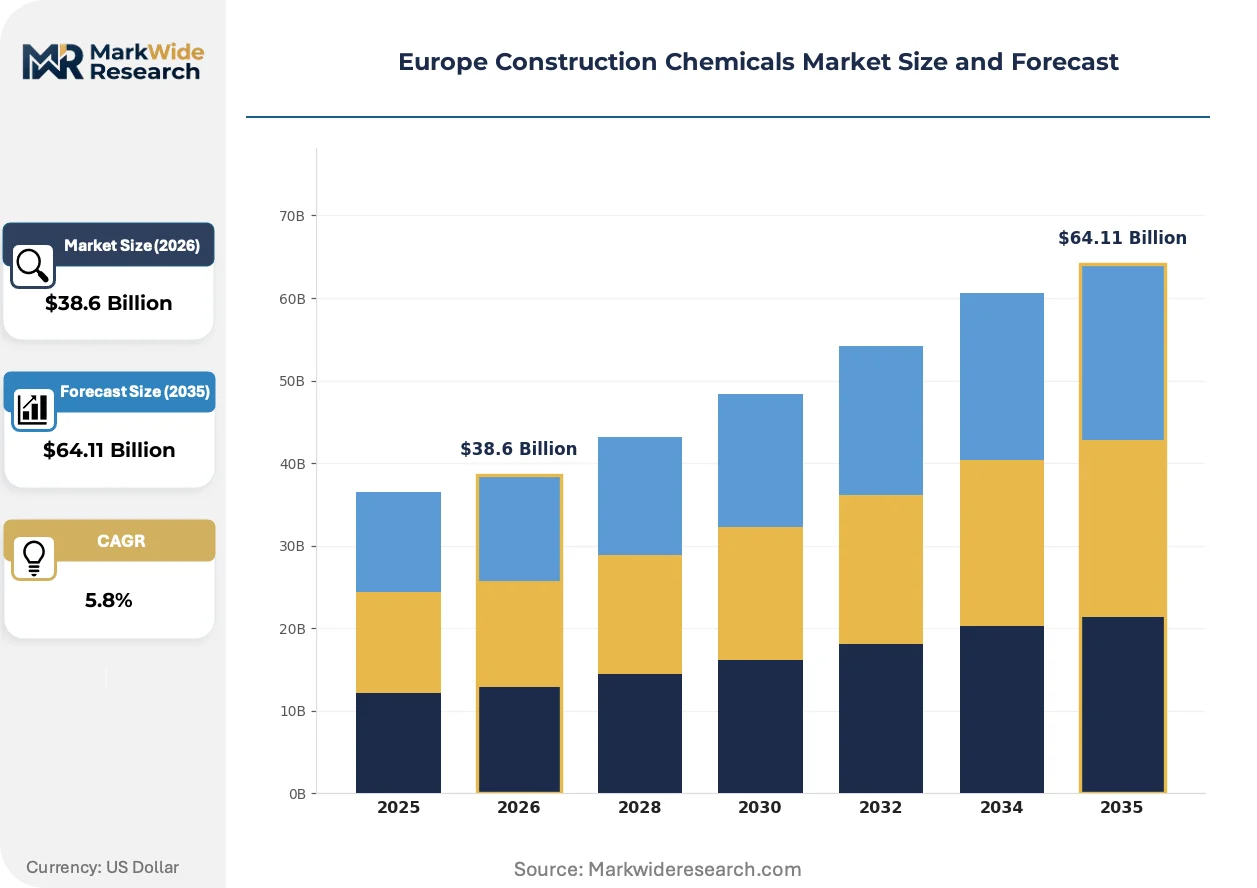
Market Dynamics
EU Green Deal embodied carbon benchmarks are forcing rapid reformulation across construction chemical portfolios, redirecting R&D spend from performance optimization to clinker reduction and bio-based feedstock substitution. This regulatory pressure is compressing traditional product lifecycles while opening specification gates for low-carbon alternatives.
Growth Catalysts
- Energy Performance of Buildings Directive transposition:German and French national building codes are tightening thermal envelope requirements, accelerating specification of advanced insulation admixtures and thermal bridge sealants in commercial renovation corridors.
- Seismic retrofit codes:Italy's updated technical standards for concrete repair are expanding injection resin volumes for aging bridge and tunnel inventories across Alpine and Apennine infrastructure networks.
- Polymer-modified cementitious systems:Waterproofing specifications for below-grade commercial construction are displacing traditional bituminous membranes with crystalline and flexible cementitious alternatives in Scandinavian markets.
Market Restraints
- Epoxy resin feedstock volatility:Bisphenol-A and amine hardener price swings are compressing margin stability for coating and adhesive formulators serving marine and industrial protection segments.
- REACH substance evaluation timelines:ECHA's accelerating biocidal active substance reviews are forcing premature reformulation of film preservatives in exterior coating systems before commercial alternatives achieve scale.
- Portland cement clinker substitution limits:Current low-clinker binder performance gaps in early-strength development are constraining adoption in fast-track infrastructure repair applications.
Strategic Opportunities
- Carbon capture utilization in concrete curing:CO2 mineralization technologies for precast concrete production are creating specification pathways for admixture suppliers in Dutch and Belgian manufacturing clusters.
- Rural and secondary city building stock:Underpenetrated renovation markets in Poland and Romania present white space for distributed mortar and grout formulation networks outside established Western European distribution density.
- Digital building passports:EU-level material traceability mandates are opening service revenue streams for chemical suppliers offering embodied carbon data and lifecycle documentation platforms.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in bio-based polymer synthesis and cement hydration kinetics is concentrating among a shrinking pool of technical professionals in German and Swiss research corridors.
- CE marking conformity assessment backlog:Notified body capacity constraints are extending time-to-market for structural repair mortars and injection resins targeting infrastructure rehabilitation contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Construction Chemicals Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Coatings, Grouts End User: Residential, Commercial, Industrial, Infrastructure Application: Concrete Repair, Surface Protection, Waterproofing, Flooring Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Sika AG, BASF, Mapei, Saint-Gobain, RPM International, Henkel, Arkema, Fosroc, Dow, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Construction Chemicals Market Emerging Trajectories
Formulation science is converging with digital specification tools and carbon accounting platforms, compressing the traditional separation between material supply and building performance verification. This integration is reshaping how technical value gets captured and renewed across project lifecycles.
Self-healing concrete admixtures incorporating microencapsulated bacteria and mineral precursors are unifying structural durability with reduced maintenance intervention cycles. German infrastructure asset managers are piloting these systems in tunnel lining applications where access constraints amplify lifecycle cost sensitivity. The technology is unifying material supply with long-term performance guarantees, shifting contract structures toward outcome-based maintenance partnerships.
REACH authorization and restriction procedures are tightening VOC thresholds for architectural coatings while accelerating substitution timelines for chromate-based corrosion inhibitors in reinforced concrete protection. Formulators serving Dutch and Belgian marine infrastructure are reformulating passivation systems around organic alternatives ahead of sunset date certainty. Waterborne epoxy and silane-siloxane systems are capturing specification share in North Sea offshore asset protection where environmental discharge regulations are most stringent.
Asset owner procurement teams are consolidating supplier relationships around integrated material-plus-service platforms, displacing transactional product purchasing in commercial facade and infrastructure maintenance segments. Engineering firms in French urban renovation corridors are bundling coating specification with application warranties and digital condition monitoring. This consolidation is most visible in German commercial property management where energy efficiency retrofit mandates are compressing contractor selection timelines.
Europe Construction Chemicals Market Segmentation
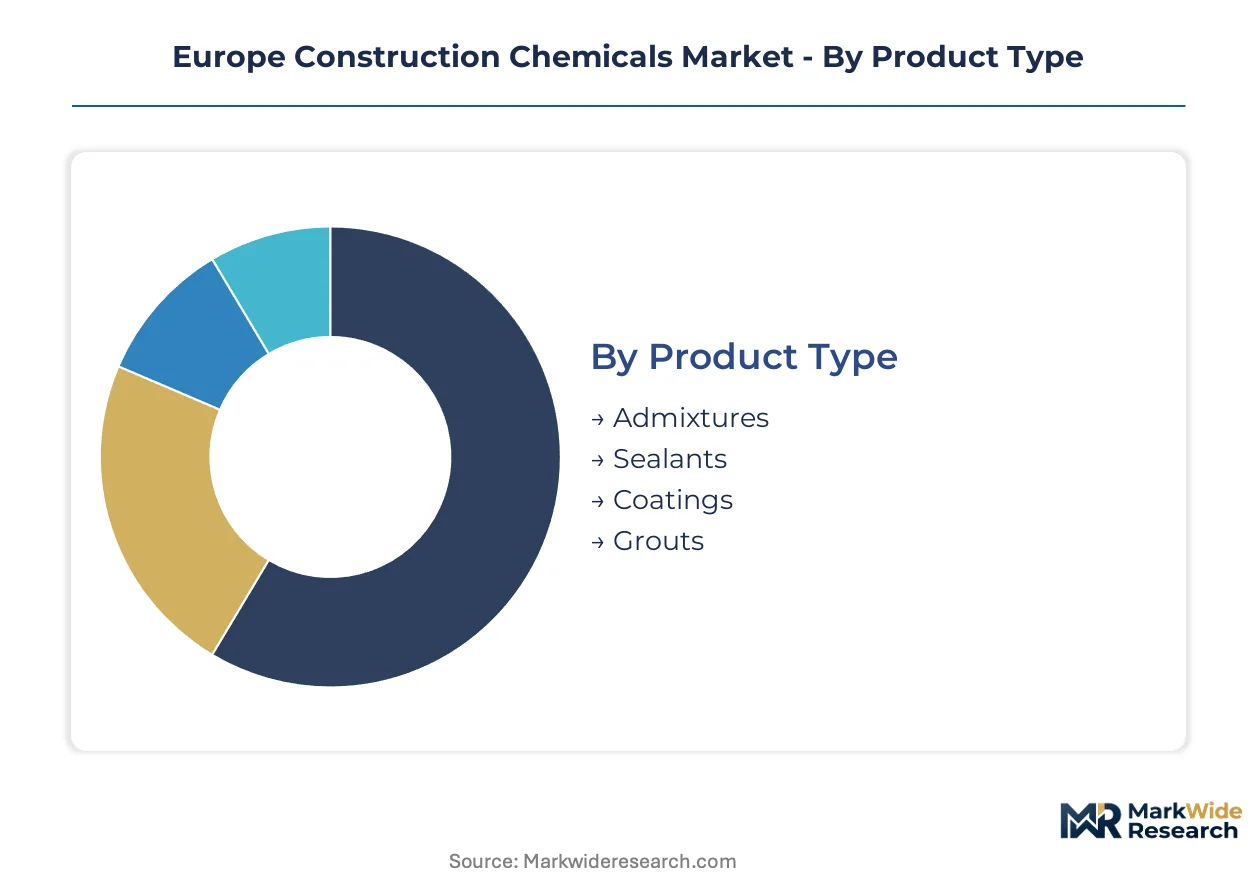
Construction chemicals serve heterogeneous performance requirements across structural, protective, and aesthetic functions. Segment boundaries reflect capital deployment patterns in manufacturing assets, formulation R&D, and specification relationships with asset owners.
Product Type:
Admixtures and coatings demand the heaviest upfront investment in polymer synthesis capabilities and REACH-compliant testing infrastructure. Sealants and grouts require less specialized production but intensive technical service networks.
- Admixtures:Polymer-modified formulations alter cement hydration kinetics to achieve specified compressive strength gains or permeability reduction. German commercial renovation corridors are accelerating specification of thermal performance admixtures under tightening Energy Performance of Buildings Directive transpositions.
- Coatings:Waterborne epoxy and silane-siloxane systems protect structural substrates from chloride ion ingress and carbonation. Dutch and Belgian marine infrastructure contractors are reformulating around organic corrosion inhibitors ahead of ECHA biocidal active substance reviews.
- Sealants:Polyurethane and silicone formulations accommodate structural movement while maintaining envelope integrity. Thermal bridge sealants are gaining specification share in French urban renovation corridors.
- Grouts:Cementitious and epoxy injection systems restore load-bearing capacity in deteriorated concrete. Italian seismic retrofit codes are expanding volumes for Alpine and Apennine bridge inventories.
Most installed capacity flows through admixtures. Expansion is steepest in coatings.
End User:
Customer procurement sophistication varies sharply across segments, with infrastructure and commercial buyers driving specification complexity while residential channels prioritize logistics efficiency.
- Infrastructure:Public asset managers specify performance-guaranteed systems for bridge, tunnel, and marine applications. German infrastructure corridors are piloting self-healing concrete admixtures under outcome-based maintenance contracts.
- Commercial:Property developers and facility managers bundle material supply with application warranties and digital condition monitoring. Energy efficiency mandates in German commercial renovation are compressing contractor selection timelines.
- Industrial:Manufacturing facility owners demand chemical-resistant flooring and protective coatings for process environments. Scandinavian below-grade specifications are displacing bituminous membranes with crystalline cementitious alternatives.
- Residential:New-build and renovation contractors prioritize stocked availability and simplified application. Polish and Romanian secondary cities present white space for distributed mortar networks outside Western European density.
Infrastructure commands the deepest technical relationships. Commercial is gaining specification influence fastest.
Application:
Performance verification requirements and project lifecycle economics shape application-level procurement, with repair and protection applications demanding documented durability guarantees.
- Concrete Repair:Injection resins and patch mortars restore structural integrity in aging reinforced concrete. Italian technical standards for seismic retrofit are accelerating volumes across Alpine tunnel networks.
- Waterproofing:Below-grade and roofing systems prevent moisture ingress through flexible membranes or crystalline cementitious barriers. Scandinavian commercial construction is specifying polymer-modified cementitious alternatives to traditional bitumen.
- Surface Protection:Anti-carbonation and chloride-resistant coatings extend service life in aggressive exposure conditions. Dutch marine contractors are adopting waterborne epoxy systems under stringent North Sea discharge regulations.
- Flooring:Industrial and decorative screeds provide wear resistance and chemical containment. Industrial end-users in Belgian manufacturing clusters are specifying CO2-mineralized precast systems.
Waterproofing holds the largest installed base. Concrete repair is climbing the fastest.
Distribution Channel:
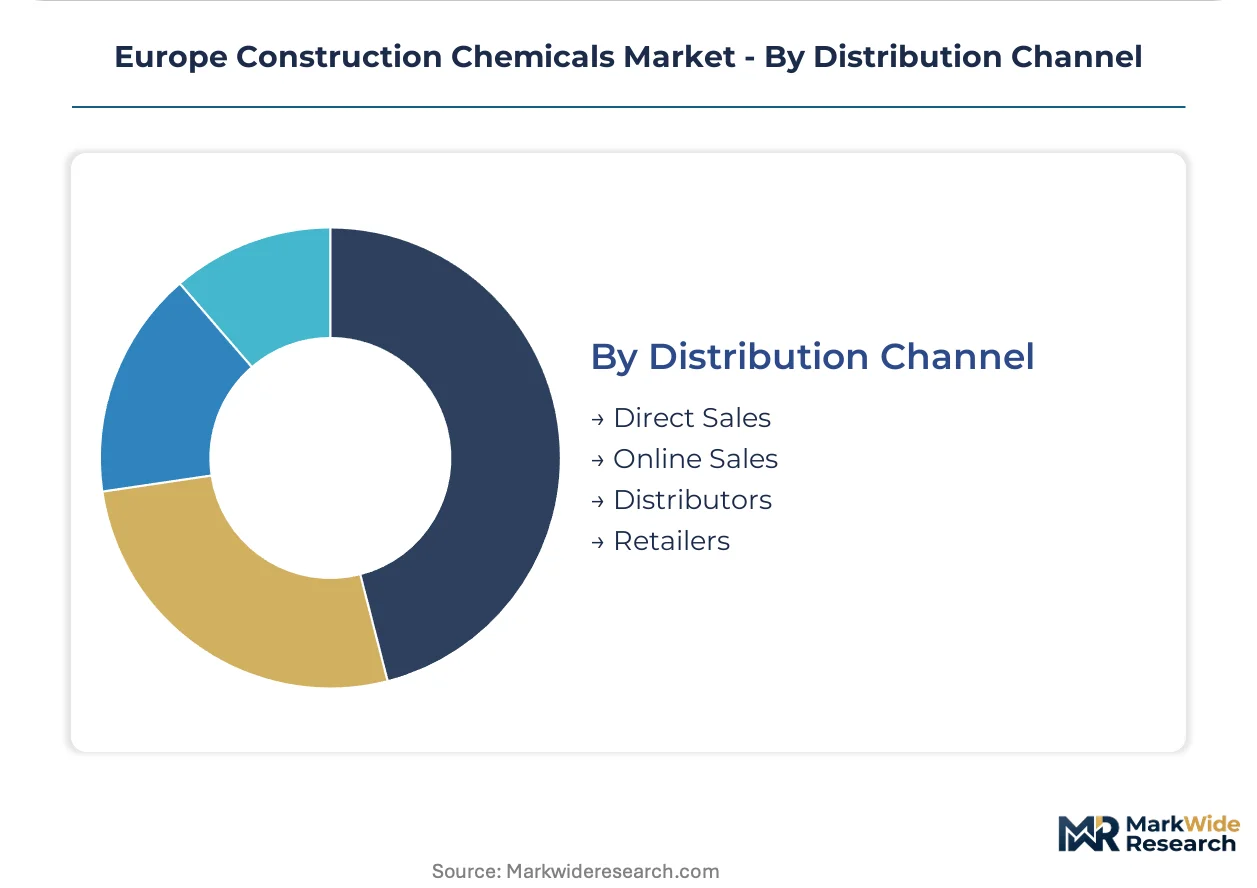
Channel selection reflects order fragmentation, technical support intensity, and geographic coverage requirements across customer segments.
- Distributors:Regional stocking intermediaries serve fragmented contractor bases with credit terms and local delivery. Mapei's Southern European dominance runs through specialized grout and mortar distribution networks.
- Direct Sales:Manufacturer-employed technical representatives manage specification relationships with major infrastructure and commercial asset owners. Sika AG anchors integrated service platforms across Swiss and German corridors through direct engagement.
- Retailers:Big-box and trade counters serve residential renovation and small commercial maintenance with standard formulations. Polish and Romanian rural building stock remains underpenetrated by organized retail.
- Online Sales:Digital procurement platforms are emerging for standardized products with documented performance data. EU digital building passport mandates are creating service revenue streams for lifecycle documentation platforms.
Distributors handle the greatest volume throughput. Direct sales is deepening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands deeper specification influence than France in commercial renovation corridors, though Italian infrastructure networks generate comparable injection resin volumes through seismic retrofit mandates. The EU Green Deal's embodied carbon benchmarks are redirecting formulation priorities across all four markets.
Germany
Commercial property managers in Berlin and Frankfurt are bundling coating procurement with digital condition monitoring under tightening Energy Performance of Buildings Directive transpositions. The national building code is accelerating thermal bridge sealant specifications in facade retrofit projects. Bavarian manufacturing clusters are piloting CO2 mineralization technologies for precast concrete admixtures.
France
Engineering firms in Paris and Lyon urban corridors are consolidating supplier relationships around integrated material-plus-service platforms. The country's national building regulator is enforcing stricter thermal envelope requirements under EU directive transpositions. Île-de-France infrastructure asset managers are specifying self-healing concrete admixtures for tunnel lining applications.
Italy
Alpine and Apennine bridge inventories are expanding injection resin volumes under updated seismic retrofit technical standards. ANSN national regulations are mandating documented durability guarantees for structural repair mortars. Lombardy and Veneto distribution networks are specializing in grout formulations tailored to regional seismic codes.
Netherlands
Marine infrastructure contractors in Rotterdam and Amsterdam are reformulating coating systems around organic corrosion inhibitors ahead of ECHA biocidal reviews. REACH compliance is tightening VOC thresholds for waterborne epoxy specifications. Dutch precast manufacturing clusters are creating specification pathways for carbon capture utilization admixtures.
Poland
Secondary city building stock in Kraków and Wrocław presents white space for distributed mortar networks outside Western European density. The country's national building code is gradually aligning with EU energy efficiency benchmarks. Polish contractors are prioritizing stocked availability and simplified application in residential renovation channels.
Europe Construction Chemicals Market Vendor Landscape
Top-tier vendors anchor specification relationships with infrastructure asset managers, while mid-tier specialists capture share through regional distribution density and application technical service. The vendor base clusters around three strategic archetypes: integrated material-plus-service platforms, polymer synthesis specialists with R&D intensity, and distribution-anchored formulation networks. Consolidation pressure is accelerating through outcome-based maintenance contracts and digital building passport service bundling.
Among Swiss and German integrated platforms, Sika AG anchors service relationships across Alpine infrastructure corridors. BASF represents polymer synthesis intensity in sealant and adhesive categories. Mapei exemplifies Southern European distribution dominance through specialized grout networks.
| Leading Market Players |
|---|
| Sika AG |
| BASF |
| Mapei |
| Saint-Gobain |
| RPM International |
| Henkel |
| Arkema |
| Fosroc |
| Dow |
| Others |
Supply Flow & Price Mechanics
EU Green Deal embodied carbon mandates are compressing specification windows for low-clinker binders, forcing suppliers to absorb reformulation costs while asset owners demand performance-guaranteed pricing for retrofit projects across German and French commercial corridors.
Pricing Analysis
Capacity additions in Belgium and the Netherlands are reshaping price floors for crystalline waterproofing admixtures. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier and technical service bundling. Cost compression in economy-grade sealants is intensifying because epoxy resin feedstock volatility from Bisphenol-A supply swings. Infrastructure asset managers show least price sensitivity due to outcome-based maintenance contracts, while residential contractors in Polish secondary cities prioritize stocked availability over performance premiums.
Supply Chain Analysis
Domestic-content preferences in Italian seismic retrofit procurement are redirecting sourcing toward Lombardy and Veneto formulation networks. Manufacturing concentrates in Germany, Italy, and Switzerland. Feedstock draws from Saudi aromatics for epoxy hardeners, Norwegian silicates for pozzolanic binders, and Belgian petrochemical derivatives for polyurethane precursors. Single-source vulnerability sits with amine hardener supply from specialty chemical clusters. Distribution runs through regional stocking intermediaries serving fragmented contractor bases with credit terms and local technical service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Construction Chemicals Market functions as a stable compounder anchored by regulatory retrofit mandates that ensure recurring specification demand across aging infrastructure inventories.
For Market Incumbents: Deepen backward integration into bio-based polymer feedstocks to defend margin position against REACH-driven reformulation cycles. Lock in notified body relationships to compress CE marking timelines for structural repair mortars. Prioritize carbon accounting platform investments to capture digital building passport service revenue. For New Entrants and Emerging Players: Begin with distributed mortar networks in Polish and Romanian secondary cities where Western European distribution density remains absent. Target residential renovation contractors prioritizing stocked availability and simplified application. Pursue white-label formulation partnerships with regional distributors to bypass direct specification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier specialists possessing seismic retrofit code expertise and Southern European distribution density. The five-to-ten year viability window favors platforms integrating material supply with outcome-based maintenance contracts. Watch ECHA biocidal active substance review timelines as inflection triggers for coating formulation substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Secures supply certainty for low-carbon binder formulations under EU Green Deal benchmarks. |
| CE Marking Fast-Track Investment | Compresses time-to-market for structural repair mortars targeting German infrastructure contracts. |
| Digital Building Passport Platform Launch | Captures service revenue from EU material traceability mandates in Dutch and Belgian markets. |
| Seismic Retrofit Code Specialization | Locks specification relationships with Italian Alpine and Apennine bridge asset managers. |
| Carbon Capture Utilization Partnership | Creates specification pathways for admixture suppliers in Dutch precast manufacturing clusters. |
Methodological Framework
Multiple input streams — technical interviews with formulation chemists and plant managers, procurement discussions with infrastructure asset managers, and secondary validation through customs data and Cefic industry reports — were reconciled to construct bottom-up and top-down estimates. Primary engagement captured specification practices across German commercial renovation, Italian seismic retrofit, and Dutch marine infrastructure corridors. Secondary sources included SEC filings from listed chemical suppliers, ECHA substance evaluation databases, and national building code transposition documents.
Historical volume trajectories were cross-referenced against panel-based input from distribution channel partners and technical service directors. The analytical framework modeled segmentation across product type, end-use industry, application function, and regional production hub throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves incorporating Energy Performance of Buildings Directive implementation timelines and clinker substitution rate assumptions.
Several conditions sit outside the modeled scope, including abrupt REACH substance restrictions, geopolitical disruptions to epoxy resin feedstock flows, and unanticipated cement chemistry breakthroughs. Forecasts reflect documented assumptions about regulatory implementation pacing and contractor adoption curves. A small set of named triggers — ECHA biocidal review outcomes, German notified body capacity expansion, and EU digital passport technical standard finalization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Bamboo Engineered Wood Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Commercial Glazing Market