
 Germany Cloud Robotics Market | 2026-2036
Germany Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Cloud Robotics Market Insights
A chronic shortage of mechatronics engineers is unwinding traditional on-premise robotics deployment across German manufacturing hubs. KUKA AG leverages its Augsburg headquarters to sustain deep integration between cloud platforms and automotive production lines. Siemens AG anchors industrial edge-to-cloud architectures through its Munich-based digital industries division. Bosch Rexroth AG competes on hydraulic-to-cloud convergence for smart factory retrofit programs.
Germany cloud robotics denotes distributed robotic systems that offload computation, data storage, and machine learning model execution to remote cloud infrastructure via low-latency connectivity protocols, typically operating with sub-50ms response thresholds for real-time teleoperation. These systems serve primarily to decouple physical robot hardware from cognitive processing, enabling fleet-scale software updates and collaborative learning across geographically dispersed assets. Hybrid cloud deployment captures dominant share among German manufacturers balancing data sovereignty requirements against computational elasticity, while edge computing integration represents the fastest-expanding technology layer as latency-sensitive predictive maintenance applications multiply. Warehouse automation leads end-user application value pools, though remote monitoring is gaining traction among capital-equipment suppliers seeking recurring service revenue models.
Germany's Federal Network Agency and the EU AI Act compliance framework impose algorithmic transparency and risk-classification obligations on autonomous robotic systems deployed in industrial settings. KBA vehicle-safety protocols and ISO 10218 collaborative robot standards further constrain cloud-connected motion planning architectures. Stakeholders must weigh cloud infrastructure vendor lock-in against the operational flexibility of multi-cloud orchestration strategies as regulatory scrutiny intensifies.
Market Dynamics
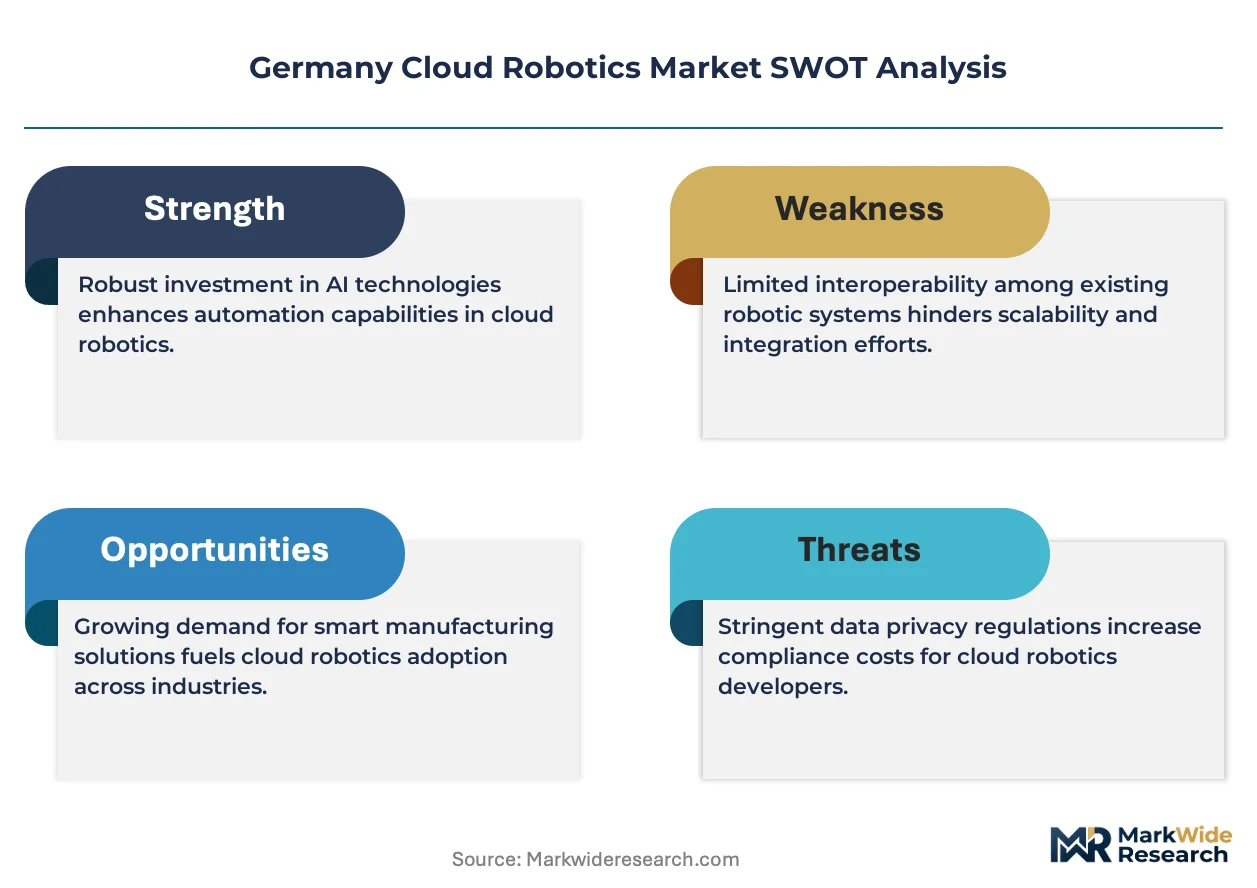
EU AI Act risk-classification mandates are forcing immediate compliance upgrades across German automotive and Mittelstand manufacturing clusters, accelerating replacement cycles for legacy robotic control systems.
Growth Catalysts
- Industry 4.0 certification programs:Baden-Württemberg and Bavaria state governments subsidize cloud-connected retrofit installations for mid-tier exporters seeking digital readiness badges.
- Predictive maintenance protocols:Hydraulic press operators in Stuttgart industrial corridors deploy vibration-sensing cloud robotics to eliminate unplanned downtime.
- Edge-to-cloud convergence:Real-time motion planning algorithms now execute split processing between factory floor nodes and remote infrastructure.
Market Restraints
- Mechatronics talent scarcity:German technical universities produce insufficient robotics engineers to support deployment velocity.
- Data sovereignty infrastructure costs:GDPR-mandated local cloud residency requires redundant German data center capacity.
- Optical sensor supply concentration:Precision LiDAR modules depend on single-source Asian component suppliers.
Strategic Opportunities
- Eastern Mittelstand penetration:Saxony and Thuringia manufacturing bases remain underserved by cloud robotics integrators.
- Remanufacturing-as-a-service:Circular economy directives enable robotic disassembly lines for automotive battery recovery.
- 5G private network bundling:Telecommunications operators pair guaranteed-latency connectivity with cloud robotics subscriptions.
Industry Challenges
- ISO 10218 collaborative safety certification:Cloud-connected cobots require extended validation timelines for human-robot interaction protocols.
- brownfield integration complexity:1980s-era Siemens S5 control architectures resist seamless cloud middleware deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Cloud Robotics Market |
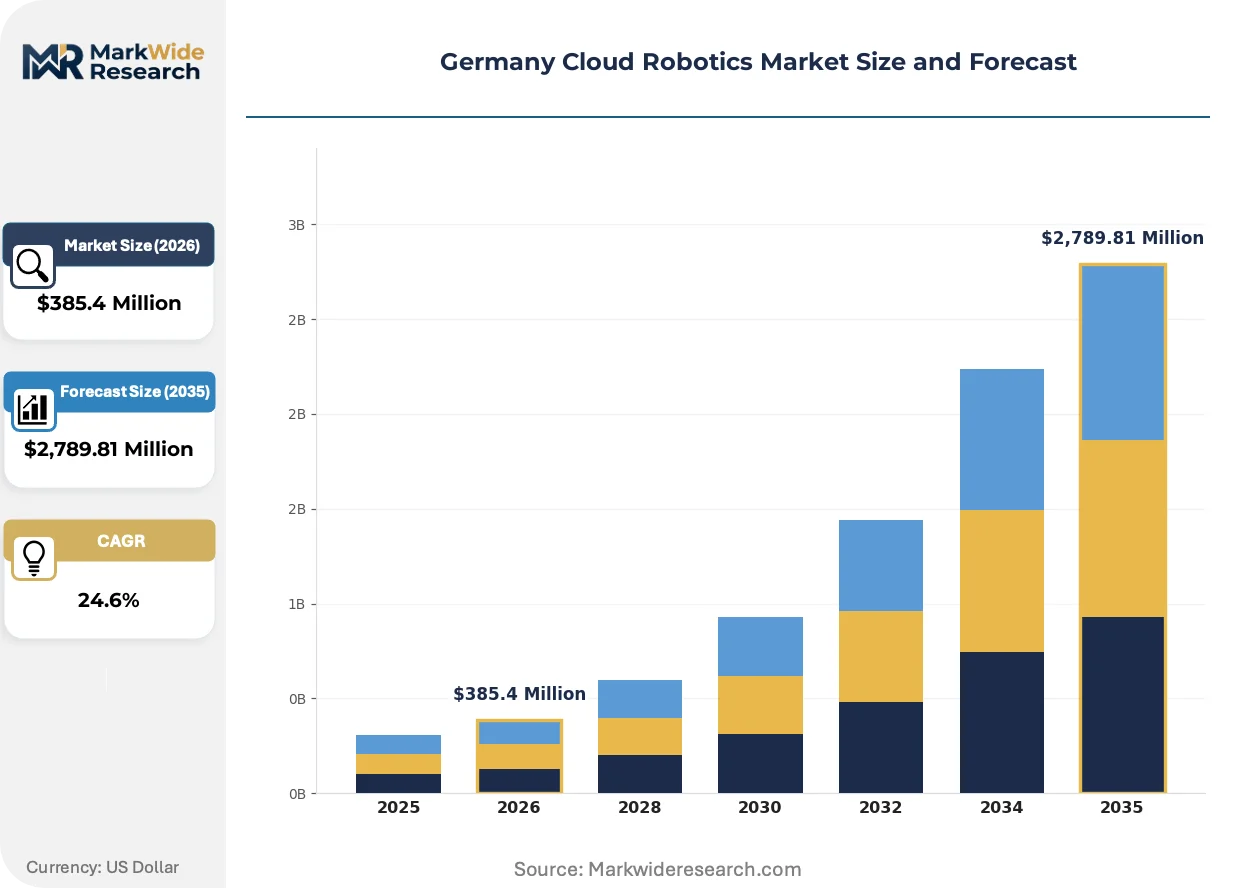
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $2,789.81 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Inter-cloud Technology: AI, Machine Learning, IoT, Edge Computing End User: Manufacturing, Healthcare, Retail, Logistics Application: Warehouse Automation, Remote Monitoring, Predictive Maintenance, Teleoperation |
| Companies Covered | KUKA AG, Siemens AG, ABB Ltd., Bosch Rexroth AG, Fanuc Corporation, Yaskawa Electric Corporation, Universal Robots A/S, Mitsubishi Electric Corporation, Omron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Cloud Robotics Market Trends and Innovations
Distributed intelligence architectures are compressing hardware footprints while expanding software-defined capabilities across German production environments.
Embedded GPU modules for robotic vision processing are miniaturizing from rack-mounted servers to palm-sized edge devices. Stuttgart automotive suppliers deploy these units directly on manipulator arms. This compression eliminates fiber runs to central compute closets.
KBA vehicle-safety protocols now mandate over-the-air update traceability for autonomous mobile robots operating in shared human workspaces. Tier-1 suppliers must maintain immutable algorithm version logs. Bavarian logistics hubs are reconfiguring fleet management software to satisfy audit requirements.
Capital equipment buyers in Rhineland manufacturing clusters now favor subscription-based remote monitoring over perpetual license purchases. System integrators respond with tiered service tiers. This preference shift concentrates purchasing authority within procurement departments rather than engineering functions.
Germany Cloud Robotics Market Segmentation
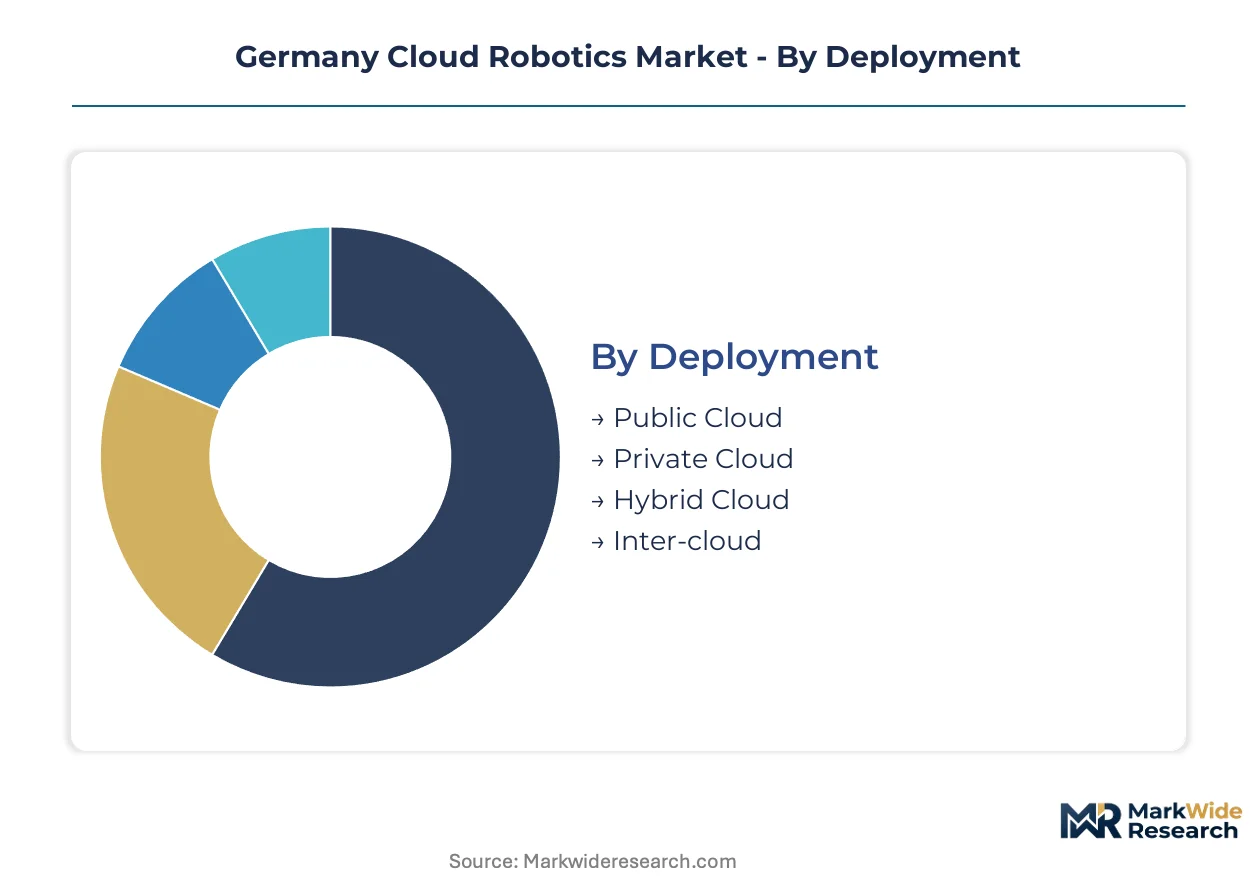
German manufacturers select cloud robotics architectures based on data sovereignty obligations, latency tolerance, and fleet scale. Segmentation reveals divergent cost structures and compliance burdens across deployment modes and technology stacks.
Deployment:
Hybrid Cloud faces the most intense substitution pressure from edge-native architectures as latency requirements tighten in Stuttgart automotive corridors.
- Public Cloud:Offloads compute-intensive machine learning training to hyperscale data centers with elastic provisioning. Mittelstand exporters in Saxony favor this model for non-sensitive simulation workloads where GDPR residency rules permit.
- Private Cloud:Dedicated infrastructure within German data center boundaries satisfies Federal Network Agency data localization mandates. Bavarian automotive suppliers deploy this architecture for proprietary welding trajectory algorithms.
- Hybrid Cloud:Splits real-time motion control at the edge with batch analytics in remote infrastructure. Baden-Württemberg hydraulic press operators leverage this balance for predictive maintenance with sub-50ms response guarantees.
- Inter-cloud:Multi-vendor orchestration across competing hyperscalers reduces vendor lock-in risk. Thuringia logistics hubs adopt this approach for disaster recovery in 5G private network environments.
Hybrid Cloud anchors the volume base while Inter-cloud gains share at the steepest rate.
Technology:
Edge Computing commands the widest cost tier spread, from palm-sized embedded GPUs to rack-mounted factory servers.
- AI:Neural network inference engines execute collision avoidance and quality inspection on cloud-connected manipulators. Rhineland capital equipment suppliers embed these capabilities for remote monitoring subscription tiers.
- Machine Learning:Fleet-wide model updates enable collaborative learning across dispersed robotic assets. KBA traceability protocols now mandate version logging for all algorithm deployments in shared human workspaces.
- IoT:Sensor fusion architectures aggregate vibration, temperature, and optical data streams. Stuttgart automotive tier-1s deploy these networks for real-time production line telemetry.
- Edge Computing:Distributed processing nodes execute latency-critical control loops locally. Embedded GPU modules miniaturizing to manipulator-mounted form factors eliminate fiber runs to central compute closets.
IoT carries the heaviest infrastructure burden while Edge Computing climbs the fastest.
End User:
Manufacturing exhibits the most mature procurement patterns, with engineering departments ceding authority to centralized procurement functions.
- Manufacturing:Automotive production lines in Bavaria and Baden-Württemberg deploy cloud-connected robotic fleets for flexible reconfiguration. EU AI Act risk-classification mandates accelerate replacement of legacy control systems.
- Healthcare:Surgical robotics and rehabilitation systems require immutable audit trails for algorithm updates. German hospital procurement groups prioritize subscription-based remote monitoring over perpetual licenses.
- Retail:Inventory management robots in urban logistics hubs demand seamless cloud middleware integration. Brownfield 1980s-era control architectures resist deployment without extensive retrofit.
- Logistics:Autonomous mobile robots in Bavarian distribution centers navigate shared human workspaces under ISO 10218 collaborative safety protocols. Over-the-air update traceability is now mandatory.
Manufacturing dominates current installations while Logistics shows the steepest expansion trajectory.
Application:
Warehouse Automation carries the deepest installed base, though margin pressure intensifies as remote monitoring services commoditize.
- Warehouse Automation:Fleet-scale coordination of pick-and-place operations across multi-site distribution networks. Eastern Mittelstand manufacturing bases in Saxony and Thuringia remain underserved by integrators.
- Remote Monitoring:Subscription-based telemetry services generate recurring revenue for capital equipment suppliers. Procurement departments now control purchasing authority rather than engineering functions.
- Predictive Maintenance:Vibration-sensing cloud robotics eliminate unplanned downtime in Stuttgart industrial corridors. Hydraulic press operators deploy these systems for condition-based intervention.
- Teleoperation:Human-in-the-loop control for hazardous environments or complex manipulation tasks. Sub-50ms latency thresholds demand 5G private network bundling with guaranteed connectivity.
Warehouse Automation anchors the value pool while Remote Monitoring expands most quickly as service models displace perpetual licenses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cloud robotics consumption concentrates in automotive-heavy southern states, where predictive maintenance and fleet coordination dominate deployment patterns, while eastern manufacturing bases lag in integrator coverage and infrastructure maturity.
Bavaria
Automotive production lines and logistics hubs anchor cloud robotics demand, with Munich-based system integrators deploying hybrid cloud architectures for flexible reconfiguration. State government subsidies through Industry 4.0 certification programs accelerate compliance-driven upgrades. Bavarian distribution centers deploy autonomous mobile robots under KBA-mandated over-the-air update traceability protocols.
Baden-Württemberg
Stuttgart industrial corridors prioritize vibration-sensing predictive maintenance on hydraulic press equipment, eliminating unplanned downtime through sub-50ms edge-to-cloud response loops. EU AI Act risk-classification mandates force immediate replacement of legacy robotic control systems in tier-1 automotive supplier facilities. Embedded GPU modules miniaturize to manipulator-mounted form factors, eliminating fiber runs.
North Rhine-Westphalia
Rhineland capital equipment buyers favor subscription-based remote monitoring services over perpetual licenses, shifting procurement authority to centralized purchasing departments. The state's dense chemical and machinery manufacturing base generates demand for hazardous environment teleoperation with 5G private network bundling. GDPR-mandated data residency requirements drive private cloud infrastructure investment.
Saxony
Eastern Mittelstand manufacturing bases remain underserved by cloud robotics integrators despite expanding export-oriented production capacity. State development agencies subsidize public cloud deployment for non-sensitive simulation workloads where GDPR rules permit. Dresden-area semiconductor fabrication plants deploy cloud-connected robotic systems for cleanroom material handling.
Thuringia
Logistics hubs adopt inter-cloud orchestration across competing hyperscalers for disaster recovery in 5G private network environments. The state's automotive supplier corridor lags Bavaria and Baden-Württemberg in fleet-scale deployment velocity. Erfurt-area integrators target brownfield retrofit programs for 1980s-era control architectures resistant to seamless cloud middleware deployment.
Germany Cloud Robotics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Germany's cloud robotics market, with tier-1 automotive suppliers and Mittelstand manufacturers driving consolidation around proven system integrators. The upper tier combines industrial automation heritage with cloud platform capabilities, while mid-tier specialists compete on sector-specific application depth. Three archetypes dominate: full-stack platform providers, edge-to-cloud middleware specialists, and component-focused sensor-robotics integrators. Competitive intensity centers on strategic partnerships with telecommunications operators for 5G private network bundling, plus vertical integration into predictive maintenance software stacks.
Among Germany-based industrial automation leaders, KUKA AG and Siemens AG exemplify the full-stack platform archetype, with KUKA leveraging its Augsburg headquarters for deep automotive production line integration and Siemens anchoring edge-to-cloud architectures through its Munich-based digital industries division. Bosch Rexroth AG occupies a position within the hydraulic-to-cloud convergence specialist tier, competing on smart factory retrofit programs. These three AG-structured entities represent distinct strategic postures: KUKA emphasizes fleet-scale software deployment, Siemens prioritizes hybrid infrastructure orchestration, and Bosch Rexroth targets legacy equipment modernization.
| Leading Market Players |
|---|
| KUKA AG |
| Siemens AG |
| ABB Ltd. |
| Bosch Rexroth AG |
| Fanuc Corporation |
| Yaskawa Electric Corporation |
| Universal Robots A/S |
| Mitsubishi Electric Corporation |
| Omron Corporation |
| Others |
Pricing and Supply Chain Analysis
Edge-native processing modules are displacing centralized compute architectures across German automotive production lines, compressing hardware procurement costs while fragmenting supplier geography toward Asian semiconductor foundries and European system integrators. This substitution simultaneously erodes pricing power for legacy rack-mounted server vendors and inflates premiums for palm-sized embedded GPU units that eliminate fiber infrastructure.
Pricing Analysis
Long-term offtake contracts dominate procurement for cloud robotics subscriptions, with Bavarian automotive suppliers locking in multi-year fleet management agreements to hedge against component volatility. Pricing stratifies across ISO 10218 certification tiers, with collaborative safety validation adding substantial premiums to base hardware costs. Cost compression in remote monitoring services is intensifying because capital equipment buyers now favor recurring revenue models over perpetual licenses, squeezing integrator margins. Mittelstand exporters in Saxony exhibit highest price sensitivity, while tier-1 automotive suppliers absorb premium pricing for guaranteed sub-50ms latency thresholds.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Stuttgart hydraulic press operators, though strategic stockpiling of precision LiDAR modules is emerging as single-source Asian dependencies harden. Component sourcing draws from Taiwan for embedded GPU silicon, South Korea for advanced memory modules, and Germany for mechanical subsystems. Single-source vulnerability concentrates in optical sensor supply, where German manufacturers depend on concentrated Asian component flows. Distribution runs through Munich-based system integrators for Bavarian automotive corridors, with direct OEM relationships dominating tier-1 supplier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-native robotics architectures threaten to commoditize cloud connectivity layers, forcing incumbents to defend value capture in hardware-software integration rather than pure infrastructure provision.
For Market Incumbents: Compound defensive moats through backward integration into predictive maintenance software stacks and captive production of embedded GPU modules for manipulator-mounted deployment. EU AI Act compliance investments create certification barriers that delay challenger entry timelines. Prioritize 5G private network bundling partnerships with telecommunications operators to lock in connectivity-layer control. For New Entrants and Emerging Players: Brownfield retrofit expertise for 1980s-era Siemens S5 control architectures represents a service-layer gap where incumbents under-serve Thuringia manufacturing bases. Target eastern Mittelstand penetration in Saxony and Thuringia through subscription-based remote monitoring offerings that bypass capital expenditure approval cycles. Lead with teleoperation capabilities for hazardous environment applications in North Rhine-Westphalia chemical corridors. For Investors and Strategic Acquirers: The market sits at a compliance-driven upgrade phase that favors system integrators with established KBA traceability protocols and ISO 10218 certification pipelines. Long-term viability hinges on capturing recurring service revenue rather than transactional hardware margins. Watch for inflection signals in 5G private network deployment velocity across Bavarian logistics hubs as fleet-scale coordination demand materializes.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Architecture Deployment | Baden-Württemberg hydraulic press operators achieve sub-50ms predictive maintenance response loops. |
| ISO 10218 Collaborative Safety Certification | Bavarian logistics hubs satisfy KBA-mandated over-the-air update traceability for autonomous mobile robots. |
| 5G Private Network Partnership | Telecommunications operators bundle guaranteed-latency connectivity with cloud robotics subscriptions in Rhineland manufacturing clusters. |
| Predictive Maintenance Software Stack Integration | Stuttgart automotive tier-1s eliminate unplanned downtime through vibration-sensing cloud robotics deployment. |
| Eastern Mittelstand Geographic Expansion | Saxony and Thuringia manufacturing bases remain underserved by cloud robotics integrators despite export growth. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at Bavarian automotive facilities, procurement leads at Mittelstand exporters, system integrators deploying edge-to-cloud architectures, and telecommunications operators bundling 5G private networks. Secondary validation drew from KBA vehicle-safety protocol filings, EU AI Act implementation guidance, Federal Network Agency data localization rulings, and ISO 10218 collaborative robot standards. Bottom-up installation counts and top-down industrial automation spending estimates were triangulated to anchor market sizing.
Across the analysis window, forecasts model deployment mode segmentation across public, private, hybrid, and inter-cloud architectures, technology layers spanning AI, machine learning, IoT, and edge computing, and end-user verticals including manufacturing, healthcare, retail, and logistics. CAGRs derive from regression analysis against industrial capital expenditure cycles and regulatory compliance upgrade timelines. Industry-specific inputs include EU AI Act risk-classification implementation schedules and Industry 4.0 certification program subsidy flows through Baden-Württemberg and Bavaria state governments.
Underlying assumptions cover sustained mechatronics talent scarcity, continued GDPR-mandated data residency requirements, and stable optical sensor supply flows from Asian component suppliers, with deviation risk concentrated in tariff exposure for embedded GPU modules and regulatory acceleration of algorithmic transparency mandates. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and 5G private network deployment velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
Cleanroom Robots in Healthcare Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Global Exoskeleton Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Global Robot Software Market