
 Thailand Cloud Robotics Market | 2026-2036
Thailand Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Cloud Robotics Market Insights
Enterprise-grade cloud robotics specifications are reorganizing competitive priorities across Thailand's industrial automation sector. NVIDIA leverages GPU-accelerated edge computing to anchor high-performance robotic workloads in Thai manufacturing facilities. IBM sustains hybrid cloud architectures that extend AI inference capabilities to distributed robot fleets. ABB dominates precision motion control integrations that differentiate its offerings in automotive assembly applications.
Cloud robotics denotes autonomous or semi-autonomous machines that offload computational tasks, sensor fusion, and AI model execution to remote cloud infrastructure via low-latency connectivity, typically requiring sub-50ms response times for real-time coordination. The architecture enables centralized fleet learning, predictive maintenance algorithms, and dynamic task reallocation across geographically dispersed robot deployments. Manufacturing Automation leads application adoption due to established industrial infrastructure and measurable throughput gains, while Healthcare represents the fastest-expanding segment as Thai hospitals deploy cloud-connected surgical assistants and patient monitoring systems. AI-Based Robots command the technology tier with the deepest margin pools, though IoT Integration grows fastest as factory digitization mandates proliferate across Thai industrial estates.
Thailand's National Digital Economy and Society Plan shapes cloud robotics deployment through data sovereignty requirements and cross-border data flow restrictions that affect multinational platform architectures. The National Broadcasting and Telecommunications Commission governs 5G spectrum allocation critical to ultra-reliable low-latency communication for real-time robot control. Stakeholders must monitor evolving spectrum policy and local data residency mandates to determine cloud architecture investments.
Market Dynamics
The convergence of 5G network rollout with Thailand's Eastern Economic Corridor industrial clustering is compressing deployment timelines for cloud-connected automation systems across Thai manufacturing estates.
Growth Catalysts
- National Digital Economy and Society Plan:Thailand's flagship policy framework mandates data infrastructure investment that directly enables industrial cloud robotics deployment in priority manufacturing zones.
- 5G spectrum allocation:The National Broadcasting and Telecommunications Commission's spectrum policies deliver ultra-reliable low-latency communication essential for real-time robotic control.
- Automotive assembly demand:Thai automotive manufacturers require cloud-connected precision motion systems to maintain throughput in high-mix production environments.
Market Restraints
- Data sovereignty requirements:Cross-border data flow restrictions under Thailand's digital economy framework complicate multinational cloud platform architectures.
- Edge computing hardware costs:GPU-accelerated processing units for robotic workloads carry premium pricing that constrains mid-tier manufacturer adoption.
- Specialized systems integration talent:Scarcity of engineers combining robotics, cloud architecture, and industrial networking expertise limits deployment velocity.
Strategic Opportunities
- Healthcare robotics expansion:Thai hospitals present underpenetrated demand for cloud-connected surgical assistance and patient monitoring systems.
- IoT integration mandates:Factory digitization requirements across Thai industrial estates create pull for sensor-fusion robotics with centralized fleet management.
- Hybrid cloud architectures:Convergence of on-premise edge processing with centralized AI training infrastructure opens margin-rich deployment models for system integrators.
Industry Challenges
- Legacy equipment interoperability:Integration friction between cloud robotics platforms and existing programmable logic controller infrastructure extends deployment cycles.
- Sub-50ms latency certification:Network performance validation for real-time robot coordination lacks standardized testing protocols, complicating procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Cloud Robotics Market |
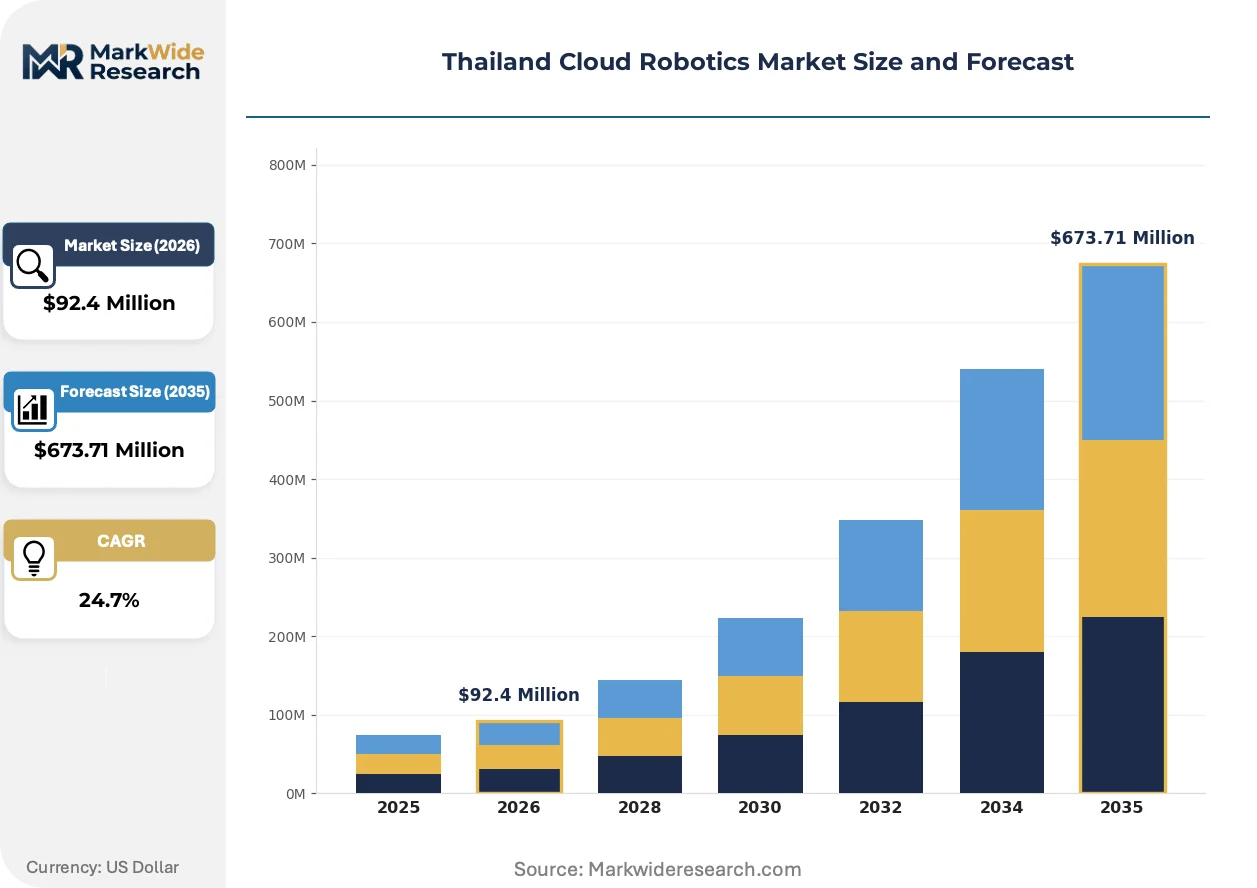
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $673.71 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing Automation, Healthcare, Logistics, Retail Technology: AI-Based Robots, IoT Integration, Machine Learning, Computer Vision End User: Manufacturers, Hospitals, Warehouses, Service Providers Service Type: Maintenance Services, Installation, Software Support, Consulting |
| Companies Covered | IBM, NVIDIA, CloudMinds, Brain Corp, H2O.ai, ABB, FANUC, Teradyne, Inc., Clearpath Robotics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Cloud Robotics Market Trends and Innovations
Thailand's cloud robotics sector is experiencing accelerated architectural evolution as connectivity infrastructure, computational offloading patterns, and buyer procurement preferences simultaneously transform.
Edge-cloud workload orchestration is bifurcating deployment models across Thai manufacturing facilities. GPU-accelerated local processing handles real-time motion control while centralized cloud infrastructure manages fleet learning and predictive maintenance algorithms. Automotive assemblers in the Eastern Economic Corridor adopt this split architecture fastest, compressing the market into high-performance integrated systems versus modular connectivity platforms.
Thailand's National Broadcasting and Telecommunications Commission governs 5G spectrum allocation that determines ultra-reliable low-latency communication availability for industrial robotics. The regulatory framework shapes where real-time cloud control becomes technically viable, privileging Bangkok metropolitan and Eastern Economic Corridor zones with prioritized infrastructure deployment. Manufacturing automation vendors calibrate product roadmaps to these geographic coverage maps.
Hospital procurement committees now specify cloud connectivity requirements in surgical robot tenders, unbundling hardware acquisition from ongoing AI model update subscriptions. This purchasing pattern shift compresses vendor selection cycles while elevating software architecture capabilities in competitive evaluations. Bangkok's tertiary medical centers drive this specification evolution, with procurement templates diffusing to provincial hospital networks.
Thailand Cloud Robotics Market Segmentation
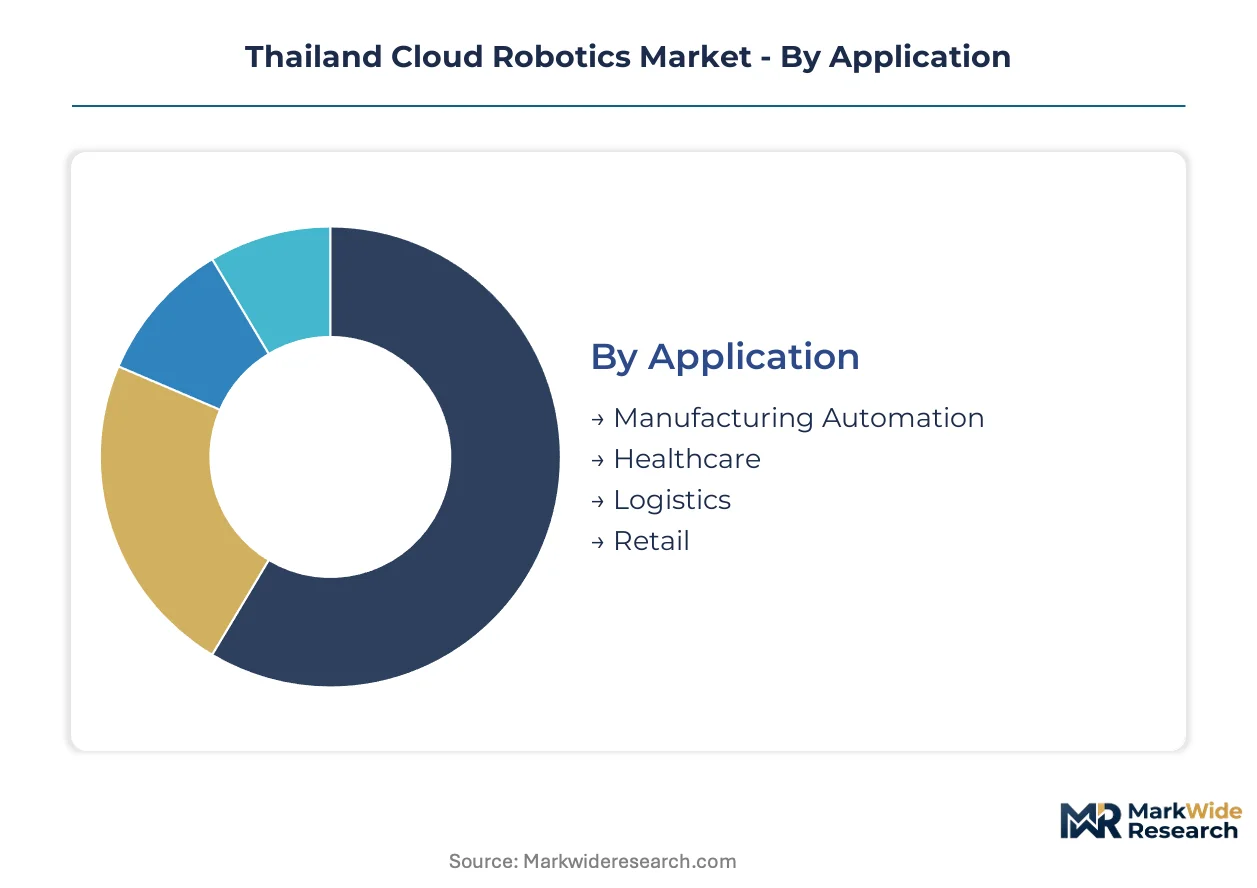
Thailand's cloud robotics market fragments across application domains, technology stacks, and service delivery models that channel procurement decisions through distinct buyer committees. Each segment carries unique latency requirements, integration complexity, and recurring revenue potential that shapes vendor positioning strategies.
Application:
Channel mix varies sharply by application: Manufacturing Automation flows through systems integrators and OEM direct sales, while Healthcare routes through medical device distributors with regulatory compliance layers.
- Manufacturing Automation:Cloud-connected robotic arms and automated guided vehicles dominate deployment volumes in Thai automotive and electronics assembly plants. Eastern Economic Corridor manufacturers prioritize real-time production optimization with sub-50ms latency requirements. Bangkok-based integrators capture the bulk of deployment contracts through established PLC integration expertise.
- Healthcare:Surgical assistance robots and patient monitoring systems require medical-grade connectivity certifications that filter vendor pools. Thai tertiary hospitals in Bangkok and Chiang Mai drive specification evolution toward subscription-based AI model updates. Procurement committees now unbundle hardware from ongoing software services.
- Logistics:Warehouse automation demand concentrates in e-commerce fulfillment centers around Bangkok and Laem Chabang port zones.
- Retail:Customer-facing service robots and inventory management systems see pilot deployments in Bangkok metropolitan shopping complexes.
By volume, Manufacturing Automation leads. By growth pace, Healthcare is ahead.
Technology:
Technology tier selection correlates with buyer sophistication and margin depth, with AI-Based Robots commanding premium pricing while IoT Integration spreads across mid-market manufacturers.
- AI-Based Robots:Autonomous systems executing sensor fusion, path planning, and adaptive manipulation through cloud-offloaded neural network inference. Thai automotive assemblers deploy these for high-mix production environments where task variability exceeds pre-programmed motion limits. GPU-accelerated edge nodes handle real-time control while centralized cloud infrastructure manages fleet learning.
- IoT Integration:Sensor-networked robotics with centralized telemetry and predictive maintenance algorithms. Factory digitization mandates across Thai industrial estates accelerate adoption among mid-tier manufacturers seeking measurable throughput gains without full AI autonomy investments.
- Machine Learning:Pattern recognition and optimization algorithms deployed for quality inspection and process tuning applications.
- Computer Vision:Visual guidance systems for pick-and-place, defect detection, and safety monitoring in manufacturing environments.
By installed base, IoT Integration leads. By margin expansion, AI-Based Robots is ahead.
End User:
End user type determines procurement cycle length and stakeholder complexity, with Manufacturers running 12-18 month evaluation periods versus Hospitals requiring 24-36 month regulatory pathways.
- Manufacturers:Thai automotive and electronics producers with established automation infrastructure seeking cloud connectivity upgrades for fleet coordination. Eastern Economic Corridor zones concentrate demand due to National Digital Economy and Society Plan infrastructure prioritization. These buyers prioritize interoperability with existing programmable logic controller networks.
- Hospitals:Public and private healthcare facilities deploying surgical assistance and patient monitoring systems. Bangkok's tertiary medical centers set procurement templates that diffuse to provincial networks. Medical device licensing through Thailand's national pharmaceutical regulator shapes vendor qualification timelines.
- Warehouses:Third-party logistics operators and e-commerce fulfillment centers seeking automated material handling.
- Service Providers:Robotics-as-a-service operators offering cloud-connected automation on subscription models to capital-constrained SMEs.
By contract value, Manufacturers lead. By deal velocity, Service Providers is ahead.
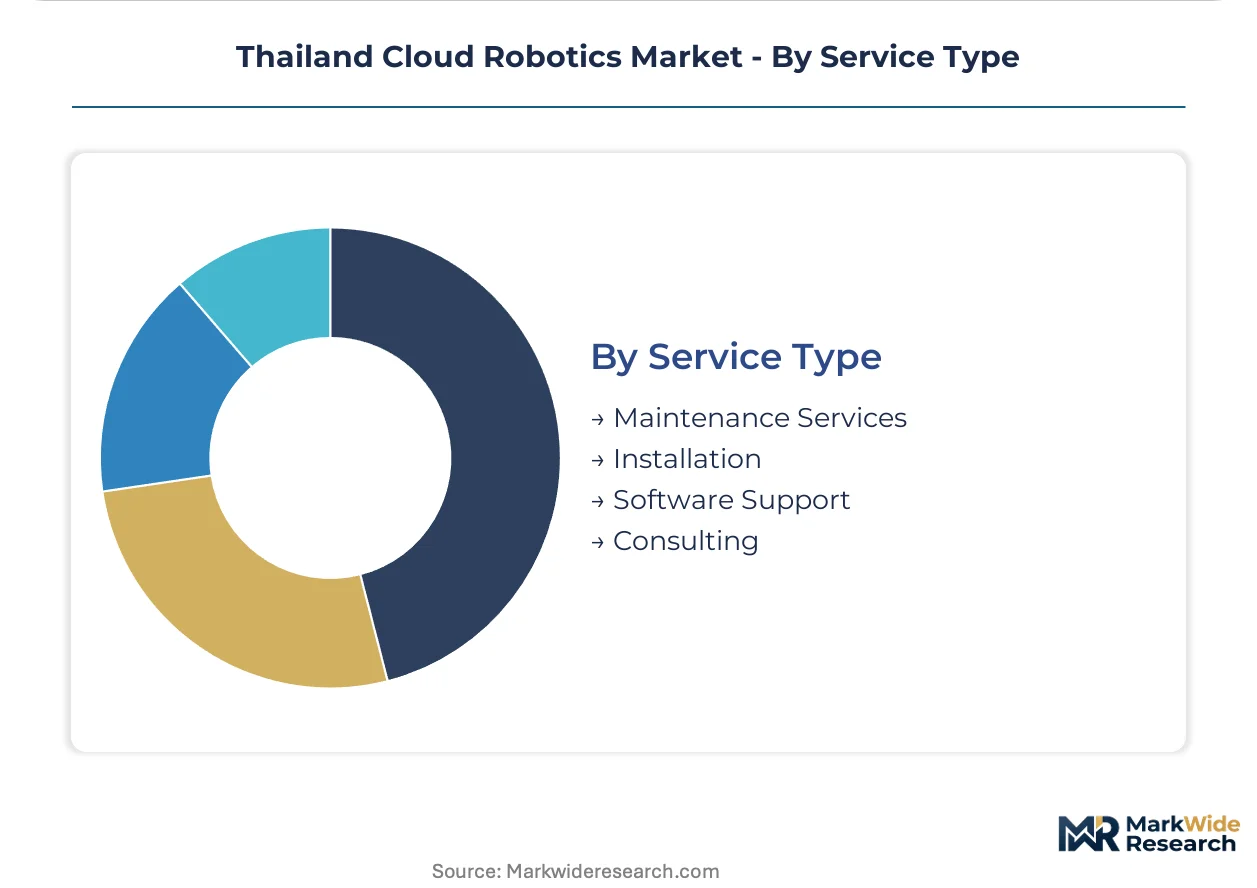
Service Type:
Service mix evolution reflects buyer preference shifts from capital expenditure toward operational expenditure models, with Software Support and Maintenance Services capturing expanding recurring revenue shares.
- Maintenance Services:Predictive maintenance algorithms leveraging cloud-stored operational data to preempt component failures and schedule interventions. Thai manufacturers with 24/7 production schedules prioritize uptime guarantees and spare parts availability commitments. Service level agreements specify maximum response times for critical subsystem failures.
- Software Support:Ongoing AI model updates, security patches, and feature releases delivered through cloud infrastructure. Hospital procurement committees increasingly specify minimum update frequency and data residency compliance in tender documents. This service tier carries the highest gross margins for platform vendors.
- Installation:Physical deployment, calibration, and initial integration with existing facility infrastructure.
- Consulting:Workflow analysis, ROI modeling, and cloud architecture design services preceding deployment decisions.
By revenue stability, Software Support leads. By expansion rate, Maintenance Services is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud robotics infrastructure investment concentrates in manufacturing corridors with prioritized 5G spectrum allocation and data center buildouts. Thailand's Eastern Economic Corridor anchors regional deployment velocity through concentrated automotive and electronics assembly demand. The National Digital Economy and Society Plan shapes cross-border data governance that affects platform architecture decisions throughout mainland Southeast Asia.
Thailand
Bangkok metropolitan manufacturers deploy cloud-connected robotic arms for real-time production optimization in high-mix automotive assembly. The National Broadcasting and Telecommunications Commission governs 5G spectrum allocation critical to ultra-reliable low-latency communication for robot control. Eastern Economic Corridor zones from Chonburi to Rayong concentrate demand where Thai assemblers integrate precision motion systems with centralized fleet learning infrastructure.
Vietnam
Northern industrial provinces around Hai Phong and Bac Ninh drive cloud robotics adoption for electronics contract manufacturing and smartphone assembly lines. The Ministry of Information and Communications regulates data localization requirements affecting multinational cloud platform deployments. Samsung and Apple supplier ecosystems in the Red River Delta prioritize IoT-integrated automation with predictive maintenance algorithms.
Singapore
Advanced manufacturing and precision engineering sectors anchor demand for AI-based robots with GPU-accelerated edge computing nodes. The Infocomm Media Development Authority oversees 5G standalone network rollout enabling sub-50ms latency for surgical robotics and semiconductor handling applications. Jurong Innovation District and Punggol Digital District cluster deployment of cloud-connected automation for pharmaceutical and aerospace component production.
Malaysia
Penang and Selangor electronics manufacturers adopt cloud robotics for back-end semiconductor processing and consumer electronics assembly. The Malaysian Communications and Multimedia Commission manages spectrum policy affecting industrial IoT connectivity for robotic fleet coordination. Iskandar Malaysia and Kulim High-Tech Park concentrate demand where medical device and automotive parts producers integrate sensor-fusion robotics with centralized telemetry.
Indonesia
Batam and Bintan special economic zones attract cloud robotics deployment for electronics manufacturing serving regional supply chains. The Ministry of Communication and Informatics governs data sovereignty frameworks affecting cross-border cloud platform architectures. Cikarang and Karawang industrial estates in West Java pilot warehouse automation and logistics robotics with subscription-based fleet management services.
Thailand Cloud Robotics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Thailand's cloud robotics sector. GPU-accelerated edge computing specialists command premium positioning in high-performance manufacturing applications while IoT connectivity platform vendors capture mid-market volume through standardized sensor integration. The competitive structure organizes around three archetypes: industrial automation incumbents with precision motion heritage, cloud infrastructure providers with AI inference capabilities, and robotics-native specialists with fleet learning expertise. Dominant competitive moves include strategic partnerships between hardware OEMs and cloud hyperscalers, plus geographic expansion through systems integrator channel relationships in prioritized manufacturing zones.
Within the industrial automation tier, ABB and FANUC represent established precision motion control providers with deep PLC integration expertise. NVIDIA occupies a position as the GPU-accelerated edge computing anchor for AI inference workloads in Thai manufacturing facilities. IBM exemplifies hybrid cloud architecture providers extending centralized fleet management to distributed robot deployments across Bangkok and Eastern Economic Corridor zones.
| Leading Market Players |
|---|
| IBM |
| NVIDIA |
| CloudMinds |
| Brain Corp |
| H2O.ai |
| ABB |
| FANUC |
| Teradyne, Inc. |
| Clearpath Robotics |
| Others |
Pricing and Supply Chain Analysis
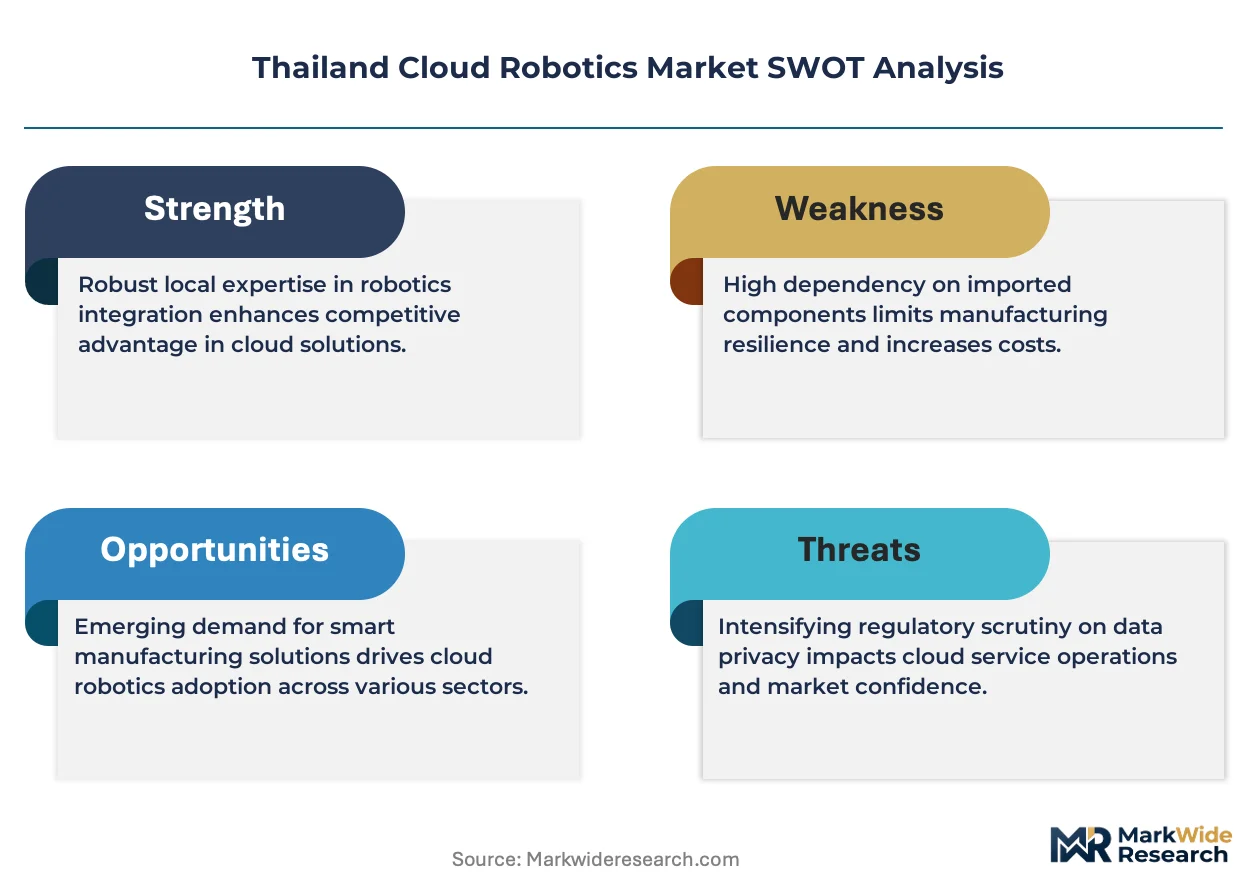
Thailand's National Digital Economy and Society Plan gates both vendor qualification and price differentiation in cloud robotics procurement, as data residency mandates and cross-border flow restrictions filter platform architectures while segmenting buyers into compliance-tolerant premium tiers versus cost-optimized domestic-only deployments.
Pricing Analysis
The National Broadcasting and Telecommunications Commission's 5G spectrum allocation dictates the pricing tier structure across Thai cloud robotics deployments. Three-tier pricing structure across premium, standard, and economy levels separates automotive assemblers requiring sub-50ms latency guarantees from mid-tier manufacturers accepting best-effort connectivity and provincial hospitals with basic telemetry needs. Cost compression in the economy tier is intensifying because domestic systems integrators crowd the mid-market with standardized IoT integration packages. Provincial manufacturers exhibit highest price sensitivity, while Bangkok's tertiary hospitals prioritize medical-grade certification over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites component flows for Thai cloud robotics assembly, with GPU-accelerated edge processors sourced from Taiwan and South Korea and precision motion control hardware anchored in Japan and Germany. Local supply draws from Singaporean data center infrastructure and Chinese sensor manufacturing clusters. Single-source vulnerability concentrates in NVIDIA's GPU allocation for AI inference workloads. Distribution runs through Bangkok-based systems integrators with Eastern Economic Corridor field engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's cloud robotics sector sits at a platform-economics inflection where interoperability standards and fleet-learning network effects are displacing standalone hardware margins, with the unbundling of surgical robot hardware from AI subscription services in Bangkok hospitals signaling ecosystem restructuring.
For Market Incumbents: Shield installed base relationships through predictive maintenance service contracts that embed GPU-accelerated edge nodes on customer premises, creating switching costs against modular connectivity platforms. Deepen backward integration into Thai systems integrator channels to control Eastern Economic Corridor deployment velocity. Prioritize certification investment for medical-grade connectivity to defend against cloud-native entrants targeting hospital procurement committees. For New Entrants and Emerging Players: Anchor in provincial hospital networks outside Bangkok where regulatory pathways remain underdeveloped and incumbent service coverage thins. Target warehouse automation around Laem Chabang port zones where e-commerce fulfillment demand outpaces integrator capacity. Pursue robotics-as-a-service subscription models to bypass capital expenditure barriers among Thai SME manufacturers. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation divisions of diversified Thai conglomerates seeking to monetize non-core robotics assets amid digital transformation mandates. Long-term viability hinges on fleet data network effects rather than hardware shipment volumes. Monitor National Broadcasting and Telecommunications Commission spectrum auction timing as inflection indicator for real-time control application viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Architecture Deployment | Converges on-premise edge processing with centralized AI training for Thai automotive assemblers. |
| 5G Spectrum Partnership | Secures ultra-reliable low-latency communication allocation from National Broadcasting and Telecommunications Commission. |
| Healthcare Regulatory Certification | Unlocks Thai tertiary hospital procurement through medical-grade connectivity validation. |
| Systems Integrator Acquisition | Captures Eastern Economic Corridor deployment channels with established PLC integration expertise. |
| IoT Platform Standardization | Enables fleet management scale across mid-tier Thai manufacturers with sensor-fusion robotics. |
Research Methodology
A standing panel of robotics systems integrators, hospital procurement committee members, automotive plant engineers, and National Broadcasting and Telecommunications Commission policy specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from Thai industrial estate authority filings, Eastern Economic Corridor infrastructure investment disclosures, 5G spectrum allocation records, and cloud hyperscaler regional capex announcements. Bottom-up deployment tallies across manufacturing facilities and top-down infrastructure spend estimates were triangulated to anchor market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across application domains, technology tiers, end-user types, and service delivery models, with additional dimensioning by latency requirement bands and data residency compliance levels. CAGRs were derived from fitted growth curves incorporating 5G coverage expansion timelines and industrial automation investment cycles specific to Thai automotive and electronics assembly.
Underlying assumptions cover National Digital Economy and Society Plan enforcement continuity and Eastern Economic Corridor infrastructure buildout schedules, with deviation risk concentrated in spectrum allocation delays and cross-border data flow regulatory evolution. Practitioners should keep alternative scenarios live as Thailand's digital sovereignty framework and regional 5G rollout pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Global Soldering Robot Market
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Eldercare-Assistive Robots Market