
 Snake Robots Market | 2026-2036
Snake Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Snake Robots Market Intelligence
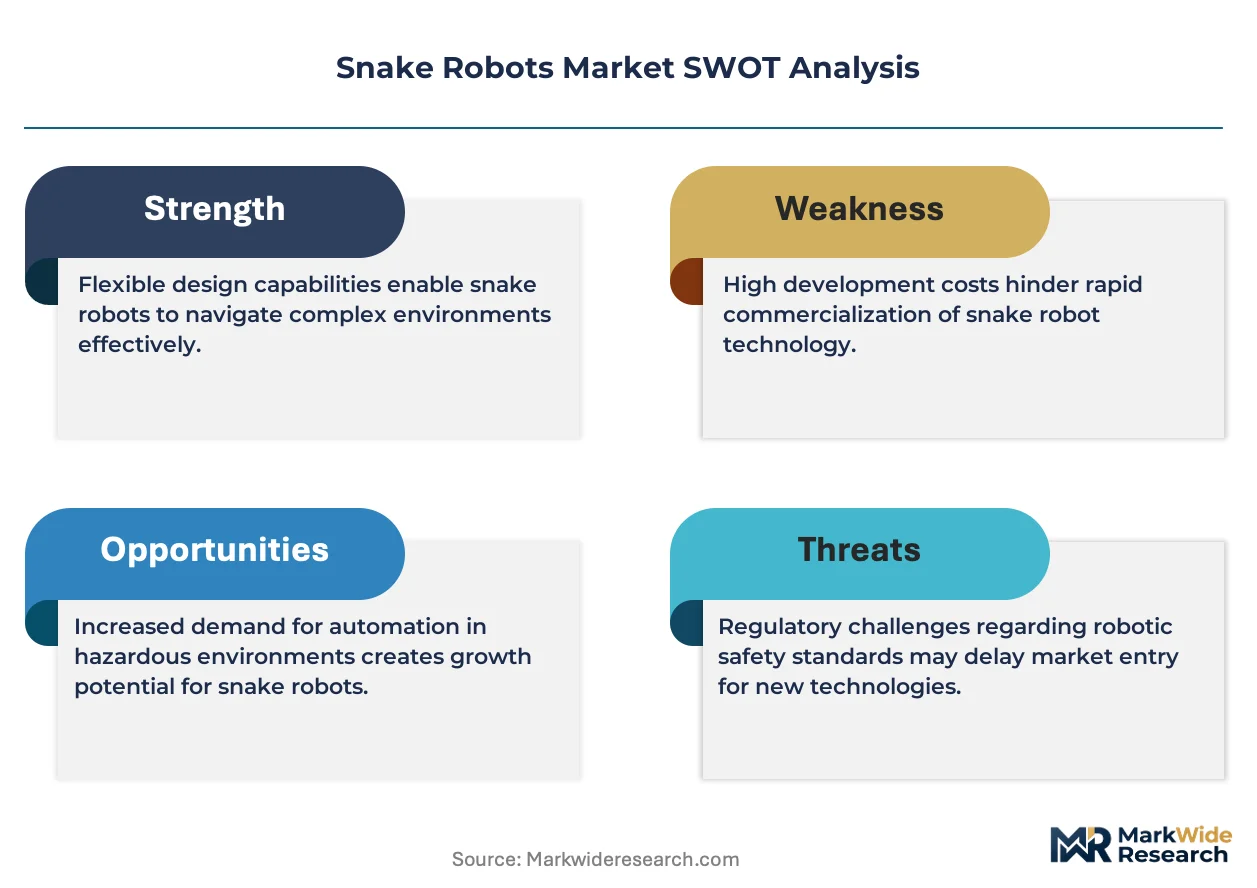
Japan is tilting toward snake robot manufacturing scale-up through METI-backed robotics clusters in Osaka and Tsukuba. OC Robotics leverages its heritage in confined-space manipulation to sustain defense and nuclear decommissioning contracts across the UK. Eelume AS anchors subsea inspection with its underwater snake robot platforms for energy clients in the North Sea. Sarcos Technology and Robotics Corporation competes on dexterous teleoperation, positioning its systems for hazardous material handling in US industrial facilities.
Snake robots are hyper-redundant articulated mechanisms with serially linked joints enabling omnidirectional bending in constrained environments; typical configurations achieve 16–32 degrees of freedom through tendon-driven or direct-drive actuation for navigation through pipes, collapsed structures, and anatomical cavities. Pipe inspection applications dominate current deployment volumes due to aging utility infrastructure in OECD economies, while soft robotics technology captures expanding margin pools through compliant material interfaces that reduce damage risk in medical procedures and fragile environment access. Modular design architectures lead R&D investment intensity as they enable field-reconfigurable joint segments that adapt payload and length to mission-specific constraints.
FDA 510(k) pathways and the EU MDR govern medical snake robot commercialization, with FDA emphasizing biocompatibility and electromechanical safety for surgical snake platforms while MDR demands clinical evidence for active implantable adjacent systems. Japan's PMDA aligns with METI robotics roadmaps to accelerate regulatory review for disaster-response snake robots. ISO 13482 service robot safety standards and IEC 60601 medical electrical equipment norms shape baseline design requirements across jurisdictions. Stakeholders must monitor how autonomous control certifications evolve under divergent national AI governance frameworks to anticipate market access timelines.
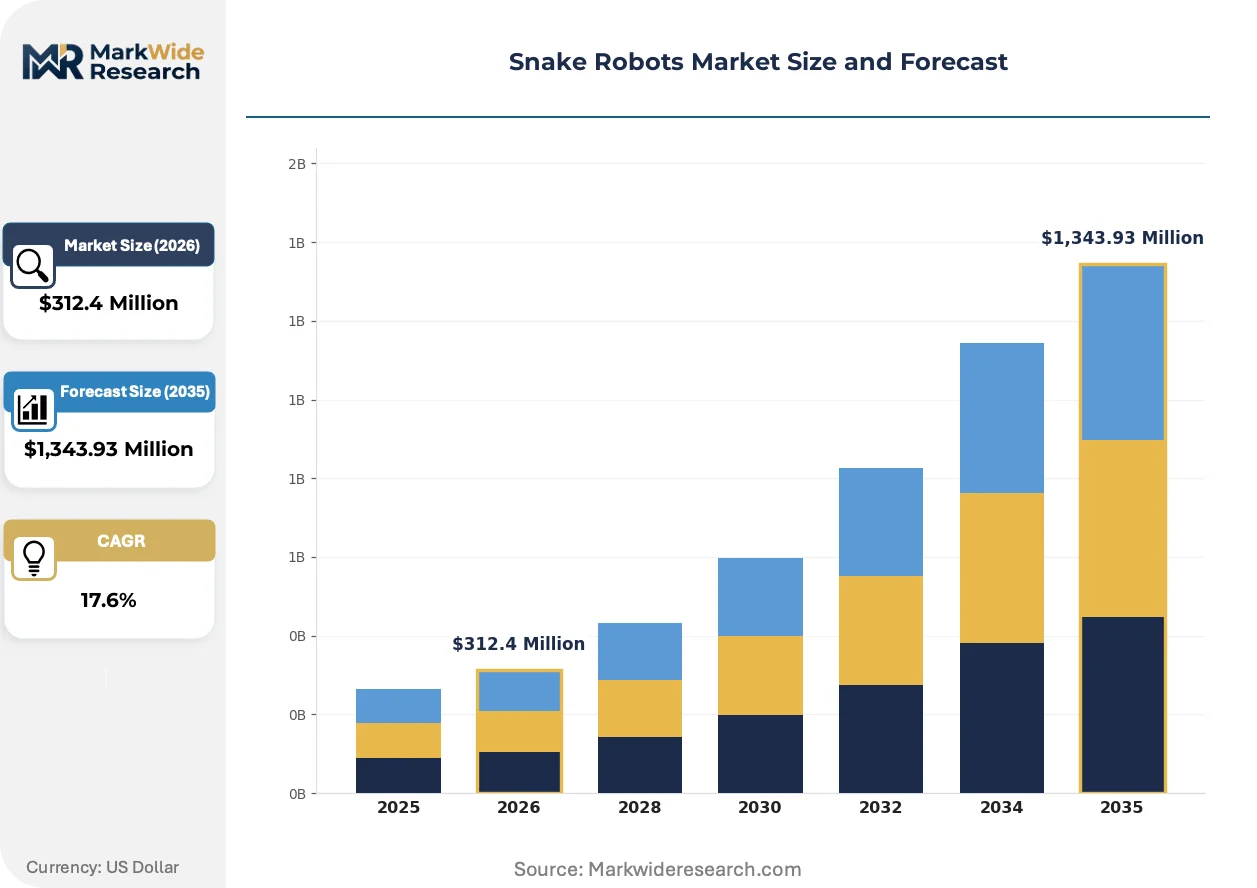
Market Dynamics
Hyper-redundant actuation architectures are compressing development cycles while METI-funded procurement clusters in Japan concentrate demand-pull for disaster-response platforms ahead of regulatory harmonization elsewhere.
Growth Catalysts
- EU MDR certification pathways:Streamlined clinical evidence requirements for active implantable adjacent systems accelerate commercial timelines for surgical snake platforms in European healthcare systems.
- Tendon-driven miniaturization:Advances in cable-actuated joint mechanisms enable 16-32 degree-of-freedom configurations that penetrate collapsed structures and anatomical cavities previously unreachable by rigid robotics.
- Japan METI disaster robotics funding:Domestic procurement intensification through Osaka and Tsukuba robotics clusters creates concentrated demand for search-and-rescue snake robot deployment.
Market Restraints
- High-performance servo motor cost volatility:Rare-earth magnet supply concentration in processing facilities creates input price instability for precision actuation subsystems.
- Biocompatibility certification friction:FDA 510(k) electromechanical safety reviews impose extended timelines for surgical snake platforms seeking US market entry.
- Soft silicone elastomer substitution risk:Compliant pneumatic continuum robots from adjacent medical robotics segments threaten snake robot positioning in minimally invasive procedures.
Strategic Opportunities
- Subsea energy infrastructure inspection:North Sea offshore wind expansion and aging oil platform decommissioning create unmet demand for pressure-rated underwater snake robot systems.
- Modular field-reconfigurable architectures:Hot-swappable joint segments enable payload and length adaptation without manufacturer intervention, opening rental and lease distribution channels.
- ISO 13482 service robot safety alignment:Proactive design-to-standard approaches reduce certification duplication across Japan, the US, and EU jurisdictions.
Industry Challenges
- Hyper-redundant kinematics expertise scarcity:Inverse Jacobian computation and real-time path planning for 20+ degree-of-freedom systems require specialized robotics software engineers in short supply.
- Legacy industrial facility integration complexity:Snake robot deployment in established nuclear decommissioning and hazardous material handling sites demands custom API development for proprietary control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snake Robots Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,343.93 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Search & Rescue, Medical Procedures, Underwater Exploration, Pipe Inspection Technology: Modular Design, Soft Robotics, Autonomous Control, Remote Operated End User: Healthcare Providers, Energy Companies, Research Institutions, Government Agencies Size: Miniature, Small, Medium, Large |
| Companies Covered | OC Robotics, Eelume AS, HiBot Corp., Applied Robotics Technologies LLC, Sintef, Sarcos Technology and Robotics Corporation, Medrobotics, Hirose Fukushima Laboratory, Oliver Crispin Robotics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snake Robots Market Strategic Shifts & Innovations
Soft robotics material interfaces are actively displacing traditional rigid-link architectures in medical and fragile-environment applications, while regulatory divergence between FDA, EU MDR, and PMDA frameworks forces parallel certification strategies.
Tendon-sheath transmission systems are collapsing the cost-performance tradeoff for hyper-redundant manipulation. Medical device manufacturers in Germany and Switzerland adopt these architectures for endoluminal surgical platforms. The technology is collapsing price premiums previously commanded by direct-drive harmonic gear alternatives in the 16-24 joint segment range.
The EU AI Act risk-classification framework imposes conformity assessment obligations on autonomous snake robots with real-time decision capabilities. Industrial facility operators in the Netherlands and Denmark now require documented algorithmic transparency for hazardous material handling deployments. Defense and nuclear decommissioning contractors are responding by segregating teleoperated and fully autonomous product lines to manage compliance scope.
Buyer consolidation among national oil companies and utility operators is compressing vendor qualification cycles. Energy sector procurement teams in Norway and the UK now mandate ISO 13628-8 subsea production system interoperability for inspection robotics. This behavioral shift favors snake robot developers with pre-certified pressure vessel designs over generalist robotics suppliers attempting lateral entry.
Snake Robots Market Segmentation
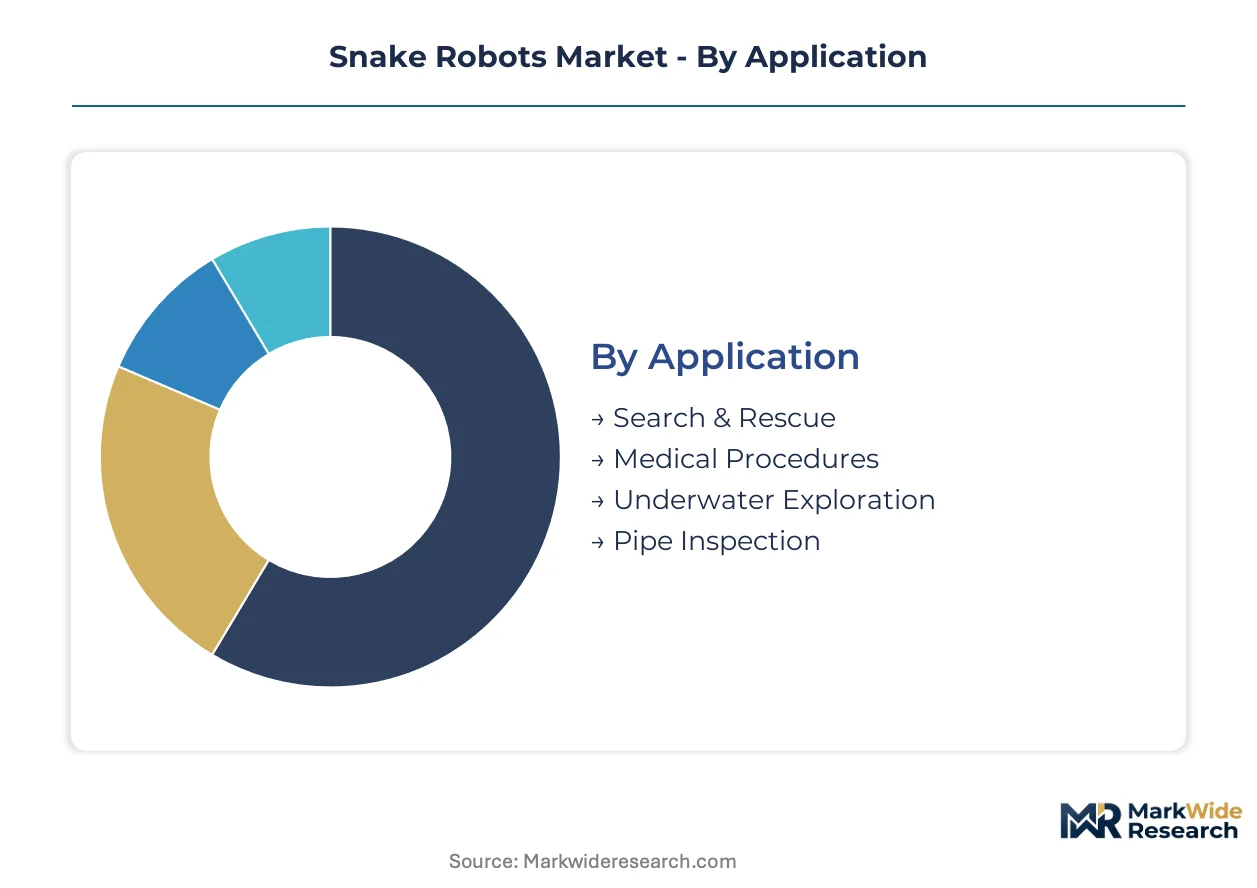
Snake robot segmentation reveals how hyper-redundant architectures adapt to radically different environmental constraints. Application requirements dictate actuator density, material compliance, and control autonomy in ways that reshape procurement patterns across defense, healthcare, and energy verticals.
Application:
Use-case spectrum spans collapsed-structure penetration, endoluminal surgery, subsea infrastructure, and confined-space industrial inspection with divergent payload and environmental sealing demands.
- Search & Rescue:Deployments concentrate on 16-32 degree-of-freedom tendon-driven platforms for navigation through earthquake-damaged buildings and tunnel collapses. METI-funded procurement clusters in Japan's Osaka and Tsukuba robotics hubs concentrate demand for disaster-response configurations ahead of other geographies.
- Medical Procedures:Endoluminal surgical platforms leverage soft silicone elastomer interfaces to reduce tissue trauma during minimally invasive interventions. FDA 510(k) electromechanical safety reviews and EU MDR clinical evidence requirements impose extended certification timelines that constrain US and European commercial velocity.
- Underwater Exploration:Pressure-rated systems target North Sea offshore wind foundation inspection and aging oil platform decommissioning with ISO 13628-8 subsea production system interoperability mandates.
- Pipe Inspection:Aging OECD utility infrastructure sustains current deployment volumes through modular tethered configurations addressing 150-900mm diameter municipal and industrial conduit networks.
Established volume favors pipe inspection; emerging adoption favors medical procedures.
Technology:
Cost tier separation runs from research-grade modular platforms to production-hardened autonomous systems with integrated safety certification.
- Modular Design:Hot-swappable joint segments enable field-reconfigurable payload and length adaptation without manufacturer intervention. Rental and lease distribution channels open as energy sector procurement teams in Norway and the UK mandate rapid reconfiguration for multi-site inspection contracts.
- Soft Robotics:Compliant pneumatic continuum architectures from adjacent medical robotics segments threaten traditional snake robot positioning through reduced damage risk in fragile environment access. German and Swiss medical device manufacturers adopt tendon-sheath transmission systems that collapse price premiums previously commanded by direct-drive harmonic gear alternatives.
- Autonomous Control:Real-time decision capabilities trigger EU AI Act risk-classification conformity assessment obligations. Dutch and Danish industrial facility operators now require documented algorithmic transparency for hazardous material handling deployments.
- Remote Operated:Teleoperated product lines segregate from autonomous configurations to manage compliance scope under divergent national AI governance frameworks.
Remote operated systems dominate current revenue; autonomous control gains share fastest in defense and nuclear decommissioning procurement.
End User:
Customer type determines certification pathway complexity and procurement cycle duration with substantial margin differentiation.
- Healthcare Providers:Hospital systems and ambulatory surgical centers demand biocompatibility certification under FDA, EU MDR, and Japan PMDA frameworks with parallel submission strategies.
- Energy Companies:National oil companies and utility operators compress vendor qualification cycles through buyer consolidation. Pre-certified pressure vessel designs command preference over generalist robotics suppliers.
- Research Institutions:Academic and government laboratory procurement sustains development-stage platform volumes with less stringent interoperability requirements.
- Government Agencies:Defense and civil emergency response budgets concentrate demand for search-and-rescue configurations with hardened environmental sealing specifications.
Energy companies drive standardization; government agencies anchor disaster-response technology maturation.
Size:
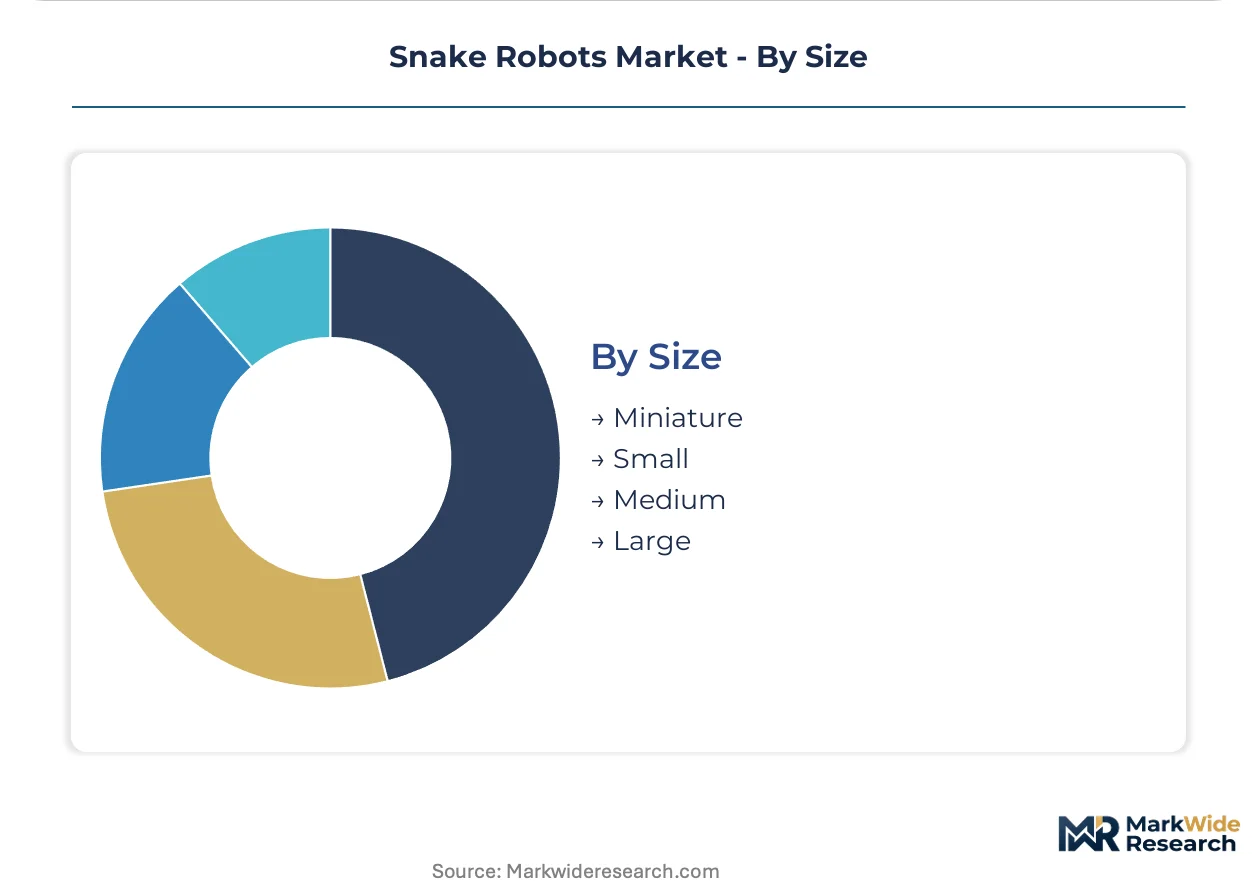
Scale tier alignment maps directly to environmental constraint severity and payload requirements.
- Miniature:Sub-50mm diameter configurations target endoluminal surgical access and micro-pipe inspection with extreme miniaturization of tendon-sheath transmission mechanisms.
- Small:Compact platforms balance maneuverability with sensor payload capacity for building collapse search operations and municipal utility networks.
- Medium:Mid-scale systems dominate industrial pipe inspection and hazardous material handling with standardized joint segment architectures.
- Large:Heavy-duty configurations address subsea infrastructure with pressure-rated housings and extended reach for offshore platform decommissioning.
Medium size captures current production volume; miniature configurations show steepest expansion trajectory as surgical applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI in Japan anchors the dominant geography through concentrated funding for disaster robotics clusters, while FDA and EU MDR frameworks reshape certification requirements across North America and Europe. Regional demand patterns diverge sharply based on regulatory maturity and infrastructure investment cycles.
Japan
Domestic procurement intensifies through Osaka and Tsukuba robotics hubs for search-and-rescue snake robot deployment. PMDA aligns with METI robotics roadmaps to accelerate regulatory review timelines for disaster-response platforms. Tokyo-based government agencies concentrate demand-pull for hardened environmental sealing specifications ahead of other geographies.
United States
Industrial facility operators drive demand for hazardous material handling configurations with dexterous teleoperation capabilities. FDA 510(k) electromechanical safety reviews impose extended timelines for surgical snake platforms seeking market entry. Greater Boston and Pittsburgh anchor defense and nuclear decommissioning contractor procurement clusters.
Germany
Medical device manufacturers adopt tendon-sheath transmission systems for endoluminal surgical platforms. EU MDR clinical evidence requirements govern commercialization pathways for active implantable adjacent systems. Baden-Württemberg and Bavaria concentrate precision actuator subsystem suppliers serving both medical and industrial snake robot OEMs.
United Kingdom
Defense and nuclear decommissioning contracts sustain demand for confined-space manipulation systems. OC Robotics leverages heritage positioning to maintain institutional relationships across UK industrial facilities. Bristol and Oxfordshire host development-stage platform clusters with less stringent interoperability requirements than energy sector procurement.
Norway
North Sea offshore wind expansion and aging oil platform decommissioning create unmet demand for pressure-rated underwater snake robot systems. ISO 13628-8 subsea production system interoperability mandates compress vendor qualification cycles. Stavanger and Bergen concentrate energy sector procurement teams mandating rapid reconfiguration for multi-site inspection contracts.
Snake Robots Market Key Industry Players
Defense contractors and medical device specialists split the market into technology-driven silos with limited cross-segment mobility. The vendor base organizes around three strategic archetypes: heritage nuclear/defense contractors with institutional relationships, subsea energy specialists with pressure-rated platform expertise, and medical device manufacturers with biocompatibility certification capabilities. Dominant competitive moves include modular architecture licensing for field-reconfigurable joint segments and strategic partnerships with national oil companies for subsea inspection qualification.
Among heritage UK-based contractors, OC Robotics and Oliver Crispin Robotics Limited occupy positions within the confined-space manipulation tier, exemplifying defense and nuclear decommissioning relationship anchoring. Eelume AS represents the subsea energy specialist archetype with Norwegian origins, sitting within the pressure-rated platform segment. Sarcos Technology and Robotics Corporation anchors the US industrial teleoperation tier, while Medrobotics exemplifies medical device specialists navigating FDA and EU MDR certification pathways. HiBot Corp. and Hirose Fukushima Laboratory represent Japanese research-to-commercialization pipelines aligned with METI funding structures.
| Leading Market Players |
|---|
| OC Robotics |
| Eelume AS |
| HiBot Corp. |
| Applied Robotics Technologies LLC |
| Sintef |
| Sarcos Technology and Robotics Corporation |
| Medrobotics |
| Hirose Fukushima Laboratory |
| Oliver Crispin Robotics Limited |
| Others |
Cost & Logistics Intelligence
Rare-earth magnet processing concentration in China and Southeast Asian refineries funnels pricing power toward precision actuator subsystem suppliers, compressing margins for downstream snake robot OEMs while concentrating value capture in tendon-drive transmission architectures.
Pricing Analysis
Japanese procurement clusters command 15-25% premiums over European equivalents for disaster-response configurations with identical joint-segment specifications. Pricing stratifies across medical-grade FDA 510(k) certified platforms, industrial ISO 13482 aligned systems, and research-grade modular kits. Cost compression in standard industrial tiers intensifies as Chinese actuator suppliers expand direct sales channels. Energy sector buyers in Norway and the UK exhibit lowest price sensitivity due to mandated ISO 13628-8 interoperability requirements that lock in qualified vendors.
Supply Chain Analysis
Neodymium-iron-boron magnet feedstock draws from Chinese rare-earth mining operations and Malaysian separation facilities, with secondary processing concentrated in Japan and Germany for high-temperature servo motor applications. Tendon-sheath cable assemblies source from Swiss and Italian precision metalworking suppliers; pressure-rated housings for subsea configurations rest on Norwegian and UK marine engineering foundries. Single-source vulnerability in rare-earth magnet supply creates tariff exposure risk under evolving trade frameworks. Distribution runs through direct OEM sales for medical and defense contracts, with rental channels emerging for modular industrial platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 510(k) and EU MDR certification pathways constructs formidable defensive moats for established medical snake robot developers, with switching costs amplified by hospital system integration requirements and clinician retraining investments.
For Market Incumbents: Pre-empt soft robotics substitution threats by accelerating biocompatibility certification for silicone elastomer joint interfaces before pneumatic continuum robots capture minimally invasive procedure share. Fortify backward integration into rare-earth magnet supply through long-term offtake agreements with Malaysian and Vietnamese processors. Expand capacity in Osaka and Tsukuba METI-funded clusters to anchor disaster-response procurement relationships ahead of regulatory harmonization elsewhere.
For New Entrants and Emerging Players: Pursue subsea energy inspection white space in North Sea offshore wind foundation markets where ISO 13628-8 interoperability mandates have disqualified generalist robotics suppliers. Target research institution procurement channels with modular field-reconfigurable platforms that bypass medical certification friction. Lead with algorithmic transparency documentation to satisfy Dutch and Danish industrial facility operator requirements under EU AI Act frameworks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across soft robotics material interfaces as pneumatic continuum architectures achieve production scale, compressing venture-scale returns in that sub-segment. Focus acquisition screening on heritage nuclear/defense contractors with embedded institutional relationships and existing pressure-rated platform expertise. Monitor PMDA-METI regulatory alignment velocity as the inflection signal for Japanese market access timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Architecture Licensing | Enables rental channel penetration for energy sector multi-site inspection contracts without manufacturer field presence. |
| Tendon-Sheath Transmission Scale-Up | Collapses cost premiums previously commanded by direct-drive harmonic gear alternatives in 16-24 joint configurations. |
| EU MDR Parallel Submission Investment | Accelerates commercial timelines for surgical platforms in European healthcare systems ahead of FDA 510(k) completion. |
| Subsea Pressure Vessel Pre-Certification | Satisfies Norwegian and UK national oil company procurement mandates for ISO 13628-8 interoperability compliance. |
| Algorithmic Transparency Documentation | Addresses Dutch and Danish hazardous material handling operator requirements under EU AI Act risk-classification frameworks. |
Research Approach
A standing panel of snake robot OEM engineering directors, hospital biomedical equipment procurement managers, nuclear decommissioning site safety officers, and North Sea energy sector inspection contractors provided ongoing calibration across the study period. Primary interview data triangulated against secondary sources including FDA 510(k) submission databases, EU MDR notified body certification registries, METI robotics roadmap publications, and ISO 13482 service robot safety standard committee documentation. Bottom-up segment sizing across application, technology, end user, and size dimensions reconciled with top-down macro constraint checks.
Scenario bracketing around rare-earth magnet supply disruption, EU AI Act enforcement intensity variation, and METI funding continuity established projection bounds. The analytical framework modeled demand across search and rescue, medical procedures, underwater exploration, and pipe inspection applications; technology segmentation captured modular design, soft robotics, autonomous control, and remote operated configurations. CAGRs derived from segment-level unit economics and pricing trajectory analysis, with tendon-drive cost curves and subsea pressure-rating premiums as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in yen-dollar exchange rates, rare-earth oxide spot pricing, or North Sea offshore wind capex cycles would shift the trajectory. Cross-checking against IEA energy infrastructure investment databases and PMDA medical device approval statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Sweeper Robot Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Claytronics Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Japan Cloud Robotics Market