

Robotics Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics Actuators Market Insights
Direct-to-factory distribution is tilting toward system integrators who bundle actuators with motion controllers. Festo leverages its pneumatic heritage to anchor European industrial automation channels. ABB competes through servo-electric platforms that dominate high-precision manufacturing lines. Moog specializes in defense-grade hydraulic actuators that sustain long-term aerospace contracts.
Robotics actuators convert electrical, hydraulic, or pneumatic energy into controlled mechanical motion, typically achieving positioning accuracy within micrometers through closed-loop feedback systems. These devices serve as the primary motion source in automated machinery, enabling programmable force, velocity, and displacement across industrial and service robot platforms. Electric actuator types, particularly servo motor variants, command the largest installed base due to energy efficiency and programmability advantages. Piezoelectric actuation technology represents the fastest-expanding segment, driven by semiconductor fabrication demand for nanometer-scale positioning. Manufacturing automation applications concentrate the deepest margin pools, where uptime guarantees and integration complexity protect supplier pricing power.
ISO 10218 safety standards and the EU Machinery Directive constrain product design requirements for collaborative robot deployments. China's GB standards and MIIT technical regulations mandate electromagnetic compatibility and energy efficiency thresholds for imported actuator systems. FDA device regulations and FAA airworthiness criteria impose additional validation burdens on actuators bound for medical and aerospace end uses. Stakeholders must monitor how regional certification divergence affects platform standardization strategies and supplier qualification costs.
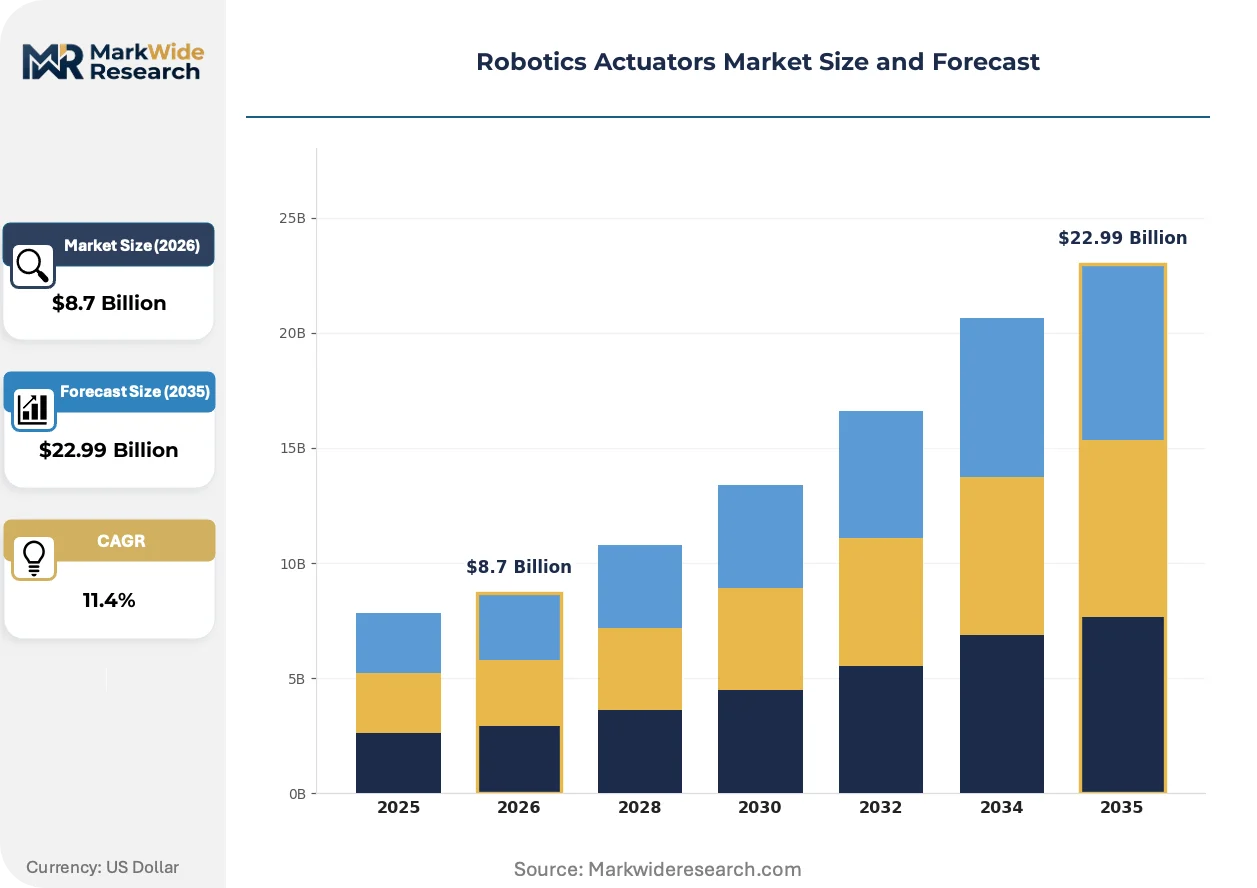
Market Dynamics
Warehouse automation intensification is compressing actuator procurement cycles, forcing suppliers to bundle motion controllers and predictive maintenance software into hardware contracts. This shift rewards system integrators who can guarantee uptime rather than component vendors selling standalone units.
Growth Catalysts
- EU Machinery Directive compliance mandates:Collaborative robot deployments require ISO 10218-certified actuators with force-limiting and safety-rated monitored stop functions, creating replacement demand across German and Italian automotive lines.
- Semiconductor fabrication expansion:Piezoelectric actuation achieves nanometer-scale positioning for EUV lithography systems, with Taiwan and South Korea fabs driving volume procurement of multi-axis nanopositioning stages.
- China's dual carbon goals:MIIT energy efficiency thresholds for industrial equipment accelerate servo-electric actuator adoption over pneumatic alternatives in Jiangsu and Guangdong manufacturing clusters.
Market Restraints
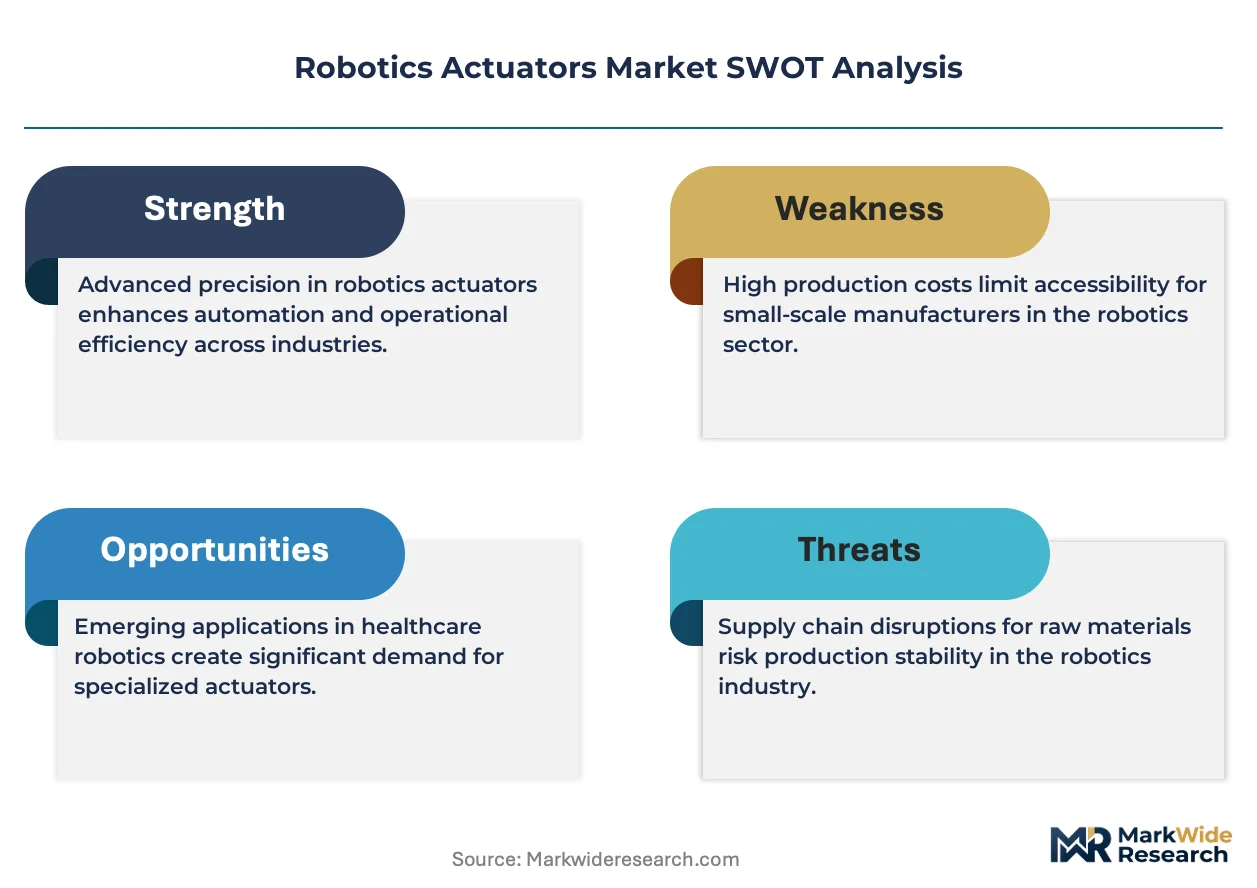
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings constrain permanent magnet servo motor margins, particularly for suppliers without long-term offtake agreements with Chinese processors.
- Hydraulic fluid environmental liability:REACH restrictions on mineral oil-based hydraulic fluids force aerospace and defense contractors toward bio-alternatives with shorter service intervals and higher maintenance burdens.
- Precision bearing supply concentration:Japanese and German specialty bearing manufacturers control sub-micron tolerance supply for harmonic drive actuators, creating single-source risk for collaborative robot producers.
Strategic Opportunities
- India PLI scheme for robotics:Production-linked incentives for industrial automation equipment attract actuator assembly investments serving domestic automotive and electronics contract manufacturers.
- Soft actuator convergence:Integration of elastomeric artificial muscles with conventional electromechanical drives enables compliant manipulation for food handling and eldercare assistance applications.
- Direct-to-factory platform distribution:Cloud-based actuator configuration tools bypass traditional distributor markups, capturing margin from mid-volume machine builders in Poland and the Czech Republic.
Industry Challenges
- Motion control firmware talent scarcity:Shortage of engineers proficient in real-time embedded systems and safety-certified code development extends product validation timelines for collaborative robot actuator suppliers.
- Multi-certification stacking:Simultaneous FDA device, FAA airworthiness, and EU Machinery Directive compliance for medical and aerospace actuators requires redundant testing protocols that compress development budgets.
- Legacy fieldbus integration friction:EtherCAT and PROFINET migration demands from brownfield manufacturing lines force actuator suppliers to maintain deprecated communication stacks, fragmenting R&D resources.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics Actuators Market Trends and Innovations
Actuator architectures are fragmenting along precision-throughput tradeoffs, with nanometer-scale semiconductor positioning diverging from high-force logistics handling. This bifurcation is compressing mid-range product viability and rewarding specialized platform suppliers.
Electro-hydraulic actuation is hybridizing servo valve control with compact power-dense hydraulic cylinders, combining electric programmability with hydraulic force multiplication. Off-highway equipment manufacturers in Germany and Japan are adopting these systems for excavator and agricultural implement automation. The technology is hybridizing previously separate electric and hydraulic supply chains, forcing component suppliers to develop dual-competency service networks.
REACH substance restrictions are tightening permissible materials in precision motion components, with ECHA candidate list updates targeting chromium plating and certain fluoropolymer seals used in linear actuator guides. European machine tool builders must redesign guide rail assemblies or qualify alternative coatings, adding six to twelve months to product recertification cycles. German automotive OEMs are responding by consolidating supplier qualification pools to vendors with pre-validated green material portfolios.
Machine builders are unbundling actuator hardware from lifecycle service contracts, separating upfront capital expenditure from predictive maintenance subscriptions. System integrators in the United States and Nordic countries now procure actuators through usage-based arrangements where sensor data feeds remote condition monitoring. Food and beverage packaging lines in Denmark and the Netherlands display the strongest uptake, driven by sanitation downtime costs that outweigh per-unit hardware premiums.
Robotics Actuators Market Segmentation
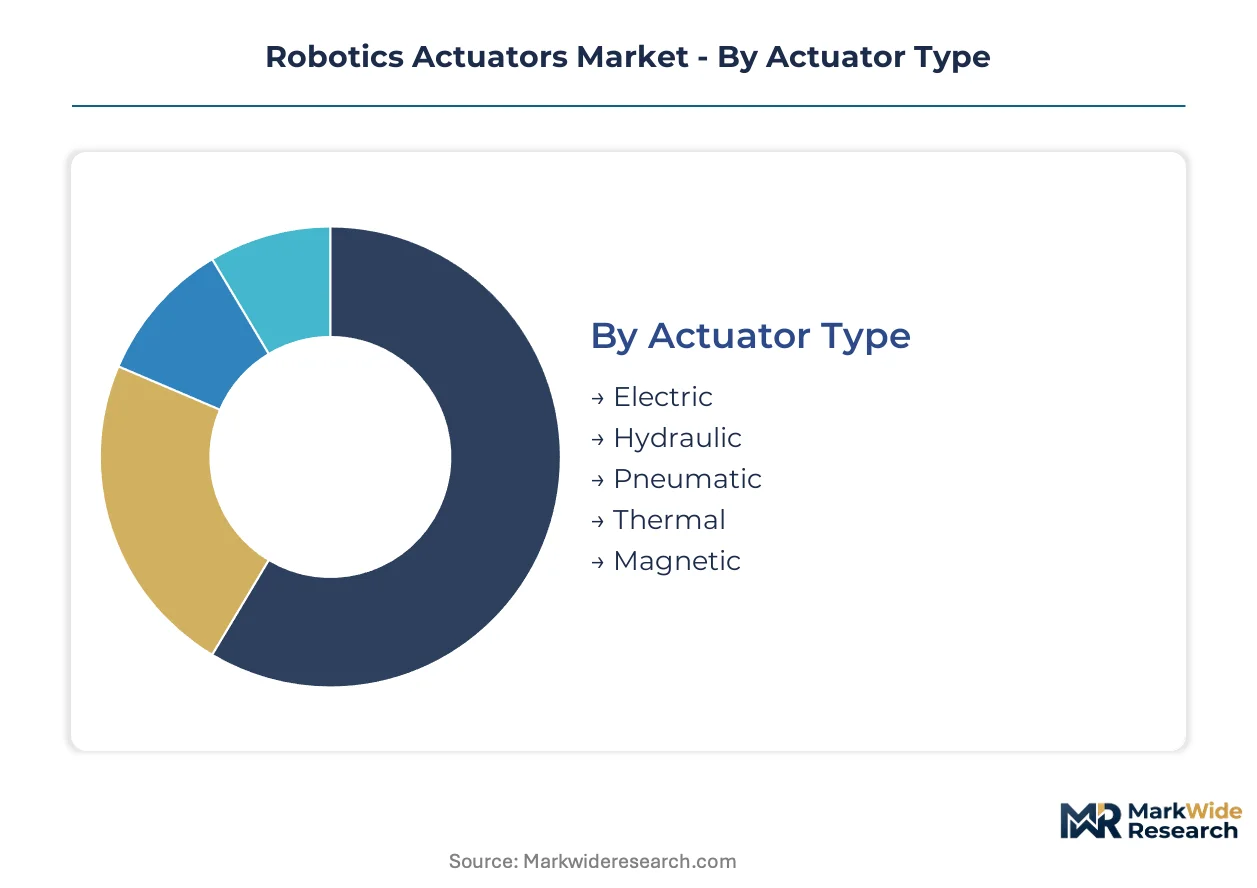
Robotics actuators fragment across incompatible performance regimes, forcing suppliers to choose between precision positioning and force multiplication. Each segment carries distinct certification burdens, maintenance intervals, and integration complexity that reshape vendor profitability and customer lock-in.
Actuator Type:
After-sales-service intensity varies dramatically across energy conversion mechanisms, with hydraulic systems demanding fluid monitoring contracts and electric variants requiring firmware update subscriptions.
- Electric:Servo motor and stepper configurations dominate precision manufacturing through closed-loop position feedback and programmable velocity profiles. German automotive OEMs and Taiwanese semiconductor fabs anchor procurement volumes, driven by MIIT energy efficiency thresholds in China and EU Machinery Directive safety mandates in Europe.
- Hydraulic:High-force density cylinders serve aerospace and construction equipment where electric alternatives cannot match torque multiplication. Defense contractors in the United States and off-highway equipment builders in Japan sustain long-term service agreements, though REACH fluid restrictions compress maintenance margins.
- Pneumatic:Compressed air systems retain cost advantages in food-grade washdown environments.
- Thermal:Shape-memory alloy actuators enable compact deployment in miniature surgical instruments.
- Magnetic:Magnetostrictive transducers provide contactless motion for vacuum chamber applications.
Electric holds the largest share; momentum sits with magnetic actuation for cleanroom compatibility.
Application:
Cost tier stratification separates capital-intensive aerospace qualification from high-volume logistics procurement with compressed payback periods.
- Manufacturing Automation:Multi-axis robotic arms and CNC machine tools consume precision servo actuators with micrometer repeatability. Automotive assembly lines in Germany and electronics contract manufacturers in Poland drive replacement cycles, constrained by ISO 10218 collaborative robot safety standards.
- Aerospace Systems:Flight control surfaces and landing gear mechanisms demand FAA-certified hydraulic and electro-hydraulic actuators with failure-rate guarantees. Boeing and Airbus tier-one suppliers in the United States and France maintain decade-long qualification relationships that freeze out new entrants.
- Consumer Electronics:Miniature linear actuators enable camera autofocus and haptic feedback in smartphones.
- Agriculture Automation:Autonomous tractors and precision sprayers adopt ruggedized electric drives.
- Logistics Equipment:Warehouse robots and automated storage systems prioritize throughput over precision.
Manufacturing automation commands the deepest margins; logistics equipment is expanding most quickly as e-commerce fulfillment accelerates.
Actuation Technology:
Volume concentration in semiconductor fabrication equipment is reshaping supplier R&D allocation toward nanometer-scale positioning systems.
- Servo Motor:Rotary and linear servo configurations provide the programmable torque-velocity-position envelope required for industrial robot joints. Machine tool builders in Germany and packaging OEMs in the Netherlands standardize on EtherCAT-interfaced servo drives, though legacy fieldbus migration fragments engineering resources.
- Piezoelectric:Ceramic-stack nanopositioners achieve sub-nanometer resolution for EUV lithography and atomic force microscopy. Taiwan Semiconductor Manufacturing and Samsung Foundry in South Korea drive multi-axis stage procurement, with each fab deployment representing hundreds of units.
- Stepper Motor:Open-loop positioning suffices for low-cost 3D printers and desktop automation.
- Voice Coil:Direct-drive linear motion serves optical image stabilization and disk drive head positioning.
- Electroactive Polymer:Compliant dielectric elastomers enable soft robotic grippers for delicate object manipulation.
Servo motor retains the broadest installed base; piezoelectric claims the steepest expansion trajectory from lithography capital expenditure.
End User Industry:
Supply concentration in Japanese and German precision bearing manufacturers creates single-source vulnerability for collaborative robot producers serving this segment.
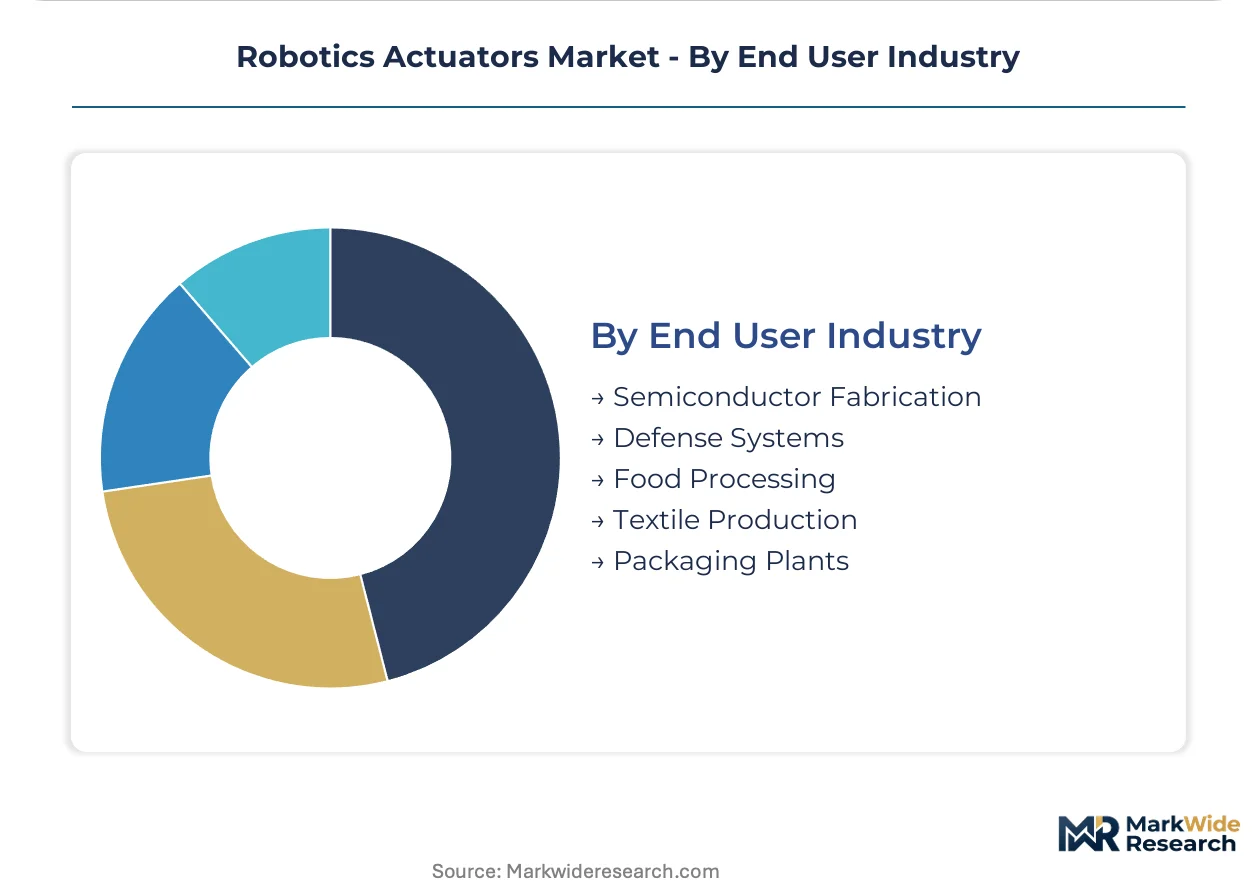
- Semiconductor Fabrication:Wafer handling robots and lithography positioning stages require vacuum-compatible actuators with zero particulate generation. ASML's EUV tool ecosystem in the Netherlands and Applied Materials' deposition systems in the United States specify piezoelectric and magnetic levitation drives with multi-year qualification locks.
- Defense Systems:Military-grade actuators for unmanned vehicles and weapon platforms must survive shock, vibration, and electromagnetic pulse. Pentagon procurement through Moog and Parker Hannifin in the United States favors hydraulic and electro-hydraulic architectures with decades-long field service support.
- Food Processing:Washdown-rated electric actuators replace pneumatic cylinders to eliminate contamination risk.
- Textile Production:High-speed loom mechanisms consume rotary servo systems with rapid acceleration profiles.
- Packaging Plants:Cartoning and palletizing lines prioritize uptime guarantees over component specifications.
Semiconductor fabrication generates the highest unit margins; food processing is gaining share fastest from sanitary automation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision manufacturing clusters while procurement volume tilts toward Chinese logistics automation hubs, creating a two-tier margin structure across the analysis window.
Germany
Automotive OEMs and machine tool builders in Stuttgart and Munich anchor actuator demand for collaborative robot deployments. EU Machinery Directive compliance mandates force ISO 10218-certified component upgrades across Bavarian and Baden-Württemberg production lines. The Mittelstand supplier network around Nuremberg specializes in harmonic drive actuators for precision positioning.
China
MIIT energy efficiency thresholds accelerate servo-electric adoption over pneumatic alternatives in Jiangsu and Guangdong manufacturing clusters. GB standards and dual carbon goals tighten electromagnetic compatibility requirements for imported systems. Shenzhen and Suzhou logistics equipment operators compress procurement cycles for warehouse automation actuators.
United States
Pentagon procurement sustains long-term demand for defense-grade hydraulic and electro-hydraulic architectures. FAA airworthiness criteria impose validation burdens on actuators bound for Boeing and Airbus tier-one suppliers in Washington State and Kansas. The Southeast automotive corridor in Tennessee and South Carolina drives replacement demand for safety-rated collaborative robot components.
Japan
Specialty bearing manufacturers in Nagoya and Osaka control sub-micron tolerance supply for harmonic drive actuators, creating single-source concentration risk. METI industrial automation policies support domestic precision motion component production. Tokyo and Yokohama-based system integrators bundle predictive maintenance software with hardware contracts.
South Korea
Samsung Foundry and SK Hynix fabs in Gyeonggi Province drive multi-axis nanopositioning stage procurement for EUV lithography systems. MFDS medical device regulations intersect with semiconductor fabrication requirements for vacuum-compatible actuators. Busan-Ulsan industrial automation clusters adopt piezoelectric actuation for nanometer-scale positioning.
Robotics Actuators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, each occupying distinct margin pools based on integration depth. The vendor base splits between consolidated multi-nationals with full motion control portfolios and focused specialists dominating single technologies. Two archetypes predominate: pneumatic heritage suppliers leveraging channel relationships, and servo-electric platforms competing on precision manufacturing integration. Competitive moves center on bundling motion controllers with predictive maintenance subscriptions and consolidating distributor networks to capture direct-to-factory relationships.
Among diversified industrial automation conglomerates, ABB and Rockwell Automation occupy positions spanning servo-electric platforms and system integration capabilities. Moog sits within the defense-aerospace specialist tier, anchoring long-term qualification relationships with Pentagon procurement channels. These three exemplify how geographic origin and corporate structure shape competitive positioning—Swiss-American, American, and American respectively—without determining specific strategic outcomes.
| Leading Market Players |
|---|
| ABB |
| Emerson Electric |
| Rockwell Automation |
| SMC |
| Moog |
| Festo |
| Harmonic Drive |
| Curtiss-Wright |
| MISUMI Group |
| Others |
Pricing and Supply Chain Analysis
Nagoya's specialty bearing manufacturing cluster dictates margin capture for precision harmonic drive actuators, concentrating upstream supply power while downstream machine builders face compressed procurement leverage. REACH substance restrictions and MIIT energy efficiency mandates feed into material cost pass-through mechanisms that reshape supplier-buyer negotiations.
Pricing Analysis
The customization-premium spread separates configured-to-order servo-electric platforms from standard pneumatic cylinders, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales bundling. ISO 10218 safety-rated actuators command substantial premiums over uncertified alternatives, while volume-scale discounts concentrate among German automotive OEMs. Cost compression in mid-range electric actuators is intensifying because Chinese domestic suppliers are expanding servo motor capacity. Logistics equipment operators display the highest price sensitivity, prioritizing throughput-per-dollar over precision specifications.
Supply Chain Analysis
Export-control regimes limiting semiconductor fabrication equipment flows constrain piezoelectric actuator technology transfer to certain fabrication hubs. Manufacturing concentrates in Germany, Japan, and China, with rare earth magnet processing anchored in Chinese Jiangsu and Guangdong provinces. The supply chain draws from neodymium-dysprosium permanent magnets, sub-micron tolerance bearings, and specialized electromagnetic steel laminations. Single-source vulnerability permeates Japanese harmonic drive gear manufacturing. Distribution runs through system integrators who bundle predictive maintenance subscriptions with hardware contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuator architectures are fragmenting along precision-throughput tradeoffs, creating specialized niches as semiconductor fabrication diverges from warehouse automation requirements. This bifurcation rewards focused platform suppliers over generalist component vendors.
For Market Incumbents: Pre-empt margin erosion in standard servo motor tiers by securing long-term rare earth offtake agreements with Chinese processors. Consolidate distributor networks to capture direct-to-factory relationships in Poland and Czech Republic machine builder clusters. Invest in firmware talent pipelines to address motion control engineer scarcity extending validation timelines. For New Entrants and Emerging Players: Establish a beachhead in soft actuator convergence for food handling and eldercare assistance applications where compliant manipulation creates defensible differentiation. Target India's PLI scheme for robotics assembly investments serving domestic automotive contract manufacturers. Pursue cloud-based actuator configuration tools to bypass traditional distributor markups in mid-volume European markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors piezoelectric nanopositioning specialists with ASML ecosystem qualification locks over general industrial servo suppliers. The five-to-ten year viability window rewards semiconductor fabrication equipment component suppliers with multi-year fab deployment cycles. Watch EUV lithography capital expenditure announcements as the primary inflection indicator for nanopositioning stage demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures neodymium-dysprosium processing capacity against Chinese processor price volatility. |
| Predictive Maintenance Platform Launch | Captures recurring revenue from Danish and Dutch food packaging line uptime guarantees. |
| Soft Actuator R&D Partnership | Accelerates compliant manipulation capabilities for washdown-rated food handling applications. |
| India PLI Scheme Manufacturing Footprint | Accesses production-linked incentives serving domestic automotive and electronics contract manufacturers. |
| REACH-Compliant Material Portfolio Certification | Qualifies for German automotive OEM consolidated supplier pools avoiding six-to-twelve month recertification delays. |
Research Methodology
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this robotics actuators assessment. Primary fieldwork combined structured interviews with motion control system integrators and precision component suppliers, validated against secondary sources including customs trade data, SEC 10-K filings from diversified industrial conglomerates, MIIT technical regulation disclosures, and ECHA substance restriction updates. Bottom-up actuator shipment tallies by application and technology type were cross-referenced with top-down manufacturing automation capital expenditure estimates.
Scenario-bracketing framed volume and value outputs across the analysis window, modeling segmentation dimensions spanning actuator type, application, actuation technology, and end user industry alongside regional regulatory cluster variations. CAGRs were derived from installed base replacement cycles and new deployment trajectories, incorporating semiconductor fabrication equipment capital expenditure patterns, warehouse automation intensification rates, and collaborative robot safety mandate compliance timelines as industry-specific forecast inputs.
Sensitivities concentrate around rare earth magnet price volatility, REACH substance list expansion, and EU Machinery Directive enforcement intensity. Forecasts reflect documented assumptions regarding technology substitution rates and regional certification harmonization progress. Material shifts in export control regime scope or EUV lithography deployment schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.