
 North America Underwater Robotics Market | 2026-2036
North America Underwater Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Underwater Robotics Market Analytics
The subsea engineering talent pool is bifurcating between legacy ROV pilot-technicians and AI-fluent autonomy engineers, creating a skills gap that slows fleet modernization for some operators while accelerating it for others. Oceaneering International sustains the largest service fleet presence across the Gulf of Mexico, leveraging decades of offshore contracting relationships. Deep Trekker specializes in portable, battery-powered inspection systems that compete on deployment speed for nearshore infrastructure. Teledyne Marine anchors the sensor and sonar subsystem supply chain, extending its reach into navigation payloads for both ROV and AUV platforms.
North America underwater robotics encompasses tethered, autonomous, and hybrid platforms engineered for pressure-rated operation typically from 300 to 6,000 meters depth, using buoyancy-modified syntactic foam hulls and oil-compensated electronics housings to perform intervention, survey, and monitoring tasks in submerged environments. The Remotely Operated Vehicles segment dominates current revenue, sustained by oil and gas decommissioning contracts and defense salvage operations, while Autonomous Underwater Vehicles represent the fastest-expanding margin pool as navies and research institutions shift toward persistent, untethered seabed survey. Artificial Intelligence and Machine Learning integration within navigation systems is displacing conventional waypoint programming, enabling real-time obstacle avoidance and adaptive mission replanning that reduces surface support vessel costs.
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer inspection intervals that directly shape ROV utilization rates in federal waters, while the Canadian Environmental Protection Act governs seabed disturbance protocols for Arctic research deployments. The US Navy's Unmanned Maritime Systems program office influences technology roadmaps through funded prototype contracts that set de facto performance benchmarks for domestic suppliers. Stakeholders must monitor how FAA coordination with maritime regulators evolves for aerial-underwater hybrid platforms, as airspace-sea interface rules will determine where cross-domain systems gain first operational clearance.
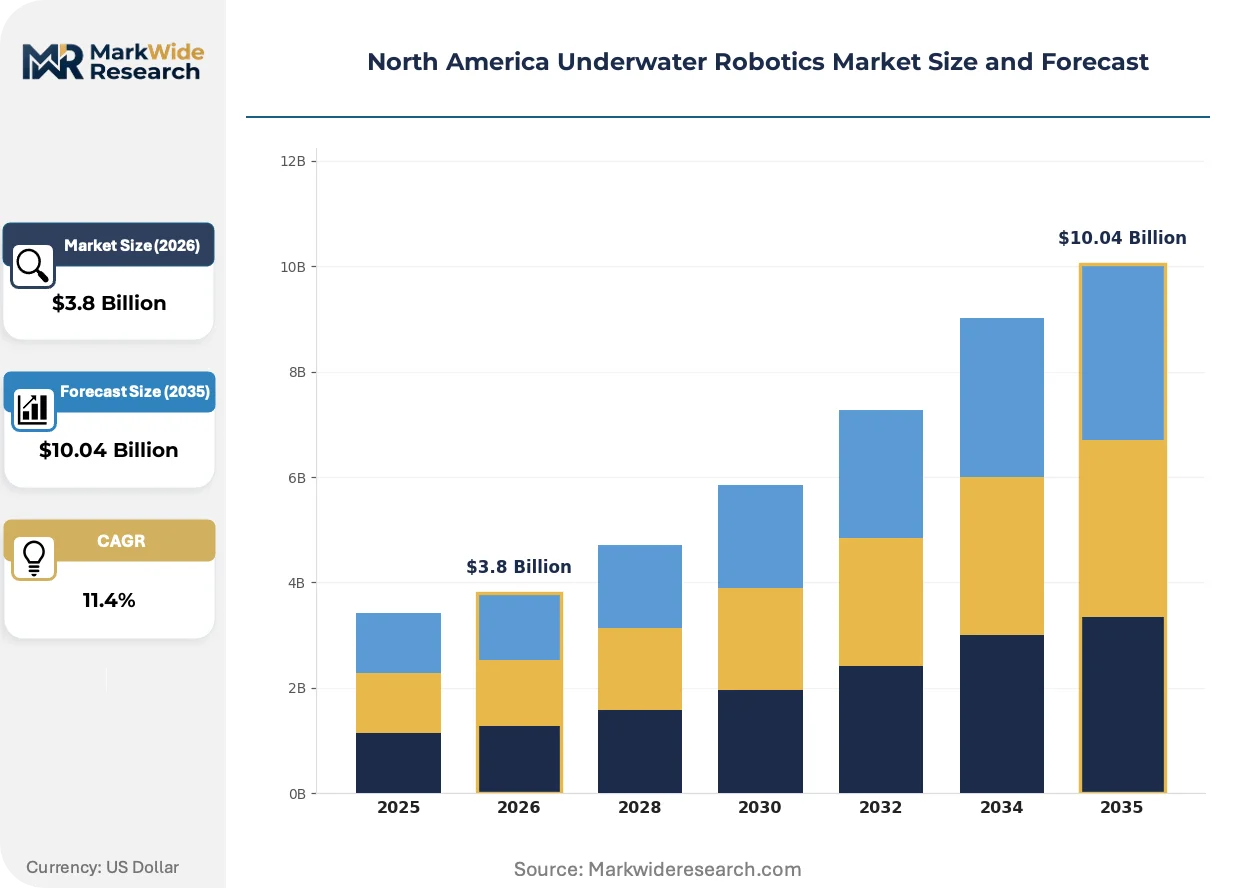
Market Dynamics
The US Bureau of Safety and Environmental Enforcement's tightened well-control regulations are forcing Gulf of Mexico operators to accelerate ROV fleet upgrades, compressing replacement cycles from seven years to four years for blowout preventer inspection systems.
Growth Catalysts
- Deepwater Decommissioning Mandates:Aging subsea infrastructure in the Gulf of Mexico requires systematic dismantling, creating sustained demand for heavy-lift ROV systems capable of cutting and retrieval operations at depths exceeding 1,500 meters.
- Arctic Research Expansion:Canadian seabed mapping initiatives under the Canadian Environmental Protection Act are funding autonomous survey platforms for ice-covered waters, opening new deployment environments for untethered vehicles.
- Hybrid Platform Development:Convergence of aerial drone and underwater vehicle architectures is enabling rapid surface-to-seabed inspection workflows that reduce mobilization time for offshore wind farm cable surveys.
Market Restraints
- Syntactic Foam Supply Concentration:Pressure-rated buoyancy materials rely on a limited supplier base concentrated in Texas and Louisiana, creating vulnerability to hurricane-related production disruptions.
- High-Reliability Electronics Cost:Oil-compensated housings and pressure-tolerant connectors add 40-60% cost premiums over commercial-off-the-shelf alternatives, constraining adoption among nearshore inspection contractors.
- Battery Energy Density Ceiling:Lithium-ion cell chemistry limits AUV endurance to 8-12 hours for high-speed survey missions, preventing single-deployment coverage of large lease blocks.
Strategic Opportunities
- Offshore Wind Installation Support:US Atlantic coast lease auctions are creating demand for cable burial verification and scour monitoring services that combine ROV intervention with autonomous persistent monitoring.
- Defense Salvage Modernization:The US Navy's Unmanned Maritime Systems program office is funding prototype contracts for deep-ocean aircraft recovery systems, establishing performance benchmarks that cascade to commercial suppliers.
- Mexican Energy Reform Access:Pemex is expanding subsea maintenance outsourcing for Cantarell field infrastructure, creating first-mover advantages for ROV service providers with Spanish-language operational capabilities.
Industry Challenges
- Autonomy Engineering Talent Scarcity:The subsea workforce splits between legacy ROV pilot-technicians and AI-fluent software engineers, slowing fleet modernization for operators without internal training pipelines.
- Certification Timeline Compression:FAA coordination with maritime regulators for aerial-underwater hybrid platforms remains unresolved, delaying operational clearance for cross-domain systems in federal waters.
- Legacy Vessel Integration:Retrofitting tether management systems onto aging offshore support vessels requires structural modifications that extend deployment schedules by 3-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Underwater Robotics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remotely Operated Vehicles, Autonomous Underwater Vehicles, Hybrid ROVs, Surface Supply End User: Oil & Gas, Defense, Research Institutions, Aquaculture Technology: Artificial Intelligence, Machine Learning, Sensors, Navigation Systems Application: Inspection, Data Collection, Environmental Monitoring, Underwater Construction |
| Companies Covered | General Dynamics Mission Systems, Inc., Oceaneering International, Inc., Teledyne Marine, Deep Ocean Engineering, Inc., VideoRay LLC, Deep Trekker Inc., SeaRobotics Corp., International Submarine Engineering Limited, Blue Robotics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Underwater Robotics Market Evolving Landscape
Artificial intelligence integration is restructuring competitive positioning across the North America underwater robotics sector, separating operators capable of autonomous mission replanning from those dependent on surface-controlled waypoint programming.
Navigation autonomy architectures are bifurcating between conventional acoustic positioning systems and real-time SLAM-based obstacle avoidance. Deepwater exploration contractors in the Gulf of Mexico are adopting hybrid approaches that blend pre-programmed survey lines with adaptive replanning. This technology is bifurcating service provider margins, compressing rates for standard visual inspection while expanding premiums for unplanned intervention capabilities.
The US Bureau of Safety and Environmental Enforcement mandates specific blowout preventer inspection intervals that directly shape ROV utilization rates in federal waters. Operators must document pressure tests and seal integrity checks at frequencies that exceed voluntary industry standards. Deepwater drillship contractors bear the highest compliance burden, passing inspection costs through day-rate structures that now embed dedicated ROV standby time.
Buyers are unbundling after-sales service from initial platform procurement, treating maintenance contracts as separately negotiable cost centers. Offshore energy procurement teams in Houston and New Orleans now issue discrete RFPs for spare parts logistics, technical training, and software upgrade subscriptions. This pattern is most visible among supermajor operators managing multi-vendor fleets across the Gulf of Mexico shelf and slope provinces.
North America Underwater Robotics Market Segmentation
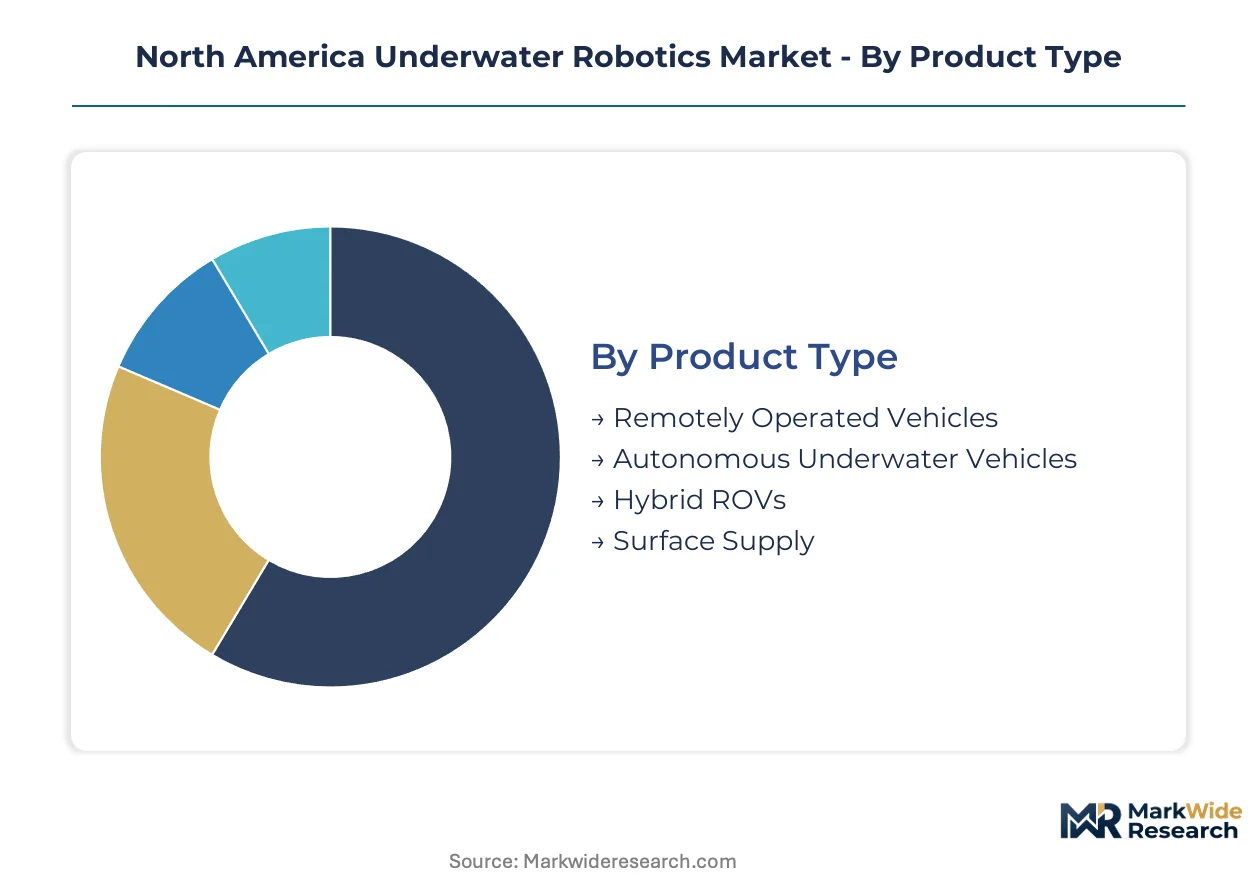
Platform architecture determines regulatory compliance pathways and operational economics across North American federal waters. The US Bureau of Safety and Environmental Enforcement and Canadian Environmental Protection Act impose distinct certification requirements that segment procurement decisions by product type and end-use.
Product Type:
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer inspection intervals that favor tethered platforms for Gulf of Mexico compliance, while Canadian Arctic research programs under the Canadian Environmental Protection Act accelerate autonomous platform adoption for ice-covered operations.
- Remotely Operated Vehicles:Tethered platforms with surface power and real-time pilot control dominate subsea intervention tasks. Gulf of Mexico decommissioning contracts in Texas and Louisiana sustain demand for heavy-lift work-class systems capable of cutting operations below 1,500 meters.
- Autonomous Underwater Vehicles:Untethered battery-powered platforms execute pre-programmed survey missions without surface vessel support. Canadian seabed mapping initiatives and US Navy persistent monitoring requirements are expanding deployment of long-endurance gliders and propeller-driven survey vehicles.
- Hybrid ROVs:Modular architectures supporting both tethered intervention and autonomous transit modes bridge operational gaps for offshore wind cable surveys.
- Surface Supply:Tether management systems and launch-and-recovery equipment constitute enabling infrastructure for ROV operations rather than standalone platforms.
Remotely Operated Vehicles handle the majority of throughput; Autonomous Underwater Vehicles are gaining share fastest as navies and research institutions shift toward untethered seabed survey.
End User:
Procurement scale and technical specifications diverge sharply between federally regulated energy operations and mission-driven defense and research programs.
- Oil & Gas:Supermajor operators and independent producers in the Gulf of Mexico deploy work-class ROVs for subsea infrastructure inspection, decommissioning, and well intervention. The US Bureau of Safety and Environmental Enforcement's tightened well-control regulations compress replacement cycles for blowout preventer inspection systems from seven years to four.
- Defense:The US Navy's Unmanned Maritime Systems program office funds prototype development for deep-ocean salvage and mine countermeasures, establishing performance benchmarks that cascade to commercial suppliers through dual-use technology transfer.
- Research Institutions:Academic and government laboratories prioritize portable, rapidly deployable platforms for Arctic and deep-ocean science missions.
- Aquaculture:Nearshore fish farm operators in British Columbia and Maine adopt low-cost inspection ROVs for net integrity monitoring and predator detection.
Oil & Gas commands the largest procurement volumes; Defense programs are expanding fastest as classified mission requirements accelerate technology development.
Technology:
Mission complexity determines technology stack composition, with navigation autonomy and sensor fusion representing the highest-value integration layers.
- Artificial Intelligence:Real-time obstacle avoidance and adaptive mission replanning algorithms reduce surface support vessel costs by enabling autonomous decision-making without pilot intervention.
- Machine Learning:Pattern recognition for seabed feature classification and anomaly detection accelerates survey data processing timelines for pipeline inspection contractors.
- Sensors:Multibeam sonar, sub-bottom profilers, and chemical sniffers constitute mission-specific payload modules.
- Navigation Systems:Acoustic positioning and simultaneous localization and mapping architectures determine operational accuracy in GPS-denied environments.
Navigation Systems anchor platform functionality; Artificial Intelligence is climbing the fastest as operators prioritize reduced surface vessel dependency.
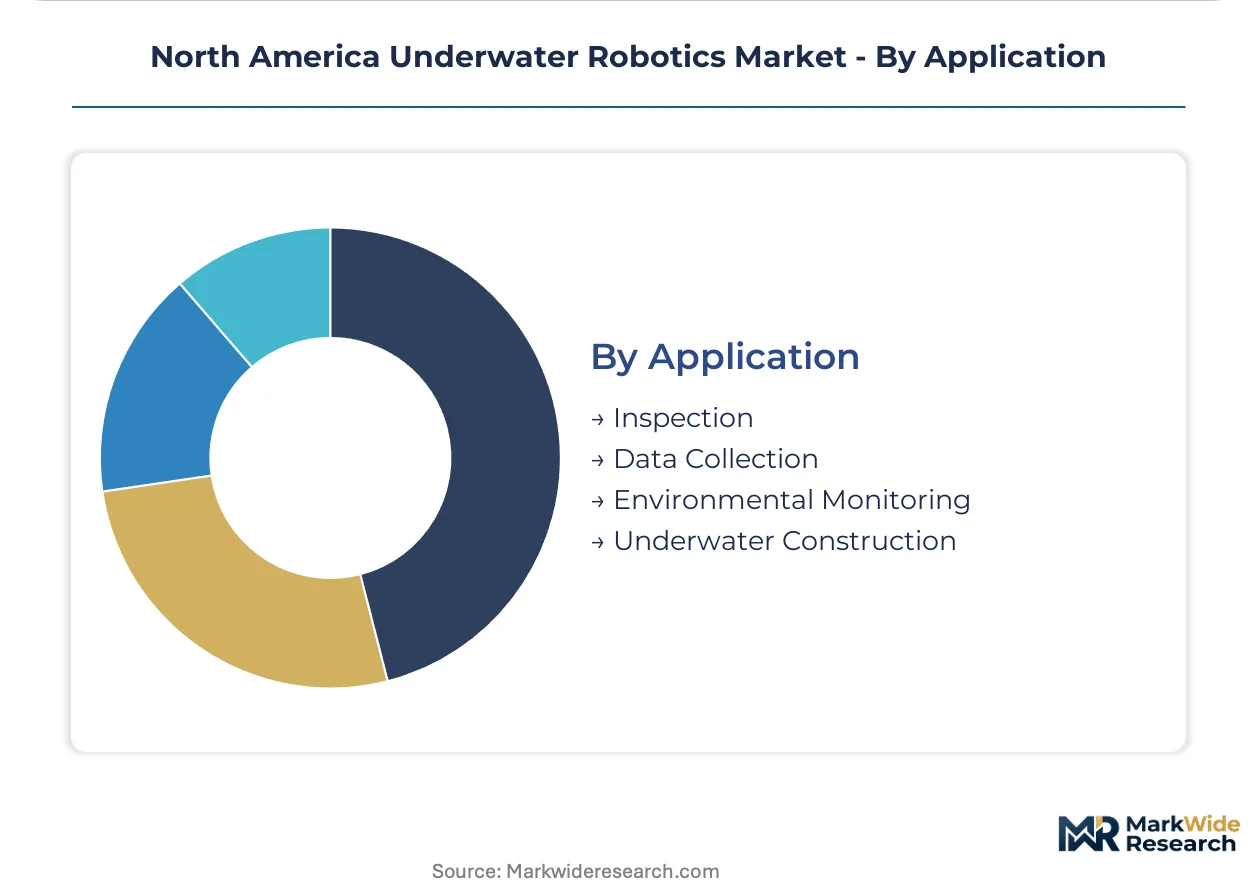
Application:
Task specificity drives platform configuration, with intervention requirements favoring tethered systems and survey tasks enabling autonomous deployment.
- Inspection:Visual and sensor-based assessment of subsea infrastructure dominates ROV utilization, with the US Bureau of Safety and Environmental Enforcement mandating specific intervals for blowout preventer verification in federal waters.
- Data Collection:Bathymetric mapping, geophysical survey, and oceanographic sampling missions favor AUV platforms for large-area coverage without surface vessel shadowing.
- Environmental Monitoring:Long-term seabed observatories and water column profiling support regulatory compliance and climate research objectives.
- Underwater Construction:Heavy-lift ROV systems execute cable burial, pipeline tie-in, and decommissioning cutting operations requiring precise manipulator control.
Inspection absorbs the greatest platform hours; Data Collection is expanding most quickly as offshore wind lease development accelerates seabed survey demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Bureau of Safety and Environmental Enforcement anchors regulatory demand across the dominant geography, with state-level procurement clusters and Canadian Arctic programs expanding the addressable footprint.
United States
Gulf of Mexico decommissioning contracts and offshore wind lease development on the Atlantic coast drive platform demand. The US Bureau of Safety and Environmental Enforcement mandates blowout preventer inspection intervals that compress ROV replacement cycles. Houston and New Orleans host the densest service provider clusters, where operators manage multi-vendor fleets across shelf and slope provinces.
Canada
Arctic seabed mapping initiatives and ice-covered research missions expand autonomous vehicle deployment. The Canadian Environmental Protection Act governs disturbance protocols for northern waters, shaping platform certification requirements. British Columbia aquaculture operations and Atlantic offshore energy provinces concentrate nearshore inspection demand in Vancouver and St. John's.
Mexico
Pemex outsourcing of subsea maintenance for mature fields creates service opportunities in the Bay of Campeche. Mexican energy reform regulations open contract bidding to international ROV operators. Ciudad del Carmen and Tampico anchor the operational infrastructure for Cantarell field support.
North America Underwater Robotics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with tier boundaries defined by fleet scale and contracting relationships. The upper tier commands multi-year service agreements with supermajor operators, while specialists compete on deployment speed and portable platform economics. Two strategic archetypes dominate: full-service contractors with integrated vessel and robotics assets, and technology-focused subsystem suppliers. Competitive moves concentrate on fleet modernization acceleration and autonomy software partnerships.
Among US-based integrated contractors, Oceaneering International and General Dynamics Mission Systems exemplify the full-service archetype, anchoring multi-decade relationships with federal and commercial customers. Teledyne Marine occupies a position as the dominant sensor and navigation subsystem supplier, with its technology extending across both ROV and AUV platform architectures.
| Leading Market Players |
|---|
| General Dynamics Mission Systems, Inc. |
| Oceaneering International, Inc. |
| Teledyne Marine |
| Deep Ocean Engineering, Inc. |
| VideoRay LLC |
| Deep Trekker Inc. |
| SeaRobotics Corp. |
| International Submarine Engineering Limited |
| Blue Robotics, Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Gulf of Mexico syntactic foam plants creates asymmetric pricing power for buoyancy material suppliers, compressing margins for ROV integrators while elevating floor prices for pressure-rated hull components. This scale concentration forces smaller inspection contractors toward commercial-off-the-shelf electronics or extended replacement cycles.
Pricing Analysis
Day-rate spreads between Houston and Vancouver service hubs exceed thirty percent for equivalent work-class ROV specifications, reflecting vessel mobilization cost differentials and union labor premiums. Three-tier pricing structure across premium, standard, and economy levels separates supermajor compliance contracts from nearshore aquaculture deployments. Cost compression in the mid-tier segment is intensifying because Pemex outsourcing is attracting low-cost Mexican operators. Nearshore fish farm contractors exhibit highest price sensitivity; defense salvage programs show least.
Supply Chain Analysis
Pressure-tolerant connector inventories at Texas distributors carry fourteen-week lead times following hurricane disruptions, forcing ROV operators into buffer stock strategies that tie up working capital. Syntactic foam production concentrates in Texas and Louisiana; sensor subsystem fabrication draws from California and Massachusetts. Lithium-ion cell supply rests on South Korean and Japanese chemistry suppliers. Single-source vulnerability sits with deep-rated buoyancy material formulations. Distribution runs through Houston and New Orleans port logistics clusters to offshore support vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bifurcation between legacy ROV pilot-technicians and AI-fluent autonomy engineers constrains fleet modernization velocity for operators lacking internal training infrastructure. This skills gap rewards early capability builders and penalizes laggards.
For Market Incumbents: Secure exclusive teaming agreements with offshore wind developers along the US Atlantic coast before cable burial verification contracts consolidate under fewer service providers. Anchor long-term syntactic foam supply commitments with Texas and Louisiana manufacturers to preempt hurricane-related shortages. Lock in autonomy software partnerships with navigation subsystem suppliers to accelerate adaptive mission replanning deployment ahead of regulatory mandates.
For New Entrants and Emerging Players: Portable battery-powered inspection systems for nearshore aquaculture and offshore wind scour monitoring represent the most penetrable white-space where legacy operators under-serve on deployment speed. Target British Columbia and Maine fish farm operators with Spanish-language service capabilities to build operational credibility before approaching Pemex outsourcing opportunities. Lead with rapid mobilization guarantees rather than depth ratings to differentiate from established work-class ROV contractors.
For Investors and Strategic Acquirers: Navigation autonomy software boutiques with proven SLAM-based obstacle avoidance algorithms offer the highest acquisition value given defense and commercial demand convergence. Long-term viability hinges on dual-use technology transfer velocity from Navy prototype contracts to commercial service applications. Watch for FAA-maritime regulator coordination milestones on aerial-underwater hybrid platforms as inflection indicators for cross-domain system clearance timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomy Software Acquisition | SLAM-based navigation capabilities from defense contractors accelerate commercial ROV fleet modernization timelines. |
| Arctic Certification Investment | Canadian Environmental Protection Act compliance for ice-covered operations opens autonomous survey contract access. |
| Offshore Wind Partnership | Atlantic coast lease developers require cable burial verification combining ROV intervention with persistent monitoring. |
| Syntactic Foam Backward Integration | Captive buoyancy material production insulates against hurricane-related supply disruptions in Gulf of Mexico. |
| Mexican Energy Reform Access | Pemex outsourcing for Cantarell field maintenance creates first-mover advantages for Spanish-capable operators. |
Research Methodology
Desk research of BSEE regulatory filings, US Navy Unmanned Maritime Systems program documentation, and Canadian Environmental Protection Act disturbance protocols preceded structured interviews with ROV fleet managers, subsea engineering directors, offshore wind procurement leads, and autonomy software developers. Secondary validation drew from SEC 10-K disclosures of integrated service contractors, customs records for pressure-rated electronics imports, and offshore support vessel utilization databases. Bottom-up platform deployment counts and top-down service contract value estimates were triangulated to anchor market sizing.
Variance decomposition across platform architecture, end-use vertical, and navigation technology maturity shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include tether status, depth rating tier, and autonomy software integration level. CAGRs were derived from replacement cycle compression effects and offshore wind lease auction timelines. Forecast inputs incorporated BSEE inspection interval mandates and Navy prototype contract award patterns.
Underlying assumptions cover regulatory enforcement continuity, lithium-ion energy density improvement trajectories, and Gulf of Mexico decommissioning schedule adherence, with deviation risk concentrated in FAA-maritime coordination delays and hurricane frequency impacts on syntactic foam production. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market