
 Agricultural Robots Market | 2026-2036
Agricultural Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Robots Market Intelligence
Chinese drone manufacturers is decoupling from Western GPS dependency by deploying BeiDou-native navigation stacks at scale. DJI leverages its consumer UAV manufacturing base to dominate agricultural spraying robot volumes across Asia. Deere & Company anchors its competitive position through proprietary precision agriculture software integrated with its autonomous tractor hardware. Trimble Inc. specializes in RTK-GPS correction networks that extend robot accuracy to sub-inch levels for row-crop operations.
Agricultural robots encompass autonomous ground vehicles and aerial systems engineered for mechanized crop production, typically integrating GNSS positioning, multispectral cameras, and actuated implements to execute soil preparation, planting, treatment, or harvesting tasks with minimal human intervention. Machine learning algorithms process terabytes of field imagery to generate prescription maps that optimize input application rates down to individual plant zones. Autonomous tractors and drones currently occupy the largest value share within robot type segmentation, while weeding robots represent the fastest-expanding category as herbicide resistance spreads and labor costs climb. GPS navigation and computer vision form the technology backbone, though sensor fusion architectures are displacing single-modality systems in premium equipment tiers.
The EPA governs aerial application rates and chemical drift thresholds that directly constrain drone payload specifications and flight planning algorithms in the United States. The EU Green Deal and F-Gas Regulation jointly pressure manufacturers to eliminate hydraulic systems and synthetic refrigerants from autonomous harvester designs. China's MIIT enforces data-localization requirements for agricultural IoT platforms, shaping cloud architecture decisions for robot fleet management systems deployed in its domestic market. Stakeholders must weigh regulatory fragmentation against platform standardization when allocating R&D budgets across geographies.
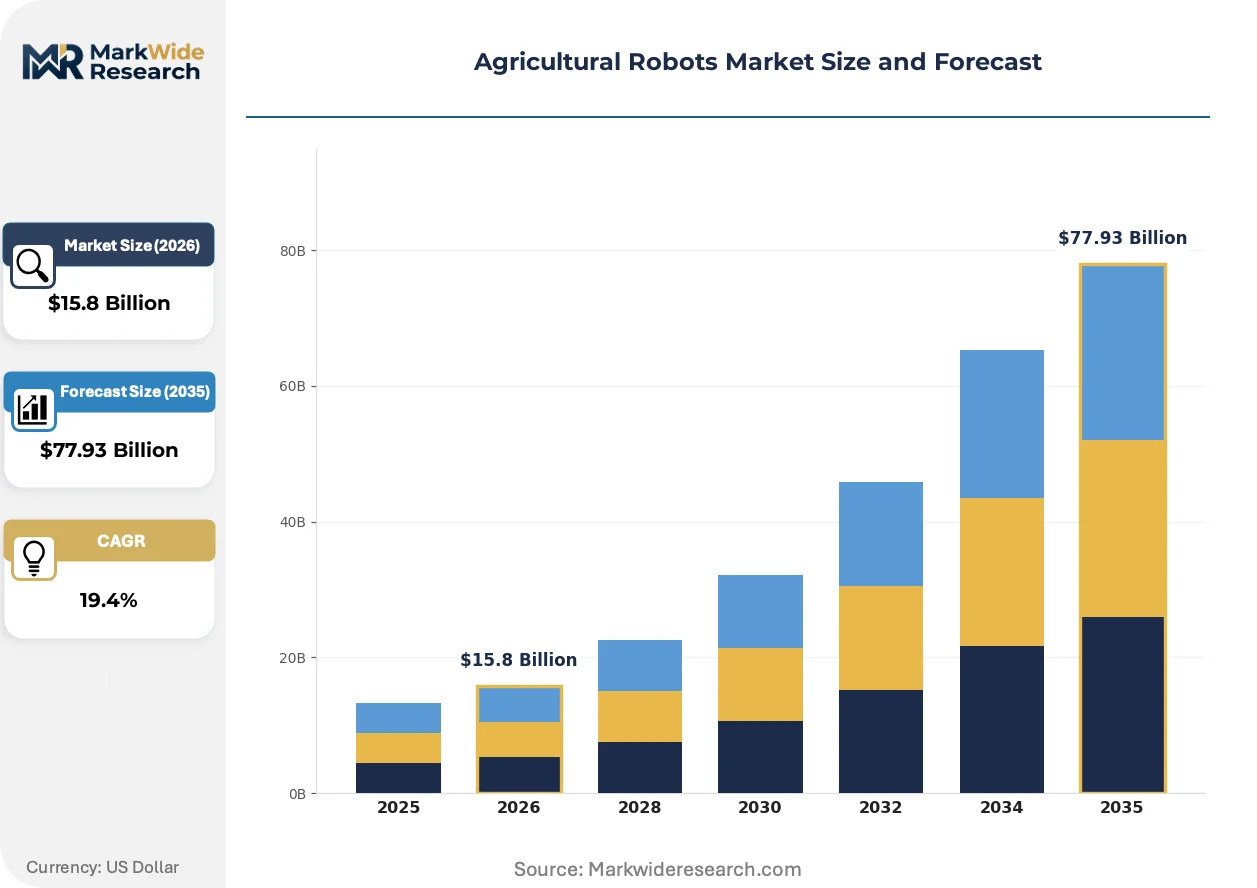
Market Dynamics
Labor shortages across commercial farming operations are forcing accelerated capital deployment into autonomous systems, with fleet-scale robot adoption now treated as operational necessity rather than experimental investment.
Growth Catalysts
- EU Farm to Fork Strategy:Binding chemical reduction targets for member states are mandating precision application equipment, creating regulatory pull for variable-rate spraying robots in arable farming.
- Multispectral imaging:Sensor costs below critical thresholds are enabling plant-level health monitoring, allowing prescription agriculture to scale from research plots to thousand-hectare operations.
- BeiDou navigation infrastructure:China's completed satellite constellation is eliminating GPS dependency for domestic drone fleets, accelerating procurement in Heilongjiang and Jilin grain provinces.
Market Restraints
- Lithium battery supply concentration:Cell production gravity in East Asian manufacturing clusters exposes Western OEMs to raw material cost volatility and export control risks.
- RTK-GPS correction network gaps:Sub-inch accuracy requires dense ground station infrastructure that remains uneven outside Midwest US corn belts and North European plains.
- CE marking complexity:Machinery Directive compliance for autonomous navigation systems demands extensive third-party certification, extending European market entry timelines.
Strategic Opportunities
- Brazilian soybean belt:Underpenetrated autonomous harvesting in Mato Grosso and Goiás offers first-mover advantage as labor costs converge with North American levels.
- Outcome-based spraying contracts:Chemical manufacturers are piloting robot-as-a-service models where equipment suppliers guarantee application efficacy, transferring agronomic risk.
- Sensor-ML convergence:Edge computing on implements is enabling real-time weed classification without cloud latency, opening closed-loop spot-treatment for specialty crops.
Industry Challenges
- Mechatronics talent scarcity:Agricultural equipment manufacturers compete with automotive and aerospace for embedded systems engineers capable of field-hardening autonomous navigation.
- Legacy fleet integration:Mixed-age tractor populations on commercial farms complicate unified fleet management software deployment, requiring expensive retrofit kits or parallel operating systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Robots Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $77.93 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Autonomous Tractors, Drones, Harvesters, Weeders, Planters Technology: GPS Navigation, Computer Vision, Lidar, Machine Learning, Sensor Fusion Application: Crop Monitoring, Precision Seeding, Pest Control, Soil Analysis, Irrigation Management End User: Commercial Farms, Greenhouses, Research Farms, Agricultural Contractors, Horticulture Specialists |
| Companies Covered | DJI, Trimble Inc., Deere & Company, Autonomous Solutions, Inc., Raven Industries, AGCO Corporation, Lely, Topcon Positioning Systems, CNH Industrial NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Robots Market Strategic Shifts & Innovations
Hardware-software decoupling is restructuring competitive boundaries, with specialized perception modules and autonomous stacks now licensable across OEM platforms rather than captive to single manufacturers.
Sensor fusion architectures are modularizing perception systems for agricultural robots, combining LiDAR, radar, and thermal imaging into standardized compute enclosures. Large row-crop operators in Iowa and Illinois are specifying these interchangeable modules to reduce single-vendor lock-in. Equipment manufacturers are modularizing their product lines to accommodate third-party perception stacks without redesigning chassis or powertrain systems.
The EPA's updated aerial application drift regulations are constraining drone payload capacities and mandating buffer zone algorithms in flight planning software. Chemical manufacturers must reformulate active ingredients for lower-volume application rates compatible with restricted UAV tank sizes. Specialty crop growers in California's Central Valley are responding by consolidating spray windows and negotiating indemnification clauses with robot service providers.
Cooperative purchasing agreements among mid-scale farms are consolidating equipment procurement decisions into regional buying pools. Traditional dealership networks in the US Corn Belt are losing influence to direct manufacturer relationships and peer-to-peer equipment sharing platforms. This concentration is most visible in Nebraska and Kansas, where farmer-owned cooperatives now specify autonomous tractor performance benchmarks in collective tender documents.
Agricultural Robots Market Segmentation
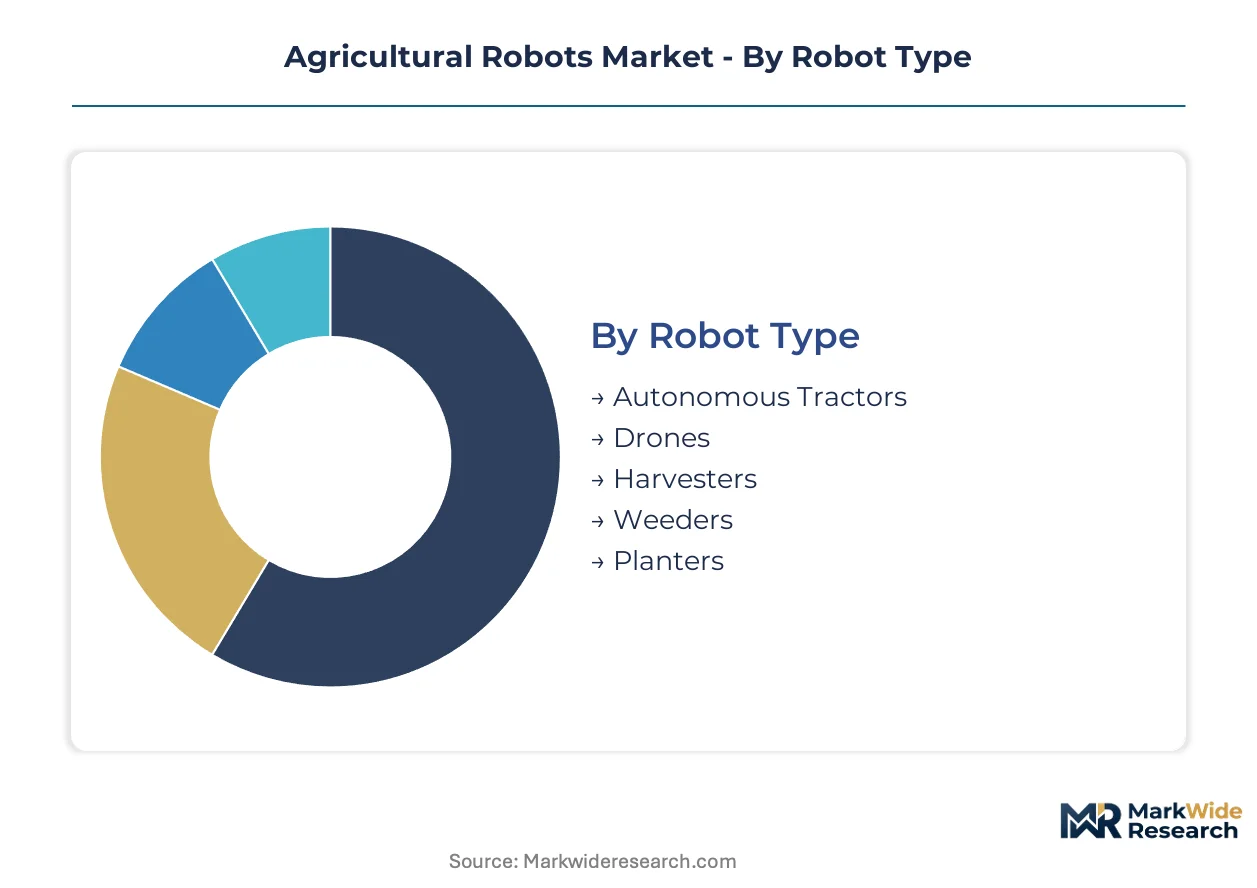
Equipment buyers prioritize task-specific performance benchmarks over universal platforms, driving divergence between aerial and ground-based robot architectures. Segmentation reveals how procurement decisions cluster around labor substitution economics, chemical reduction mandates, and precision agriculture maturity across farm types.
Robot Type:
Capital allocation intensity varies sharply by operational scale, with row-crop enterprises favoring heavy iron and specialty growers selecting nimble autonomous units.
- Autonomous Tractors:Diesel-electric hybrid powertrains with GNSS-guided implement control dominate large-scale soil preparation and cultivation. Fleet procurement in Iowa and Illinois concentrates on 300+ horsepower units capable of 24-hour continuous operation during narrow planting windows.
- Drones:Multirotor and fixed-wing aerial platforms carry multispectral sensors and variable-rate spray payloads for plant-level intervention. Heilongjiang grain provinces in China deploy BeiDou-native navigation stacks at scale, eliminating Western GPS dependency for domestic procurement.
- Harvesters:Cereal and specialty crop variants integrate yield mapping with real-time moisture sensing for automated cut-height adjustment.
- Weeders:Computer-vision-guided mechanical and thermal elimination systems target herbicide-resistant populations in organic and conventional operations.
- Planters:Precision seeding robots execute singulation and depth control at speeds exceeding manual planter benchmarks.
Volume sits with autonomous tractors; growth tilts toward weeders.
Technology:
Accuracy requirements and cost thresholds determine technology stacking decisions, with premium tiers pursuing sensor fusion and value tiers accepting single-modality navigation.
- GPS Navigation:RTK-corrected positioning delivers sub-inch accuracy for row-crop operations, though ground station density gaps persist outside Midwest US corn belts and North European plains.
- Computer Vision:Convolutional neural networks process field imagery for plant detection, disease identification, and navigation obstacle avoidance. Edge deployment on implements enables real-time weed classification without cloud latency, opening closed-loop spot-treatment for specialty crops.
- Lidar:Point-cloud mapping generates 3D terrain models for autonomous path planning in orchards and vineyards with complex canopy structures.
- Machine Learning:Prescription algorithms optimize input application rates down to individual plant zones using terabytes of accumulated field imagery.
- Sensor Fusion:LiDAR-radar-thermal combinations modularize into standardized compute enclosures, reducing single-vendor lock-in for large row-crop operators.
Revenue concentrates in GPS navigation; sensor fusion claims the steepest expansion trajectory.
Application:
Task economics and regulatory constraints shape application prioritization, with chemical-use restrictions elevating precision treatment workflows.
- Crop Monitoring:Multispectral and thermal imaging generate plant health indices for irrigation and nutrient stress detection. Sensor cost thresholds below critical levels enable thousand-hectare deployment from prior research-plot limitation.
- Precision Seeding:Variable-rate planting algorithms adjust population density based on soil productivity zones mapped via electrical conductivity and yield history.
- Pest Control:Autonomous spraying robots execute variable-rate application mandated by EU Farm to Fork Strategy chemical reduction targets.
- Soil Analysis:Mobile probes and in-situ sensors map pH, organic matter, and macronutrient distribution for targeted amendment.
- Irrigation Management:Moisture-sensor-driven valve control and pivot automation reduce water consumption in drought-prone growing regions.
Deployment frequency favors crop monitoring; regulatory pressure accelerates pest control adoption fastest.
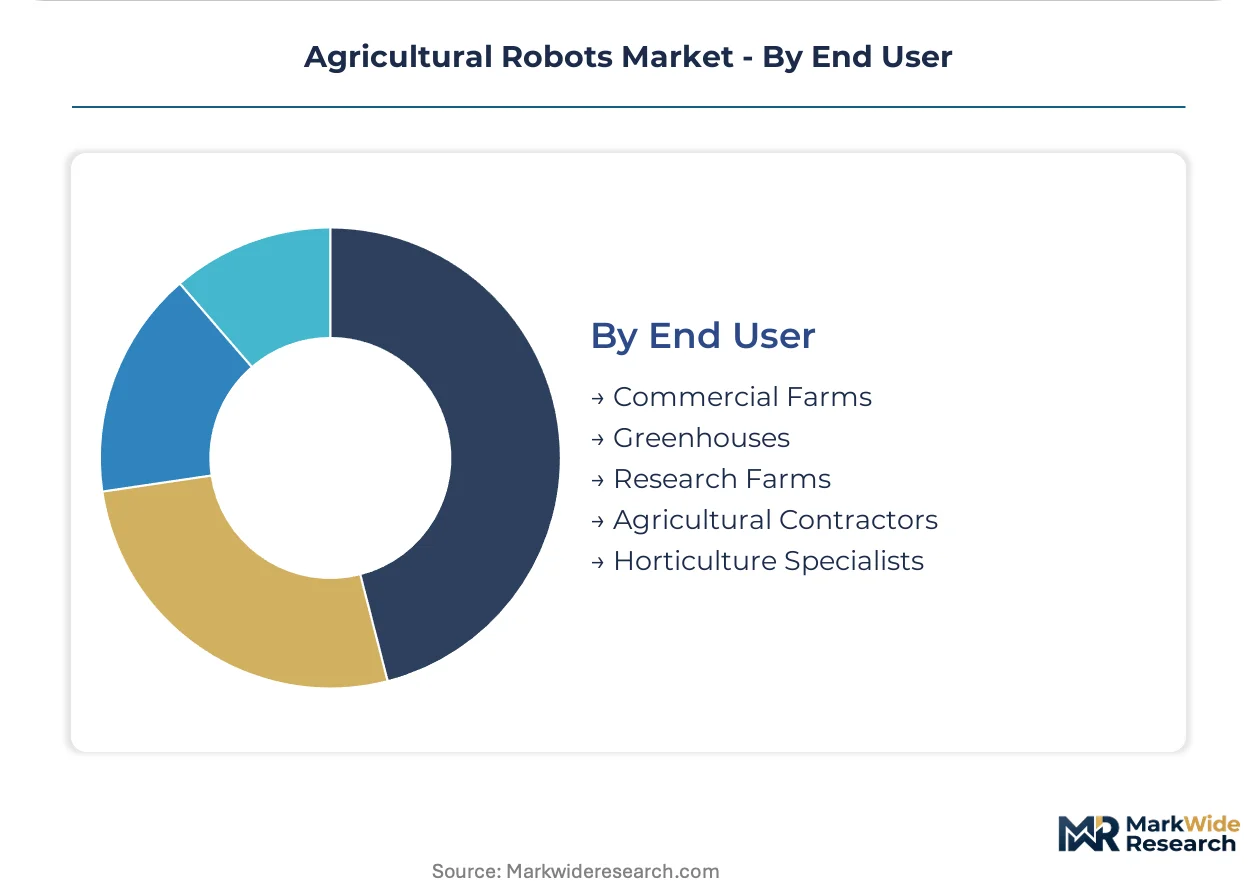
End User:
Operational sophistication and capital access stratify end-user segments, with cooperative purchasing consolidating mid-scale farm procurement decisions.
- Commercial Farms:Row-crop and broadacre operations deploy fleet-scale autonomous systems as operational necessity amid intensifying labor shortages. Nebraska and Kansas farmer-owned cooperatives now specify autonomous tractor performance benchmarks in collective tender documents.
- Greenhouses:Controlled-environment agriculture employs robotic transplanting, harvesting, and climate management in high-value vegetable and ornamental production.
- Research Farms:University and government experimental stations pilot next-generation perception and manipulation technologies prior to commercial field-hardening.
- Agricultural Contractors:Service providers offer robot-as-a-spray contracts where equipment suppliers guarantee application efficacy, transferring agronomic risk from growers.
- Horticulture Specialists:Tree fruit, vine, and nursery operations select compact autonomous platforms for tasks incompatible with conventional tractor geometry.
Capital deployment dominates commercial farms; horticulture specialists expand platform adoption most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium cell manufacturing gravity in East Asian industrial clusters anchors supply-side configuration, while precision agriculture demand concentrates in mechanized farming belts across three continents.
United States
Commercial row-crop operators in Iowa and Illinois deploy 300+ horsepower autonomous tractors for 24-hour planting windows. The EPA governs aerial application rates and chemical drift thresholds that constrain drone payload specifications and flight planning algorithms. Nebraska and Kansas farmer-owned cooperatives now specify autonomous tractor performance benchmarks in collective tender documents.
China
Heilongjiang and Jilin grain provinces concentrate procurement of agricultural drones at scale. The MIIT enforces data-localization requirements for agricultural IoT platforms, shaping cloud architecture decisions for robot fleet management systems. DJI leverages its consumer UAV manufacturing base to dominate agricultural spraying robot volumes across Asia.
Germany
Premium equipment manufacturers anchor precision agriculture development for arable farming operations. The EU Green Deal and F-Gas Regulation jointly pressure manufacturers to eliminate hydraulic systems and synthetic refrigerants from autonomous harvester designs. Bavaria-based engineering clusters specialize in sensor fusion architectures for row-crop automation.
Brazil
Mato Grosso and Goiás soybean belts present underpenetrated autonomous harvesting opportunities as labor costs converge with North American levels. ANVISA regulates agricultural chemical formulations that drone spraying robots must accommodate. Regional equipment distributors in the Cerrado biome pilot robot-as-a-service contracts for variable-rate application.
Netherlands
Greenhouse robotics for controlled-environment agriculture commands premium positioning in high-value vegetable production. CE marking complexity under the Machinery Directive demands extensive third-party certification for autonomous navigation systems. Wageningen University research corridors pilot next-generation perception technologies prior to commercial field-hardening.
Agricultural Robots Market Key Industry Players
Global majors compete with regional champions across precision agriculture software and hardware integration, producing a tiered structure where full-line manufacturers anchor premium positioning while specialized perception vendors modularize across OEM platforms. Three archetypes dominate: integrated tractor-and-software stacks, GNSS correction network specialists, and aerial platform volume leaders. Competitive moves concentrate on strategic partnerships for sensor fusion licensing and geographic expansion into underpenetrated soybean belts.
Within the integrated-equipment tier, Deere & Company and CNH Industrial NV represent full-line manufacturers combining autonomous hardware with proprietary precision agriculture software. DJI occupies the aerial-platform volume position, leveraging consumer UAV manufacturing scale for agricultural spraying dominance. Trimble Inc. exemplifies the GNSS-specialist archetype, delivering RTK correction networks that extend robot accuracy to sub-inch levels for row-crop operations.
| Leading Market Players |
|---|
| DJI |
| Trimble Inc. |
| Deere & Company |
| Autonomous Solutions, Inc. |
| Raven Industries |
| AGCO Corporation |
| Lely |
| Topcon Positioning Systems |
| CNH Industrial NV |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's phased elimination of hydraulic systems and synthetic refrigerants from autonomous harvester designs gates qualified supply and premium-tier pricing access. Equipment manufacturers absorbing redesign costs for compliant powertrain architectures pass through tiered premiums to buyers seeking CE-marked autonomous navigation systems, while non-compliant OEMs face exclusion from European procurement channels.
Pricing Analysis
Extended warranty and predictive maintenance bundling separates premium autonomous tractor offerings from hardware-only transactions in North American row-crop markets. Three-tier pricing structure across premium sensor-fusion platforms, standard GPS-guided systems, and economy retrofit kits reflects certification grade and after-sales service depth. Cost compression in economy tiers intensifies as Chinese drone manufacturers scale BeiDou-native navigation stacks for Asian grain provinces. Specialty crop operators in California's Central Valley exhibit highest price sensitivity due to compressed operating margins, while Midwest commercial farms prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Mechatronics talent scarcity in German and Japanese precision manufacturing hubs constrains production scaling for sensor fusion modules and autonomous navigation compute enclosures. Lithium cell production draws from Chinese, South Korean, and Japanese manufacturing clusters, with raw material feedstock anchored in Chilean and Australian mining operations. Single-source vulnerability in rare earth magnet supply for electric drivetrains exposes Western OEMs to export control risks. Distribution runs through traditional dealership networks in the US Corn Belt, though direct manufacturer relationships and farmer-owned cooperative purchasing pools are consolidating procurement decisions in Nebraska and Kansas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Farm to Fork Strategy's binding chemical reduction targets erect a compliance moat that favors precision spraying robot manufacturers with established variable-rate application certifications. This regulatory barrier-to-entry structure rewards early investment in CE-marked autonomous navigation systems while marginalizing hardware-only vendors lacking integrated prescription agriculture software.
For Market Incumbents: Deepen proprietary precision agriculture software integration with autonomous tractor hardware to defend against modular perception vendors licensing across OEM platforms. Anchor competitive position through captive RTK-GPS correction network infrastructure in Midwest US corn belts, while accelerating sensor fusion R&D to offset mechatronics talent scarcity threatening field-hardening timelines.
For New Entrants and Emerging Players: Enter via underpenetrated autonomous harvesting opportunities in Brazil's Mato Grosso and Goiás soybean belts, where labor cost convergence with North American levels creates first-mover conditions. Target agricultural contractor segments with robot-as-a-service contracts that transfer agronomic risk from growers, leveraging outcome-based spraying guarantees as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Cooperative purchasing consolidation among Nebraska and Kansas farmer-owned cooperatives is the leading indicator that regional buying pools will reshape equipment procurement economics. Acquisition focus should center on modular perception stack vendors with licensable LiDAR-radar-thermal architectures, as hardware-software decoupling restructures competitive boundaries across the projection horizon.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Module Licensing | Modular perception stacks reduce single-vendor lock-in for Iowa and Illinois row-crop operators. |
| RTK-GPS Network Expansion | Dense ground station infrastructure extends sub-inch accuracy beyond Midwest corn belt boundaries. |
| BeiDou-Native Navigation Deployment | Chinese grain provinces eliminate Western GPS dependency for domestic drone fleet procurement. |
| Outcome-Based Spray Contracts | Chemical manufacturers transfer agronomic risk to equipment suppliers via efficacy guarantees. |
| CE Marking Pathway Investment | Machinery Directive compliance accelerates European market entry for autonomous navigation systems. |
Research Approach
Trade publications, customs databases, and equipment manufacturer SEC filings formed the secondary backbone, cross-referenced against primary interviews with precision agriculture software directors, autonomous systems engineers at OEMs, and procurement leads at Midwest commercial farming cooperatives. Bottom-up triangulation aggregated unit shipment data across robot type categories, while top-down validation anchored aggregate market sizing against regional agricultural machinery trade flows.
Historical trendline analysis of autonomous tractor and drone deployment densities informed penetration curve modeling across the projection horizon. Segmentation dimensions spanned robot type, navigation technology tier, application workflow, and end-user operational scale. CAGRs derived from fitted growth curves incorporating lithium battery cost trajectories, labor shortage intensity indices, and regulatory compliance timeline assumptions specific to EU Farm to Fork Strategy implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation affecting rare earth magnet supply and sudden EPA aerial application drift regulation revisions. A small set of named triggers warrants ongoing watch: MIIT data-localization enforcement intensity in Chinese agricultural IoT platforms, ANVISA chemical formulation rulings impacting Brazilian drone spraying specifications, and F-Gas Regulation phase-out acceleration affecting autonomous harvester thermal management system redesign costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
Gantry Industrial Robots Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Latin America Autonomous Mobile Robot Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Collaborative Robots Market
Robotics and Automation
Healthcare Assistive Robot Market