
 Germany Car Rental Market | 2026-2036
Germany Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Car Rental Market Analysis
Airport counter networks and downtown satellite locations are reshaping how rental inventory reaches customers in Germany. SIXT leverages its premium positioning to dominate urban centers and major transport hubs. Buchbinder competes through aggressive price positioning in the mid-market segment. Europcar International sustains broad coverage across secondary cities and regional airports.
Germany car rental denotes a service industry supplying temporary vehicle access through fixed-term contracts, typically governed by mileage allowances, insurance bundles, and fuel policies. Fleet composition increasingly incorporates battery-electric vehicles to satisfy corporate sustainability mandates and KBA emissions protocols. Short-term rental and long-term rental represent the core revenue pillars, with the former capturing tourist and business traveler flows while the latter absorbs corporate fleet outsourcing demand. Luxury rentals occupy a narrower but higher-margin niche serving executive travel and event-driven consumption.
KBA vehicle-type approval requirements, EU Green Deal fleet electrification targets, and German commercial leasing tax frameworks collectively dictate fleet investment cycles and operator profitability. These regulations compress diesel vehicle residual values while accelerating capital commitments to electric platforms. Stakeholders must monitor charging infrastructure density along corridor routes and assess residual value risk on electrified fleet segments before committing to procurement schedules.
Market Dynamics
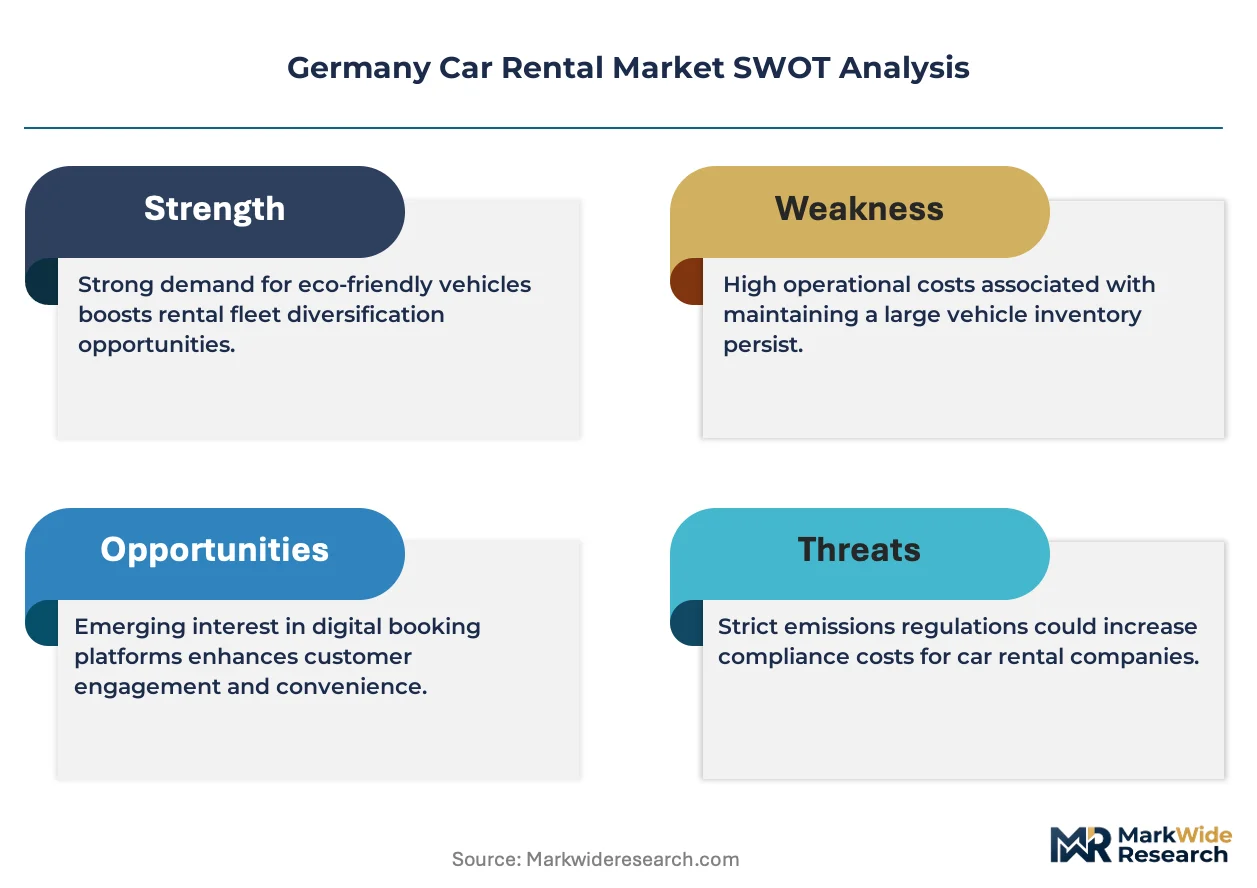
KBA fleet-average CO2 mandates are compressing diesel residual values while forcing rental operators into accelerated electrification cycles. This regulatory pressure reshapes capital allocation, procurement timing, and geographic fleet distribution across German urban corridors.
Growth Catalysts
- EU Green Deal fleet targets:Binding electrification quotas for commercial fleets push rental operators toward battery-electric procurement. Corporate clients now mandate zero-emission vehicle shares in outsourcing contracts.
- Corporate fleet outsourcing:German enterprises are shedding owned vehicle assets in favor of operational leases. This transfers maintenance burden and residual risk to rental providers while stabilizing long-term revenue streams.
- Autobahn charging corridors:Federal infrastructure investment along major transport axes reduces range anxiety for electric rental customers. Munich-Stuttgart and Berlin-Hamburg routes now support intercity EV mobility.
Market Restraints
- Residual value compression on diesel stock:KBA emissions protocols and city entry bans erode secondary market prices for internal combustion fleet. Operators face accelerated depreciation schedules on legacy assets.
- Battery supply concentration:European cell manufacturing capacity lags procurement demand, creating dependency on Asian suppliers. Delivery timelines for electric fleet stretch 12-18 months.
- Charging infrastructure asymmetry:Rural and eastern German regions lack sufficient fast-charging density. This limits electric fleet deployment outside Berlin, Munich, and Hamburg metropolitan zones.
Strategic Opportunities
- Last-mile logistics electrification:E-commerce fulfillment demand in Bavaria and North Rhine-Westphalia creates appetite for small commercial EV rentals. Urban delivery operators seek flexible electric van access without ownership.
- Corporate mobility budgets:German tax frameworks incentivize employer-funded mobility allowances over company car provision. Rental operators can capture this spend through subscription-based vehicle access models.
- Intermodal station integration:Deutsche Bahn hub development at Frankfurt, Cologne, and Düsseldorf main stations positions rental counters at rail-air interchange points. This captures arriving business travelers before they reach airport facilities.
Industry Challenges
- Technician certification for high-voltage systems:Electric fleet maintenance requires specialized training that traditional mechanical workforces lack. Rental operators must fund upskilling programs or outsource to manufacturer-authorized service networks.
- Telematics platform integration:Legacy reservation and fleet management systems require costly retrofitting to support real-time battery state monitoring, charging station routing, and dynamic pricing for electric assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Car Rental Market |
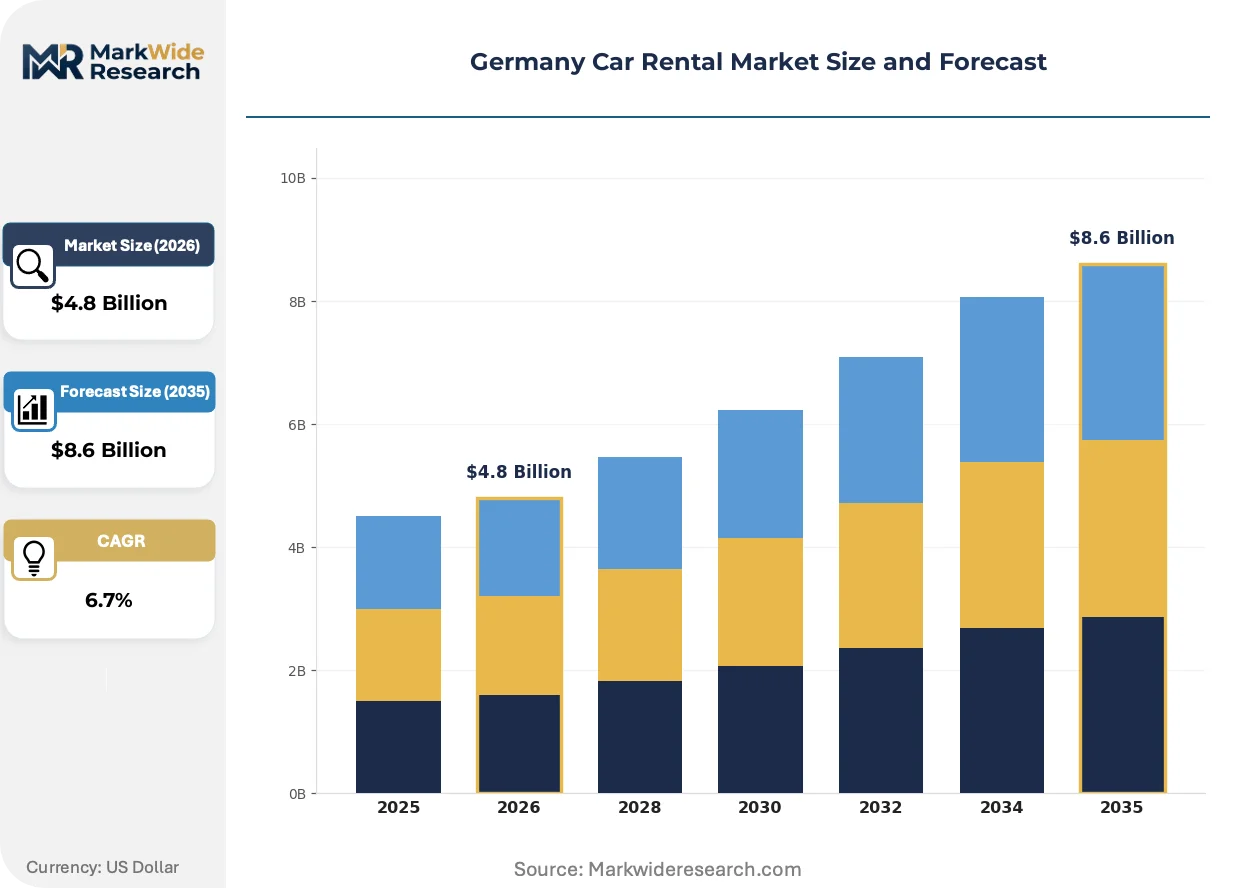
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Long-Term Rental, Short-Term Rental, Car Sharing, Luxury Rentals Customer Type: Tourists, Business Travelers, Corporate Clients, Local Residents Vehicle Type: Economy Cars, SUVs, Vans, Luxury Vehicles Booking Channel: Online Platforms, Mobile Apps, Travel Agencies, Direct Booking |
| Companies Covered | Enterprise Holdings, Buchbinder, Avis Budget Group, Mercedes-Benz Group AG, Volkswagen AG, SIXT, Hertz, Bayerische Motoren Werke AG, Europcar International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Car Rental Market Emerging Trajectories
Digital fleet management platforms and connected vehicle architectures are transforming how German rental operators optimize utilization, pricing, and customer touchpoints. Three developments merit particular attention.
Telematics-enabled predictive maintenance is migrating from aftermarket add-ons to factory-integrated standard equipment. Fleet managers now receive real-time diagnostics on brake wear, tire pressure, and battery health before vehicles return to depot. This compresses unplanned downtime and extends asset service intervals. The technology is migrating from premium fleet segments toward mid-market economy rentals as OEMs bundle connectivity in base configurations.
German KBA type-approval requirements for software-defined vehicles impose new compliance burdens on imported fleet. OTA update capabilities must demonstrate cybersecurity resilience and functional safety before registration. This delays introduction of certain non-European electric models and favors established suppliers with existing homologation expertise. Rental procurement teams now prioritize platforms with proven KBA certification timelines.
Subscription-based mobility access is displacing traditional daily-rate structures among younger German corporate travelers. Flat monthly fees covering insurance, maintenance, and vehicle swaps appeal to project-based consultants and rotational staff. This model concentrates demand in Berlin and Hamburg where housing and workplace proximity reduce mileage requirements. Providers offering 30-day minimum terms with mid-contract vehicle exchanges capture this segment from conventional short-term rental counters.
Germany Car Rental Market Segmentation
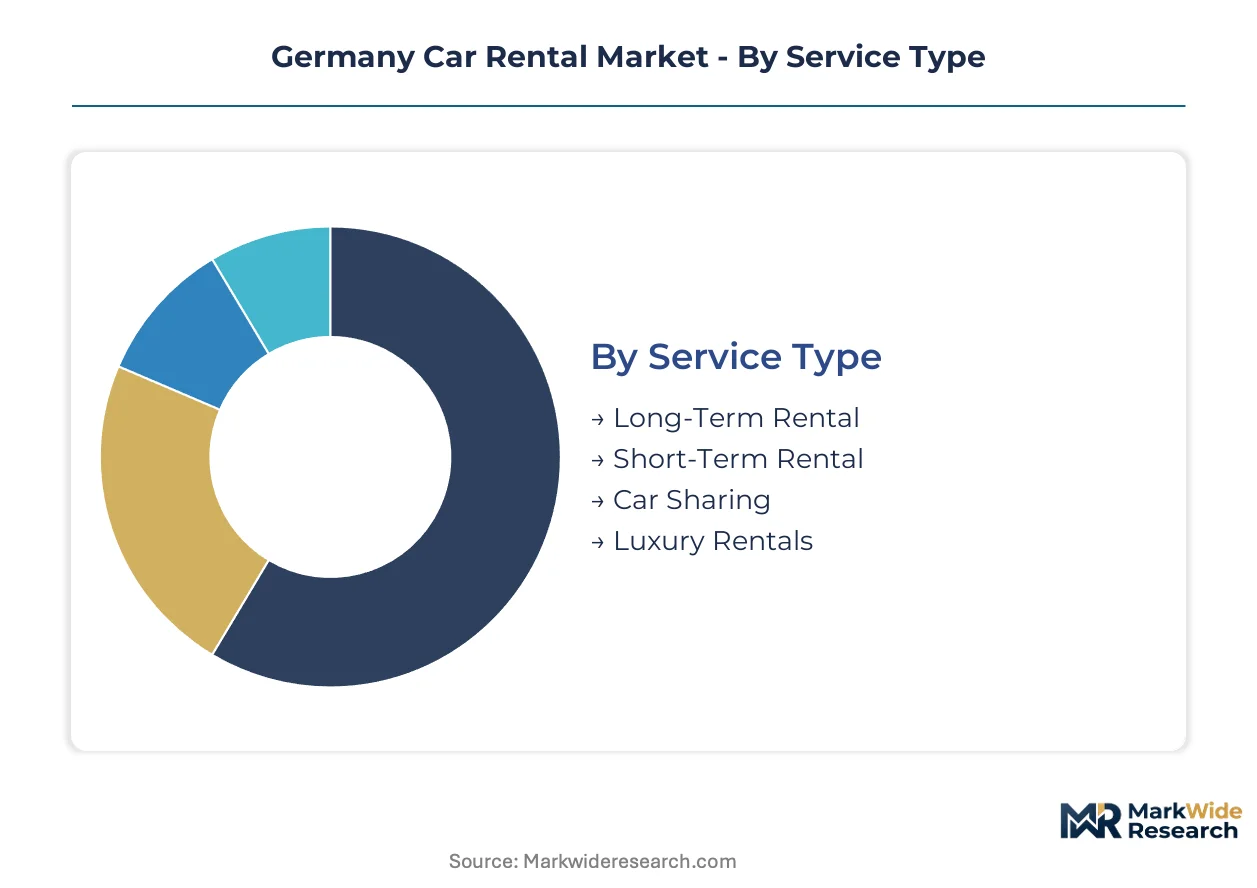
German rental operators structure fleet and pricing around distinct usage patterns that separate airport tourism flows from corporate mobility programs. Segmentation discipline determines capital allocation between electric vehicle platforms and residual-risk diesel stock.
Service Type:
Service type segmentation traces the use-case spectrum from single-day tourism to multi-year corporate fleet outsourcing.
- Long-Term Rental:Contracts span 12-36 months with fixed monthly rates covering maintenance, insurance, and registration. Corporate clients in Stuttgart and Frankfurt manufacturing corridors favor this structure for sales force mobility.
- Short-Term Rental:Daily or weekly agreements dominate airport counters and downtown locations serving inbound business travelers. Berlin Tegel and Munich Franz Josef Strauß terminals generate the highest transaction density.
- Car Sharing:Minute-based billing through smartphone unlock appeals to urban residents in Hamburg and Cologne who reject vehicle ownership. Fleet utilization peaks during weekday commuting windows.
- Luxury Rentals:Premium sedans and performance vehicles serve executive roadshows and event-driven consumption in Düsseldorf's fashion and media districts.
The dominant share belongs to Long-Term Rental, while Car Sharing is closing the gap fastest.
Customer Type:
Customer segmentation follows procurement authority and trip purpose rather than demographics alone.
- Corporate Clients:Fleet managers negotiate enterprise agreements with sustainability clauses mandating electric vehicle minimums. KBA emissions protocols drive contract renegotiation cycles.
- Business Travelers:Individual road warriors book through employer-negotiated rate codes at airport facilities. Munich and Berlin generate the highest per-capita spending.
- Tourists:International visitors prioritize compact automatic vehicles for Autobahn cruising and Black Forest touring routes.
- Local Residents:Substitution demand spikes when personal vehicles require repair or during relocation periods in dense urban districts.
Corporate Clients command the largest revenue pool, though Business Travelers deliver the steepest expansion trajectory.
Vehicle Type:
Vehicle classification determines depreciation schedules and charging infrastructure requirements across German operator networks.
- Economy Cars:Compact hatchbacks and sedans dominate short-term rental pools with lowest acquisition cost and highest turnover frequency.
- SUVs:Mid-size crossovers satisfy family tourism and executive preferences for elevated seating position on extended Autobahn journeys.
- Vans:Commercial configurations serve last-mile logistics operators in North Rhine-Westphalia e-commerce corridors seeking flexible capacity without ownership burden.
- Luxury Vehicles:Premium German marques occupy narrow fleet share but generate disproportionate margin per rental day in financial and professional services segments.
Economy Cars retain volume leadership, though Vans are climbing the fastest on logistics electrification demand.
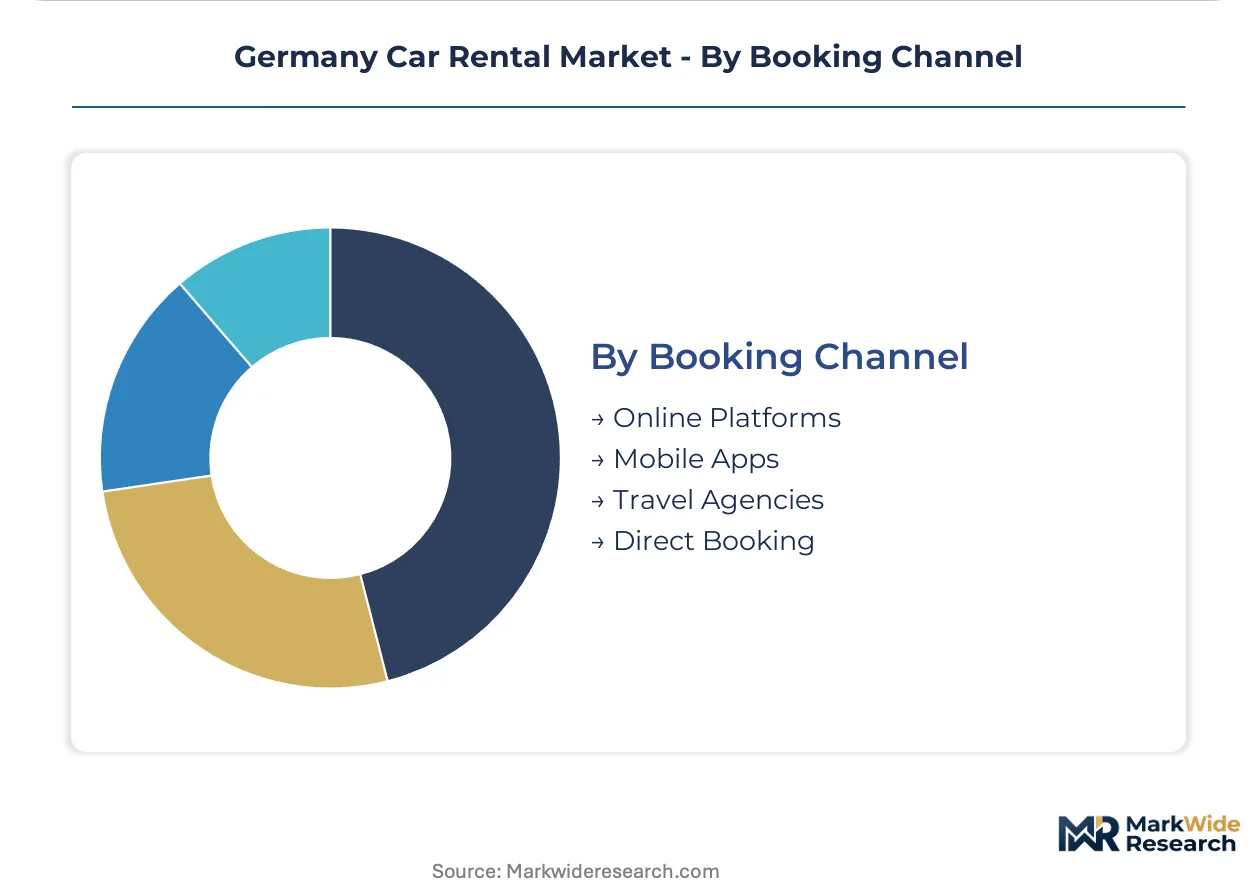
Booking Channel:
Channel mix reflects technology adoption curves and corporate travel policy enforcement across German enterprises.
- Online Platforms:Aggregator websites enable price comparison and instant confirmation for leisure travelers planning ahead.
- Mobile Apps:Smartphone-native booking with digital key integration captures younger demographics and spontaneous demand in urban centers.
- Travel Agencies:Traditional intermediaries retain relevance for complex multi-city itineraries and inbound tourism packages.
- Direct Booking:Operator-owned websites and loyalty programs bypass commission structures while capturing repeat corporate accounts.
Online Platforms maintain the widest reach, yet Mobile Apps are gaining share fastest on contactless service preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deutsche Bahn's integrated rail network and the Autobahn charging corridor infrastructure position Germany as the central European mobility hub. Federal transport investment concentrates rental demand along high-speed rail axes and international airport gateways.
Bavaria
Munich Franz Josef Strauß Airport and the Stuttgart manufacturing corridor drive corporate fleet demand for premium electric vehicles. KBA emissions protocols accelerate contract renegotiation cycles for operational leases. Ingolstadt and Munich host the densest concentration of luxury rental counters serving executive roadshows.
North Rhine-Westphalia
E-commerce logistics operators in the Düsseldorf-Cologne axis seek flexible electric van capacity for last-mile fulfillment. EU Green Deal fleet targets mandate zero-emission minimums in municipal procurement. The Ruhr industrial belt generates sustained demand for commercial vehicle rentals among mid-sized manufacturers shedding owned fleets.
Baden-Württemberg
Automotive supplier clusters around Stuttgart create rotational staff mobility needs met through subscription-based access models. Federal Ministry for Digital and Transport funding expands fast-charging density along A8 and A81 corridors. Karlsruhe and Mannheim serve as intermodal exchange points capturing rail-arriving business travelers.
Berlin-Brandenburg
Startup ecosystem density and project-based consulting labor pools favor car-sharing and short-term rental over ownership. Berlin's low-emission zone enforcement compresses residual values for non-compliant internal combustion stock. Potsdam and Berlin Tegel generate the highest per-capita transaction density for airport counter networks.
Hamburg
Port logistics and maritime services sustain commercial van rental demand for container drayage and shipyard support. The city's 2030 climate plan mandates fleet electrification for all municipal contractors. HafenCity development and Elbphilharmonie event traffic anchor premium vehicle rental counters in the urban core.
Germany Car Rental Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in fleet procurement and maintenance networks. The Germany car rental market structures around three operational archetypes: premium-positioned full-service operators, price-competitive volume players, and manufacturer-captive mobility services. Consolidation pressures intensify as electrification capital requirements favor scale. Dominant competitive moves include strategic partnerships with charging infrastructure providers and portfolio diversification into subscription-based mobility access.
Among international platform operators, Enterprise Holdings and Avis Budget Group exemplify the integrated network archetype with broad geographic coverage. SIXT occupies a distinctive position through premium-tier urban center concentration and digital-first customer interfaces. These three entities anchor the competitive structure while manufacturer-affiliated services from Mercedes-Benz Group AG and Volkswagen AG represent the captive-fleet segment.
| Leading Market Players |
|---|
| Enterprise Holdings |
| Buchbinder |
| Avis Budget Group |
| Mercedes-Benz Group AG |
| Volkswagen AG |
| SIXT |
| Hertz |
| Bayerische Motoren Werke AG |
| Europcar International |
| Others |
Supply Flow & Price Mechanics
Overcapacity in legacy diesel fleet across eastern German depots compresses daily rental rates while forcing operators to accelerate electric vehicle procurement cycles. This utilization imbalance simultaneously erodes residual value recovery on internal combustion stock and elevates capital commitments to battery-electric platforms, reshaping procurement timing and geographic fleet distribution.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates German rental contracts, with differentiation driven by vehicle class tier and bundled insurance coverage depth. Corporate fleet outsourcing agreements command steepest volume discounts due to 12-36 month contract durations and guaranteed utilization floors. Pricing pressure stems from KBA emissions protocols accelerating diesel depreciation schedules. Tourist segments at Munich and Berlin airport counters exhibit highest price sensitivity, while executive luxury rentals in Düsseldorf show lowest elasticity.
Supply Chain Analysis
Battery cell supply concentration between China, South Korea, and Japan dominates procurement risk for German rental electrification programs. Lithium-ion cells, power electronics modules, and electric drivetrain assemblies constitute critical component dependencies. Single-source vulnerability in Asian cell manufacturing creates 12-18 month delivery timeline exposure for fleet procurement teams. Distribution runs through manufacturer-authorized service networks for high-voltage maintenance, with spare parts flowing from Stuttgart and Wolfsburg logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate buyer consolidation around large fleet outsourcing contracts has shifted negotiating leverage toward enterprise procurement functions. Three German automotive suppliers now control over half of operational lease volume, compressing operator margins.
For Market Incumbents: Pre-empt subscription-based mobility entrants by integrating Deutsche Bahn intermodal partnerships at Frankfurt and Cologne main stations. Capture corporate mobility budget flows through employer-funded allowance structures before fintech challengers establish digital-first platforms. Defensive priority rests on charging infrastructure partnerships along Autobahn corridors. For New Entrants and Emerging Players: Establish a beachhead in last-mile electric van rentals serving North Rhine-Westphalia e-commerce fulfillment operators. Target Bavarian logistics corridors where incumbent operators under-index on commercial vehicle electrification. Go-to-market angle should emphasize flexible 30-day minimum terms with mid-contract vehicle swaps absent from traditional lease structures. For Investors and Strategic Acquirers: Capital is best deployed toward regional operators with proven KBA homologation expertise and established manufacturer service authorizations. Long-term viability across the projection horizon hinges on electric fleet transition pace and residual value risk management capabilities. Watch charging infrastructure density along Berlin-Hamburg and Munich-Stuttgart corridors as inflection indicator for intercity EV rental adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Deutsche Bahn hub integration at Frankfurt and Düsseldorf captures rail-arriving business travelers before airport facilities. |
| Electric Fleet Procurement Scale-Up | KBA fleet-average CO2 mandates force accelerated battery-electric procurement to satisfy corporate sustainability clauses. |
| Subscription Model Launch | Flat monthly fees with vehicle swaps appeal to Berlin and Hamburg project-based consultants rejecting ownership. |
| Last-Mile Logistics Expansion | Electric van rentals in Bavaria and North Rhine-Westphalia address e-commerce fulfillment demand without ownership burden. |
| Telematics Platform Integration | Real-time battery state monitoring enables dynamic pricing for electric assets and compresses unplanned downtime. |
Methodological Framework
Desk research of KBA registration databases, EU Green Deal policy documentation, and operator fleet disclosure filings preceded structured interviews with rental fleet procurement directors, charging infrastructure planners, and corporate mobility managers. Primary fieldwork with Stuttgart and Munich operational lease specialists combined with secondary validation against IHS Markit vehicle registration data and federal transport investment records. Bottom-up transaction analysis triangulated against top-down market sizing from automotive leasing association aggregates.
Assumptions held KBA emissions protocol stringency and EU Green Deal fleet targets fixed across the analysis window, while electric vehicle adoption curves and charging infrastructure deployment timelines varied by scenario. Segmentation modeling incorporated service type, customer archetype, vehicle propulsion architecture, and regional production cluster dimensions. CAGRs derived from logistic diffusion curves fitted to historical fleet electrification patterns, with inputs including battery cost decline trajectories and corporate outsourcing penetration rates.
Sensitivities concentrate around KBA regulatory enforcement timing and battery supply chain disruption events. Forecasts reflect documented assumptions on residual value recovery rates and charging corridor completion schedules. Macroeconomic contraction, regulatory acceleration, or solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Airport Handling Service Market
Transportation Services
Drayage Services Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Philippines Car Rental Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Spain Car Rental Market
Transportation Services
Russia Car Rental Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Bike and Scooter Rental Market