
 Airport Handling Service Market | 2026-2036
Airport Handling Service Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Handling Service Market Insights
Capital-intensity divergence between automated baggage systems and labor-intensive ramp services is reorganizing competitive tiers in airport handling. Swissport International AG leverages its integrated cargo-to-passenger platform across European hubs to sustain premium contract renewals. dnata anchors Middle Eastern operations through dedicated freighter terminals at Dubai and Abu Dhabi. Menzies Aviation competes aggressively on third-party agreements in growth airports across Southeast Asia and Latin America.
Airport handling service encompasses the complete range of ground-based support functions required to prepare aircraft for departure and arrival, including baggage sorting through destination-coded vehicle systems, aircraft pushback with towbarless tractors, and cargo unit load device management. Ramp services and cargo handling dominate revenue pools, with automated systems and real-time tracking representing the fastest-expanding technology segments as airports prioritize turnaround-time reduction. Passenger assistance and lounge services occupy mature margin positions where contract type—particularly outsourcing versus in-house operations—determines profitability more than volume growth.
FAA mandates on ground support equipment emissions, EU F-Gas Regulation phasing out high-GWP refrigerants in airport vehicles, and IATA Safety Audit for Ground Operations standards collectively elevate compliance costs for service providers. EASA oversight of ground handling training certification in Europe parallels ICAO's push for harmonized competency frameworks across signatory states. Stakeholders must monitor regulatory divergence between carbon-neutral airport mandates and labor restrictions that limit automation deployment in certain jurisdictions.
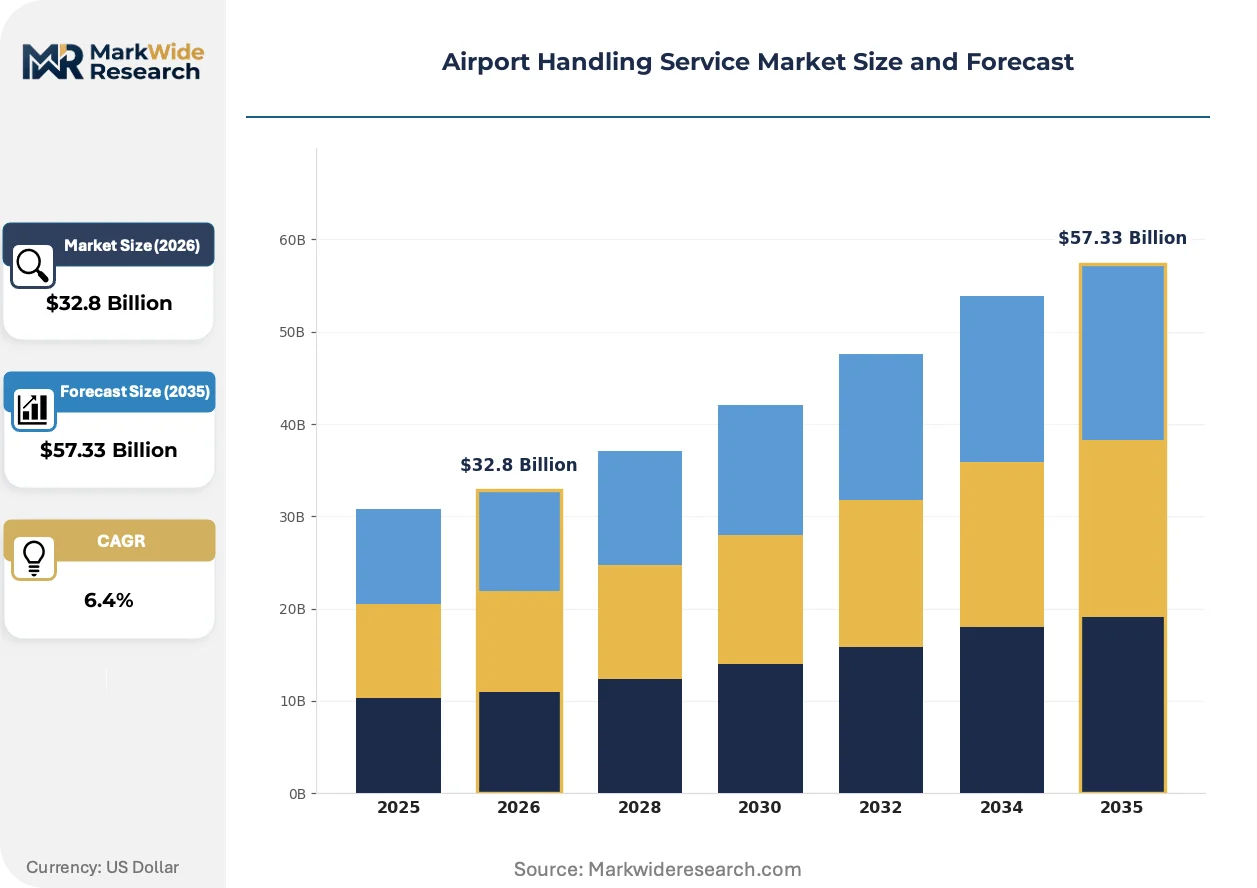
Market Dynamics
Full-service carriers outsourcing ground operations to third-party specialists is compressing turnaround-time requirements while elevating compliance burdens across Asia-Pacific hubs.
Growth Catalysts
- EU F-Gas Regulation:Phased refrigerant mandates for ground support equipment are accelerating fleet replacement cycles and creating service contract opportunities for compliant handlers.
- India:Terminal capacity expansion at Delhi and Mumbai airports under liberalized ground handling rules is opening formerly restricted ramp services to private operators.
- Automated baggage systems:Destination-coded vehicle installations are reducing aircraft turnaround windows and driving recurring maintenance revenue for integrated platform providers.
Market Restraints
- Specialized labor pools:Certified aircraft pushback and cargo ULD management technicians concentrate in Dubai and Singapore, creating wage inflation and recruitment bottlenecks for expansion markets.
- Equipment supply concentration:Towbarless tractor and automated baggage system manufacturing clusters in Germany and Switzerland expose procurement timelines to single-source vulnerabilities.
- Regulatory fragmentation:Divergent EASA ground handling training certification requirements across EU member states complicate cross-border workforce mobility and standardization investments.
Strategic Opportunities
- Indonesia:Underpenetrated secondary airports in Surabaya and Makassar lack dedicated freighter terminal infrastructure, creating first-mover positioning for cargo-to-passenger integrated platforms.
- Real-time tracking convergence:Integration of RFID baggage tags with IoT-enabled ground support equipment is enabling predictive maintenance contracts and outcome-based service pricing.
- Carbon-neutral airport mandates:Singapore's Changi and Dubai's Al Maktoum are requiring electric ground support equipment procurement, favoring handlers with capitalized fleet transition capabilities.
Industry Challenges
- IATA Safety Audit for Ground Operations certification:Compressed audit timelines and recurrent competency verification requirements are straining training infrastructure at mid-tier service providers.
- Legacy system integration:Retrofitting automated baggage sorting into existing terminal architectures without operational disruption demands specialized project management capabilities that concentrate among incumbent handlers.
- Capex intensity for fleet electrification:Battery-powered pushback tractors and cargo loaders require charging infrastructure investments that conflict with short-term contract renewal cycles at price-sensitive airports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Handling Service Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Baggage Handling, Passenger Assistance, Cargo Handling, Aircraft Cleaning, Ramp Services, Lounge Services End User: Airlines, Cargo Operators, Charter Services, Ground Handling Companies, Freight Forwarders, Maintenance Providers Technology: Automated Systems, Radio Frequency Identification, Real-Time Tracking, GPS Monitoring, Mobile Applications, Cloud-Based Platforms Contract Type: Outsourcing, In-House Operations, Third-Party Agreements, Joint Ventures, Public-Private Partnerships |
| Companies Covered | Swissport International AG, dnata, Menzies Aviation, Aviapartner, Fraport AG, Celebi Aviation Holding, Worldwide Flight Services, SATS Ltd., AHS Aviation Handling Services GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Handling Service Market Trends and Innovations
Digital integration across passenger, baggage, and cargo workflows is compressing coordination layers between airlines, airports, and ground handlers while elevating real-time data exchange requirements.
Autonomous baggage tractors equipped with LiDAR navigation and collision-avoidance systems are miniaturizing the operational footprint of ramp services while reducing labor headcount at high-frequency turnarounds. Full-service carriers at Singapore Changi and Dubai International are piloting these units during overnight narrow-body rotations. The technology is miniaturizing the traditional tractor-to-operator ratio from one-to-one toward one-to-many remote monitoring configurations.
FAA mandates on ground support equipment emissions are forcing diesel fleet retirements ahead of natural replacement cycles at US hub airports. The regulatory pressure is compressing capital deployment timelines for electric alternatives and favoring handlers with established equipment financing relationships. Cargo handlers at Memphis and Louisville are most affected, accelerating partnerships with charging infrastructure providers.
Airline procurement departments are unbundling ground handling contracts into discrete service modules—ramp, cargo, passenger assistance—enabling competitive benchmarking and supplier rotation. This fragmentation is displacing integrated full-service agreements that previously locked in multi-year relationships. The shift is most visible among low-cost carriers expanding Southeast Asian point-to-point networks.
Airport Handling Service Market Segmentation
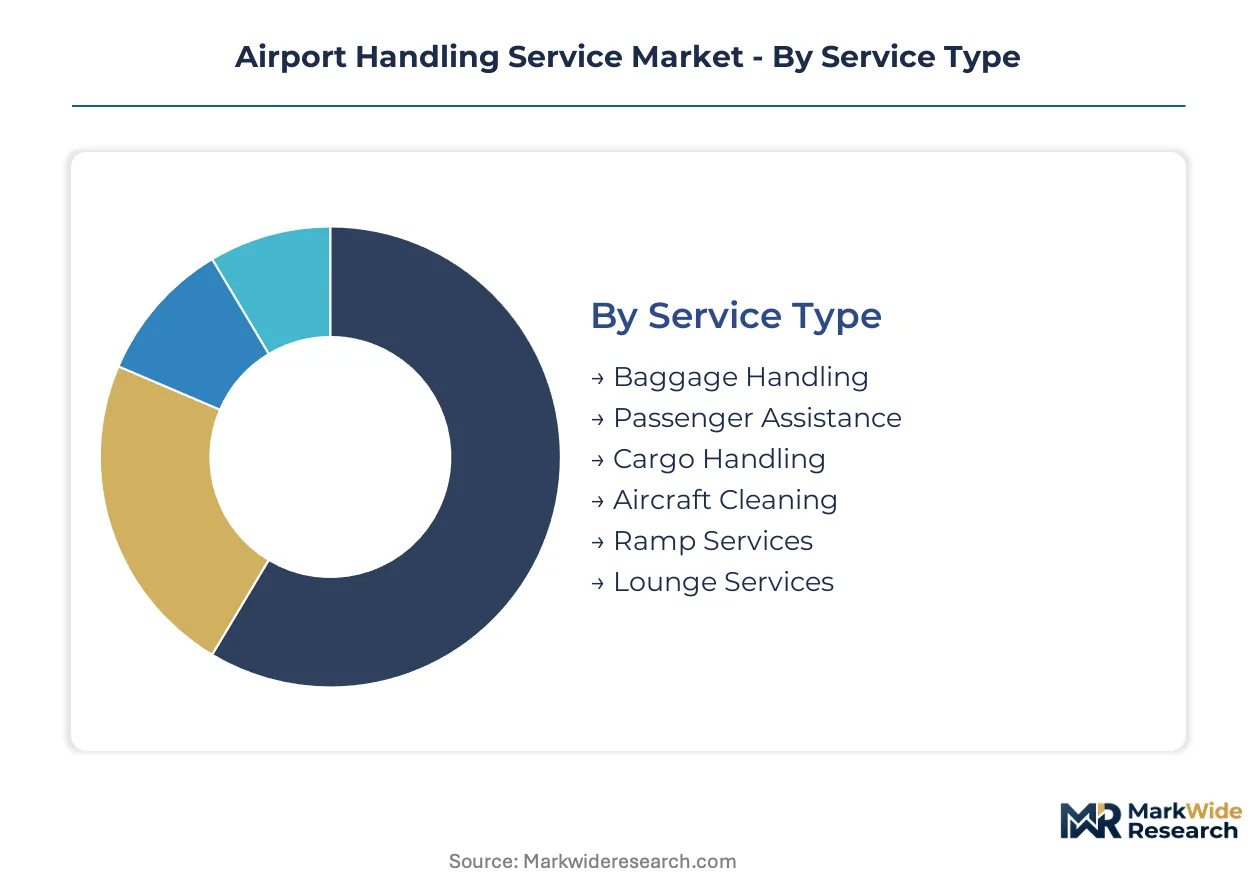
Segmentation in airport handling reveals how service providers allocate capital between labor-intensive ramp operations and technology-driven automation platforms. Contract structure and technology adoption determine margin sustainability across divergent regulatory environments.
Service Type:
Substitution pressure from autonomous equipment and self-service technologies is most acute in baggage sorting and passenger assistance, while specialized ramp services retain defensive moats.
- Baggage Handling:Destination-coded vehicle systems and automated sorting infrastructure dominate capital deployment at major hubs. Delhi and Mumbai liberalization is opening this segment to private operators previously restricted under legacy rules.
- Cargo Handling:Unit load device management and freighter terminal operations concentrate revenue at Dubai and Singapore hubs. dnata's dedicated cargo infrastructure anchors Middle Eastern competitive positioning.
- Ramp Services:Aircraft pushback, towing, and marshalling require certified technicians with specialized training credentials.
- Passenger Assistance:Wheelchair services and unaccompanied minor handling remain labor-dependent with limited automation pathways.
- Aircraft Cleaning:Turnaround-time pressures compress service windows at low-cost carrier hubs.
- Lounge Services:Premium passenger amenities operate on fixed-fee contracts with mature margin profiles.
Ramp services anchors the volume base while automated baggage handling gains share at the steepest rate.
End User:
Cost tier divergence separates price-sensitive low-cost carriers from full-service airlines prioritizing integrated service platforms.
- Airlines:Full-service carriers at Changi and Dubai International are unbundling contracts into discrete modules for competitive benchmarking. Swissport's integrated cargo-to-passenger platform sustains premium renewals at European hubs.
- Cargo Operators:Express freight networks at Memphis and Louisville drive demand for electric ground support equipment under FAA emission mandates.
- Ground Handling Companies:Third-party specialists compete on IATA Safety Audit certification and turnaround-time guarantees.
- Freight Forwarders:Consolidation and deconsolidation services require flexible contract structures.
- Charter Services:Irregular operations demand surge-capacity agreements with variable pricing.
- Maintenance Providers:Technical handling for AOG situations requires specialized equipment access.
Airlines dominate contract value while cargo operators expand most quickly under e-commerce freight growth.
Technology:
Application maturity separates proven automation from pilot-phase innovations still seeking operational validation.
- Automated Systems:Towbarless tractors and autonomous baggage vehicles with LiDAR navigation are miniaturizing traditional operator-to-equipment ratios at Singapore Changi overnight rotations.
- Real-Time Tracking:IoT-enabled ground support equipment integration enables predictive maintenance contracts and outcome-based pricing models.
- Radio Frequency Identification:Baggage tag tracking is standardizing across IATA Resolution 753 compliance mandates.
- GPS Monitoring:Fleet positioning systems optimize equipment allocation across dispersed ramp areas.
- Mobile Applications:Dispatcher-to-crew communication platforms streamline turnaround coordination.
- Cloud-Based Platforms:Centralized data aggregation supports multi-airport operator visibility.
Automated systems command the largest installed base while real-time tracking climbs the fastest as airports prioritize predictive capabilities.
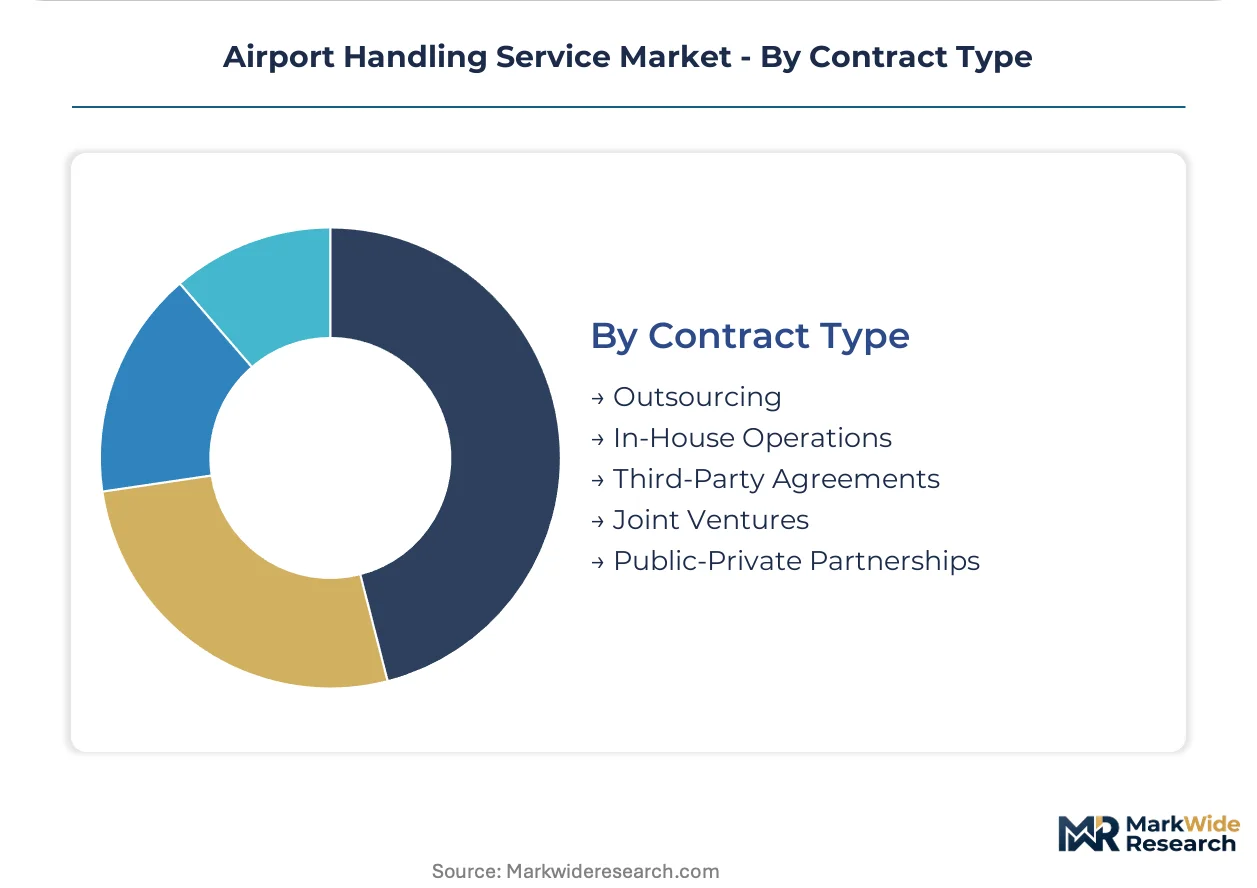
Contract Type:
Volume concentration favors outsourcing specialists with scale economies over fragmented in-house operations.
- Outsourcing:Third-party ground handling specialists capture expanding share as Asia-Pacific full-service carriers divest non-core operations. Menzies Aviation competes aggressively on modular agreements across Southeast Asian growth airports.
- Third-Party Agreements:Competitive benchmarking and supplier rotation are displacing integrated full-service contracts among low-cost carriers.
- In-House Operations:Legacy carrier-owned handling persists at fortress hubs with restrictive slot access.
- Joint Ventures:Airline-handler partnerships balance operational control with capital efficiency.
- Public-Private Partnerships:Terminal concession structures integrate handling rights with infrastructure investment obligations.
Outsourcing structures anchor revenue concentration while third-party agreements expand most rapidly under procurement unbundling trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates at Dubai and Singapore hubs where dedicated freighter terminals command premium rates, while Indian operators absorb margin pressure from liberalized ground handling rules and new market entry.
United States
FAA emission mandates on ground support equipment are forcing premature diesel fleet retirements at Memphis and Louisville cargo hubs. Battery-powered pushback tractors and charging infrastructure partnerships are reshaping procurement timelines. Express freight networks dominate electric equipment adoption under regulatory pressure.
Germany
Towbarless tractor manufacturing clusters in southern Germany expose procurement timelines to single-source vulnerabilities. EASA ground handling training certification requirements complicate cross-border workforce mobility. Frankfurt anchors integrated cargo-to-passenger platform competition among European handlers.
India
Terminal capacity expansion at Delhi and Mumbai under liberalized ground handling rules is opening formerly restricted ramp services to private operators. BIS standards for ground support equipment create compliance entry barriers. Secondary airport development in Bangalore and Hyderabad attracts modular service contracts.
Singapore
Changi Airport's carbon-neutral mandates require electric ground support equipment procurement, favoring handlers with capitalized fleet transition capabilities. Autonomous baggage tractors with LiDAR navigation are piloting during overnight narrow-body rotations. The city-state anchors ASEAN technology adoption for predictive maintenance contracts.
United Arab Emirates
Dubai International and Abu Dhabi dedicated freighter terminals concentrate certified aircraft pushback technician pools. MOHAP oversight of aviation safety standards elevates training infrastructure requirements. dnata's integrated cargo infrastructure anchors Middle Eastern competitive positioning against price-sensitive entrants.
Airport Handling Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with automated baggage system integrators commanding premium contract renewals while labor-intensive ramp specialists compete on turnaround-time guarantees. The market structure shows tiered consolidation: integrated full-service platforms at fortress hubs, modular specialists at growth airports, and legacy in-house operations at slot-restricted facilities. Two strategic archetypes dominate—capital-heavy automation providers and relationship-driven third-party handlers. Competitive moves concentrate on equipment fleet electrification partnerships and IATA Safety Audit certification differentiation.
Within the integrated platform tier, Swissport International AG and dnata represent archetypes of cargo-to-passenger service bundling, with the former anchoring European hub positioning and the latter exemplifying Middle Eastern infrastructure concentration. Menzies Aviation occupies a position among aggressive modular competitors seeking Southeast Asian growth airport contracts through third-party agreement specialization.
| Leading Market Players |
|---|
| Swissport International AG |
| dnata |
| Menzies Aviation |
| Aviapartner |
| Fraport AG |
| Celebi Aviation Holding |
| Worldwide Flight Services |
| SATS Ltd. |
| AHS Aviation Handling Services GmbH |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month procurement cycles for towbarless tractors and automated baggage systems concentrate pricing power with German and Swiss equipment manufacturers, while compressed turnaround-time requirements at Asia-Pacific hubs force handlers to absorb premium lease rates or risk contract loss.
Pricing Analysis
The customization-premium spread between standard ramp-service contracts and configured-to-order integrated platforms spans significant value bands, with IATA Safety Audit certification tiers and dedicated freighter terminal access serving as primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels captures contract unbundling trends among low-cost carriers in Southeast Asia, where procurement departments rotate suppliers on modular benchmarks. Cost compression in standard ramp services intensifies because labor wage inflation in Dubai and Singapore outpaces automation deployment timelines. Cargo operators at Memphis and Louisville exhibit least price sensitivity due to FAA-mandated fleet electrification timelines, while secondary airport authorities in India demonstrate highest sensitivity under liberalized ground handling rules.
Supply Chain Analysis
Just-in-time equipment procurement dominates at established European hubs, whereas strategic stockpiling of certified pushback technicians and battery-powered ground support equipment accelerates at Dubai and Singapore under carbon-neutral airport mandates. Manufacturing clusters in Germany, Switzerland, and the United States anchor supply for towbarless tractors and destination-coded vehicle systems, with lithium-ion battery cells and high-torque electric motors drawing from East Asian component networks. Single-source vulnerability concentrates in automated baggage system integrators, exposing procurement timelines to semiconductor availability constraints. Distribution runs through equipment financing partnerships and long-term service agreements rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as full-service carriers unbundle ground handling contracts into discrete modules, creating niches for specialists with targeted certification investments and regional infrastructure plays.
For Market Incumbents: Fortify integrated platform positioning at fortress hubs through captive maintenance capabilities for automated baggage systems, while accelerating IATA Safety Audit certification differentiation to defend against modular competitors targeting contract rotation at price-sensitive airports. Vertical integration into electric ground support equipment charging infrastructure anchors long-term renewal leverage at Singapore and Dubai. For New Entrants and Emerging Players: Lead with underpenetrated secondary airports in Indonesia's Surabaya and Makassar, where dedicated freighter terminal infrastructure gaps create first-mover positioning for cargo-to-passenger integrated platforms. Target modular ramp-service contracts at Indian growth airports under liberalized ground handling rules, leveraging competitive turnaround-time guarantees against incumbent cost structures. For Investors and Strategic Acquirers: Carve-out targets emerge from airline-owned ground handling subsidiaries divesting non-core operations at Asia-Pacific hubs, particularly where terminal capacity expansion coincides with regulatory liberalization. Mid-tier handlers with established EASA training certification and electric fleet transition capabilities present viable acquisition profiles. Monitor IATA Safety Audit completion rates as inflection indicator for contract renewal momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Battery-powered pushback tractor deployment at Changi satisfies MOHAP carbon mandates. |
| IATA Safety Audit Certification | Recurrent competency verification anchors contract renewal eligibility at European hubs. |
| Modular Service Unbundling | Discrete ramp-cargo-passenger contracts enable competitive benchmarking among low-cost carriers. |
| Secondary Airport Infrastructure | Dedicated freighter terminals at Surabaya capture underpenetrated Indonesian cargo flows. |
| Predictive Maintenance Contracts | IoT-enabled ground support equipment integration enables outcome-based pricing at Dubai. |
Research Methodology
Initial hypotheses were tested against primary input from ground handling operations directors, airline procurement executives, airport authority concession managers, and EASA-certified training instructors, and refined through secondary validation against IATA operational safety audit databases, FAA ground support equipment emission filings, EU F-Gas Regulation compliance registries, and customs trade data for towbarless tractor imports. Bottom-up equipment deployment counts and top-down terminal capacity expansion schedules were triangulated to reconcile volume estimates.
Variance-decomposition across service type, technology adoption tier, contract structure, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from equipment replacement cycle analysis and outsourcing penetration curves, with automated baggage system installation timelines and certified technician pool growth serving as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Asia-Pacific terminal capacity expansion and harmonized ICAO competency framework adoption would require recalibration. Forecasts reflect documented assumptions regarding fleet electrification capital deployment and labor mobility liberalization. Revision becomes warranted when FAA emission mandate enforcement intensity or EU F-Gas Regulation phase-out timelines cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Refuse Truck Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
Germany Car Rental Market
Transportation Services
Bike Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Driving Vacation Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Middle East Car Rental Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Europe Light Commercial Vehicle Rental Market