
 Bike and Scooter Rental Market | 2026-2036
Bike and Scooter Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Bike and Scooter Rental Market Intelligence
The commuter user archetype is collapsing the historical distinction between tourism-focused rentals and daily transport solutions. Major operators like Lime leverage proprietary app data to optimize fleet distribution for morning and evening peak travel times. TIER Mobility competes by integrating its services with public transport networks in cities like Berlin and Paris. Bolt extends its ride-hailing platform to include scooter and bike options, creating a multimodal ecosystem.
Bike and scooter rental services provide short-term, on-demand access to shared micro-mobility vehicles, typically unlocked via a mobile application. These vehicles are equipped with IoT modules for GPS tracking, remote locking, and payment processing, with electric models featuring lithium-ion batteries offering specific ranges per charge. The electric scooter segment leads vehicle type adoption due to its ease of use and small footprint in congested urban areas. While pay-as-you-go remains the dominant rental model, subscription-based plans are gaining traction among commuters seeking predictable monthly costs.
Operational viability is governed by a patchwork of municipal permits, such as those issued by the New York City Department of Transportation, which dictate fleet size and operating zones. Concurrently, data handling practices must comply with regulations like the EU's GDPR, while vehicle safety standards are increasingly scrutinized by bodies like Germany's KBA. Stakeholders must now navigate the challenge of achieving profitable unit economics while adapting to a fragmented regulatory environment.
Market Dynamics
The central dynamic shaping the market is the tension between municipal authorities seeking to manage public space and operators striving for profitable, scalable fleet operations. This conflict dictates operating zones, fleet sizes, and data-sharing requirements, directly impacting unit economics.
Growth Catalysts
- Urban Policy Frameworks:The EU Green Deal and similar urban mobility plans in Asia-Pacific cities incentivize a modal shift away from private cars, creating favorable conditions for shared micro-mobility as a last-mile solution.
- IoT Module Integration:The proliferation of advanced IoT modules enables operators to optimize fleet distribution, implement remote locking, and streamline payment processing, improving asset utilization and the user experience for commuters.
- Corporate Segment Adoption:Businesses are increasingly integrating bike and scooter rentals into corporate mobility plans to provide employees with efficient, eco-friendly options for commuting and campus travel, creating a stable B2B revenue stream.
Market Restraints
- Fragmented Regulatory Permits:A patchwork of municipal regulations, such as those from the New York City Department of Transportation, creates high compliance costs and operational complexity, hindering seamless expansion across different jurisdictions.
- Battery Material Volatility:The market's reliance on electric models exposes it to supply chain risks and price fluctuations for key lithium-ion battery components like cobalt and lithium, impacting vehicle acquisition costs.
- Infrastructure Dependency:The viability of electric fleets depends on the availability of reliable charging infrastructure, a factor that remains underdeveloped in many potential expansion markets and limits operational uptime.
Strategic Opportunities
- Secondary City Expansion:Operators have a significant opportunity to enter less-saturated secondary cities in regions like Latin America and Southeast Asia, where traffic congestion is rising but micro-mobility competition is lower.
- MaaS Platform Integration:Deeper integration with public transport apps and Mobility-as-a-Service platforms can position bike and scooter rentals as an indispensable component of a city's multimodal transit ecosystem, increasing user reach.
- Subscription Model Refinement:Expanding subscription plans targeted at corporate clients and daily commuters can generate more predictable revenue streams and foster greater user loyalty compared to purely transactional, pay-per-ride models.
Industry Challenges
- Unit Economic Viability:Achieving profitability on a per-vehicle basis remains a primary challenge, given high costs associated with vehicle depreciation, vandalism, theft, and the labor-intensive process of rebalancing and maintenance.
- Data Privacy Compliance:Operators must navigate complex data regulations like the EU's GDPR, balancing the need to collect user location data for operational efficiency with strict consumer privacy protection mandates.
- High Capital Expenditure:The need for constant fleet renewal and expansion to remain competitive requires significant upfront capital investment, creating a high barrier to entry and pressuring operational cash flow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike and Scooter Rental Market |
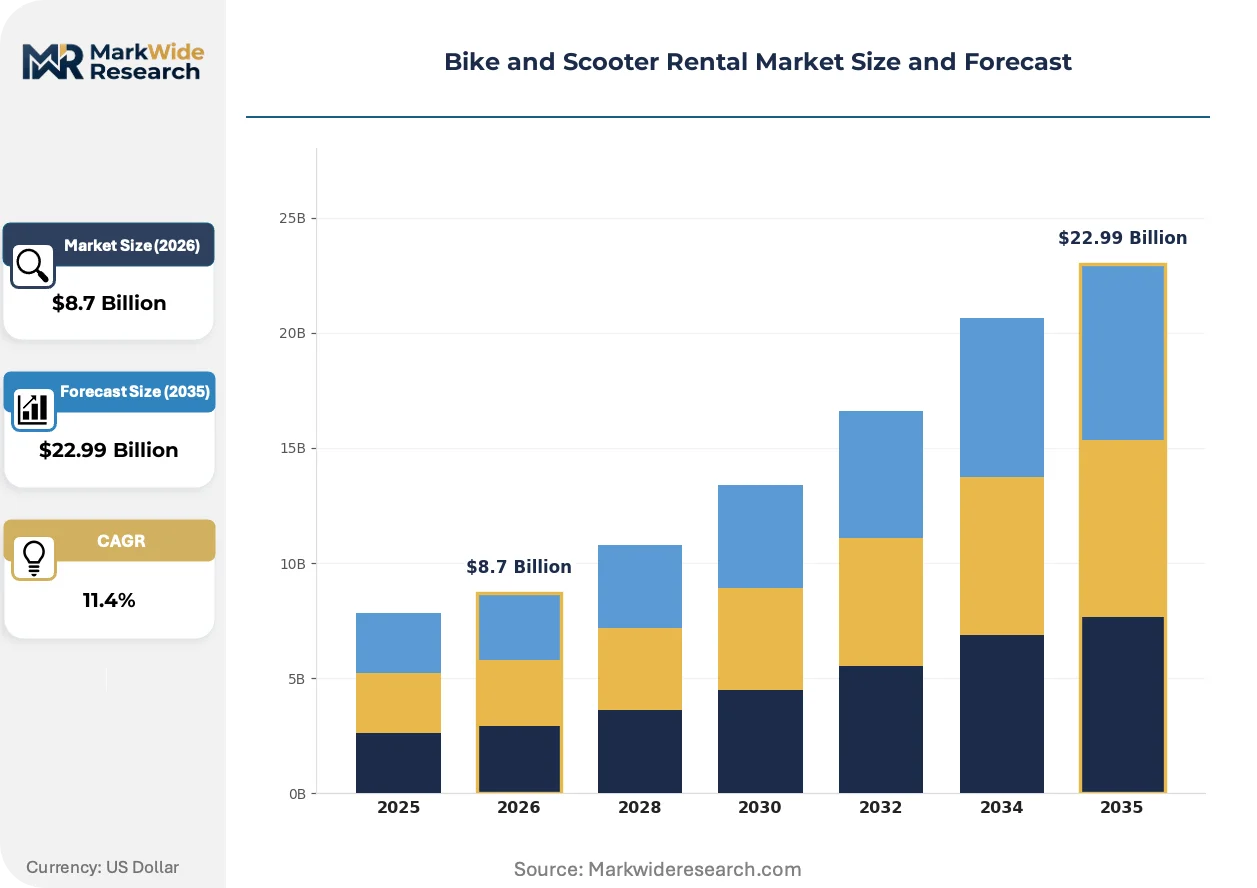
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Electric Bike, Gasoline Bike, Electric Scooter, Kick Scooter, Folding Bike Rental Model: Hourly Rental, Daily Rental, Weekly Rental, Subscription, Pay-as-you-go Customer Type: Tourists, Commuters, Students, Corporate Users, Delivery Partners Booking Channel: Mobile App, Website, Kiosk, Call Center, Third-party Platforms |
| Companies Covered | Lime, Bird, Jump, Cityscoot, nextbike, Lyft, TIER Mobility, Voi Technology, Bolt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike and Scooter Rental Market Strategic Shifts & Innovations
Intensifying urban density and regulatory scrutiny are forcing a maturation of the market. Service models are shifting from disruptive growth-at-all-costs approaches toward sustainable, integrated components of formal urban transportation networks, driven by data and hardware innovation.
Swappable battery systems are a key hardware evolution, designed to minimize vehicle downtime and centralize charging logistics away from public spaces. Major operators in dense European and North American cities are rapidly adopting this technology to boost fleet availability and operational efficiency. This technology is decomposing the legacy model of collecting entire scooters for off-site charging, reallocating labor from vehicle retrieval to more efficient battery-swapping routes.
Germany's federal motor transport authority, the KBA, exemplifies a broader regulatory shift toward stricter vehicle safety and construction standards. This mandate compels manufacturers to invest in more durable frames, certifiable braking systems, and reliable lighting, raising the baseline quality and cost of fleet vehicles. The electric scooter segment is most impacted, with operators prioritizing KBA-compliant models to ensure access across the lucrative and highly regulated German market.
Subscription-based plans are gaining traction among commuters, signaling a behavioral shift away from purely spontaneous, per-minute rentals. This change disrupts the traditional tourism-focused business model, creating an advantage for operators who can offer predictable monthly pricing for daily transportation. This trend is most pronounced in major European hubs like Paris and Berlin, where micro-mobility is becoming a fully integrated part of the daily commute.
Bike and Scooter Rental Market Segmentation
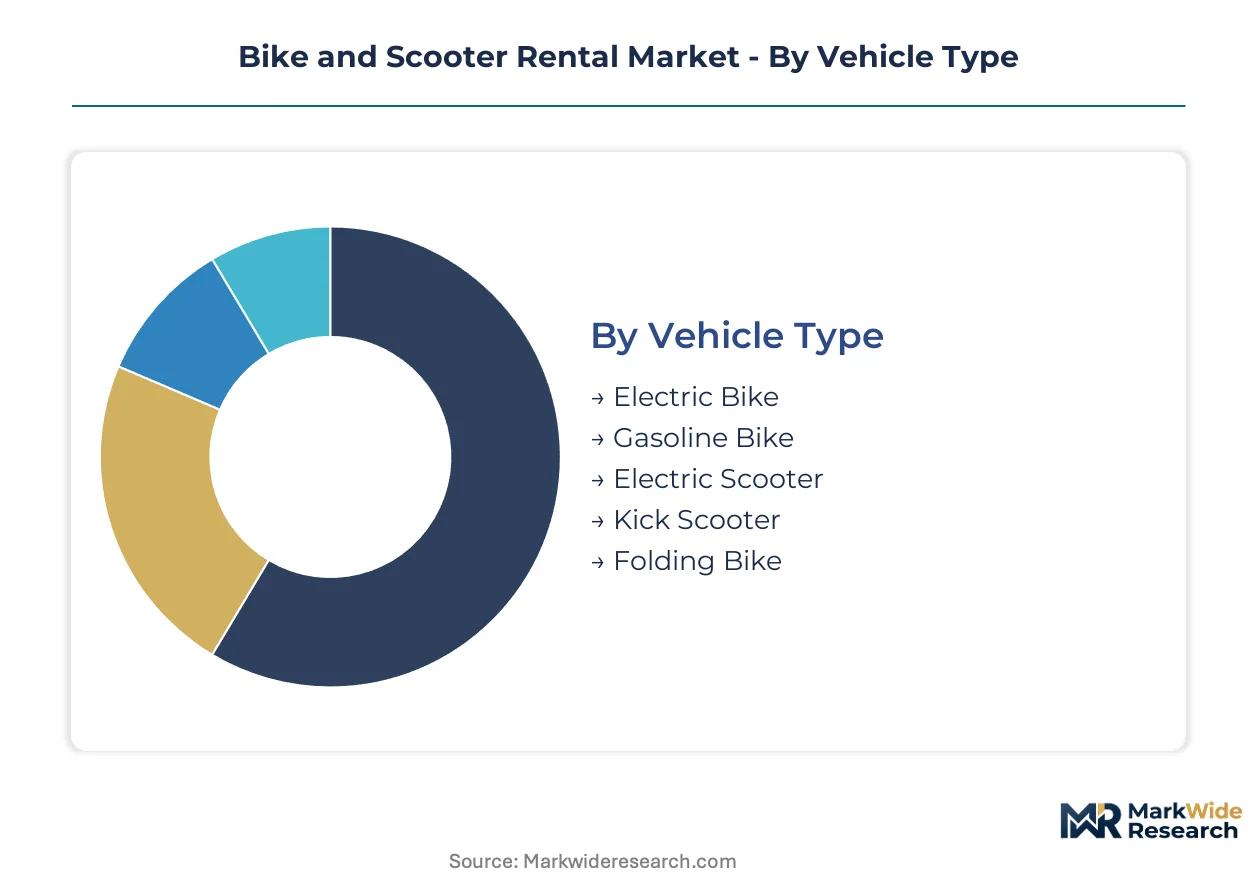
The Bike and Scooter Rental Market's varied segments reflect diverse user needs and operational models. Understanding these distinctions helps operators tailor services, optimize fleet deployment, and navigate regulatory landscapes. This segmentation highlights key areas of revenue generation and operational complexity within urban micro-mobility.
Vehicle Type:
Margin pools within vehicle types are heavily influenced by acquisition costs and operational efficiency.
- Electric Bike:These vehicles feature pedal-assist or throttle power, extending range and reducing rider effort. Demand concentrates in European cities like Paris, driven by urban planning that favors cycling infrastructure and environmental incentives.
- Electric Scooter:These stand-up vehicles utilize electric motors for propulsion, offering high maneuverability in congested areas. Demand concentrates in major metropolitan areas, with operators optimizing fleet distribution for last-mile connectivity.
- Gasoline Bike:Traditional motorized bicycles, less common in shared fleets due to environmental regulations and maintenance complexity.
- Kick Scooter:Non-electric, human-powered scooters, offering a low-cost, short-distance micro-mobility option for quick trips.
- Folding Bike:Compact bicycles designed for easy portability and storage, often used for multimodal journeys.
The dominant share belongs to Electric Scooter, while Electric Bike is closing the gap fastest.
Rental Model:
The market's operational flexibility is defined by various rental models, each targeting distinct user behaviors.
- Pay-as-you-go:Users are charged per minute or per ride, offering maximum flexibility without long-term commitment. This model dominates initial user adoption due to its low barrier to entry and convenience.
- Subscription:Monthly or annual plans provide unlimited or discounted rides, appealing to frequent commuters seeking predictable monthly costs. This model is gaining traction among commuters in major European hubs.
- Hourly Rental:Users pay a fixed rate for each hour of use, suitable for short-to-medium duration trips, often popular with tourists.
- Daily Rental:Provides access to a vehicle for a full 24-hour period, catering to users needing extended access.
- Weekly Rental:Offers a longer-term rental option, often preferred by visitors or temporary residents.
Pay-as-you-go continues to capture the largest user base, with Subscription models showing the steepest expansion trajectory.
Customer Type:
Customer types delineate distinct usage patterns and revenue opportunities for operators.
- Commuters:Individuals using rentals for daily travel to and from work or school, prioritizing speed and cost-effectiveness. This segment drives predictable demand during peak hours, particularly in European cities with integrated public transport.
- Corporate Users:Businesses integrating micro-mobility into employee benefits or campus transport solutions, seeking efficient and eco-friendly options. This segment offers stable B2B revenue streams and reduced fleet idle time.
- Tourists:Visitors utilizing rentals for sightseeing and leisure, often for short-term, spontaneous exploration.
- Students:University and college students using rentals for campus travel and short trips around educational institutions.
- Delivery Partners:Individuals using bikes or scooters for last-mile food or package delivery services.
Commuters represent the largest and most consistent demand, while Corporate Users are rapidly increasing their share.
Booking Channel:
Booking channels reflect user convenience preferences and technological integration capabilities.
- Mobile App:Dedicated smartphone applications enable users to locate, unlock, and pay for vehicles seamlessly. This channel is fundamental for optimizing fleet distribution and user experience, especially for operators like Lime.
- Third-party Platforms:Integration with Mobility-as-a-Service (MaaS) apps or other ride-hailing platforms expands user reach and multimodal options. This channel is gaining traction in cities like Berlin, where TIER Mobility integrates with public transport apps.
- Website:Online portals offering booking and account management, typically for longer-term rentals or corporate accounts.
- Kiosk:Physical stations providing rental access, often found in high-traffic tourist areas or transport hubs.
- Call Center:Customer service lines for booking assistance, troubleshooting, and support, catering to diverse user needs.
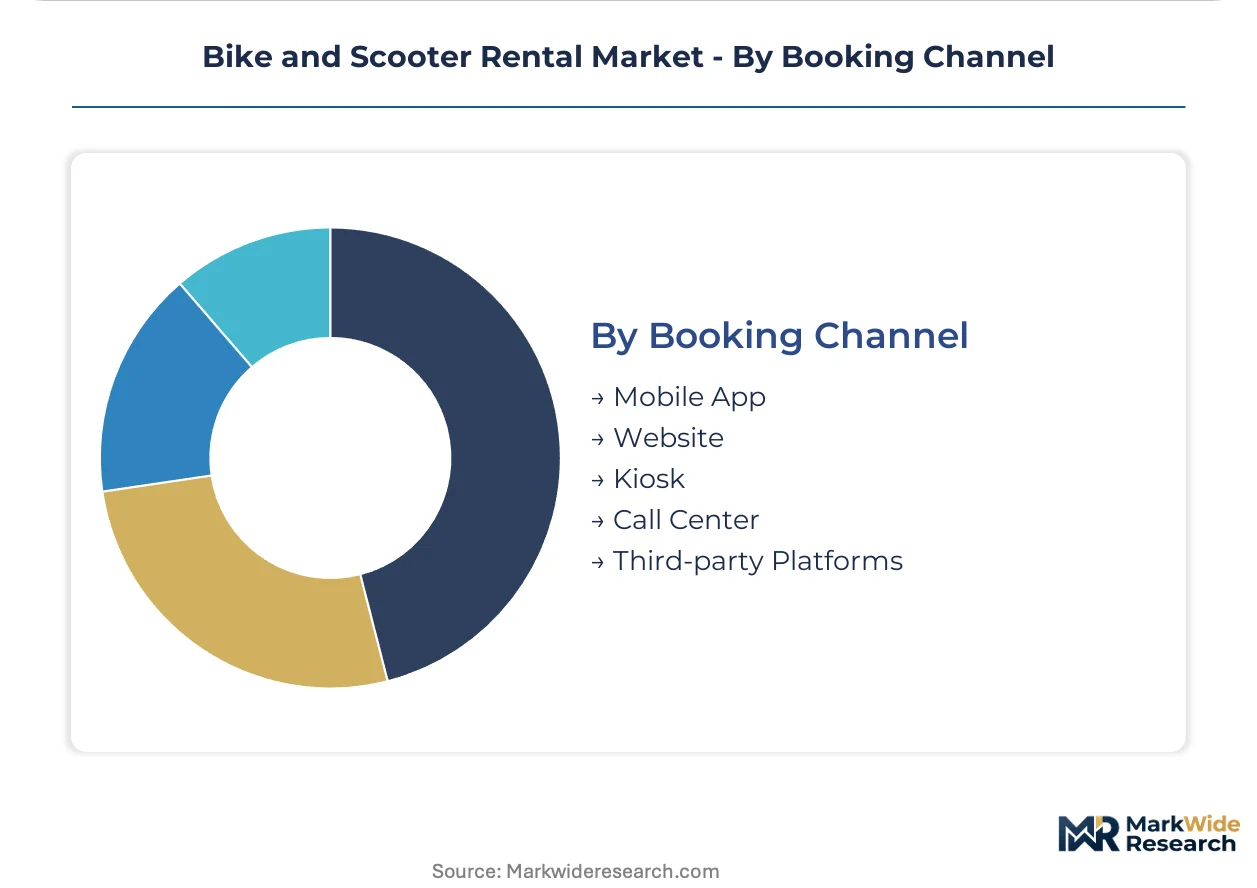
Mobile App bookings remain the primary access point, with Third-party Platforms demonstrating significant growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Operational models for bike and scooter rentals, pioneered in European cities like Paris, now influence market development in major urban centers globally. This service-oriented market sees significant exchange of best practices and technological innovations. Regulatory frameworks and user adoption patterns vary, shaping regional growth trajectories.
United States
Demand for micro-mobility services in the United States stems from urban congestion and a push for sustainable transport. The New York City Department of Transportation issues permits dictating fleet sizes and operating zones. Major operators optimize fleet distribution in cities like New York, catering to dense commuter populations. Corporate users integrate these services into employee benefits.
Germany
Germany's market benefits from strong environmental policies and a robust public transport network. The KBA enforces strict vehicle safety and construction standards. Berlin and Munich are hubs for integrated micro-mobility, with TIER Mobility connecting services to public transport. Swappable battery systems are rapidly adopted to boost fleet availability.
France
Urban planning initiatives in France, particularly in Paris, strongly favor cycling infrastructure and green mobility solutions. The EU Green Deal provides a broad policy framework incentivizing modal shifts. Paris represents a key market where subscription models are gaining traction among daily commuters. Cityscoot operates a significant fleet within the Parisian area.
Japan
Japan experiences demand for compact, efficient urban transport solutions, especially in highly dense metropolitan areas. Local municipal authorities often collaborate with operators to establish designated parking zones. Tokyo sees significant micro-mobility adoption, driven by last-mile connectivity. Operators optimize fleet distribution to serve peak travel times.
Brazil
Rising traffic congestion in major Brazilian cities fuels demand for agile urban transportation options. Municipal permits in cities like São Paulo govern fleet operations and rider safety. São Paulo and Rio de Janeiro are emerging markets where micro-mobility offers last-mile connectivity. Secondary city expansion presents a significant opportunity for operators.
Bike and Scooter Rental Market Key Industry Players
Player mix skews toward a blend of dedicated micro-mobility specialists and larger multimodal transportation platforms. The market exhibits a tiered structure, with established global players operating alongside numerous regional and local entities. Strategic archetypes include technology-driven fleet optimizers, public transport integrators, and ride-hailing ecosystem expanders. These operators primarily engage in geographic expansion, multimodal service integration, and subscription model refinement to capture market share.
Within the technology-driven fleet optimization tier, Lime exemplifies leveraging proprietary app data for efficient fleet management and user experience enhancement. TIER Mobility, a European-based operator, represents the archetype focused on integrating micro-mobility services with existing public transport networks, particularly in dense urban centers. Bolt, known for its broader ride-hailing platform, occupies a position as an ecosystem expander, integrating various micro-mobility options into its multimodal offerings to provide comprehensive urban transit solutions. These companies anchor distinct strategic approaches within the competitive landscape, each contributing to the market's evolving structure.
| Leading Market Players |
|---|
| Lime |
| Bird |
| Jump |
| Cityscoot |
| nextbike |
| Lyft |
| TIER Mobility |
| Voi Technology |
| Bolt |
| Others |
Cost & Logistics Intelligence
Germany's KBA standards and the EU Green Deal gate both vehicle supply qualification and price differentiation for micro-mobility fleets. These regulatory frameworks directly impact acquisition costs and operational viability across major urban markets.
Pricing Analysis
Next-generation electric scooter models, compliant with stricter safety standards, command a premium over older, non-compliant vehicles. Pay-as-you-go remains the dominant rental model, while subscription plans offer predictable monthly costs, appealing to frequent commuters. Price differentiation stems from vehicle quality and the level of public transport integration. Pricing pressure stems from intense competition among operators in dense urban areas, with tourists often representing the most price-sensitive segment.
Supply Chain Analysis
The short inventory cycles observed in urban micro-mobility fleets demand agile supply chain operations. Supply concentration centers in China for vehicle manufacturing and in South Korea for advanced lithium-ion battery components. Key raw material dependencies include lithium, cobalt, and specialized IoT modules, exposing operators to commodity price volatility. Distribution runs through direct-to-operator channels, often involving regional assembly hubs for final customization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bike and Scooter Rental Market is a high-growth disruption, driven by urban planning initiatives like the EU Green Deal incentivizing modal shifts away from private cars.
For Market Incumbents: Compound operational efficiency by integrating swappable battery systems across fleets, minimizing vehicle downtime and rebalancing costs. Enhance multimodal integration with public transport networks to counter competition from ride-hailing platforms. Invest in KBA-compliant vehicle models to navigate stricter regulatory environments in lucrative European markets. Leverage proprietary app data for advanced fleet distribution optimization, addressing urban congestion and maximizing asset utilization.
For New Entrants and Emerging Players: Differentiate on niche segments, such as underserved secondary cities in Latin America, where competition remains lower. Target corporate users with tailored subscription plans, offering stable B2B revenue streams and predictable demand. Focus on establishing strong municipal partnerships for permit acquisition, streamlining operational expansion. Develop purpose-built vehicles optimized for specific urban terrains, enhancing user experience and durability.
For Investors and Strategic Acquirers: The EU Green Deal reshapes the acquisition landscape, favoring operators demonstrating strong environmental compliance and integrated urban mobility solutions. Long-term viability hinges on companies achieving profitable unit economics and scaling efficiently across multiple jurisdictions. Target technology-driven fleet optimizers with robust data analytics capabilities and proven subscription model success. Watch for regulatory harmonization across major metropolitan areas as an inflection indicator for accelerated market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| MaaS Platform Integration | Positions micro-mobility as an indispensable part of urban transit, expanding user reach in cities like Berlin. |
| Swappable Battery System Deployment | Boosts fleet availability and operational efficiency by minimizing vehicle downtime and centralizing charging logistics. |
| Corporate Subscription Plan Expansion | Generates predictable revenue streams and fosters user loyalty among high-frequency commuter segments. |
| Secondary City Market Entry | Captures demand in less-saturated urban centers with rising congestion and lower micro-mobility competition. |
| KBA-Compliant Vehicle Procurement | Ensures access to highly regulated and lucrative markets like Germany, meeting evolving safety standards. |
Research Approach
Initial hypotheses were tested against primary input from micro-mobility operators, urban planners, transport authorities, and corporate mobility managers, then refined through iterative analysis. This involved combining qualitative insights from interviews with quantitative data validation from secondary sources. Secondary data included city transport reports, EU Green Deal documents, Germany's KBA vehicle standards, and public company filings. Bottom-up and top-down triangulation ensured data consistency and comprehensive market coverage.
Variance decomposition provided the analytical framework for projecting market trajectories across the analysis window. Segmentation dimensions modeled included vehicle type, rental model, customer type, booking channel, and regional adoption patterns. Compound annual growth rates were derived from historical data trends and forward-looking market drivers. Key industry-specific forecast inputs included urban density trends and public transport integration rates.
Material uncertainties — including municipal policy shifts and battery material supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Poland Car Rental Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Driving Vacation Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Airport Handling Service Market
Transportation Services
Latin America Tourism Vehicle Rental Market