
 Latin America Tourism Vehicle Rental Market | 2026-2036
Latin America Tourism Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Tourism Vehicle Rental Market Insights
Certified fleet maintenance technicians is rotating toward scarcity across Latin American rental hubs, constraining fleet turnaround capacity during peak tourism windows. Localiza&Co leverages its captive technician training academies to sustain above-market vehicle availability in Brazilian beach markets. Avis Car Rental anchors its Caribbean basin operations through direct airport concession control. Movida differentiates via telematics-integrated fleet monitoring across southeastern Brazil.
Latin America tourism vehicle rental denotes short-term vehicle provisioning to leisure and business visitors, encompassing combustion and electrified passenger vehicles maintained to commercial duty cycles with standardized interior configurations and liability coverage frameworks. The primary purpose centers on mobility substitution for travelers lacking local vehicle ownership or seeking destination-appropriate transportation. SUVs dominate margin capture across Andean adventure tourism corridors where road conditions demand elevated clearance. Self-drive rental models lead volume in Mexico's cenote route and Patagonian highway circuits. Online platforms and mobile apps represent the fastest-expanding booking channel, displacing traditional travel agent intermediation in urban Brazilian and Colombian markets.
Brazil's ANVISA and CONTRAN regulations mandate periodic commercial vehicle inspection protocols that elevate fleet compliance expenditures for operators serving international tourists. Mexico's PROFECO consumer protection standards enforce transparent pricing disclosure across online booking channels, reshaping revenue management system requirements. Argentina's CNRT commercial transport authority imposes driver qualification standards on chauffeur-driven segments that filter market participation. Stakeholders must monitor telematics data ownership frameworks and cross-border insurance harmonization as fleet electrification accelerates through Andean markets.
Market Dynamics
Telematics integration across Latin American rental fleets is compressing operational visibility gaps while elevating compliance costs under Brazil's ANVISA-aligned safety protocols. This technology shift restructures competitive positioning between integrated operators and fragmented local providers.
Growth Catalysts
- ANVISA Commercial Inspection Mandates:Brazil's periodic vehicle safety protocols force fleet modernization, accelerating replacement cycles and expanding addressable market for certified rental operators serving international tourists.
- Leisure Concentration in Coastal Corridors:Mexico's Yucatán Peninsula and Brazil's Rio de Janeiro state corridor concentrate tourism demand, creating predictable utilization patterns that justify fleet expansion.
- Mobile Booking Platforms:Smartphone penetration across urban Brazilian and Colombian markets displaces traditional travel agent intermediation, expanding direct customer acquisition channels.
Market Restraints
- Certified Technician Scarcity:Fleet maintenance skill gaps constrain turnaround capacity during peak tourism windows, limiting revenue capture for operators without captive training infrastructure.
- Cross-Border Insurance Fragmentation:Harmonization gaps between national liability frameworks complicate fleet deployment across Andean corridor routes, elevating administrative overhead.
- Input Cost Volatility in Vehicle Procurement:Currency fluctuations against dollar-denominated OEM supply contracts compress margin predictability for Mexican and Argentine operators.
Strategic Opportunities
- Electrification in Andean Markets:Chile and Colombia's emerging charging infrastructure creates first-mover positioning for zero-emission fleet segments targeting eco-conscious adventure tourism.
- Chauffeur-Driven Segment Expansion:Argentina's CNRT driver qualification standards filter competition, creating protected niches for compliant operators in premium inbound tourism.
- Telematics-Insurance Convergence:Usage-based coverage models aligned with real-time fleet monitoring data unlock new revenue streams and risk-adjusted pricing structures.
Industry Challenges
- Legacy Reservation System Integration:Operators face friction migrating from on-premise property management systems to cloud-native platforms capable of PROFECO-mandated pricing transparency.
- Certification Timeline Compression:Brazil's CONTRAN commercial vehicle inspection cycles demand accelerated compliance documentation, straining back-office capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Tourism Vehicle Rental Market |
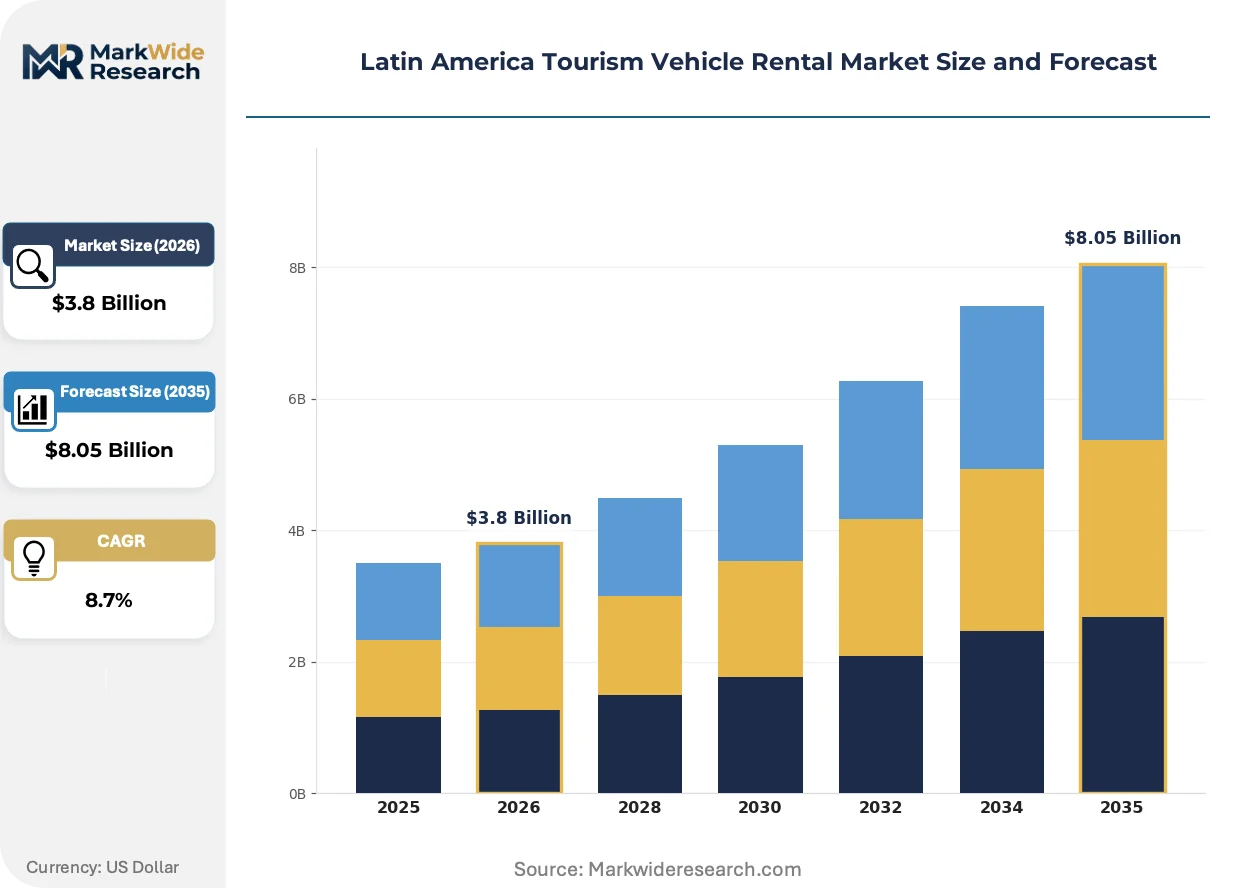
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Van, Convertible Rental Model: Self-Drive, Chauffeur-Driven, Long-Term, Short-Term End User: Tourists, Business Travelers, Local Residents, Corporates Booking Channel: Online Platforms, Travel Agents, Direct Booking, Apps |
| Companies Covered | Enterprise Rent-A-Car, Avis Car Rental, Localiza&Co, Element Fleet Management, Budget Car Rental, Movida, Hertz, Arval, Unidas, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Tourism Vehicle Rental Market Trends and Innovations
Digital distribution channels and connected fleet technologies are restructuring how Latin American rental operators capture demand and manage asset utilization. Three developments merit particular attention.
Telematics hardware is bifurcating fleet management capabilities across the market. Embedded GPS and diagnostic sensors enable real-time vehicle tracking and predictive maintenance scheduling. Premium operators in southeastern Brazil deploy these systems to optimize asset deployment during seasonal demand spikes. The technology is bifurcating competitive positioning between data-integrated fleets and operators reliant on manual dispatch.
PROFECO's transparent pricing disclosure mandates reshape revenue management system requirements across Mexican online booking channels. The consumer protection standards enforce upfront cost visibility, eliminating hidden fee structures that previously padded operator margins. Domestic platforms and international aggregators serving the Yucatán corridor have reconfigured their checkout flows to comply, accelerating technology investment cycles.
Self-drive rental preferences are displacing chauffeur-dependent models across Mexico's cenote route and Patagonian highway circuits. Independent travelers prioritize itinerary flexibility over guided experiences, compressing demand for traditional driver services. This pattern concentrates in adventure tourism verticals where road conditions previously favored professional operation, now enabled by improved route mapping and roadside assistance networks.
Latin America Tourism Vehicle Rental Market Segmentation
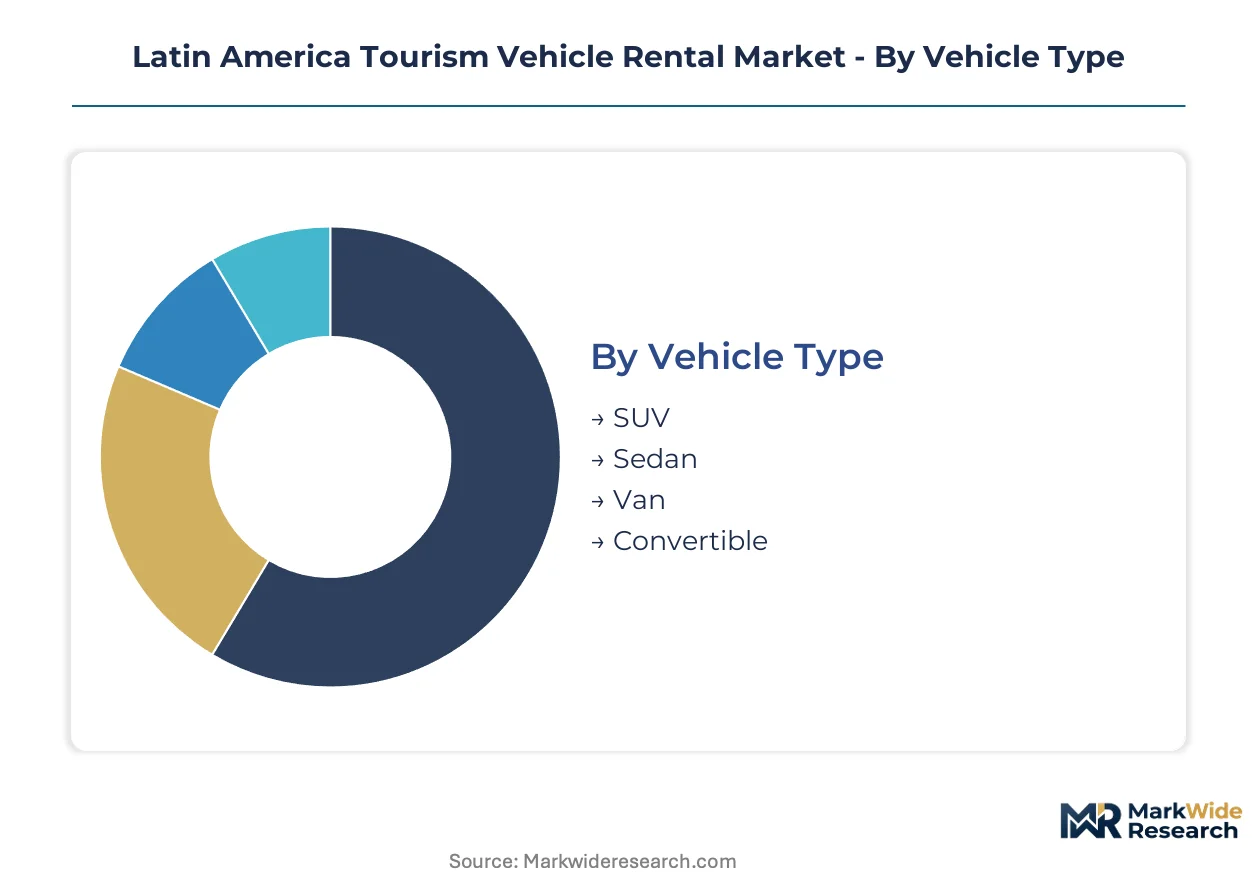
Segmentation reveals how margin pools concentrate across vehicle configurations and customer acquisition channels in Latin American tourism rental markets. Understanding these divisions exposes where fleet investment and technology deployment generate differential returns for operators competing across Mexico's Yucatán corridor and Brazil's southeastern beach markets.
Vehicle Type:
Margin capture varies sharply by ground clearance and passenger capacity, with adventure tourism corridors commanding premium daily rates over urban airport transfers.
- SUV:Elevated suspension and four-wheel-drive configurations dominate Andean routes where unpaved access roads to Patagonian trailheads and Colombian coffee region fincas demand all-terrain capability. Operators serving Rio de Janeiro's coastal mountain circuits capture above-market daily rates during southern hemisphere summer peaks.
- Sedan:Compact and mid-size passenger vehicles anchor volume in Mexico's cenote route and Brazilian metropolitan airport transfers where fuel efficiency and parking maneuverability outweigh clearance requirements. Fleet standardization around sedan platforms enables faster turnaround between rentals.
- Van:Multi-passenger configurations serve extended family groups and dive equipment transport across the Yucatán Peninsula's resort corridor.
- Convertible:Open-top leisure vehicles concentrate in Caribbean coastal markets where destination imagery drives tourist preference.
The dominant share belongs to Sedan, while SUV is closing the gap fastest.
Rental Model:
Customer control over itinerary versus service bundling defines how revenue per transaction scales with operational complexity.
- Self-Drive:Independent operation models concentrate in Mexico's cenote route and Patagonian highway circuits where improved digital mapping and roadside assistance networks reduce traveler anxiety about remote navigation. This configuration minimizes labor overhead while maximizing fleet utilization through 24-hour rental windows.
- Chauffeur-Driven:Professional driver inclusion commands premium pricing in Argentina's inbound tourism segment where CNRT qualification standards filter competition and create protected margin pools. Corporate roadshow circuits in São Paulo and Bogotá sustain contracted driver pools.
- Long-Term:Extended-duration contracts spanning weeks to months serve snowbird populations and remote work relocations across Mexican coastal zones.
- Short-Term:Daily and weekend rentals dominate airport pickup locations and urban hotel concierge desks.
Self-Drive holds the volume lead, though Chauffeur-Driven maintains the highest margin per transaction.
End User:
Customer origin and trip purpose shape pricing elasticity and ancillary attachment rates across fleet deployment decisions.
- Tourists:Leisure visitors from North American and European source markets generate peak-season utilization spikes across Mexico's Yucatán Peninsula and Brazil's Rio de Janeiro state corridor, with demand clustering around December through March windows.
- Business Travelers:Corporate road warriors prioritize airport proximity and express checkout, concentrating in São Paulo, Mexico City, and Bogotá financial districts where time sensitivity overrides rate shopping.
- Local Residents:Domestic customers seeking temporary vehicle substitution during repair cycles or special events represent counter-cyclical demand during international tourism low seasons.
- Corporates:Fleet outsourcing contracts from regional enterprises sustain baseline utilization across secondary city locations.
Tourists command the dominant revenue share, while Business Travelers deliver the most predictable year-round yield.
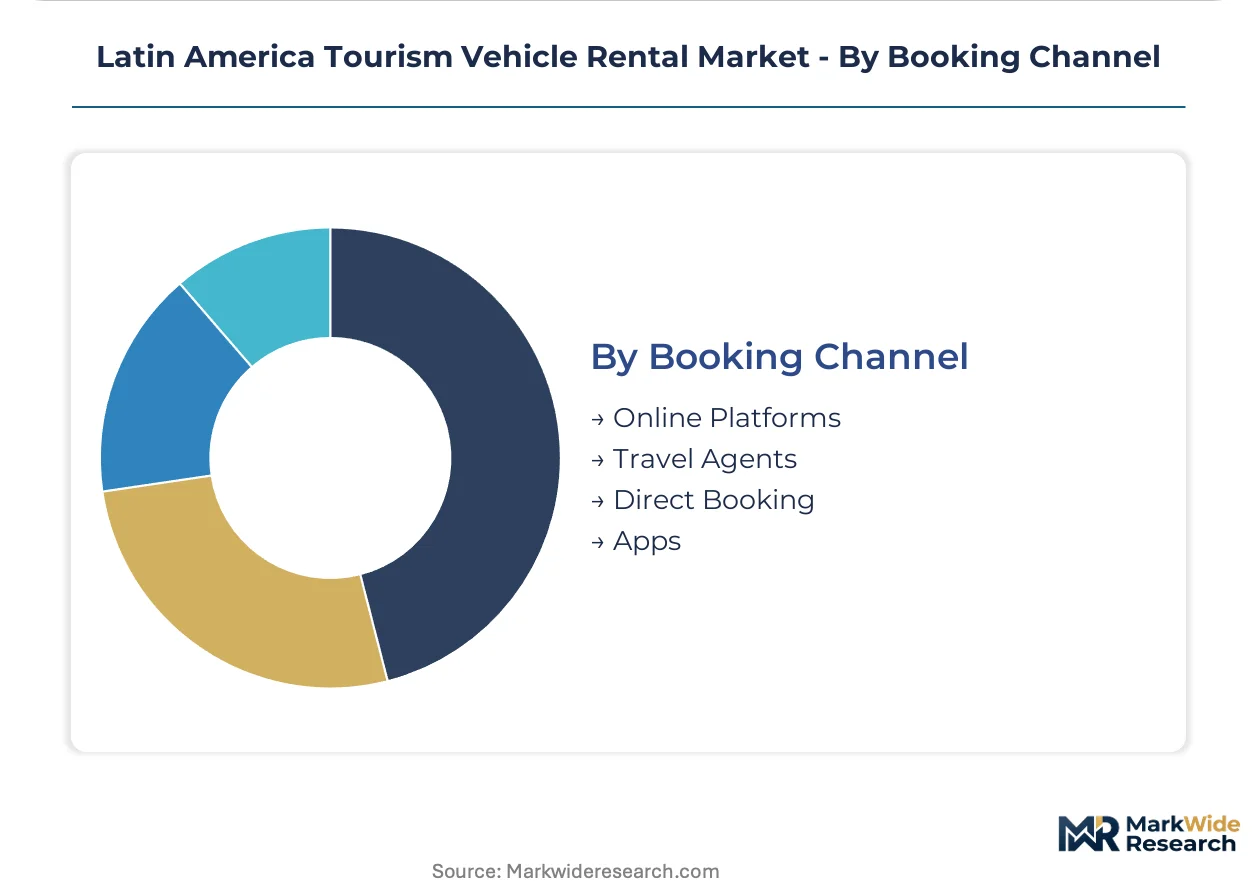
Booking Channel:
Customer acquisition cost and rate transparency exposure diverge sharply between direct digital relationships and intermediated distribution.
- Online Platforms:Aggregator websites and operator direct sites displace traditional intermediation across urban Brazilian and Colombian markets, with PROFECO-mandated pricing transparency in Mexico eliminating hidden fee structures that previously padded margins.
- Travel Agents:Traditional intermediaries retain relevance in packaged tour distribution for European source markets and corporate travel management relationships.
- Direct Booking:Walk-in counter and telephone reservations persist in smaller coastal markets with limited digital infrastructure penetration.
- Apps:Smartphone-native booking interfaces represent the steepest expansion trajectory among acquisition channels, particularly among younger demographic segments.
Online Platforms capture the largest transaction volume, while Apps are gaining share fastest among emerging customer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's Yucatán corridor concentrates self-drive leisure demand around cenote tourism circuits, while Brazil's southeastern beach markets sustain higher fleet utilization through chauffeur-driven corporate contracts. Argentina's inbound tourism segment operates under distinct regulatory constraints that reshape competitive entry requirements.
Brazil
ANVISA-aligned safety protocols and CONTRAN commercial inspection mandates force fleet modernization across Rio de Janeiro and São Paulo state corridors. The country's national vehicle safety regulator imposes periodic certification cycles that accelerate replacement timelines for operators serving international tourists. Localiza&Co anchors southeastern beach market positioning through captive technician training infrastructure.
Mexico
PROFECO consumer protection standards enforce transparent pricing disclosure across online booking channels serving the Yucatán Peninsula's resort corridor. The federal consumer protection agency mandates upfront cost visibility that eliminates hidden fee structures. Avis Car Rental controls direct airport concession relationships across Cancún and Mérida gateway locations.
Argentina
CNRT driver qualification standards filter competition in chauffeur-driven segments targeting premium inbound tourism from European source markets. The national commercial transport authority imposes certification requirements that elevate operational barriers. Buenos Aires and Patagonian gateway cities concentrate demand around corporate roadshow circuits and adventure tourism circuits.
Chile
Emerging charging infrastructure across Santiago and Valparaíso corridors creates positioning opportunities for electrified fleet segments targeting eco-conscious adventure tourism. The national energy commission promotes alternative fuel adoption through station deployment subsidies. Atacama Desert and Lake District tourism circuits drive SUV demand for unpaved access routes.
Colombia
Mobile booking platform penetration across Bogotá and Medellín urban markets displaces traditional travel agent intermediation in corporate travel management. The national tourism promotion agency channels infrastructure investment toward coffee region finca access roads. Movida deploys telematics-integrated fleet monitoring across southeastern industrial corridors.
Latin America Tourism Vehicle Rental Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Latin American tourism vehicle rental. Fleet-scale operators with captive maintenance infrastructure command above-market availability during peak tourism windows. Three archetypes dominate: multinational brand licensors with airport concession control, domestic integrated operators with technician training academies, and telematics-native specialists with real-time asset optimization. Competitive moves concentrate on direct airport concession acquisitions and cloud-native reservation platform deployment.
Among Brazil-based integrated operators, Localiza&Co and Unidas exemplify the fleet-scale archetype with captive infrastructure investment. Enterprise Rent-A-Car represents multinational brand licensing with direct concession relationships. Movida occupies the telematics-native positioning with connected fleet capabilities. These three anchors illustrate how vertical integration, brand licensing, and technology differentiation carve distinct competitive territories across Mexican and Brazilian tourism corridors.
| Leading Market Players |
|---|
| Enterprise Rent-A-Car |
| Avis Car Rental |
| Localiza&Co |
| Element Fleet Management |
| Budget Car Rental |
| Movida |
| Hertz |
| Arval |
| Unidas |
| Others |
Pricing and Supply Chain Analysis
Brazil's ANVISA-aligned commercial vehicle inspection protocols gate both fleet qualification and daily rate differentiation across Latin American tourism corridors. Operators absorbing accelerated compliance documentation costs capture premium positioning against fragmented local competitors lacking certified maintenance infrastructure.
Pricing Analysis
Long-term corporate offtake contracts anchor revenue predictability for fleet-scale operators serving São Paulo and Mexico City financial districts, while spot-market leisure rentals concentrate margin volatility around Yucatán Peninsula seasonal peaks. Price differentiation separates telematics-integrated fleet tiers from manual-dispatch competitors, with certification-grade maintenance records commanding loyalty premiums from risk-averse international tourists. Cost compression in sedan segments intensifies as currency fluctuations against dollar-denominated OEM supply contracts squeeze Mexican and Argentine operators. Business travelers demonstrate lowest price sensitivity, prioritizing airport proximity and express checkout over rate shopping.
Supply Chain Analysis
Brazil and Mexico anchor vehicle procurement for Latin American rental fleets, with assembly plant proximity reducing logistics overhead for operators serving southeastern beach markets and Yucatán resort corridors. Fleet replenishment draws from dollar-denominated OEM contracts, captive technician training academies, and aftermarket parts distribution networks concentrated in São Paulo and Mexico City industrial zones. Single-source vulnerability sits with consolidated OEM supply agreements that lack regional diversification. Distribution runs through direct airport concession relationships, mobile-native booking platforms, and hotel concierge counter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified fleet maintenance technician pipelines constrain turnaround capacity during peak tourism windows, creating structural scarcity that rewards operators with captive training infrastructure. This capability gap separates integrated fleet-scale players from fragmented local providers competing on price alone.
For Market Incumbents: Secure captive technician training academy expansion to sustain above-market vehicle availability during December-through-March peak windows. Deepen backward integration into predictive maintenance software development to offset telematics compliance cost elevation under Brazil's CONTRAN inspection mandates. Control direct airport concession relationships across Cancún, Mérida, and Rio de Janeiro gateway locations to lock out emerging aggregator platforms.
For New Entrants and Emerging Players: Chauffeur-driven service gaps in Argentina's premium inbound tourism segment offer protected margin pools where CNRT driver qualification standards filter competition. Target electrified fleet segments across Chile's emerging charging infrastructure corridors, where first-mover positioning captures eco-conscious adventure tourism demand. Deploy usage-based insurance models aligned with real-time telematics data as a differentiated go-to-market wedge against legacy operators.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic integrated operators lacking telematics-native technology stacks. Five-to-ten year viability hinges on fleet electrification transition timing and cross-border insurance harmonization progress. Watch for telematics data ownership framework clarifications across Andean markets as the inflection signal for platform-scale consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Real-time fleet monitoring compresses operational visibility gaps under ANVISA safety protocols. |
| Captive Technician Academy Expansion | Localiza&Co's training infrastructure sustains above-market availability in Brazilian beach markets. |
| Airport Concession Acquisition | Direct gateway control locks out aggregator platforms in Cancún and Rio de Janeiro corridors. |
| Electrified Fleet Deployment | Chile's charging infrastructure subsidies enable zero-emission positioning in adventure tourism. |
| Usage-Based Insurance Partnership | Telematics-data alignment unlocks risk-adjusted pricing for international tourist segments. |
Research Methodology
The analysis maps self-drive rental, chauffeur-driven service, and electrified fleet segments, each validated through fleet operations directors, airport concession managers, and telematics platform engineers. Primary interviews with ANVISA compliance officers, PROFECO consumer protection leads, and CNRT certification specialists combined with secondary validation against SEC filings from listed operators, Brazilian customs vehicle import records, and Mexican tourism board arrival statistics. Bottom-up fleet utilization modeling and top-down tourism expenditure triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include vehicle configuration, rental model control structure, customer origin and trip purpose, and digital acquisition channel. CAGRs derived from replacement cycle acceleration under regulatory mandates, smartphone penetration trajectories, and charging infrastructure deployment curves. Forecast inputs incorporated ANVISA inspection timeline compression effects and PROFECO-mandated pricing transparency implementation costs.
Forecasts assume regulatory continuity in Brazil's ANVISA/CONTRAN frameworks and Mexico's PROFECO disclosure standards; material policy shifts would require re-modeling. Specific risks that could revise projections include cross-border insurance harmonization failures, OEM supply contract currency renegotiations, and telematics data ownership regime changes. Recalibration cycles align with material shifts in fleet electrification subsidies and international tourism arrival patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
United States Vehicle Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Bird Carriers Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Truck Rental Market
Transportation Services
Europe Van Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
Car Rental Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Australia Taxi Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Brazil Vehicle Rental Market