
 Corporate Car Sharing Market | 2026-2036
Corporate Car Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Corporate Car Sharing Market Analysis
Germany is narrowing the gap between corporate mobility demand and available shared fleet infrastructure through dedicated urban car-sharing lanes and integrated public transit partnerships. Sixt leverages its established rental network to anchor corporate fleet operations across European business districts. Zipcar competes through technology leadership in real-time vehicle reservation systems. Enterprise CarShare sustains channel control via direct corporate account management and on-site parking privileges.
Corporate car sharing denotes a business-to-business mobility service where organizations procure pooled vehicle access for employees through centralized booking platforms, typically featuring telematics-enabled keyless entry and usage-based billing. The primary commercial purpose centers on replacing owned fleet assets with flexible, cost-allocated transportation that reduces parking footprint and administrative overhead. Full-service platforms dominate current revenue as corporations outsource fleet logistics, maintenance, and insurance bundling to specialized operators. Electric vehicles within the vehicle type dimension represent the fastest-growing category as carbon accounting requirements intensify. Subscription plans under the pricing model segment command favorable margin pools through predictable recurring revenue and lower customer acquisition costs compared to pay-per-use structures.
The EU Green Deal and associated F-Gas Regulation shape vehicle procurement standards by mandating progressive emissions reductions across corporate fleets. Germany's KBA enforces type-approval requirements that filter eligible vehicles into shared service pools. The EPA in the United States influences demand through corporate average fuel economy standards that alter fleet composition decisions. Stakeholders must monitor how evolving emissions compliance deadlines interact with charging infrastructure deployment timelines to determine optimal electrification pacing for shared corporate fleets.
Market Dynamics
Fleet electrification mandates from the EU Green Deal are compressing vehicle replacement cycles and forcing shared mobility operators to restructure procurement around battery-electric platforms with integrated charging infrastructure.
Growth Catalysts
- EU Green Deal emissions targets:The F-Gas Regulation and associated fleet decarbonization deadlines mandate progressive electrification of corporate vehicle pools, accelerating capital deployment into zero-emission shared fleets.
- Telematics-enabled keyless entry systems:Real-time vehicle access platforms reduce administrative overhead for human resources departments managing distributed workforces across multiple office locations.
- German corporate mobility budget restructuring:Employers in Berlin, Munich, and Hamburg are consolidating individual lease contracts into centralized shared vehicle pools with usage-based cost allocation.
Market Restraints
- Charging infrastructure deployment lag:Grid connection queues and permitting delays in urban centers create operational gaps between vehicle procurement and service availability.
- Residual value uncertainty for battery-electric fleets:Rapid battery technology advancement and chemistry shifts depress secondary market pricing for shared service vehicles.
- Insurance bundling complexity:Underwriters apply heterogeneous risk models to pooled corporate usage, creating premium volatility across different operator business models.
Strategic Opportunities
- Integrated public transit partnerships:Municipal transport authorities in Stuttgart and Frankfurt seek seamless first-mile last-mile connectivity through combined ticketing with corporate car-sharing platforms.
- Carbon accounting software convergence:Shared fleet operators embedding Scope 3 emissions tracking into booking platforms capture sustainability procurement mandates from ESG-focused enterprises.
- Subscription plan expansion:Fixed monthly access fees with unlimited kilometer allowances attract finance departments seeking predictable mobility budget forecasting.
Industry Challenges
- Telematics systems integration:Legacy enterprise resource planning software requires custom API development to ingest real-time vehicle utilization data from shared fleet platforms.
- Workforce electrification training:Maintenance technicians need certification in high-voltage battery systems and electric powertrain diagnostics to service expanding electric vehicle fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corporate Car Sharing Market |
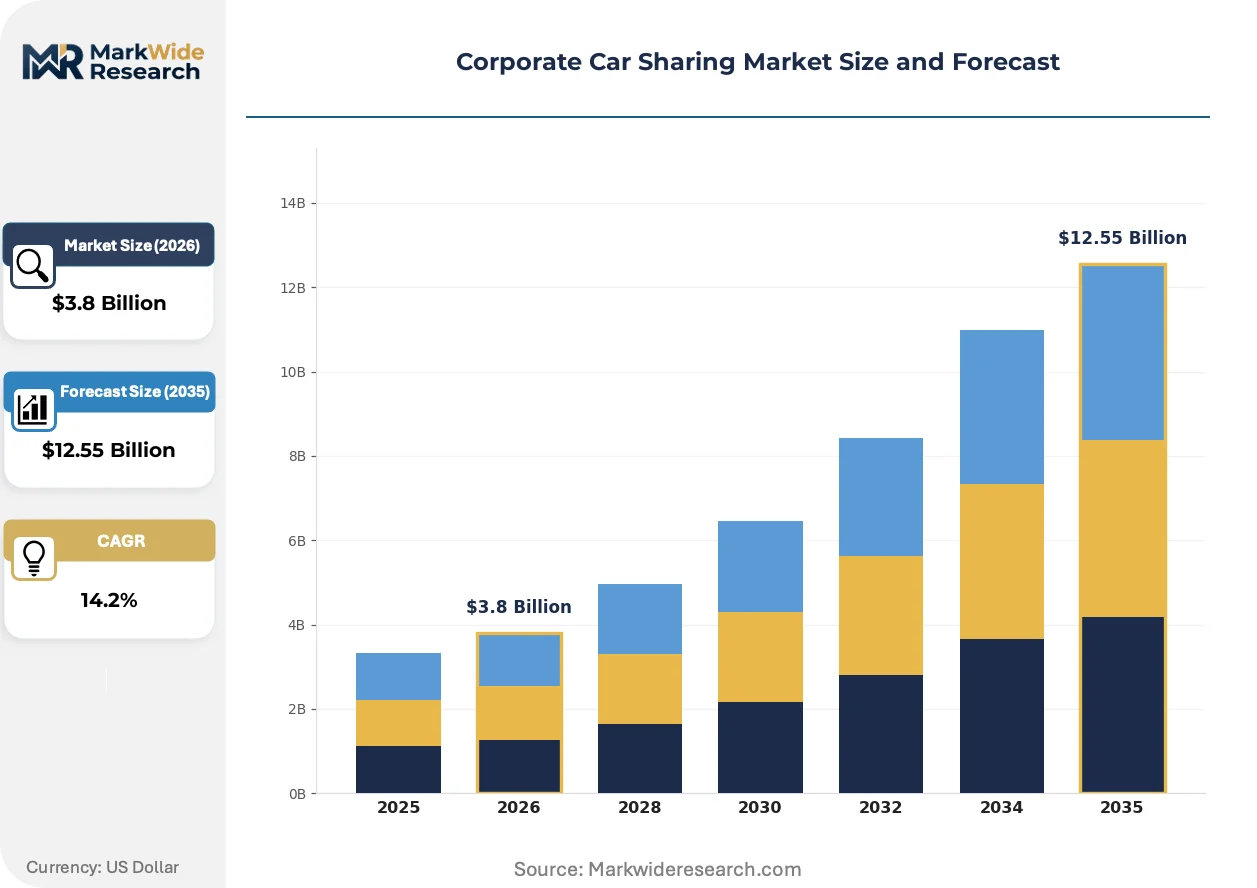
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Platforms, Peer-to-Peer Sharing, Enterprise Solutions, Managed Fleets End User: Corporations, SMEs, Non-Profits, Educational Institutions Vehicle Type: Sedans, SUVs, Vans, Electric Vehicles Pricing Model: Pay-Per-Use, Subscription Plans, Corporate Contracts, Hourly Rates |
| Companies Covered | Zipcar, Sixt, Getaround, Free2move, Turo, Mobility Carsharing, Enterprise CarShare, Communauto, SOCAR Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corporate Car Sharing Market Emerging Trajectories
Artificial intelligence route optimization and dynamic pricing algorithms are compressing vehicle idle times and maximizing asset utilization rates across distributed corporate fleets.
Machine learning predictive maintenance systems analyze telematics data streams to forecast component failures before roadside incidents occur. Fleet operators in Düsseldorf and Cologne deploy these platforms to minimize service disruptions during peak commuting periods. Traditional scheduled maintenance intervals are rendering obsolete as condition-based servicing reduces downtime and extends vehicle operational lifespans.
The EU Green Deal's binding emissions reduction trajectories force shared fleet operators to accelerate battery-electric vehicle procurement ahead of original replacement schedules. Germany's KBA type-approval requirements filter eligible models into service pools based on real-world efficiency testing. Corporate clients with net-zero commitments now specify minimum electric vehicle percentages in shared fleet contracts.
Human resources departments are consolidating individual transportation allowances into centralized mobility budgets with pooled vehicle access. Finance teams prefer subscription-based pricing with fixed monthly costs over variable pay-per-use structures that complicate accrual accounting. This procurement pattern shift concentrates purchasing authority with procurement departments rather than individual business units across technology and professional services firms.
Corporate Car Sharing Market Segmentation
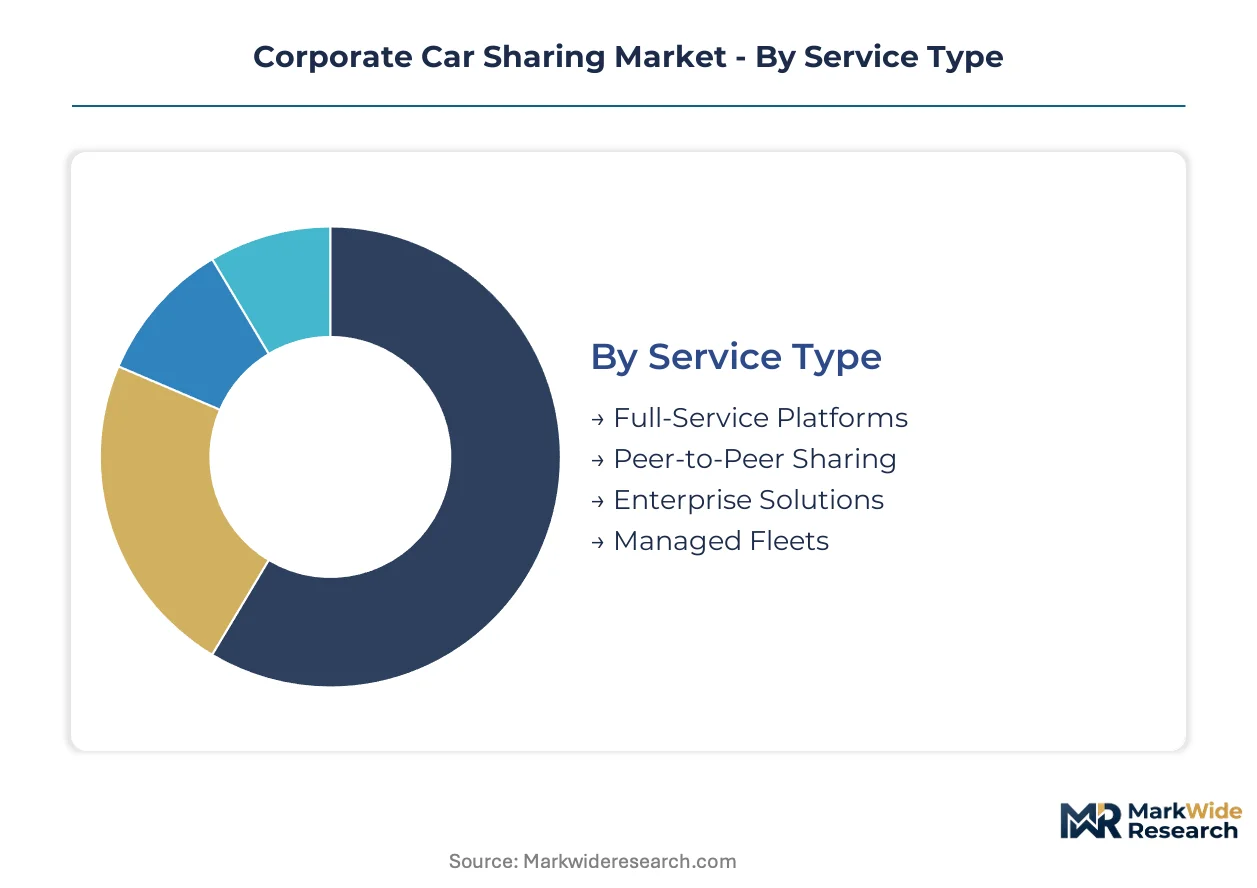
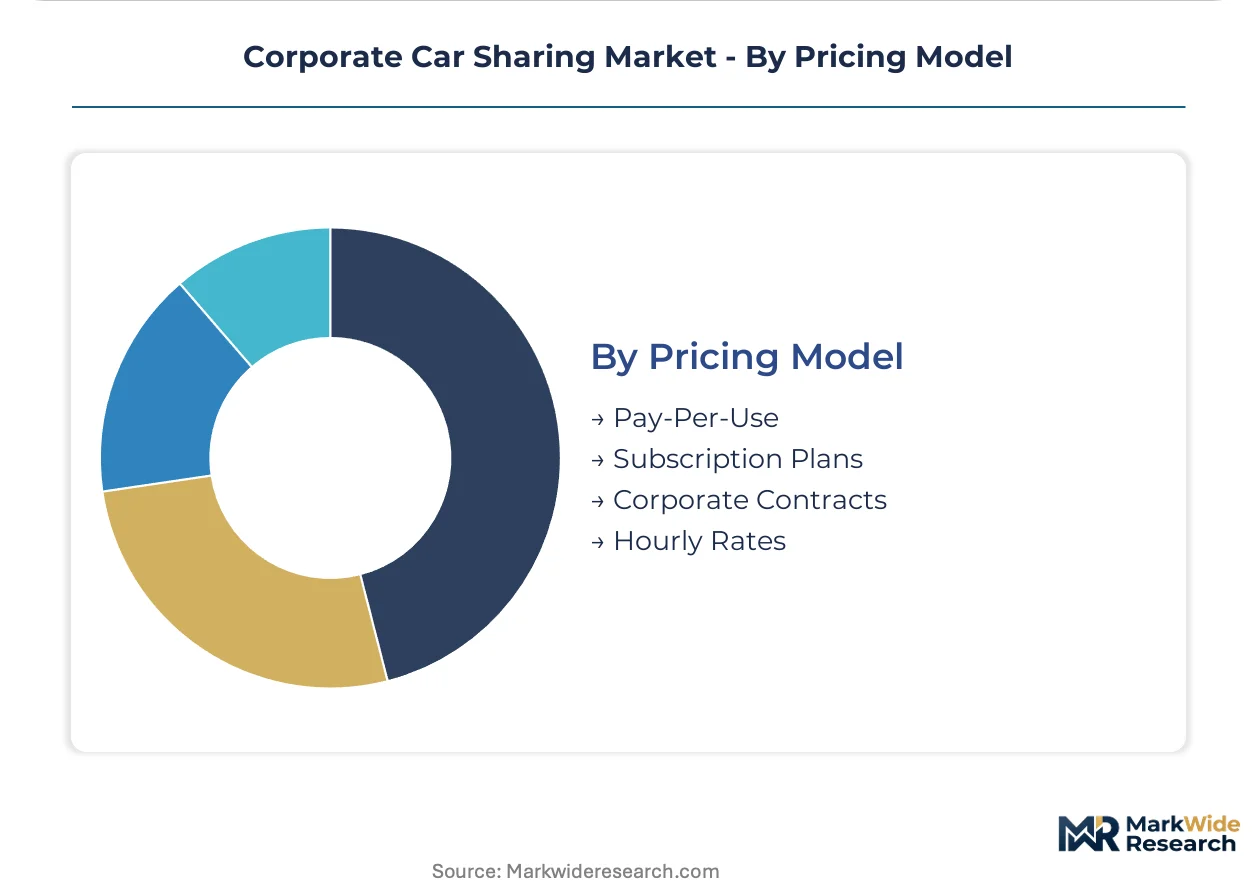
Segmentation in corporate car sharing reveals how procurement authority, vehicle specifications, and billing structures reshape fleet economics. Procurement departments select service tiers based on workforce distribution density and carbon accounting requirements. Pricing model preferences diverge sharply between finance-controlled mobility budgets and decentralized departmental spending.
Service Type:
Full-Service Platforms turn over fastest as procurement cycles compress under sustainability mandates, while Peer-to-Peer Sharing maintains longer adoption horizons due to liability framework uncertainties.
- Full-Service Platforms:Operators bundle fleet logistics, maintenance, insurance, and telematics into centralized contracts with usage-based billing. Demand concentrates among technology companies with distributed workforces across Berlin, Munich, and Hamburg as HR departments outsource mobility administration entirely.
- Enterprise Solutions:Custom-configured platforms integrate with corporate ERP systems through API layers for real-time utilization tracking. Procurement teams at professional services firms in Frankfurt and Stuttgart prioritize these configurations for consolidated carbon reporting under EU Green Deal compliance deadlines.
- Managed Fleets:Hybrid arrangements where operators retain asset ownership while corporations control booking policies and access permissions.
- Peer-to-Peer Sharing:Employee-owned vehicles enrolled in corporate pools with standardized insurance and maintenance verification.
Full-Service Platforms dominate installed base. Enterprise Solutions is where expansion concentrates.
End User:
Cost tier differentiation separates high-volume contract negotiators from price-sensitive adopters with limited procurement leverage.
- Corporations:Large enterprises with dedicated mobility budgets negotiate multi-year contracts featuring guaranteed vehicle availability and embedded carbon tracking. German automotive suppliers and chemical conglomerates in the Rhine-Ruhr corridor drive standardization of fleet electrification clauses.
- SMEs:Mid-sized enterprises access shared pools through consortium arrangements or tier-two operator networks with reduced minimum commitments.
- Educational Institutions:Universities and research institutes procure semester-based access for faculty and visiting researchers with intermittent vehicle needs.
- Non-Profits:Mission-driven organizations prioritize cost minimization over feature depth, often selecting older vehicle vintages with depreciated capital costs.
Corporations capture the premium pricing tier. SMEs represent the volume expansion opportunity.
Vehicle Type:
Technology refresh cycles vary dramatically, with battery-electric platforms replacing internal combustion assets ahead of mechanical end-of-life under regulatory pressure.
- Electric Vehicles:Battery-electric and plug-in hybrid configurations with integrated charging infrastructure and telematics-optimized range management. Fleet operators in Düsseldorf and Cologne deploy these most aggressively where municipal permitting for depot charging accelerates fastest.
- SUVs:Mid-size and full-size utility vehicles serving field service teams and executive transport with cargo capacity requirements.
- Sedans:Compact and mid-size passenger cars for single-occupant commuting and client meeting transport.
- Vans:Light commercial vehicles with payload ratings for equipment transport and multi-passenger shuttle services.
Sedans dominate current fleet composition. Electric Vehicles are climbing the fastest as KBA type-approval filters accelerate eligible model availability.
Pricing Model:
Margin structure separates predictable recurring revenue from transaction-dependent yield volatility.
- Subscription Plans:Fixed monthly fees with unlimited or tiered kilometer allowances and guaranteed vehicle class access. Finance departments at Frankfurt-based financial services firms prefer these structures for quarterly budget forecasting precision.
- Corporate Contracts:Negotiated enterprise rates with volume commitments, custom billing cycles, and dedicated account management.
- Pay-Per-Use:Variable pricing tied to actual kilometers driven, parking duration, and congestion zone entries.
- Hourly Rates:Short-term access pricing for intermittent users with unpredictable mobility needs.
Corporate Contracts anchor operator revenue stability. Subscription Plans are gaining share fastest as procurement centralization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shared fleet operators concentrate procurement and service deployment in jurisdictions with mature charging infrastructure and favorable corporate tax treatment of mobility benefits. Germany anchors European deployment volume through integrated public transit partnerships. The United States and China follow with divergent regulatory drivers shaping electrification timelines.
Germany
Mobility budget restructuring and fleet electrification mandates drive corporate adoption across the Rhine-Ruhr corridor and southern manufacturing belts. The KBA enforces stringent type-approval requirements that filter eligible battery-electric vehicles into shared service pools. Düsseldorf and Cologne operators deploy predictive maintenance platforms to minimize peak-period service disruptions.
United States
Technology companies with distributed workforces expand fleet access programs to reduce parking footprint and administrative overhead. The EPA influences fleet composition through corporate average fuel economy standards that alter procurement decisions. San Francisco and Seattle clusters lead deployment of telematics-integrated keyless entry systems for campus-based vehicle pools.
China
Dual carbon goals accelerate battery-electric vehicle procurement ahead of mechanical end-of-life schedules for legacy combustion fleets. The MIIT issues GB standards for connected vehicle telematics that shape platform interoperability requirements. Yangtze River Delta manufacturing hubs concentrate operator investment in depot charging infrastructure.
France
Enterprise clients in Île-de-France consolidate individual transportation allowances into centralized mobility budgets with pooled vehicle access. The ANSM and CNIL frameworks govern data processing for telematics platforms handling employee location information. Lyon and Marseille operators pursue integrated ticketing partnerships with municipal transport authorities.
United Kingdom
Professional services firms in London prioritize subscription-based pricing for quarterly budget forecasting precision. The FCA and Information Commissioner's Office regulate embedded insurance products and driver data privacy in corporate fleet contracts. Manchester and Birmingham clusters experiment with peer-to-peer sharing arrangements for intermittent field service needs.
Corporate Car Sharing Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in telematics hardware and charging infrastructure. The market structures around three archetypes: full-service operators bundling logistics and insurance, technology-led reservation platforms, and rental incumbents leveraging established depot networks. Consolidation pressure intensifies as electrification mandates force capital deployment at scale. Strategic moves concentrate on M&A for charging infrastructure access and API partnerships for ERP integration.
Within the full-service tier, Sixt and Enterprise CarShare anchor established positions through rental network leverage and direct corporate account management. Zipcar occupies a technology-forward position exemplifying real-time reservation platform specialization. These three entities represent divergent strategic bets: physical infrastructure depth, enterprise relationship control, and software-led user experience respectively.
| Leading Market Players |
|---|
| Zipcar |
| Sixt |
| Getaround |
| Free2move |
| Turo |
| Mobility Carsharing |
| Enterprise CarShare |
| Communauto |
| SOCAR Group |
| Others |
Supply Flow & Price Mechanics
Chinese battery cell manufacturing concentration anchors cost structures for fleet electrification, with cell chemistry procurement costs flowing directly into operator subscription pricing tiers and residual value guarantees offered to corporate clients.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across corporate car-sharing contracts, with F-Gas Regulation compliance deadlines separating premium electrified fleets from standard hybrid pools and economy-tier combustion remnants. Price differentiation rests on carbon accounting certification grade and bundled charging infrastructure access. Cost compression in economy tiers is intensifying because legacy vehicle residual values are deteriorating under accelerated phase-out schedules. SMEs exhibit the highest price sensitivity, while automotive suppliers in the Rhine-Ruhr corridor accept premium tiers for guaranteed electric vehicle availability.
Supply Chain Analysis
Export controls on semiconductor manufacturing equipment are constraining telematics hardware flows, forcing fleet operators to secure alternative chip sourcing. Supply draws from Taiwan for advanced semiconductors, South Korea for memory components, and Germany for automotive-grade sensors. Lithium carbonate, nickel cathode materials, and rare-earth permanent magnets anchor battery cost volatility. Single-source vulnerability in telematics control units creates operational risk for real-time booking platform reliability. Distribution runs through operator-owned depot networks with integrated charging infrastructure rather than third-party logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate car sharing represents a high-growth disruption as fleet electrification mandates compress replacement cycles and restructure mobility procurement around subscription-based access models.
For Market Incumbents: Build charging infrastructure moats through depot ownership in Düsseldorf and Cologne corridors where grid permitting accelerates fastest. Secure long-term battery supply agreements to lock in cell chemistry ahead of technology shifts. Consolidate telematics platform capabilities through API standardization to defend against software-led entrants eroding enterprise account control. For New Entrants and Emerging Players: Eastern European markets outside Germany's saturated Rhine-Ruhr belt offer the most penetrable white-space for fleet expansion. Target SME consortium arrangements in Poland and Czech Republic where mobility budget centralization lags Western adoption curves. Pursue municipal transit authority partnerships as the primary go-to-market angle for first-mile last-mile integration contracts. For Investors and Strategic Acquirers: Capital is best deployed toward full-service platform operators with embedded carbon tracking capabilities and existing ERP integration layers. Long-term viability centers on electrification pacing alignment with charging infrastructure deployment timelines. Monitor KBA type-approval acceleration rates for battery-electric models as the critical signal for fleet refresh cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Depot charging access in Düsseldorf and Cologne secures operational availability for electrified fleets under EU Green Deal timelines. |
| ERP Platform Integration | API connectivity with SAP and Oracle systems captures procurement centralization mandates from finance-controlled mobility budgets. |
| Carbon Accounting Software Embedding | Scope 3 emissions tracking integration addresses ESG procurement requirements from net-zero committed enterprises. |
| Predictive Maintenance Technology Deployment | Machine learning telematics analytics in Stuttgart and Frankfurt minimizes peak-period service disruptions for corporate clients. |
| Subscription Plan Expansion | Fixed monthly pricing structures attract finance departments seeking quarterly budget forecasting precision over variable pay-per-use models. |
Methodological Framework
Initial hypotheses were tested against primary input from fleet operations directors, corporate procurement managers, municipal transport authority planners, and telematics platform engineers and refined through secondary validation against SEC operator filings, KBA vehicle registration databases, EU emissions compliance registries, and customs trade data for battery component flows. Bottom-up triangulation across operator fleet deployment records and top-down reconciliation against corporate mobility budget disclosures anchored market sizing.
Demand-supply balance modeling across the analysis window incorporated service type segmentation, vehicle propulsion architecture, pricing model preference, and regional electrification pacing as core dimensions. CAGRs were derived from fleet replacement cycle compression rates and charging infrastructure deployment trajectories. Electric vehicle cost parity timelines and carbon accounting software adoption curves served as industry-specific forecast inputs.
Practitioners should monitor regulatory acceleration in EU Green Deal implementation and charging infrastructure permitting delays for early signals of forecast deviation. Forecasts reflect assumptions about battery technology cost curves and telematics platform interoperability standards. Material shifts in F-Gas Regulation enforcement timelines or lithium supply contract structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Thailand Car Rental Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Vietnam Taxi Market
Transportation Services
Refuse Truck Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
Ship Management Software Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Global Taxi Market
Transportation Services
India Car Rental Market
Transportation Services
Truck Rental Market
Transportation Services
Airline Passenger Service System Market