
 Equipment Relocation Service Market | 2026-2036
Equipment Relocation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Equipment Relocation Service Market Insights
Pharmaceutical manufacturers are redrawing equipment relocation procurement priorities, shifting from cost-centric vendor selection to validation-capable specialists. Meyer Rigging anchors its position through deep expertise in cleanroom-compliant machinery moving for FDA-regulated production lines. Gottstein Corporation differentiates via specialized rigging protocols for oversized reactor vessels and distillation columns. Deufol SE extends its footprint across European pharmaceutical clusters with integrated packaging and transport documentation services.
Equipment relocation services encompass the engineered disassembly, transport, reassembly, and calibration of industrial assets across facilities, requiring precision leveling within 0.001 inch tolerances, vibration isolation below 0.5 G, and contamination-controlled environments for sensitive instrumentation. Heavy machinery moving commands the largest revenue pool due to capital-intensive manufacturing plant reconfigurations, while IT hardware transfer generates the fastest expansion as hyperscale data center operators pursue geographic diversification of compute capacity. Laboratory equipment transport sustains premium pricing through ISO 17025 traceability requirements and specialized cold-chain maintenance for analytical devices.
FDA validation protocols, OSHA rigging standards, and EPA hazardous material transport regulations collectively elevate barrier-to-entry for service providers serving regulated industries. The EU Machinery Directive and CE conformity assessment further shape cross-border relocation complexity for equipment originating from or destined for European manufacturing sites. Stakeholders must weigh vendor certification depth against total project cost when selecting relocation partners for multi-site consolidation programs.
Market Dynamics
Semiconductor fabrication cleanroom protocols are compressing relocation timelines and forcing service providers to invest in ISO Class 1-3 compliant transport infrastructure. Equipment owners now disqualify vendors lacking particle contamination controls below 0.1 micron per cubic meter.
Growth Catalysts
- Electric vehicle battery plant construction:Germany's automotive OEMs are consolidating supplier parks near gigafactory sites, creating sustained demand for precision machinery relocation with vibration isolation below 0.5 G.
- OSHA rigging standard enforcement:United States hazardous material handling mandates are elevating service standards and filtering out uncertified operators from pharmaceutical and chemical sector contracts.
- Hyperscale data center geographic diversification:Cloud operators are redistributing compute capacity across secondary markets, accelerating IT hardware transfer volumes with zero-downtime migration requirements.
Market Restraints
- Specialized labor scarcity:Certified rigging engineers with cleanroom qualifications command wage premiums exceeding 40% above standard industrial movers, compressing margins for mid-tier providers.
- Equipment concentration risk:European semiconductor tool manufacturers dominate high-precision relocation hardware supply, creating vulnerability to single-source dependencies for air-ride suspension systems.
- CE conformity assessment complexity:EU Machinery Directive cross-border requirements add documentation overhead and extend project timelines for equipment originating from or destined for European manufacturing sites.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO-regulated API production facilities are relocating to Gujarat and Telangana clusters, creating demand for FDA-validation-capable relocation specialists.
- Modular cleanroom transport systems:Prefabricated ISO 14644-1 compliant enclosures are converging with autonomous guided vehicle platforms to enable plug-and-play facility reconfiguration.
- Carbon border adjustment mechanism preparation:EU importers are pre-positioning equipment to minimize embodied carbon exposure, generating relocation demand ahead of full CBAM implementation.
Industry Challenges
- Calibration technician shortages:Analytical instrument requalification requires ISO 17025-traceable specialists with specific OEM certification, creating bottlenecks in laboratory equipment transfer projects.
- Legacy system integration friction:Decades-old pharmaceutical production lines lack digital twin documentation, forcing manual reverse-engineering during disassembly and extending project risk windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equipment Relocation Service Market |
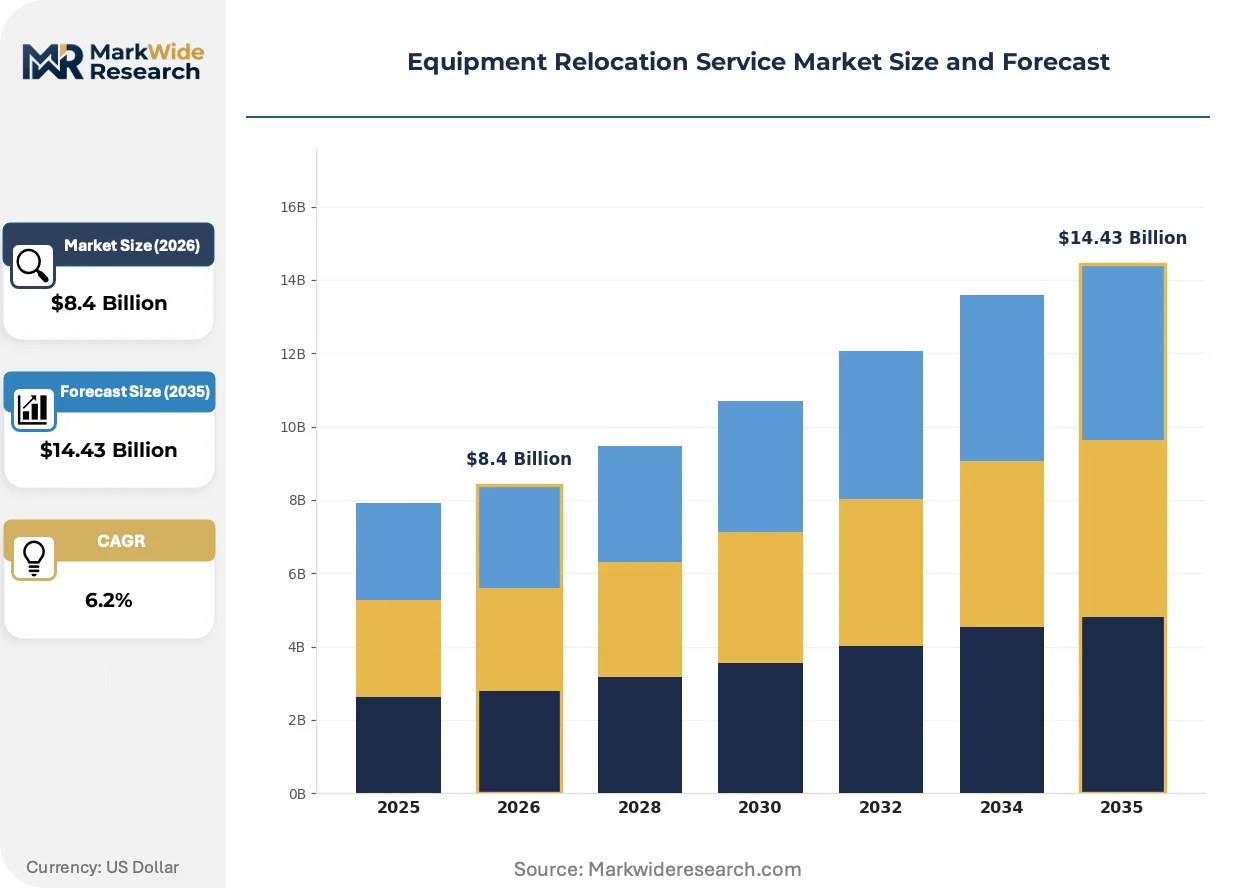
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Heavy Machinery Moving, Office Equipment Shifting, IT Hardware Transfer, Laboratory Equipment Transport, Audio Visual Relocation Application: Manufacturing Plants, Data Centers, Research Facilities, Retail Outlets, Educational Institutions Deployment Mode: On-Premise Transfer, Inter-Building Movement, Cross-City Relocation, International Shipment, Temporary Setup End User Industry: Construction Firms, Telecommunication Providers, Healthcare Providers, Financial Institutions, Event Management Companies |
| Companies Covered | SGS, AssureShift, Meyer Rigging, A&A Machinery Moving, CSM Group, Deufol SE, Gottstein Corporation, Red Carpet Movers, Modpack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equipment Relocation Service Market Trends and Innovations
Active pneumatic isolation platforms are displacing traditional spring-damped transport systems across precision manufacturing relocation. This shift reflects buyer intolerance for vibration-induced calibration drift in semiconductor metrology tools.
Air-ride suspension with real-time accelerometer feedback is displacing passive mechanical damping for lithography tool transport. Taiwan Semiconductor Manufacturing and Samsung Foundry now mandate six-axis vibration logging with sub-0.1 G threshold alarms. The technology is displacing established rigging contractors lacking sensor-integrated fleet capabilities from high-value cleanroom contracts.
EPA hazardous material transport regulations are tightening manifest documentation for lithium-ion battery production equipment containing electrolyte residues. Relocation providers must now deploy chemists for on-site neutralization before interstate movement. Pharmaceutical manufacturers in New Jersey and North Carolina are absorbing 15-20% cost premiums for certified hazmat handling during facility consolidation.
Validation bundling is consolidating equipment relocation with IQ/OQ/PQ documentation into single-source contracts. Biotechnology firms in Boston and San Diego now reject vendors offering transport-only services without in-house metrology requalification. The model is displacing fragmented procurement patterns where separate vendors handled physical movement and regulatory documentation.
Equipment Relocation Service Market Segmentation
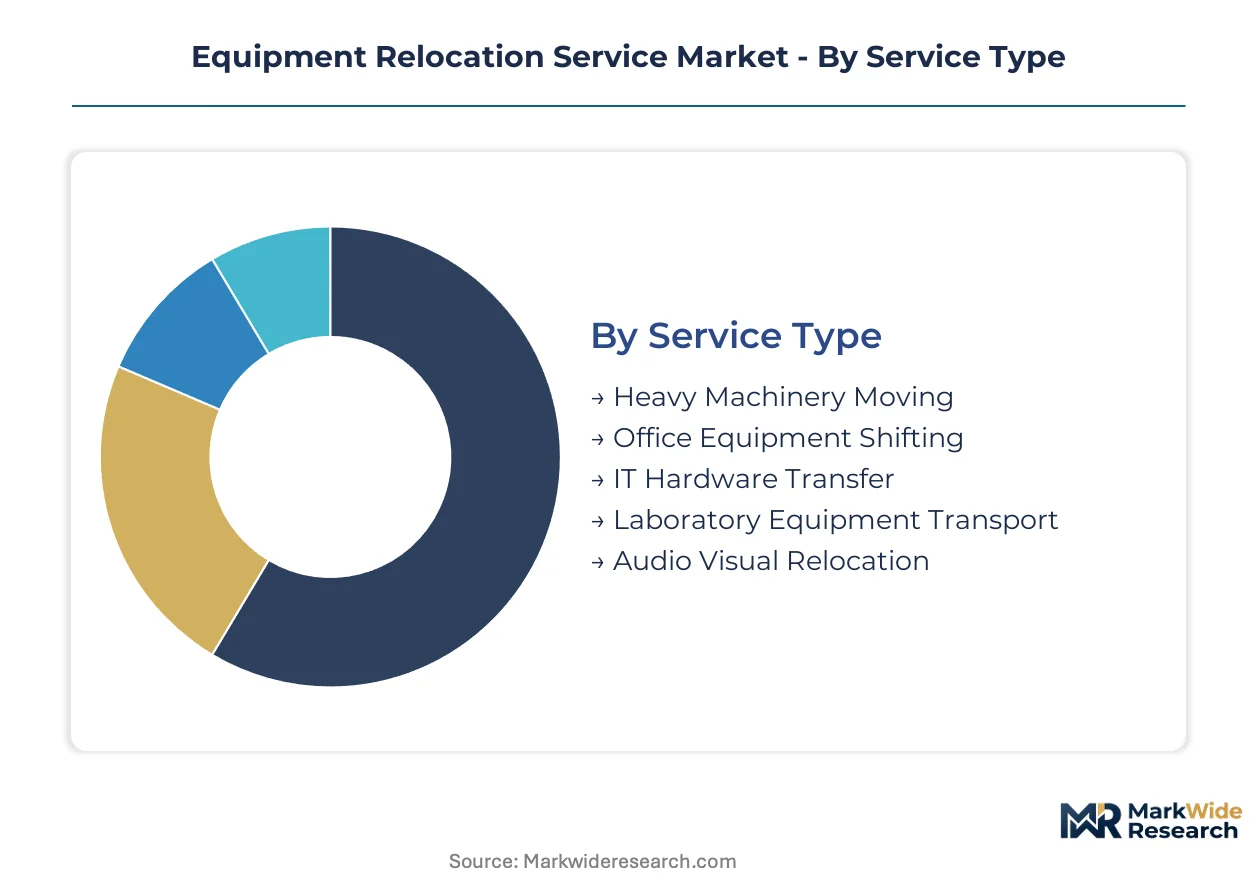
Equipment relocation service segmentation reflects divergent compliance burdens across service types and end-use industries. Regulatory stringency varies sharply between FDA-validated pharmaceutical moves and standard industrial machinery transfers, creating tiered vendor qualification requirements.
Service Type:
Regulatory differentiation separates cleanroom-qualified specialists from general industrial movers, with certification depth determining contract eligibility for regulated sectors.
- Heavy Machinery Moving:Capital-intensive manufacturing plant reconfigurations demand precision leveling within 0.001 inch tolerances and vibration isolation below 0.5 G. Automotive OEMs in Germany and semiconductor fabricators in Taiwan concentrate procurement with rigging contractors possessing ISO 14644-1 compliant transport infrastructure.
- Laboratory Equipment Transport:Analytical instrument relocation requires ISO 17025 traceability, specialized cold-chain maintenance, and OEM-certified calibration technicians. Pharmaceutical manufacturers in New Jersey and North Carolina absorb 15-20% cost premiums for validation-capable service providers.
- IT Hardware Transfer:Hyperscale data center operators mandate zero-downtime migration protocols with real-time environmental monitoring.
- Office Equipment Shifting:Standard commercial relocations prioritize speed and cost efficiency over precision specifications.
- Audio Visual Relocation:Broadcast and entertainment sector moves require specialized casing for sensitive electronic components.
Heavy machinery moving handles the majority of throughput; laboratory equipment transport is expanding most quickly on share.
Application:
Cost tier separation distinguishes capital-intensive facility reconfigurations from routine operational moves, with validation requirements scaling proportionally to equipment sensitivity.
- Manufacturing Plants:Production line reconfiguration involves engineered disassembly, transport, and recalibration of industrial assets with contamination-controlled environments for sensitive instrumentation. Electric vehicle battery plant construction in Germany is consolidating supplier parks near gigafactory sites.
- Data Centers:Cloud operators redistribute compute capacity across secondary markets, accelerating IT hardware transfer volumes with stringent uptime requirements. Hyperscale facilities in Virginia and Oregon demand six-axis vibration logging with sub-0.1 G threshold alarms.
- Research Facilities:Academic and government laboratory moves require chain-of-custody documentation for grant-funded equipment.
- Retail Outlets:Point-of-sale system relocation emphasizes rapid turnaround to minimize revenue disruption.
- Educational Institutions:Campus equipment transfers balance budget constraints with asset protection requirements.
Manufacturing plants anchor revenue concentration; data centers are climbing the fastest on contract value.
Deployment Mode:
Geographic scope determines regulatory complexity, with cross-border movements triggering conformity assessment requirements that extend project timelines.
- International Shipment:Cross-border equipment movement activates EU Machinery Directive CE conformity assessment, EPA hazardous material manifest documentation, and customs clearance protocols. Semiconductor tool manufacturers face single-source dependencies for European air-ride suspension systems.
- Cross-City Relocation:Interstate transport within the United States requires OSHA rigging standard compliance and EPA electrolyte residue neutralization for lithium-ion battery production equipment.
- On-Premise Transfer:Single-facility movement minimizes regulatory exposure and permits faster turnaround.
- Inter-Building Movement:Campus or industrial park relocations balance distance constraints with infrastructure continuity.
- Temporary Setup:Event-driven or project-based deployments prioritize modular transport systems.
Cross-city relocation handles routine volume; international shipment commands the steepest expansion trajectory.
End User Industry:
Customer type dictates procurement sophistication, with regulated industries imposing validation bundling requirements that filter out transport-only vendors.
- Healthcare Providers:Hospital and pharmaceutical manufacturing equipment relocation demands FDA validation protocols, IQ/OQ/PQ documentation, and cleanroom-compliant machinery moving. Biotechnology firms in Boston and San Diego reject vendors lacking in-house metrology requalification.
- Construction Firms:Heavy civil and commercial projects require oversized load permitting and specialized rigging for reactor vessels and distillation columns.
- Telecommunication Providers:Network infrastructure relocation emphasizes minimal service interruption.
- Financial Institutions:Data center and trading floor moves prioritize security protocols and redundancy maintenance.
- Event Management Companies:Temporary installation and teardown cycles demand rapid deployment capabilities.
Healthcare providers dominate premium contract value; construction firms sustain the highest project frequency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs are consolidating supplier parks near electric vehicle battery plants, creating sustained demand for precision machinery relocation services across European trade corridors into Central and Eastern European manufacturing zones.
United States
Semiconductor fabrication facilities in Arizona and Texas are expanding relocation budgets to minimize cleanroom contamination risks during equipment transfers. OSHA rigging standards and EPA hazardous material handling mandates are elevating service standards and filtering out uncertified operators from pharmaceutical sector contracts in New Jersey and North Carolina.
Germany
Automotive OEMs are consolidating supplier parks near gigafactory sites in Lower Saxony and Baden-Württemberg, creating sustained demand for precision machinery relocation with vibration isolation below 0.5 G. The EU Machinery Directive and CE conformity assessment shape cross-border relocation complexity for equipment destined for European manufacturing sites.
India
CDSCO-regulated API production facilities are relocating to Gujarat and Telangana clusters, creating demand for FDA-validation-capable relocation specialists. The country's national pharmaceutical regulator is tightening documentation requirements for equipment transfers into regulated manufacturing zones near Ahmedabad and Hyderabad.
China
Domestic semiconductor tool manufacturers dominate high-precision relocation hardware supply, creating single-source dependencies for air-ride suspension systems. NMPA-regulated pharmaceutical facilities in Jiangsu and Zhejiang provinces are absorbing cost premiums for cleanroom-compliant machinery moving during facility consolidation programs.
South Korea
Samsung Foundry and domestic memory manufacturers now mandate six-axis vibration logging with sub-0.1 G threshold alarms for lithography tool transport. National industrial standards are displacing established rigging contractors lacking sensor-integrated fleet capabilities from high-value cleanroom contracts in the Seoul Capital Area.
Equipment Relocation Service Market Competitive Landscape
Player mix skews toward specialized rigging contractors with cleanroom qualifications and validation-capable service integrators. Market structure concentrates around mid-sized regional specialists rather than diversified industrial conglomerates. Three archetypes dominate: FDA-validation specialists serving pharmaceutical manufacturers, precision semiconductor tool movers with ISO Class 1-3 infrastructure, and heavy machinery riggers for automotive and chemical plant reconfiguration. Competitive moves center on certification depth expansion and geographic clustering near electric vehicle battery plant construction zones.
Within the validation-specialist tier, Meyer Rigging and Gottstein Corporation exemplify archetypes serving regulated manufacturing sectors. Deufol SE occupies a position among European-integrated service providers with packaging and documentation capabilities. These three anchors represent distinct competitive vectors: cleanroom-compliant machinery moving for FDA-regulated production lines, specialized rigging protocols for oversized reactor vessels, and integrated transport documentation services across pharmaceutical clusters.
| Leading Market Players |
|---|
| SGS |
| AssureShift |
| Meyer Rigging |
| A&A Machinery Moving |
| CSM Group |
| Deufol SE |
| Gottstein Corporation |
| Red Carpet Movers |
| Modpack |
| Others |
Pricing and Supply Chain Analysis
Specialized fleet capacity utilization above 85% in Taiwan and South Korea anchors price floors for precision semiconductor tool transport, while underutilized general rigging capacity in Eastern Europe compresses margins for standard industrial moves. This scale asymmetry concentrates supply-side pricing power with ISO Class 1-3 certified operators and fragments procurement leverage across mid-tier buyers.
Pricing Analysis
Next-generation sensor-integrated air-ride suspension commands 35-50% premiums over passive mechanical damping systems for lithography tool transport. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validation-capable specialists from OSHA-compliant generalists and uncertified local movers. Price differentiation hinges on ISO 17025 traceability depth and real-time vibration logging capabilities. Cost compression in the standard tier is intensifying because automotive OEMs are consolidating supplier parks and forcing volume discounts. Pharmaceutical manufacturers in regulated clusters show least price sensitivity; retail and educational institutions absorb highest procurement friction.
Supply Chain Analysis
Air-ride suspension system manufacturing concentrates in Germany, Taiwan, and South Korea, creating single-source chokepoints for six-axis vibration isolation hardware. European semiconductor tool manufacturers draw from specialized steel foundries in Austria and precision sensor suppliers in Japan. Supply chain risk centers on tariff exposure for Chinese-manufactured active pneumatic components entering US and EU markets. Distribution runs through rigging contractors with captive maintenance capabilities and OEM-certified calibration technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers creates niche opportunities as validation bundling displaces transport-only vendors from pharmaceutical and biotechnology contracts.
For Market Incumbents: Secure FDA-validation-capable technician pipelines through apprenticeship partnerships with community colleges in New Jersey and North Carolina. Expand ISO 14644-1 compliant fleet capacity near emerging electric vehicle battery plant construction zones in Lower Saxony and Telangana. Vertical integration into metrology requalification services defends margin position against emerging validation-specialist entrants. For New Entrants and Emerging Players: Fast-track CDSCO certification through Gujarat and Telangana regulatory liaison partnerships to penetrate India's API production facility relocation market. Target modular cleanroom transport system integration with autonomous guided vehicle platforms as the most penetrable white-space segment. Lead with plug-and-play facility reconfiguration pilots at under-served research facilities in secondary US markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-integrated fleet operators over legacy mechanical damping rigging contractors. Long-term viability rests on certification depth moats rather than geographic coverage scale. Acquisition target archetype: regional specialists with ISO 17025 traceability infrastructure and existing pharmaceutical client relationships. Watch for inflection when semiconductor fabricators mandate sub-0.05 G vibration thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Depth Expansion | FDA and ISO 17025 credentials unlock pharmaceutical contracts in Boston and San Diego clusters. |
| Sensor-Integrated Fleet Deployment | Six-axis vibration logging meets Samsung Foundry and TSMC lithography tool transport mandates. |
| Geographic Clustering Near Gigafactories | Proximity to Lower Saxony and Baden-Württemberg battery plants captures automotive OEM procurement. |
| Validation Bundling Integration | IQ/OQ/PQ documentation consolidation displaces fragmented procurement in biotechnology sectors. |
| Modular Cleanroom Transport Development | Prefabricated ISO 14644-1 enclosures enable rapid facility reconfiguration for pharmaceutical manufacturers. |
Research Methodology
Desk research of customs trade databases, SEC equipment capex filings, and semiconductor tool manufacturer technical specifications preceded structured interviews with rigging operations directors, pharmaceutical facility engineers, and cleanroom compliance officers. Primary fieldwork with FDA-validation specialists and automotive plant logistics managers cross-referenced against secondary validation from EPA hazardous material transport records and EU Machinery Directive conformity assessment databases. Bottom-up project pipeline analysis triangulated with top-down end-use industry capital expenditure tracking.
Variance decomposition across service type, end-use industry, and geographic deployment mode shaped analytical framework construction throughout the forecast period. Segmentation dimensions modeled include equipment sensitivity tier, regulatory compliance burden, and facility scale category. CAGRs were derived from weighted average of historical relocation project frequency and forward-looking capital investment announcements. Industry-specific forecast inputs incorporated electric vehicle battery plant construction timelines and hyperscale data center geographic diversification patterns.
Decision-makers should treat outputs as directional under assumptions of sustained OSHA enforcement intensity and stable EU Machinery Directive interpretation; material deviation in regulatory stringency would warrant model refresh. Practitioners should keep alternative scenarios live as CBAM implementation timelines and semiconductor fabrication cleanroom protocol evolution reshape equipment relocation demand patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Global Garbage Truck Market
Transportation Services
India Car Rental Market
Transportation Services
Corporate Car Sharing Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
MUV Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Bird Carriers Market
Transportation Services
ASEAN Taxi Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Scooter Rental Market