
 Australia Architectural Coatings Market | 2026-2036
Australia Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Architectural Coatings Market Outlook
Skilled applicator shortages across Queensland and Western Australia is unwinding project timelines and pushing contractors toward simplified water-based systems that demand less specialized training. DuluxGroup leverages its national distribution network to secure shelf space in independent hardware channels throughout regional Australia. PPG Industries, Inc. anchors its position through automotive-refinish technology transfer into architectural-grade epoxy formulations. Akzo Nobel N.V. competes on premium interior pigment chemistry for designer-specified residential projects.
Australia architectural coatings encompass solvent-borne and water-borne films applied to building substrates for protection, decoration, and environmental resistance, typically formulated with acrylic, alkyd, or epoxy binders at 30-50% volume solids for brush, roller, or spray application. Their primary purpose spans weatherproofing exterior masonry, inhibiting corrosion on structural steel, and delivering aesthetic finish layers across residential, commercial, and institutional envelopes. Interior Paints command the largest revenue pool due to shorter repaint cycles in rental housing stock, while Water-Based formulations capture the fastest trajectory as VOC thresholds tighten and contractor preferences shift toward faster recoat windows. The DIY Consumers segment remains structurally significant in Australia's dispersed regional markets where professional labor availability constrains project scheduling.
TGA oversees chemical ingredient notification requirements for coatings marketed in Australia, while the Building Code of Australia mandates fire-performance ratings on specified substrate applications, effectively filtering out non-compliant imported alkyd systems. State-level EPA offices in Victoria and New South Wales enforce additional VOC limits that exceed federal baselines, creating a patchwork compliance burden for national distributors. Stakeholders must monitor pending revisions to the National Construction Code and anticipate whether Green Star certification criteria will extend from commercial into multi-residential specifications.
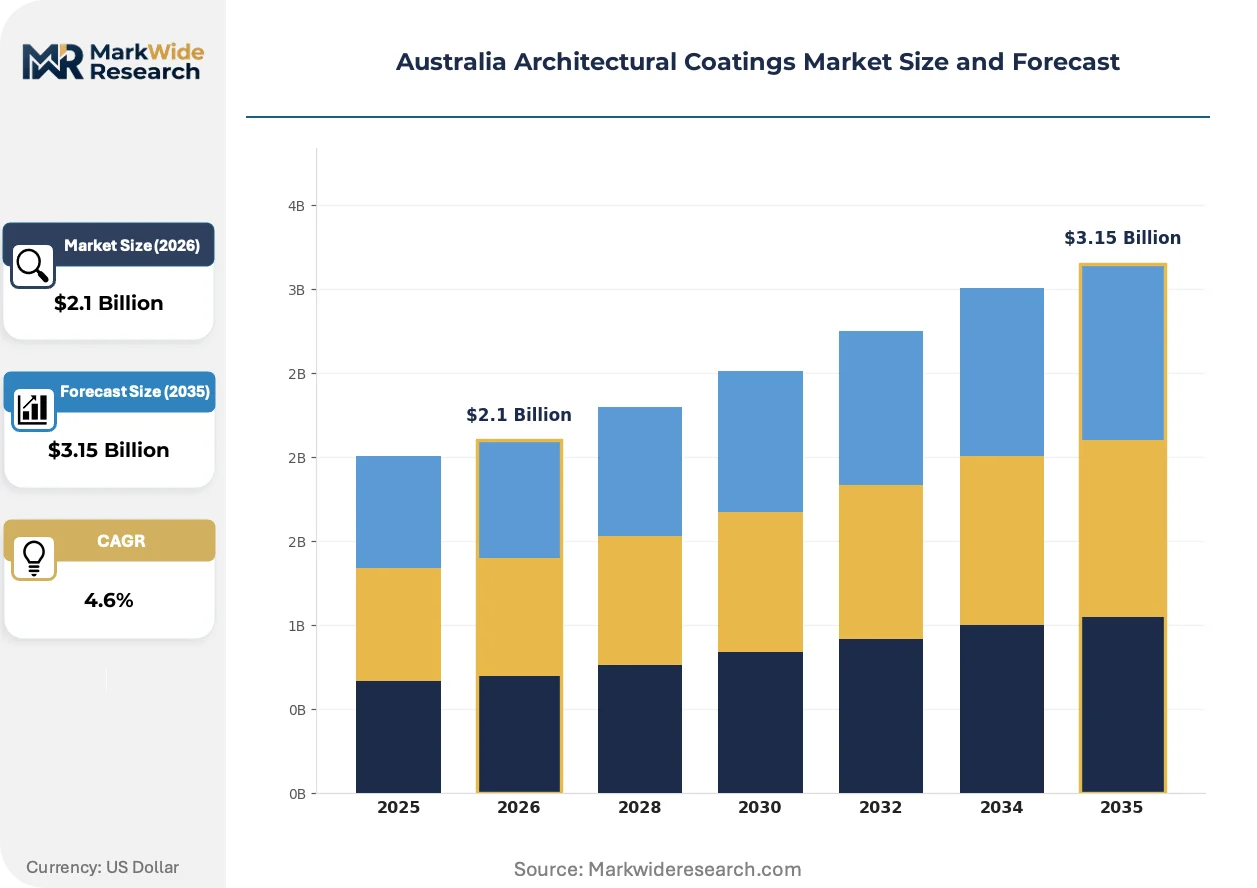
Market Dynamics
Tightening VOC thresholds under the Building Code of Australia and state-level EPA mandates are compressing solvent-borne formulation margins while redirecting R&D investment toward water-based acrylic systems with faster recoat properties.
Growth Catalysts
- New South Wales residential renovation pipeline:High-density corridor projects in Sydney are specifying low-VOC interior finishes to meet strata compliance deadlines, pulling volume through independent hardware channels.
- TGA chemical notification alignment:Streamlined ingredient disclosure requirements reduce import friction for compliant water-borne systems, accelerating product registration cycles.
- Epoxy technology transfer:Automotive refinish-grade durability standards are migrating into commercial architectural specifications, opening specification pathways for high-performance floor and structural steel coatings.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin predictability for mid-tier interior paint portfolios, forcing reformulation toward alternative opacifiers with performance trade-offs.
- Queensland applicator scarcity:Skilled labor shortages in regional markets extend project timelines and limit uptake of multi-coat solvent systems requiring specialized spray certification.
- Green Star certification gaps:Absence of mandatory multi-residential criteria leaves sustainability premiums uncaptured in volume housing segments, constraining eco-formulation ROI.
Strategic Opportunities
- Victorian commercial refurbishment precincts:Melbourne's aging office stock faces mandatory fire-performance upgrades under BCA Section J, creating specification windows for intumescent epoxy systems.
- DIY channel digitization:Regional consumers in Western Australia and Tasmania are migrating toward click-and-collect platforms, opening direct-to-contractor bypass routes for national distributors.
- National Construction Code revision pipeline:Pending 2025 updates to condensation management provisions may mandate breathable membrane coatings in new residential envelopes.
Industry Challenges
- Spray applicator certification bottlenecks:VOC-compliant water-based epoxies demand modified equipment calibration, but training infrastructure lags in Perth and Adelaide metro markets.
- Fire-rating test timeline compression:BCA substrate-specific approvals require 12-18 month AS 1530.4 validation cycles, delaying product launches for reformulated intumescent lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Architectural Coatings Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Paints, Exterior Paints, Primers, Sealers Application: Residential, Commercial, Industrial, Institutional Formulation: Acrylic, Alkyd, Epoxy, Water-Based End User: Contractors, DIY Consumers, Architects, Interior Designers |
| Companies Covered | PPG Industries, Inc., Nippon Paint Holdings Co., Ltd., Hempel A/S, Jotun, Resene Group, Haymes, DuluxGroup, Akzo Nobel N.V., A&I Coatings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Architectural Coatings Market Strategic Shifts
Formulation chemistry and application protocols are diverging along performance-versus-convenience axes, with contractor labor constraints and specification complexity driving parallel innovation tracks rather than unified standards.
Self-crosslinking water-borne acrylic technology is bifurcating the mid-market interior segment. Specifiers in Sydney's high-rise residential towers are specifying these systems for same-day recoat schedules. The technology is compressing traditional alkyd market share in rental housing repaint cycles where downtime carries penalty clauses.
Victoria's EPA has enacted VOC limits exceeding federal baselines, creating a compliance patchwork that fragments national product portfolios. Importers must maintain separate SKUs for state-specific markets. Queensland and New South Wales contractors are consolidating procurement around dual-compliant formulations to simplify inventory exposure.
Builder preferences are fragmenting specification authority away from architects toward direct contractor-procurement agreements. Volume residential developers in Melbourne's outer corridors are bundling coatings into fixed-price construction contracts. This pattern concentrates buying power with national distributors holding warehouse presence across multiple state EPA jurisdictions.
Australia Architectural Coatings Market Segmentation
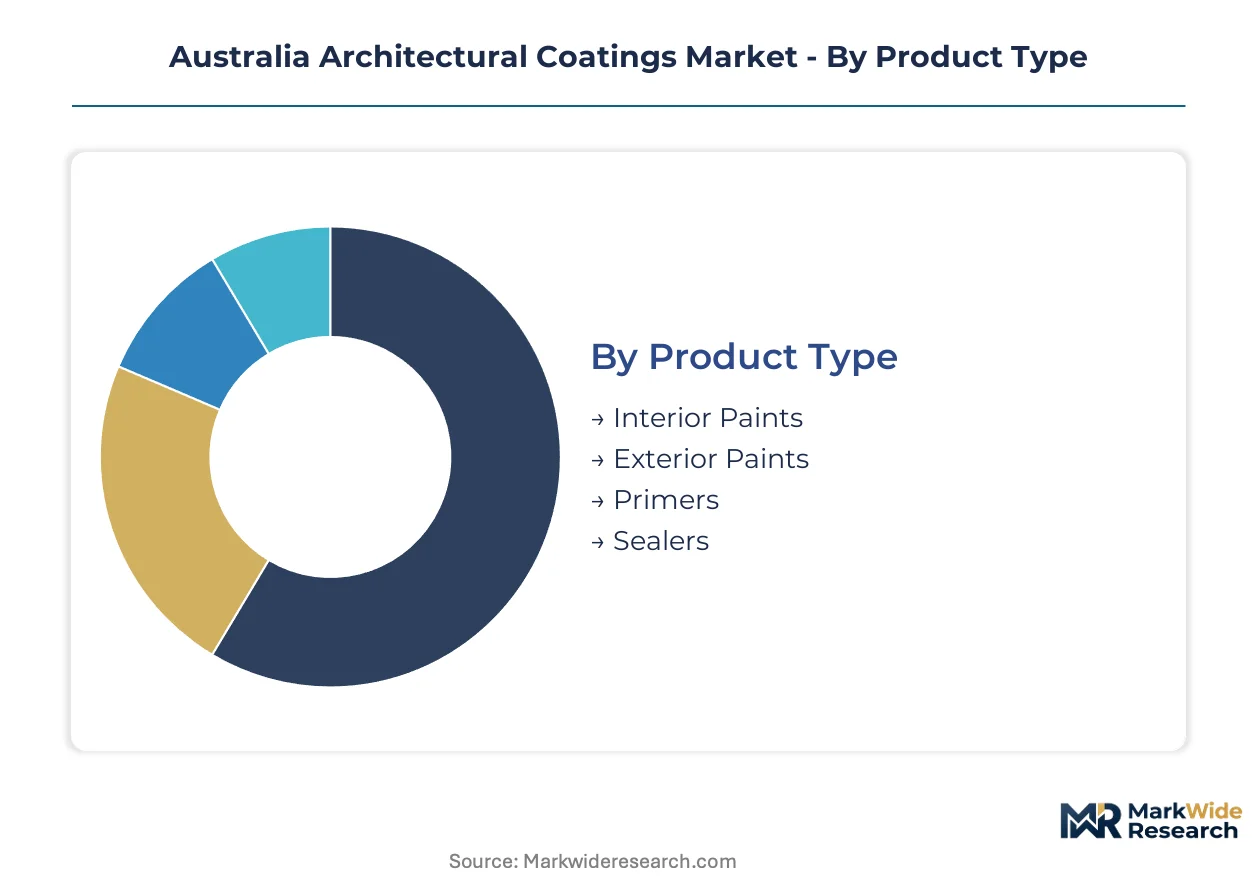
Segmentation in Australian architectural coatings reveals how regulatory geography and labor availability reshape procurement patterns. TGA-aligned chemical standards and state-level EPA thresholds fragment product portfolios across domestic markets. Understanding these divides exposes where formulation investments align with enforceable compliance windows versus speculative sustainability premiums.
Product Type:
Interior Paints and Exterior Paints dominate domestic manufacturing capacity, while Primers and Sealers see heavier import dependence from Southeast Asian supply bases.
- Interior Paints:Formulated at 30-45% volume solids with acrylic or alkyd binders for walls, ceilings, and trim surfaces. Demand concentrates in Sydney's high-density residential corridor where strata compliance deadlines accelerate repaint cycles in rental housing stock. Shorter recoat windows favor water-based acrylic systems that compress project timelines for contractors facing penalty clauses.
- Exterior Paints:Engineered with higher pigment loading and UV-resistant binders to withstand Australia's solar exposure on masonry, timber, and metal substrates. Melbourne's commercial refurbishment precincts are specifying these systems for weatherproofing aging envelopes under mandatory fire-performance upgrade schedules. BCA Section J compliance is redirecting procurement toward intumescent-capable formulations.
- Primers:Adhesion-promoting films applied to bare substrates before topcoat application, typically alkyd-based for timber or epoxy-based for steel.
- Sealers:Low-viscosity penetrating formulations for porous masonry and concrete surfaces, critical for moisture management in Queensland's tropical construction zones.
Interior Paints commands the established base. The steepest expansion runs through Exterior Paints.
Application:
Residential and Commercial applications absorb the bulk of water-based formulation output, while Industrial and Institutional segments retain solvent-borne demand for corrosion resistance specifications.
- Residential:Encompasses single-family dwellings, multi-unit housing, and renovation activity across detached and attached formats. New South Wales renovation pipelines in Sydney's inner-ring suburbs are pulling volume through independent hardware channels as owners respond to strata compliance deadlines. Low-VOC interior finishes are becoming default specifications in high-density towers.
- Commercial:Covers office buildings, retail spaces, and hospitality venues requiring durable, maintainable finishes. Melbourne's aging office stock faces mandatory BCA Section J fire-performance upgrades, creating specification windows for intumescent epoxy systems on structural steel and floor coatings. Refurbishment timelines are compressing as lease rollover dates force accelerated project delivery.
- Industrial:Manufacturing facilities, warehouses, and logistics centers demanding chemical-resistant, abrasion-tough films.
- Institutional:Schools, hospitals, and government buildings subject to extended durability warranties and public procurement protocols.
Residential anchors volume throughput. Commercial is climbing the fastest as refurbishment mandates tighten.
Formulation:
Water-Based and Acrylic systems align with tightening VOC thresholds, while Alkyd and Epoxy formulations serve performance segments where solvent content remains permissible.
- Acrylic:Thermoplastic resin systems offering color retention, flexibility, and rapid drying for interior and exterior architectural applications. Self-crosslinking water-borne acrylic technology is bifurcating the mid-market interior segment as Sydney high-rise specifiers demand same-day recoat schedules. The technology is compressing traditional alkyd market share in rental housing repaint cycles.
- Water-Based:Emulsion systems with VOC content below state EPA thresholds, using water as primary carrier. Victoria's EPA has enacted limits exceeding federal baselines, creating a compliance patchwork that fragments national product portfolios. Queensland and New South Wales contractors are consolidating procurement around dual-compliant formulations to simplify inventory exposure.
- Alkyd:Oil-modified polyester resins providing gloss retention and flow characteristics for trim and door applications.
- Epoxy:Two-component thermoset systems delivering chemical resistance and adhesion for floors, steel, and high-wear surfaces.
Acrylic holds the dominant position. Water-Based is gaining share fastest as regulatory thresholds harden.
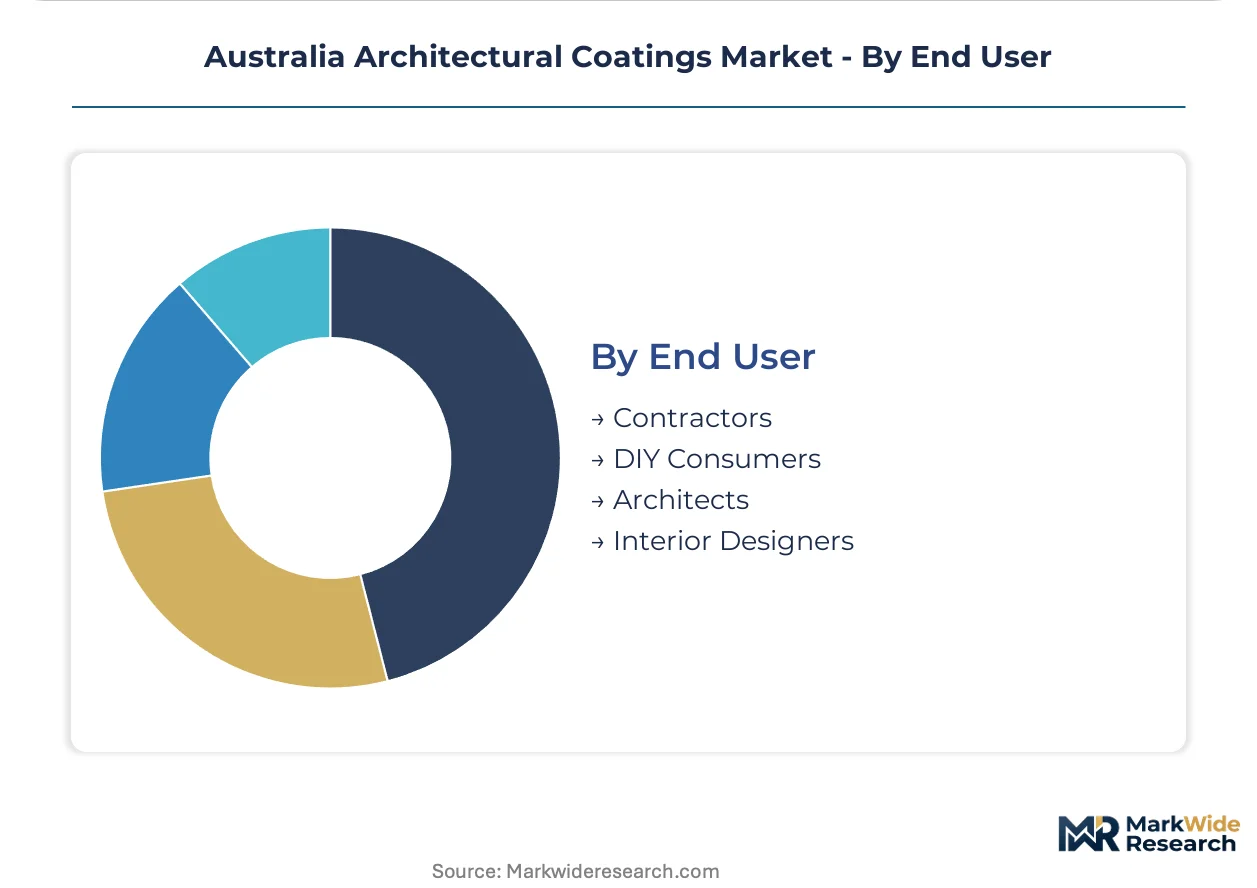
End User:
Contractors and DIY Consumers drive volume through distinct channel configurations, while Architects and Interior Designers exercise specification influence on premium residential and commercial projects.
- Contractors:Professional applicators executing new construction and refurbishment projects under fixed-price or time-and-materials agreements. Builder preferences are fragmenting specification authority away from architects toward direct contractor-procurement agreements in Melbourne's outer corridors. Volume residential developers are bundling coatings into construction contracts, concentrating buying power with national distributors.
- DIY Consumers:Homeowners and property managers purchasing through retail channels for self-application. Regional consumers in Western Australia and Tasmania are migrating toward click-and-collect platforms, opening direct-to-contractor bypass routes. Australia's dispersed regional markets sustain this segment where professional labor availability constrains project scheduling.
- Architects:Design professionals specifying finishes for aesthetic and performance criteria in commercial and institutional projects.
- Interior Designers:Residential and hospitality specialists selecting premium pigment chemistry for designer-specified environments.
Contractors control the volume base. DIY Consumers is expanding most quickly as digital channels penetrate regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TGA chemical notification requirements and the Building Code of Australia establish the regulatory baseline that shapes state-level procurement patterns across the country's construction corridors.
New South Wales
Sydney's high-density residential corridor drives demand for low-VOC interior finishes as strata compliance deadlines accelerate repaint cycles. The state's EPA enforces VOC limits that exceed federal baselines, filtering non-compliant imported alkyd systems from specification lists. Independent hardware channels throughout Greater Sydney and Wollongong are consolidating procurement around dual-compliant water-based acrylic formulations.
Victoria
Melbourne's aging commercial office stock faces mandatory BCA Section J fire-performance upgrades, creating specification windows for intumescent epoxy systems. The Victorian EPA has enacted the nation's strictest VOC thresholds, fragmenting national product portfolios into state-specific SKUs. Refurbishment precincts in the CBD and inner suburbs are compressing project timelines as lease rollover dates force accelerated delivery schedules.
Queensland
Skilled applicator shortages across Brisbane and regional markets extend project timelines and limit uptake of multi-coat solvent systems. The state's tropical construction zones sustain demand for penetrating sealers formulated for moisture management on porous masonry. Gold Coast and Sunshine Coast residential developments are bundling coatings into fixed-price construction contracts, concentrating buying power with national distributors.
Western Australia
Perth metro markets face spray applicator certification bottlenecks as VOC-compliant water-based epoxies demand modified equipment calibration. Regional consumers throughout the state are migrating toward click-and-collect platforms, opening direct-to-contractor bypass routes for national distributors. DIY activity remains structurally significant in dispersed regional markets where professional labor availability constrains project scheduling.
South Australia
Adelaide's construction pipeline reflects slower uptake of self-crosslinking water-borne acrylic technology due to lagging training infrastructure. State-level procurement patterns favor simplified water-based systems that demand less specialized applicator certification. The city's commercial refurbishment activity remains subdued compared to eastern state capitals, moderating specification pressure for high-performance epoxy formulations.
Australia Architectural Coatings Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Australian architectural coatings market. The vendor base clusters around three tiers: multinational chemical conglomerates with integrated resin capabilities, regional specialists with state-level distribution density, and import-dependent niche formulators serving premium specification segments. Consolidation pressure concentrates in the mid-market interior segment where self-crosslinking acrylic technology is compressing traditional alkyd share. Dominant competitive moves include strategic partnerships with national hardware distributors and portfolio diversification toward fire-performance-compliant epoxy systems.
Within the multinational tier, PPG Industries, Inc. and Akzo Nobel N.V. occupy positions anchored by technology transfer capabilities and premium pigment chemistry respectively. DuluxGroup exemplifies the regional specialist archetype through national distribution network density in independent hardware channels. These three entities represent the competitive anchors around which mid-tier and niche players position for specification access in state-fragmented regulatory environments.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Hempel A/S |
| Jotun |
| Resene Group |
| Haymes |
| DuluxGroup |
| Akzo Nobel N.V. |
| A&I Coatings |
| Others |
Value Chain & Pricing Dynamics
Titanium dioxide substitution toward alternative opacifiers is fragmenting procurement economics across state EPA jurisdictions while compressing margin predictability for mid-tier interior portfolios. This input shift simultaneously redirects supply geography toward Southeast Asian pigment producers and intensifies price competition in rental housing repaint segments where penalty clauses dominate contractor decision-making.
Pricing Analysis
Price spreads between Victoria's strictest-compliant formulations and federal-baseline products exceed transport-cost differentials across the Tasman Sea corridor. Three-tier pricing structure across premium, standard, and economy levels stratifies by VOC compliance grade and fire-performance certification, with premium tiers capturing designer-specified residential projects. Cost compression in standard interior acrylics is intensifying because titanium dioxide feedstock volatility forces reformulation trade-offs. DIY Consumers in Western Australia and Tasmania exhibit highest price sensitivity due to click-and-collect platform transparency, while Architects specifying Melbourne commercial refurbishments show lowest sensitivity contingent on BCA Section J compliance guarantees.
Supply Chain Analysis
Inbound container availability through Port Botany and Port of Melbourne constrains just-in-time delivery windows for water-borne resin imports. Manufacturing concentration centers on China, Thailand, and domestic Australian plants for acrylic emulsions, while epoxy hardeners and specialty pigments draw from South Korea and Japan. Raw material dependencies include titanium dioxide from Chinese sulfate-process producers, water-borne acrylic resins from Thai petrochemical complexes, and epoxy curing agents from Japanese specialty chemical houses. Single-source vulnerability runs through titanium dioxide feedstock where sulfate-process capacity concentration creates price spike exposure. Distribution runs through national distributors holding warehouse presence across multiple state EPA jurisdictions, with independent hardware channels serving regional Queensland and Western Australia markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian architectural coatings market rewards players who control certified applicator pipelines, as Queensland and Western Australia shortages extend project timelines and limit specification access for undertrained competitors. This capability gap separates incumbent national distributors from import-dependent challengers.
For Market Incumbents: Secure dual-compliant formulation portfolios that simplify contractor inventory exposure across New South Wales and Victorian EPA thresholds. Anchor channel control through exclusive shelf-space agreements in independent hardware networks throughout regional Australia. Invest in spray applicator certification infrastructure to preempt Perth and Adelaide bottlenecks before pending National Construction Code revisions mandate breathable membrane specifications. For New Entrants and Emerging Players: Lead with self-crosslinking water-borne acrylic technology targeting Sydney high-rise residential towers where same-day recoat schedules command specification premiums. Penetrate Western Australia DIY Consumers through click-and-collect platform partnerships that bypass established distributor networks. Position around moisture-management sealers for Queensland tropical construction zones where national distributors maintain weaker inventory depth. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional specialists holding Victorian distribution density but lacking fire-performance epoxy capabilities. Five-to-ten year viability hinges on consolidation capture in the mid-market interior segment where self-crosslinking technology compresses traditional alkyd share. Watch for National Construction Code revision announcements as inflection indicators for breathable membrane coating mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Compliant Formulation Development | State EPA fragmentation forces separate SKUs for Victoria versus federal-baseline markets. |
| Spray Applicator Certification Infrastructure | VOC-compliant water-based epoxies demand modified equipment calibration in Perth metro markets. |
| Click-and-Collect Platform Integration | Western Australia and Tasmania DIY Consumers migrate toward direct-to-contractor bypass routes. |
| Fire-Performance Epoxy Portfolio Expansion | Melbourne BCA Section J upgrades create specification windows for intumescent systems. |
| Independent Hardware Channel Exclusivity | DuluxGroup's national network demonstrates shelf-space control as competitive moat. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with coatings procurement managers at national distributors, technical directors at formulator facilities, and state EPA compliance officers; and secondary validation through Building Code of Australia amendment tracking, TGA chemical notification databases, and Australian Bureau of Statistics construction activity indices. Bottom-up triangulation cross-referenced contractor purchasing patterns with top-down regulatory timeline analysis.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, formulation chemistry, application segment, and end-user archetype. CAGRs derived from regression analysis against construction pipeline data and renovation cycle frequency. Industry-specific inputs included strata compliance deadline clustering in Sydney rental housing and Victorian commercial lease rollover schedules.
The analysis sits within stated boundaries; outcomes outside sustained residential renovation activity or accelerated EPA harmonization would require recalibration. Forecasts reflect assumptions about skilled labor availability and feedstock price stability. Recalibration cycles align with material shifts in National Construction Code revision timing and titanium dioxide supply contract renegotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Fiber Cement Siding Market
Building Materials
Earthen Plasters Market
Building Materials
Building Asphalt Market
Building Materials
Asia-Pacific Cement Market
Building Materials
North America Construction Aggregates Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
Indonesia Architectural Coatings Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
South Africa White Cement Market
Building Materials
Cement Tiles Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Africa Green Cement Market
Building Materials
Facade Gasket Market