
 AI in Insurance Market | 2026-2036
AI in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Insurance Market Intelligence
The historical reliance on human actuaries and underwriters for complex risk assessment is unwinding as AI models become more sophisticated. Technology providers like Microsoft Corporation offer scalable cloud infrastructure and pre-built machine learning tools for insurers. Meanwhile, established insurers such as Allstate leverage proprietary data sets to train custom fraud detection algorithms. Guidewire Software, Inc. specializes in core system platforms that embed AI capabilities for claims processing.
AI in insurance refers to the application of computational algorithms, particularly machine learning models, to analyze vast datasets for risk modeling and operational automation. Its primary commercial purpose is to improve accuracy in underwriting, reduce fraudulent claims, and personalize customer interactions. Within the application segment, claims processing and underwriting automation currently command the largest investment from insurers. Machine Learning and Predictive Analytics represent the dominant technologies, while cloud-based deployment models show the fastest adoption rate.
Regulatory frameworks such as the EU AI Act and state-level mandates in the United States are setting stringent requirements for algorithmic transparency and fairness. Data privacy rules, including Europe's GDPR and the US HIPAA for health data, govern how insurers collect and process customer information for AI models. Insurers must now balance the pursuit of efficiency gains with the escalating compliance costs and ethical considerations of model explainability.
Market Dynamics
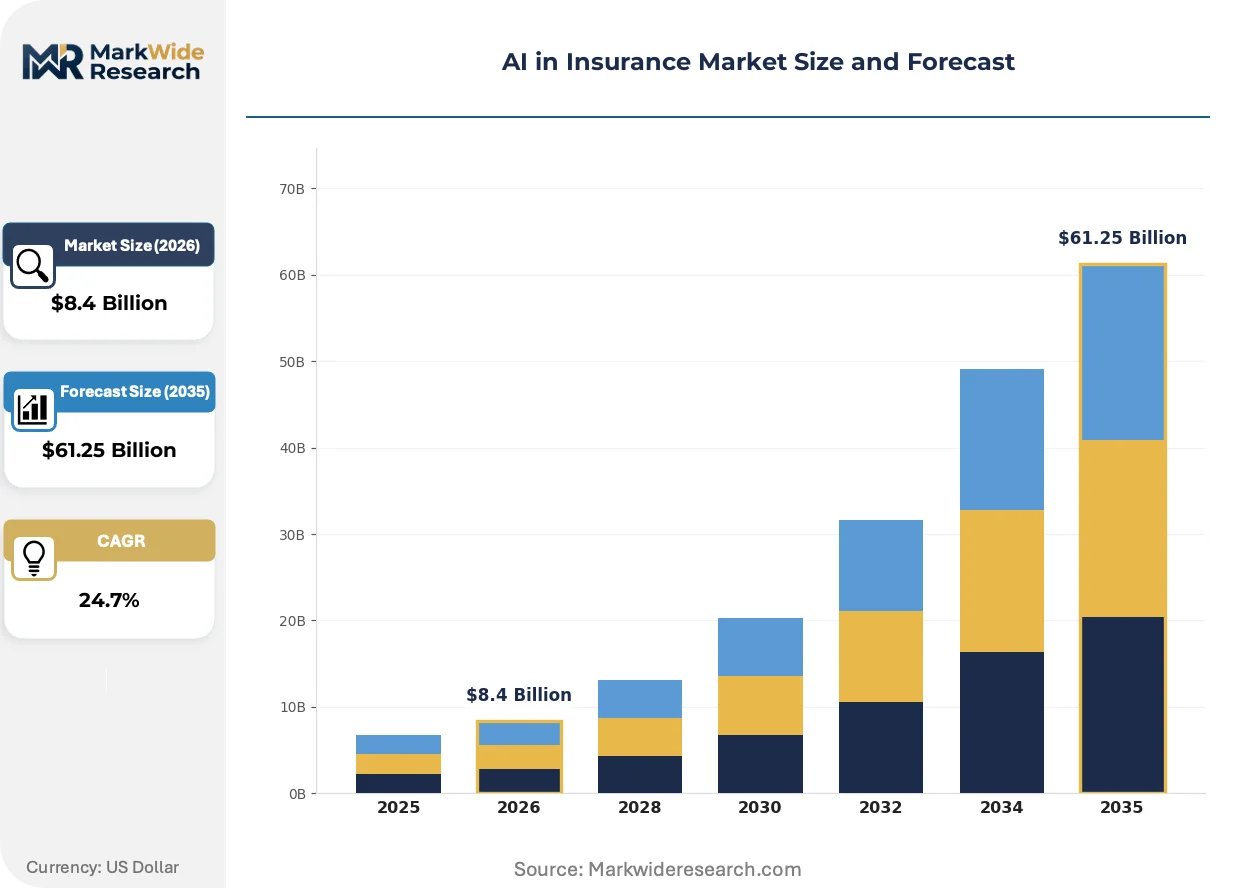
The AI in Insurance market is defined by the fundamental tension between the drive for operational efficiency through automation and the increasing stringency of global regulatory frameworks. This dynamic forces insurers to balance technological investment in machine learning with rising compliance costs for algorithmic fairness and data privacy.
Growth Catalysts
- Claims Processing Automation:The use of AI to automate the intake, analysis, and settlement of insurance claims significantly reduces manual labor and operational expenditures, directly improving insurer profitability and accelerating payout times for policyholders.
- Demand for Personalization:Consumers increasingly expect personalized insurance products and pricing. AI enables insurers to analyze vast customer datasets to offer tailored policies, dynamic premiums, and targeted services, which enhances customer acquisition and retention.
- Cloud Infrastructure Accessibility:Scalable cloud computing platforms provide the necessary computational power and data storage for training and deploying complex AI models, removing the need for massive upfront capital expenditure on on-premise hardware.
Market Restraints
- Regulatory Compliance Costs:Frameworks like the EU AI Act and various US state-level mandates impose significant compliance burdens and operational hurdles for high-risk AI systems, particularly those used in underwriting and claims assessment.
- Data Quality and Integration:Poor quality, fragmented, and siloed data within legacy insurance systems hinder the development of accurate and reliable AI models, limiting their effectiveness and creating a barrier to successful implementation.
- Model Explainability Deficits:The inherent complexity of many machine learning models creates a "black box" problem, making it difficult for insurers to explain algorithmic decisions to regulators and customers as new transparency rules require.
Strategic Opportunities
- Proactive Risk Mitigation:Deploying AI to analyze data from telematics and IoT devices allows insurers to offer proactive risk mitigation services, warning policyholders of potential hazards to reduce claim frequency and deepen customer relationships.
- Emerging Asian Markets:Insurtech adoption in Southeast Asian countries presents a significant growth vector, where mobile-first populations and rising disposable incomes create demand for AI-driven insurance products and digital distribution.
- AI and Blockchain Convergence:The combination of AI with blockchain technology offers a pathway to create immutable records of claims and automate payouts via smart contracts, which can drastically enhance transparency and combat fraud.
Industry Challenges
- Talent Scarcity:A pronounced talent gap exists for data scientists and AI specialists who also possess deep domain knowledge of the insurance industry, which slows down in-house model development and effective deployment.
- Legacy System Integration:Integrating modern AI platforms with entrenched, decades-old core insurance systems presents a major technical and financial challenge, creating implementation bottlenecks for many established carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Insurance Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $61.25 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Claims Processing, Customer Insights, Risk Assessment, Underwriting Automation, Policy Management Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotic Process Automation, Predictive Analytics, Speech Recognition Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Insurers, Brokers, Reinsurers, Third-Party Administrators, Actuaries |
| Companies Covered | IBM Corporation, Microsoft Corporation, SAP SE, Guidewire Software, Inc., SAS Institute Inc., Allstate, Nationwide, Travelers, USAA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Insurance Market Strategic Shifts & Innovations
The insurance industry's operational core is shifting from human-led assessment to algorithm-driven automation. This transition creates new paradigms for risk evaluation, customer engagement, and regulatory oversight, fundamentally altering the competitive landscape for both incumbent insurers and technology providers.
Generative AI is emerging as a powerful tool for tasks like summarizing complex claims documents, generating personalized customer communications, and creating synthetic data for model training. Insurers in property, casualty, and life insurance are beginning to pilot these systems for back-office functions. This technology is displacing significant manual effort in data entry and routine correspondence, freeing up underwriters and claims adjusters for higher-value analysis.
State-level regulations in the United States, such as those developed in Colorado and New York, are establishing new standards for algorithmic fairness and anti-discrimination in insurance pricing. These rules require insurers to prove their AI models do not produce unfairly discriminatory outcomes against protected classes. The life and auto insurance segments are most impacted, forcing vendors and carriers to invest heavily in model governance and explainability tools.
A demand-side shift toward embedded insurance is gaining momentum, where coverage is offered as an add-on at the point of sale for another product or service. This model bypasses traditional brokers, integrating AI-powered underwriting directly into e-commerce platforms, travel booking sites, and automotive sales processes. This trend is most prominent in the consumer electronics and travel industries, particularly in Europe and North America.
AI in Insurance Market Segmentation
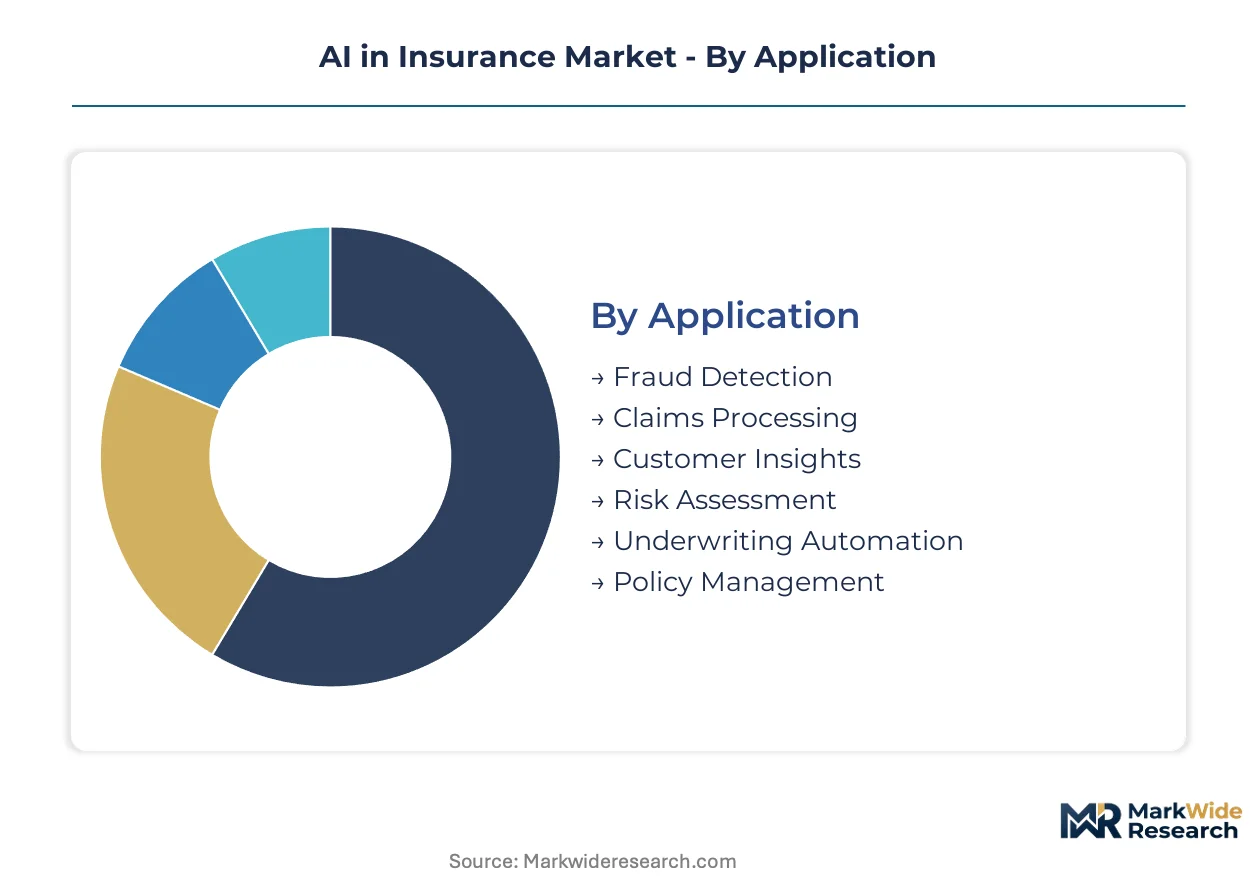
The AI in Insurance market segments reflect the diverse applications and technological underpinnings transforming the industry. Understanding these distinctions helps insurers tailor their AI investments to specific operational needs and regulatory compliance requirements. This segmentation also highlights areas of concentrated demand and emerging innovation across the value chain.
Application:
Regulatory frameworks, such as the EU AI Act, differentiate how AI applications are governed, particularly for high-risk systems in insurance.
- Claims Processing:This application automates the intake, analysis, and settlement of insurance claims, leveraging AI to verify information and calculate payouts. It significantly reduces manual effort and accelerates payout times for policyholders, driving operational efficiency for insurers.
- Underwriting Automation:AI models analyze extensive datasets to assess risk profiles and determine policy terms and premiums with greater precision. This application is crucial for personalizing insurance products and improving the accuracy of risk evaluation, especially in the United States and Germany.
- Fraud Detection:AI algorithms identify suspicious patterns and anomalies in claims data, flagging potential fraudulent activities for human review. This helps insurers minimize financial losses and maintain policy integrity across all lines of business.
- Customer Insights:AI analyzes customer data to understand behaviors, preferences, and needs, enabling insurers to offer personalized products and services. This enhances customer engagement and supports targeted marketing efforts.
- Risk Assessment:Beyond underwriting, AI continuously monitors and assesses various risks, including catastrophic events and market fluctuations, providing proactive insights. This supports strategic decision-making and portfolio management for carriers.
- Policy Management:AI streamlines the entire policy lifecycle from issuance to renewals and amendments, automating routine administrative tasks. This improves efficiency and reduces errors in policy administration.
Claims Processing handles the majority of AI application throughput; Underwriting Automation is the fastest mover on share.
Technology:
The maturity of AI technologies influences their integration costs and speed of deployment within insurance operations.
- Machine Learning:This foundational technology involves algorithms that learn from data to identify patterns and make predictions or decisions without explicit programming. Machine Learning models are widely applied for risk modeling, fraud detection, and predictive analytics in insurance.
- Predictive Analytics:Utilizing statistical algorithms and machine learning techniques, predictive analytics forecasts future outcomes and behaviors based on historical data. Insurers use this technology for actuarial modeling, customer churn prediction, and identifying potential claim events, thereby enabling proactive strategies.
- Natural Language Processing:NLP enables AI systems to understand, interpret, and generate human language, facilitating the analysis of unstructured text data from claims documents and customer interactions. This automates tasks like document summarization and sentiment analysis.
- Computer Vision:This technology allows AI to interpret and understand visual information from images and videos, used for assessing property damage or verifying identity. It enhances efficiency in claims inspection processes.
- Robotic Process Automation:RPA automates repetitive, rule-based tasks within insurance workflows, such as data entry and processing, by mimicking human interactions with digital systems. This frees up human staff for more complex analysis.
- Speech Recognition:AI systems convert spoken language into text, enabling automated processing of customer service calls and voice commands. This improves efficiency in call centers and enhances customer interaction analysis.
Machine Learning models drive the largest volume of AI-powered analytics; Computer Vision exhibits the steepest expansion trajectory.
Deployment:
Deployment models reflect varying infrastructure preferences and data sovereignty requirements across different insurer sizes.
- Cloud-Based:AI solutions hosted on remote servers and accessed via the internet offer scalability, flexibility, and reduced upfront infrastructure costs. This model is gaining rapid adoption due to its accessibility and ability to handle large datasets for complex AI models.
- On-Premises:AI systems are installed and run on an insurer's local servers and infrastructure, providing greater control over data security and compliance. This deployment is favored by organizations with stringent data privacy rules or existing legacy IT systems.
- Hybrid:This model combines elements of both cloud-based and on-premises deployments, allowing insurers to leverage the scalability of the cloud for some AI tasks while keeping sensitive data on local servers. It offers a balanced approach to flexibility and control.
- Edge Computing:AI processing occurs closer to the data source, such as on IoT devices or local servers, reducing latency and bandwidth usage. This is critical for real-time risk mitigation and telematics applications.
Cloud-Based solutions are increasingly preferred for scalability; Edge Computing is gaining traction for real-time processing.
End User:
Each end-user group leverages AI to address distinct functional requirements and improve specific operational efficiencies.
- Insurers:Primary users of AI, directly implementing solutions for underwriting, claims, fraud detection, and customer service to enhance their core operations. Insurers leverage AI to gain a competitive edge and improve profitability.
- Actuaries:Professionals who assess and manage financial risks use AI for more accurate and dynamic risk modeling, pricing, and reserving. AI tools augment their analytical capabilities, allowing for deeper insights into complex data.
- Brokers:Intermediaries who sell insurance products utilize AI for personalized customer recommendations, lead generation, and efficient policy comparisons. This helps them better serve clients and streamline their sales processes.
- Reinsurers:Companies that provide insurance to other insurers use AI for advanced risk aggregation, portfolio optimization, and catastrophe modeling. AI enhances their ability to manage large-scale and complex risks.
- Third-Party Administrators:Organizations that handle claims processing and other administrative functions for insurers deploy AI to automate routine tasks and improve service delivery efficiency. This reduces operational costs for their clients.
Insurers remain the primary beneficiaries of AI in insurance; Third-Party Administrators demonstrate expanding engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US HIPAA for health data and state-level mandates establish stringent requirements for AI model deployment in insurance. These regulations influence how insurers across major global markets approach AI adoption. Regional disparities in regulatory maturity and technological infrastructure shape localized investment patterns.
United States
Demand for advanced underwriting automation and sophisticated fraud detection drives AI adoption across US insurers. State-level mandates in Colorado and New York enforce stringent algorithmic fairness and anti-discrimination standards. Major tech hubs like Silicon Valley foster significant AI innovation for insurtech startups and established carriers.
Germany
Germany's insurance sector demands advanced underwriting automation and improved operational efficiency from AI solutions. The EU AI Act significantly influences the compliance landscape for high-risk AI systems deployed by German insurers. Munich's prominent insurance cluster actively integrates AI for complex risk assessment and claims processing.
China
Chinese consumers increasingly expect personalized insurance products and seamless digital distribution channels. National data privacy regulations govern how insurers collect and process vast customer information for AI models. Major tech centers in Shanghai and Beijing host insurtech companies leveraging AI for enhanced customer engagement.
India
India's rapidly expanding insurance market seeks AI for efficient claims processing automation and robust fraud detection. The IRDAI provides regulatory guidance for technology adoption, influencing AI deployment strategies across carriers. Bengaluru's vibrant tech ecosystem supports AI development, particularly for insurance back-office functions and analytics.
United Kingdom
UK insurers prioritize AI for proactive risk mitigation services and highly personalized customer interactions. GDPR and Financial Conduct Authority guidelines significantly shape AI governance and data privacy practices. London's financial district serves as a prominent hub for AI-driven insurtech innovation and strategic partnerships.
AI in Insurance Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the AI in insurance market. This market features distinct archetypes, including large technology providers, established insurance carriers, and specialized core system platforms. Dominant competitive moves center on strategic partnerships between tech firms and insurers, along with technology licensing agreements. Many players are also pursuing portfolio diversification to offer comprehensive AI solutions across the insurance value chain.
Technology providers like Microsoft Corporation exemplify the scalable cloud infrastructure offerings and pre-built machine learning tools available to insurers seeking rapid AI deployment and integration. Guidewire Software, Inc. occupies a significant position among core system platform specialists, embedding sophisticated AI capabilities directly into claims processing and underwriting solutions for enhanced efficiency. Established insurers such as Allstate anchor the market for proprietary data-driven AI, leveraging extensive internal datasets to train highly effective custom fraud detection algorithms and personalize customer interactions. This blend of infrastructure, platform, and application-specific expertise defines the current competitive dynamics, driving both technological advancement and operational transformation across the industry.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Guidewire Software, Inc. |
| SAS Institute Inc. |
| Allstate |
| Nationwide |
| Travelers |
| USAA |
Cost & Logistics Intelligence
The substitution of human analytical effort with advanced AI models simultaneously reshapes the supply geography of technology providers and alters the pricing economics for insurance carriers. This fundamental shift drives both efficiency gains and new cost structures within the industry.
Pricing Analysis
Project-based and subscription-tiered models dominate AI solution pricing within the insurance sector. Price differentiation stems from the level of customization required for specific insurance products and the complexity of data integration with legacy systems. Pricing softness stems from the increasing availability of off-the-shelf AI tools and competitive pressure from numerous insurtech providers. Smaller insurers and new market entrants demonstrate the highest price sensitivity for AI solutions, prioritizing cost-effective, scalable options.
Supply Chain Analysis
The scarcity of specialized AI talent, particularly data scientists with deep insurance domain knowledge, represents a critical chokepoint in the AI insurance supply chain. Key technology and talent hubs in the United States, Germany, and India are central to AI model development and deployment. Data, both proprietary and publicly available, forms a core raw material for training effective AI algorithms. Vendor lock-in with major cloud infrastructure providers represents a structural supply chain risk for many insurers. Distribution for these solutions largely occurs through direct sales from technology providers or via specialized consulting firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI in Insurance market is experiencing a buyer-power shift as insurers consolidate their technology stacks, demanding more integrated and compliant solutions from fewer vendors.
For Market Incumbents:
Compound existing proprietary data assets by investing in advanced data governance frameworks and secure cloud infrastructure. This defends against new entrants leveraging open-source models and mitigates regulatory compliance costs associated with data privacy. Strategic partnerships with specialized AI firms can accelerate capabilities without massive in-house development. Incumbents should prioritize investment in explainable AI tools to address the "black box" problem and meet evolving transparency rules.
For New Entrants and Emerging Players:
Anchor in niche application segments, such as embedded insurance or specialized risk assessment for emerging perils. These areas represent underpenetrated white spaces where legacy systems offer less competitive advantage. Targeting small to mid-sized insurers with a SaaS-based, rapid deployment model can provide a viable go-to-market angle. Focus on delivering solutions that demonstrably reduce operational costs or improve specific regulatory compliance metrics.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with PE-backed insurtechs that have proven solutions but require broader market access or deeper capital. The long-term viability of AI in insurance is strong, driven by persistent demand for efficiency and personalized services. Acquisition targets should include specialized AI platform providers with robust data integration capabilities and strong regulatory compliance features. A signal to watch is the successful, large-scale deployment of generative AI solutions by established carriers, indicating broader market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Explainable AI (XAI) Tools | Enhances compliance with EU AI Act and US state mandates, building trust and transparency in algorithmic decisions. |
| Form Strategic Partnerships with Hyperscalers | Secures scalable cloud infrastructure and access to advanced machine learning tools for complex model training. |
| Focus on Embedded Insurance AI Solutions | Captures new distribution channels and reaches mobile-first populations, particularly in emerging Asian markets. |
| Develop Proprietary Data Governance Frameworks | Leverages unique internal datasets for custom fraud detection algorithms while adhering to GDPR and HIPAA regulations. |
| Acquire Niche Insurtechs with Proven Solutions | Expands AI capabilities quickly into specialized risk assessment or customer personalization segments, bypassing lengthy R&D. |
Research Approach
A spread of perspectives from insurance executives, chief data officers, AI solution architects, and regulatory compliance officers converged on the working assumptions for this analysis. This involved combining extensive primary interviews with industry stakeholders with rigorous secondary validation from company annual reports, government regulatory publications, and industry association reports. Bottom-up and top-down triangulation ensured comprehensive data coverage.
The market was segmented by application, technology, deployment model, end user, and regional adoption patterns across the analysis window. Compound Annual Growth Rate calculations integrated historical data with projected trends, factoring in insurance premium growth, regulatory compliance costs, and AI talent availability. This framework provides a robust foundation for understanding market dynamics and future trajectories.
Decision-makers should treat outputs as directional under current base assumptions; material deviation in regulatory frameworks, such as the EU AI Act or US state mandates, would warrant a model refresh. Practitioners should keep alternative scenarios live as technological breakthroughs, like generative AI, and macroeconomic shifts impacting insurance spending evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Endowment Insurances Market
Insurance
Business Travel Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Business Income Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Small Business Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Marine Crew Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Insurance Aggregators Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market