
 Commercial Insurance Market | 2026-2036
Commercial Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Insurance Market Intelligence
Healthcare sector exposure growth is recalibrating how carriers allocate capital across commercial lines. Chubb leverages its international infrastructure to dominate high-severity professional indemnity placements for hospital networks. AIG sustains leadership in cyber liability through proprietary risk-engineering protocols tailored to electronic health record vulnerabilities.
Commercial insurance encompasses risk-transfer instruments underwritten for business entities, with policies typically specifying per-occurrence limits, aggregate caps, and deductible structures calibrated to loss severity distributions. The primary industrial purpose is indemnification against operational, financial, and third-party liabilities that would otherwise impair capital reserves or solvency. Liability coverage leads premium generation among coverage types due to litigation frequency in employment and professional service contexts. Small businesses represent the fastest-expanding client type segment as embedded insurance APIs lower distribution friction for micro-enterprises.
FDA oversight of clinical trial liability shapes healthcare professional indemnity pricing in the United States, while EU AI Act transparency mandates compel European carriers to validate algorithmic underwriting fairness. The National Association of Insurance Commissioners coordinates state-level reserve requirements that constrain capacity deployment timing across US jurisdictions. Stakeholders must monitor how emerging algorithmic accountability regimes redefine actuarial data permissibility and exclusion language.
Market Dynamics
Algorithmic underwriting is forcing carriers to rebuild actuarial infrastructure as the EU AI Act and similar frameworks mandate explainability in risk-scoring models. This regulatory pressure is compressing legacy pricing cycles and redistributing competitive advantage toward data-science capabilities.
Growth Catalysts
- EU AI Act transparency mandates:European carriers must document algorithmic decision logic, creating demand for audit-ready underwriting platforms and specialized compliance technology vendors.
- Healthcare cyber liability multiplication:Electronic health record breaches and ransomware attacks on hospital networks are expanding per-policy limits and accelerating coverage adoption across provider systems.
- Embedded insurance APIs:Micro-enterprises now access commercial coverage through accounting software and payment platforms, collapsing traditional broker distribution friction for small business segments.
Market Restraints
- Catastrophe model opacity:Proprietary climate risk engines from dominant vendors concentrate pricing power and limit carrier ability to validate loss projections independently.
- Reinsurance capacity cyclicality:Florida and California property markets face periodic treaty renewal disruptions as global retrocession markets retrench following major loss events.
- Long-tail liability reserve volatility:Asbestos and environmental claims continue generating adverse development, constraining statutory capital deployment into emerging lines.
Strategic Opportunities
- Parametric structures for supply chain disruption:Index-triggered policies bypass claims adjustment friction, appealing to manufacturing buyers seeking immediate liquidity post-event.
- India's PLI scheme expansion:Production-linked incentives for electronics and pharmaceutical manufacturing are creating captive insurance demand for new industrial capacity.
- Telematics-usage-based convergence:Fleet operators now accept real-time driver monitoring in exchange for dynamic premium adjustments, opening data-monetization pathways.
Industry Challenges
- Actuarial data science talent scarcity:Traditional underwriters lack Python and machine-learning fluency required to validate algorithmic model outputs.
- Legacy policy administration integration:Core systems from the 1990s resist API connectivity, forcing expensive middleware layers for digital distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Insurance Market |
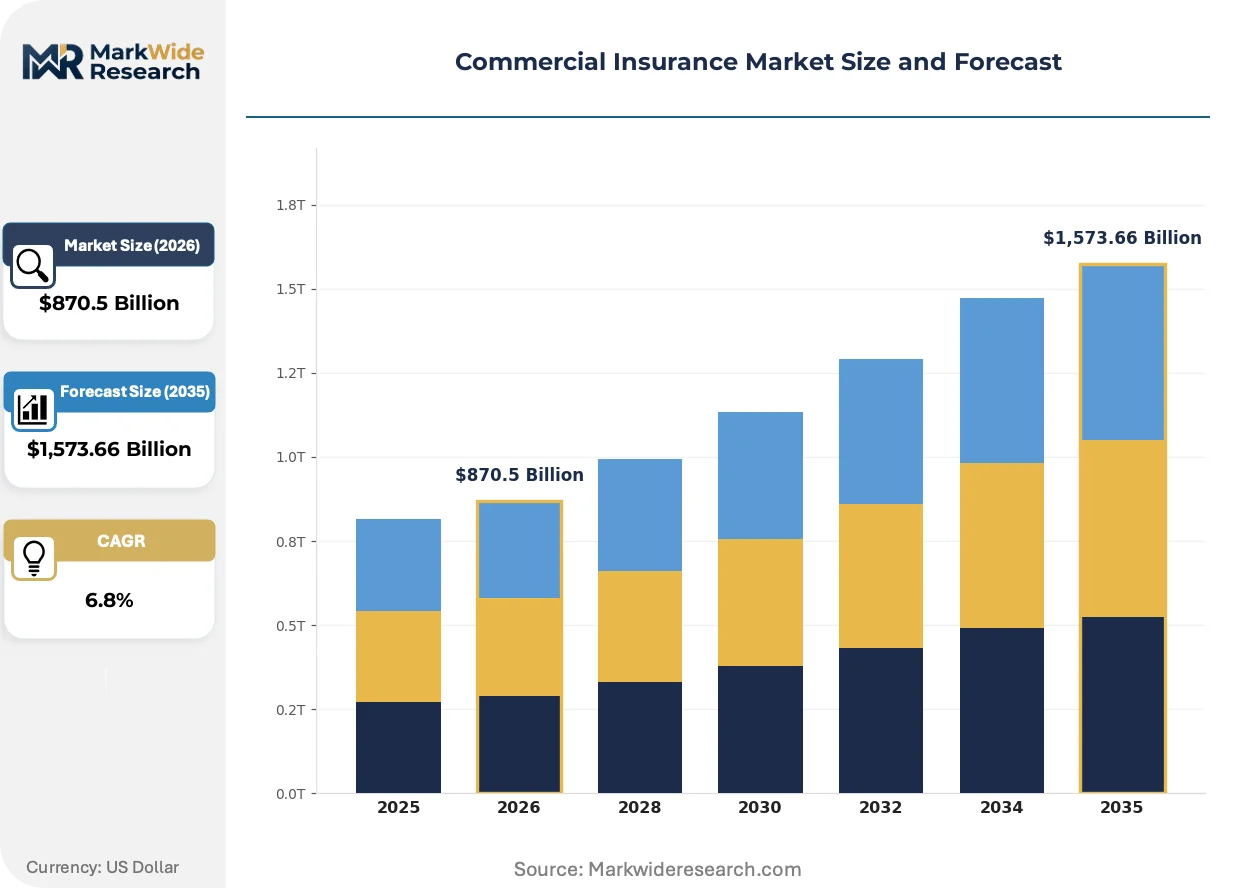
| Market Size in 2026 | $870.5 Billion |
| Market Size in 2035 | $1,573.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability, Property, Workers' Compensation, Professional Indemnity Client Type: Small Businesses, Corporations, Non-Profits, Government Entities Industry Vertical: Construction, Healthcare, Retail, Technology Policy Duration: Annual, Multi-Year, Short-Term, Long-Term |
| Companies Covered | Chubb, Travelers, Liberty Mutual, The Hartford, AIG, CNA Financial, Allianz, AXA, Zurich Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Insurance Market Strategic Shifts & Innovations
Carriers are rearchitecting around real-time data ingestion as static annual renewal cycles give way to continuous risk monitoring. This shift is compressing product development timelines and elevating technology vendors to strategic partnership status.
Blockchain-enabled smart contracts are decentralizing claims settlement authority by encoding payout triggers into immutable distributed ledgers. Marine cargo and trade credit underwriters at Lloyd's and Singapore hubs are piloting these instruments for documentary verification. The technology is decentralizing the traditional adjuster role and compressing indemnification timelines from weeks to hours.
The EU AI Act's risk-tiering framework is compelling carriers to segregate algorithmic models by automation depth and decision consequence. High-risk underwriting applications now require human-in-the-loop documentation and bias auditing. European professional indemnity carriers are responding by embedding fairness validation into product development workflows before regulatory deadlines.
Hospital networks and pharmaceutical manufacturers are consolidating procurement authority into centralized risk management functions, displacing decentralized broker relationships. This buyer concentration is compressing commission structures and favoring carriers with dedicated healthcare vertical teams. The pattern is most visible in the United States, where FDA clinical trial liability requirements add specialized coverage complexity that generalist distributors cannot address.
Commercial Insurance Market Segmentation
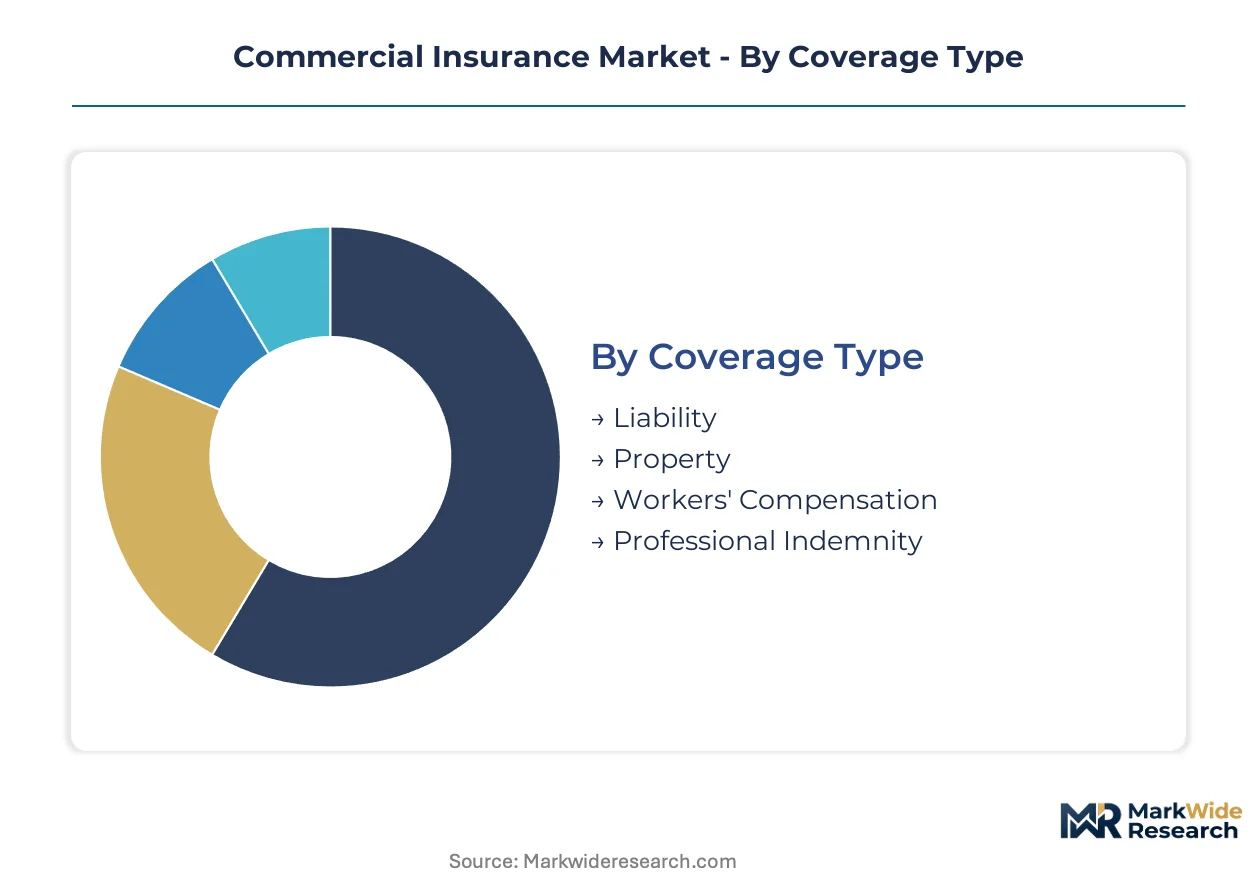
Commercial insurance segmentation reveals how carriers deploy capital against heterogeneous risk profiles. Coverage type and client scale determine pricing sophistication, while industry verticals dictate regulatory exposure and loss severity distributions.
Coverage Type:
Liability coverage operates as standalone placement for litigation-exposed enterprises, whereas property and workers' compensation typically embed within packaged programs for mid-market buyers.
- Liability:Indemnifies third-party bodily injury, property damage, and advertising injury claims. Employment practices liability dominates premium flow in the United States as state-level litigation frequency accelerates; EPLI now commands dedicated underwriting teams at major carriers.
- Property:Protects physical assets against named perils including fire, windstorm, and theft. Florida and California commercial property markets face capacity constraints as catastrophe model opacity limits reinsurance treaty renewal; carriers are tightening deductibles and sublimits in response.
- Workers' Compensation:Statutory coverage for occupational injury and illness. State funds in Ohio and Washington compete with private carriers, compressing margins in monopolistic jurisdictions.
- Professional Indemnity:Shields service providers against negligence claims. Hospital networks in the United States consolidate procurement authority here as FDA clinical trial liability requirements add coverage complexity.
Liability leads volumes today; professional indemnity is gaining share fastest as healthcare cyber exposures multiply.
Client Type:
Cost tier stratification separates micro-enterprises accessing coverage through embedded APIs from corporations demanding bespoke manuscript policies with dedicated claims handlers.
- Small Businesses:Firms with fewer than 100 employees. Embedded insurance APIs through accounting software and payment platforms are collapsing traditional broker distribution friction; this segment expands most quickly as digital onboarding reduces acquisition costs.
- Corporations:Large enterprises with complex risk profiles. Risk managers at Fortune 500 manufacturers negotiate manuscript policies with per-occurrence limits exceeding $100 million; captive insurance subsidiaries in Vermont and Bermuda provide alternative risk transfer.
- Non-Profits:Charitable and educational organizations. Directors and officers coverage dominates placements as fiduciary duty litigation targets volunteer boards.
- Government Entities:Municipalities and state agencies. Risk pools in Texas and California aggregate coverage for public infrastructure against tort claims.
Corporations dominate premium dollars today; small businesses show the steepest expansion trajectory as embedded distribution scales.
Industry Vertical:
Application-specific exposure patterns force carriers to build vertical expertise—healthcare demands FDA regulatory fluency while construction requires surety bonding integration.
- Construction:Contractors and developers. Surety bonds accompany general liability as project owners mandate completion guarantees; OSHA enforcement severity shapes workers' compensation pricing.
- Healthcare:Hospitals, physicians, and pharmaceutical manufacturers. Cyber liability exposures from electronic health record breaches are expanding per-policy limits; EU AI Act transparency mandates now compel European carriers to validate algorithmic underwriting fairness for this vertical.
- Retail:Brick-and-mortar and e-commerce operators. General liability concentrates on slip-and-fall premises exposure while product liability attaches to private-label goods.
- Technology:Software vendors and data processors. Errors and omissions coverage blends with cyber liability as cloud service agreements impose contractual indemnification obligations.
Healthcare commands the highest loss severity today; technology is climbing the fastest as ransomware attacks proliferate.
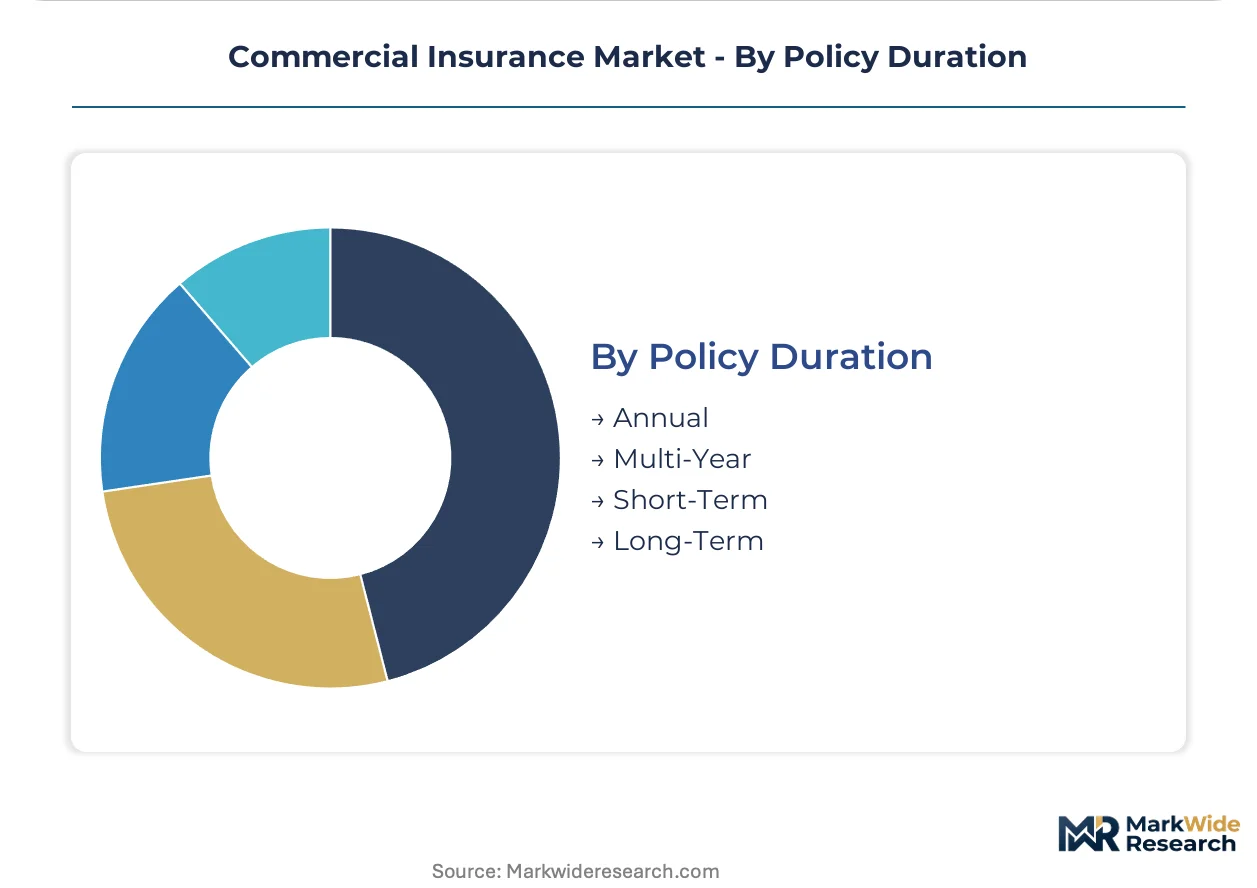
Policy Duration:
Maturity gradients separate annual renewals with rate fluctuation exposure from multi-year structures that lock pricing but constrain carrier flexibility.
- Annual:One-year terms with guaranteed renewal options. Rate adequacy cycles in Florida property markets create volatility for commercial real estate owners.
- Multi-Year:Two-to-five year terms with fixed premiums. Manufacturing buyers with stable operations prefer this structure to hedge against hard market pricing.
- Short-Term:Coverage periods under twelve months. Event cancellation and construction project-specific policies dominate this niche.
- Long-Term:Terms exceeding five years. Captive fronting arrangements and risk retention groups utilize this structure for asbestos and environmental liabilities with extended tail exposure.
Annual policies anchor volume today; multi-year structures are gaining share fastest as buyers seek rate stability through hard market cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States commercial lines density exceeds all developed economies, with hospital networks and pharmaceutical manufacturers driving professional indemnity demand. Regulatory fragmentation across state insurance commissioners shapes carrier capital deployment timing. Carrier concentration clusters in New York, Hartford, and Bermuda.
United States
Hospital network consolidation and FDA clinical trial liability requirements expand professional indemnity placements. The National Association of Insurance Commissioners coordinates state-level reserve requirements that constrain capacity timing. Hartford, Connecticut anchors domestic carrier headquarters density while Bermuda captive formations accelerate alternative risk transfer.
Germany
Industrial manufacturing and automotive supply chains sustain property and casualty premium flow. The EU AI Act transparency mandates compel carriers to document algorithmic underwriting logic. Munich and Frankfurt concentrate reinsurance treaty negotiation activity as carriers retool actuarial infrastructure.
United Kingdom
Lloyd's syndicates and London market brokers dominate specialty lines including marine cargo and cyber liability. The Prudential Regulation Authority supervises Solvency II compliance for carrier balance sheets. The City of London remains the global hub for complex commercial risk placement and alternative capital structuring.
India
Production-linked incentive schemes for electronics and pharmaceutical manufacturing create captive insurance demand for new industrial capacity. The Insurance Regulatory and Development Authority of India governs foreign ownership limits and product approval timelines. Gujarat and Maharashtra industrial corridors attract manufacturing-linked commercial coverage expansion.
Japan
Aging infrastructure and natural catastrophe exposure sustain property reinsurance demand from domestic carriers. The Financial Services Agency oversees solvency margin requirements and rate filing procedures. Tokyo concentrates head offices of non-life insurers while Osaka anchors western Japan commercial placement activity.
Commercial Insurance Market Key Industry Players
Strategic partnerships dominate the current landscape as carriers seek external data-science capabilities to meet algorithmic transparency mandates. The market structure concentrates around multinational incumbents with dedicated healthcare vertical teams and established reinsurance relationships. Three archetypes prevail: global diversified carriers with Lloyd's market access, domestic specialists with state-level regulatory fluency, and technology-forward insurers with proprietary risk-engineering protocols. Competitive intensity centers on M&A targeting niche cyber liability expertise and geographic expansion into India's manufacturing corridors.
Among US-based diversified carriers, Chubb and Travelers exemplify contrasting strategic positions. Chubb occupies the international infrastructure archetype with demonstrated strength in high-severity professional indemnity placements. Travelers represents the mid-market commercial specialization model with embedded distribution through independent agency networks. AIG anchors the technology-intensive tier, with risk-engineering protocols tailored to electronic health record vulnerabilities distinguishing its cyber liability positioning.
| Leading Market Players |
|---|
| Chubb |
| Travelers |
| Liberty Mutual |
| The Hartford |
| AIG |
| CNA Financial |
| Allianz |
| AXA |
| Zurich Insurance Group |
| Others |
Cost & Logistics Intelligence
Manuscript-to-program bifurcation separates Fortune 500 buyers negotiating bespoke policies with per-occurrence limits exceeding $100 million from micro-enterprises accessing embedded coverage through accounting software APIs. This tier divergence manifests in carrier capital allocation: high-touch underwriting teams concentrate on complex healthcare and cyber liability placements while automated platforms absorb small business volume at compressed acquisition costs.
Pricing Analysis
Reinsurance treaty costs pass through to primary policy rates, with Florida and California property markets experiencing the steepest adjustments as catastrophe model opacity limits retrocession capacity. Three-tier pricing structure across premium, standard, and economy levels reflects deductible gradients and claims handling sophistication. Pricing pressure stems from long-tail liability reserve volatility as asbestos and environmental claims generate adverse development. Small businesses exhibit highest price sensitivity, while hospital networks prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Reverse-logistics flows for policy endorsements and mid-term adjustments cycle through Bermuda captive formations and Vermont domiciled risk retention groups. Capital concentration centers on the United States, Bermuda, and London as primary underwriting hubs. Carrier capacity draws from reinsurance treaties, alternative capital through catastrophe bonds, and retrocession markets. Single-source vulnerability concentrates in proprietary climate risk engines from dominant vendors. Distribution runs through independent agency networks, wholesale brokers, and direct API-enabled platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
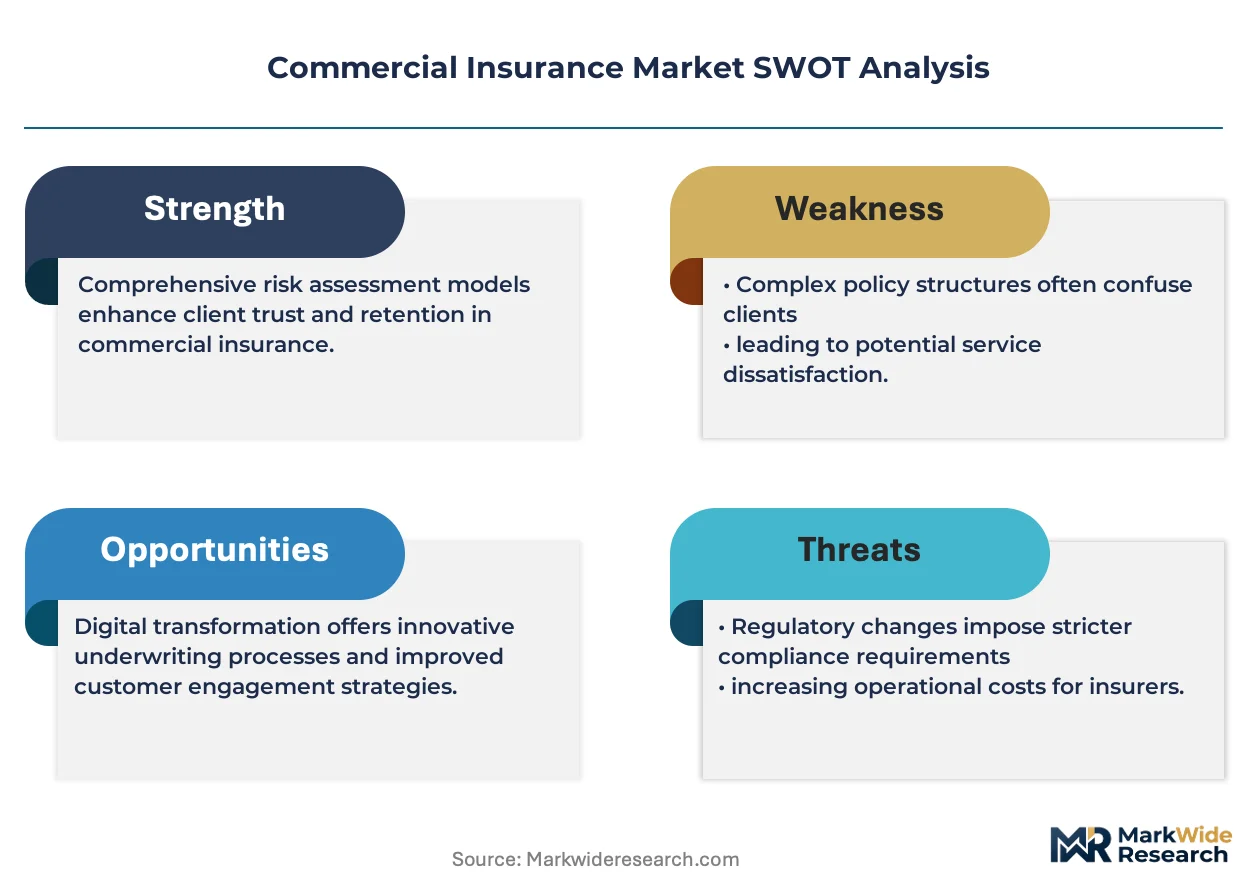
The commercial insurance market functions as a regulatory compounder, with the EU AI Act transparency mandates forcing carriers to rebuild actuarial infrastructure and creating sustained demand for audit-ready underwriting platforms.
For Market Incumbents: Hedge against algorithmic underwriting disruption by acquiring specialized data-science capabilities and embedding fairness validation into product development workflows before regulatory deadlines tighten. Chubb's international infrastructure model offers a template for defending high-severity professional indemnity positions against technology-forward entrants. Capacity addition in India's manufacturing corridors provides geographic diversification as US property markets face cyclical pressure. For New Entrants and Emerging Players: Enter via embedded insurance APIs targeting micro-enterprises in underserved verticals where traditional broker distribution remains entrenched. India's production-linked incentive schemes for electronics and pharmaceutical manufacturing create captive insurance demand with limited incumbent presence. Parametric structures for supply chain disruption offer a differentiated go-to-market angle bypassing legacy claims adjustment infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-forward insurers possessing proprietary risk-engineering protocols and demonstrated healthcare cyber liability expertise. Long-term viability favors carriers with Lloyd's market access and established reinsurance relationships that endure through hard market cycles. Monitor EU AI Act enforcement patterns and FDA clinical trial liability rulemaking as inflection indicators for regulatory-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Infrastructure Investment | EU AI Act compliance requirements compel carriers to document decision logic in underwriting models. |
| Healthcare Vertical Specialization | FDA clinical trial liability complexity favors dedicated teams over generalist distributors. |
| Embedded Distribution Partnership | API integrations with accounting software collapse acquisition friction for micro-enterprises. |
| Parametric Product Development | Index-triggered policies bypass claims adjustment for manufacturing buyers seeking immediate liquidity. |
| Geographic Expansion into India | PLI scheme manufacturing growth creates captive insurance demand in Gujarat and Maharashtra corridors. |
Research Approach
Multiple input streams — carrier underwriting executives, reinsurance treaty negotiators, healthcare risk managers, regulatory affairs specialists — were reconciled against secondary validation from NAIC reserve requirement filings, Lloyd's market data, EU AI Act implementation guidance, and SEC carrier financial disclosures. Primary interviews with hospital network procurement directors and commercial insurance brokers informed pricing dynamics and distribution friction points. Bottom-up policy volume estimates and top-down premium flow analysis were triangulated to anchor market sizing.
Data-stream reconciliation across coverage type, client scale, and industry vertical dimensions structured the analytical framework over the projection horizon. CAGRs were derived from loss severity trend analysis and regulatory-driven demand elasticity modeling. Segmentation modeling incorporated policy duration preferences, geographic regulatory clusters, and algorithmic underwriting adoption curves. Healthcare cyber liability exposure multiplication and embedded API distribution penetration served as key forecast inputs.
The model holds under stable reinsurance capacity conditions and gradual regulatory implementation; deviation in catastrophe loss frequency or accelerated EU AI Act enforcement timelines would shift carrier capital deployment patterns. Practitioners should monitor retrocession market pricing and FDA clinical trial liability rulemaking for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Small Business Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Peru Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Income Protection Insurance Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
Liability Insurance Market
Insurance
Reinsurance Market
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
Disability Insurance Market
Insurance
Financial Guarantee Market
Insurance
Self Funded Insurance Market
Insurance
Agriculture Insurance Market