
 Asia-Pacific Forage Seed Market | 2026-2036
Asia-Pacific Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Forage Seed Market Outlook
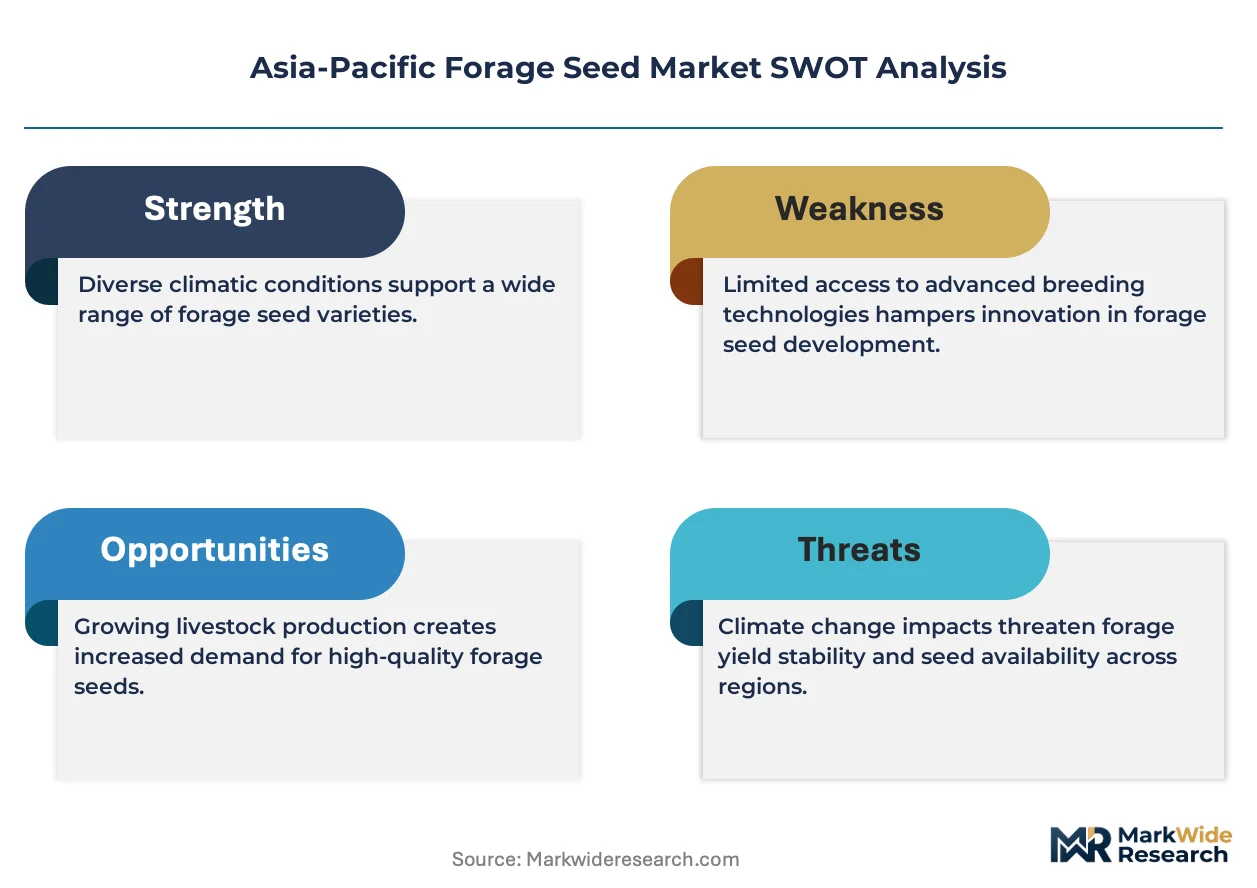
Precision breeding and genomic selection is tilting cultivar development toward drought-tolerant and high-metabolizable-energy varieties across the Asia-Pacific forage seed sector. Corteva Agriscience leverages its CRISPR-enabled trait pipelines to accelerate perennial ryegrass improvements for Australian dairy systems. Bayer AG anchors its regional position through proprietary alfalfa seed treatments that reduce soil-borne pathogen pressure in China's Loess Plateau. Royal Barenbrug Group dominates temperate grass breeding for New Zealand's intensive pastoral platforms, exporting certified cultivars throughout Southeast Asian highland zones.
Forage seed comprises botanically verified propagules of grasses, legumes, and herbaceous broadleaf species cultivated specifically for animal consumption, with certified germination rates typically exceeding 85% and varietal purity standards enforced through field inspection protocols. These seeds function as the biological foundation of managed pasture systems, converting solar energy into digestible protein and fiber for ruminant production. Grasses occupy the largest volume share across the Asia-Pacific landscape, driven by perennial ryegrass and tall fescue demand from New Zealand and Australian exporters, while legumes capture expanding acreage in India's cooperative dairy belts where crude protein fixation reduces imported soybean meal dependency. Retail and wholesale distribution channels still control last-mile seed delivery to smallholder livestock producers, though direct sales from breeder-multiplier networks are gaining traction among Australian station properties exceeding ten thousand hectares.
India's Seeds Act enforcement through the Central Seed Committee shapes cultivar release timelines and mandatory field certification standards for commercial forage varieties. Australia's Plant Breeder's Rights Office and New Zealand's Plant Variety Rights regime collectively govern royalty collection and genetic ownership across trans-Tasman seed trade corridors. China's Ministry of Agriculture and Rural Affairs implements national forage seed reserve policies that buffer livestock producers against supply interruptions during climatic stress events. Stakeholders must monitor how evolving carbon accounting methodologies for perennial pastures reshape seed procurement criteria and premium pricing structures.
Market Dynamics
Water stress across eastern Australia and northern India is forcing rapid cultivar turnover toward deep-rooted perennials, compressing traditional breeding cycles and reshaping seed multiplication networks across the Asia-Pacific grazing belt.
Growth Catalysts
- India's PLI scheme for fodder crops:Production-linked incentives for certified seed multiplication are pulling private capital into berseem and oat seed chains across Haryana and Punjab.
- Pastoral automation:Precision sowing drones and variable-rate seeders are cutting establishment costs for large Australian station properties, accelerating certified ryegrass adoption.
- Crossbred cattle expansion:Dairy cooperatives in India's northern plains are locking in multi-year offtake contracts that guarantee seed procurement volumes for irrigated alfalfa systems.
Market Restraints
- Phosphorus input volatility:Fertilizer cost spikes in New Zealand are squeezing margins for pasture renovation programs, delaying perennial reseeding cycles.
- Genetic concentration risk:Australia's PGG Wrightson and New Zealand's Barenbrug control dominant temperate grass germplasm pools, creating royalty stacking for secondary breeders.
- Quarantine friction:Australia's biosecurity protocols block rapid import of novel drought-tolerant Mediterranean germplasm, extending cultivar release timelines.
Strategic Opportunities
- Myanmar highland penetration:Underserved upland livestock zones lack certified temperate grass access, creating first-mover openings for New Zealand-origin perennial ryegrass.
- Carbon credit integration:Australia's Clean Energy Regulator is piloting soil carbon methodologies that reward perennial pasture establishment with tradable offsets.
- Blockchain traceability:Immutable seed certification records are emerging as a procurement filter for export-oriented New Zealand dairy processors.
Industry Challenges
- Seed pathology diagnostics gap:Australia's regional laboratories lack capacity for rapid soil-borne pathogen screening, delaying treated seed release.
- Multiplication contract enforcement:India's informal seed grower networks default on certified isolation protocols, contaminating foundation stock purity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Forage Seed Market |
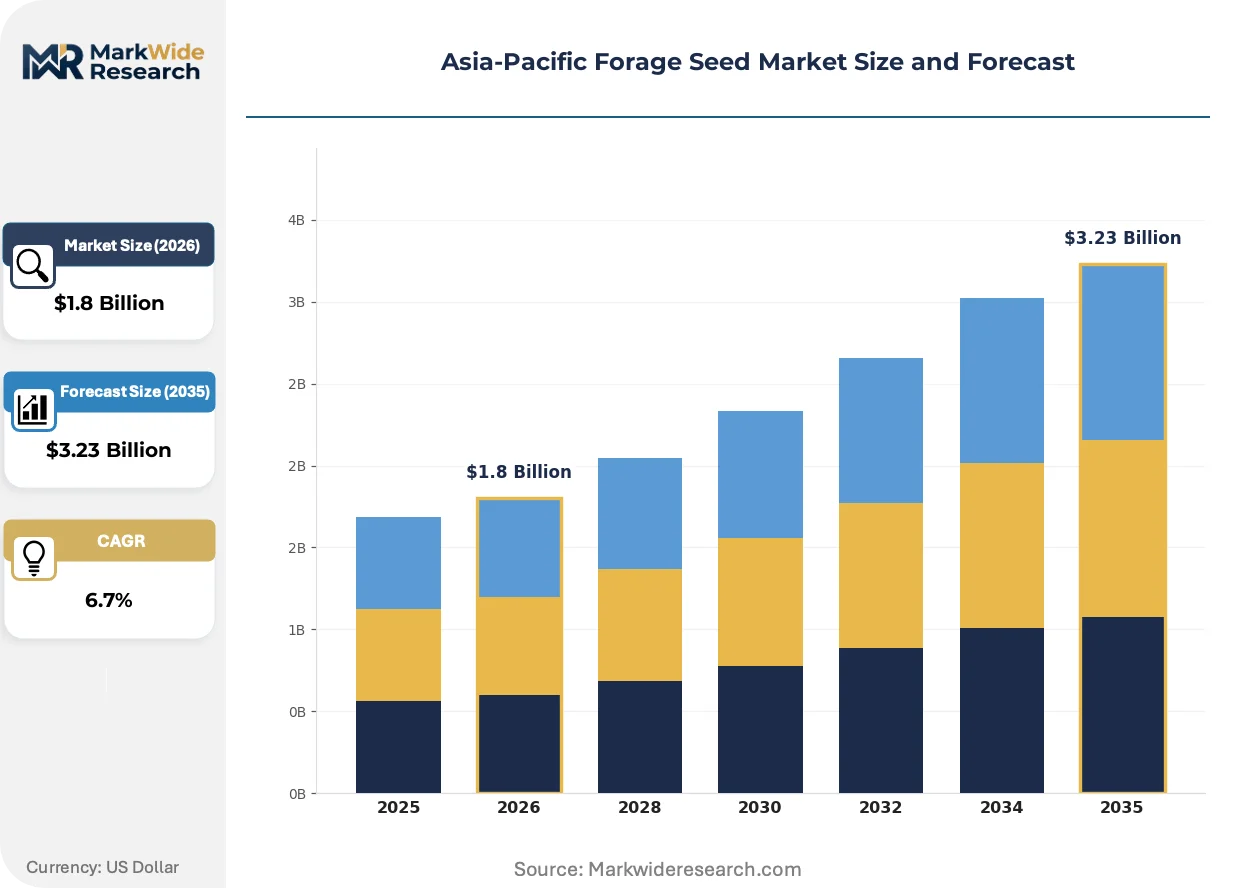
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Legumes, Grasses, Forbs, Mixtures Distribution Channel: Retail, Wholesale, Online, Direct Sales End User: Agriculture, Livestock, Government, Research Institutions Packaging Type: Bags, Bulk, Boxes, Containers |
| Companies Covered | Corteva Agriscience, Bayer AG, Royal Barenbrug Group, Advanta Seeds - UPL, Ampac Seed Company, Groupe Limagrain, Land O’Lakes Inc, PGG Wrightson Seeds, Kaveri Seeds, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Forage Seed Market Strategic Shifts
Biological nitrogen fixation and climate-adaptive phenotyping are converging to redefine cultivar selection criteria, shifting procurement priorities away from yield-maximizing genetics toward resilience-per-unit-water metrics.
CRISPR-enabled gene editing is hybridizing conventional backcrossing with accelerated trait stacking for drought escape mechanisms. Australian dairy cooperatives are piloting these cultivars across the Murray-Darling Basin, compressing variety turnover from eight-year cycles to four-year replacements. The technology is hybridizing seed company R&D portfolios, forcing mergers between genomics service providers and traditional breeding stations.
China's Ministry of Agriculture and Rural Affairs is tightening national forage seed reserve mandates, requiring provincial stockpiles covering two production seasons. This policy is fragmenting procurement into state-directed tenders rather than open-market spot purchases. Australia's export-oriented seed houses are responding by establishing licensed production partnerships within China's Gansu and Inner Mongolia seed multiplication zones.
Buyer consolidation among India's dairy cooperatives is compressing switching cycles for certified varieties. Multiplier networks that once served dispersed smallholders now face concentrated procurement committees demanding varietal performance guarantees and embedded technical advisory. This shift is most visible in Gujarat and Rajasthan, where Amul-linked federations are phasing out uncertified farmer-saved seed through bundled input-finance packages.
Asia-Pacific Forage Seed Market Segmentation
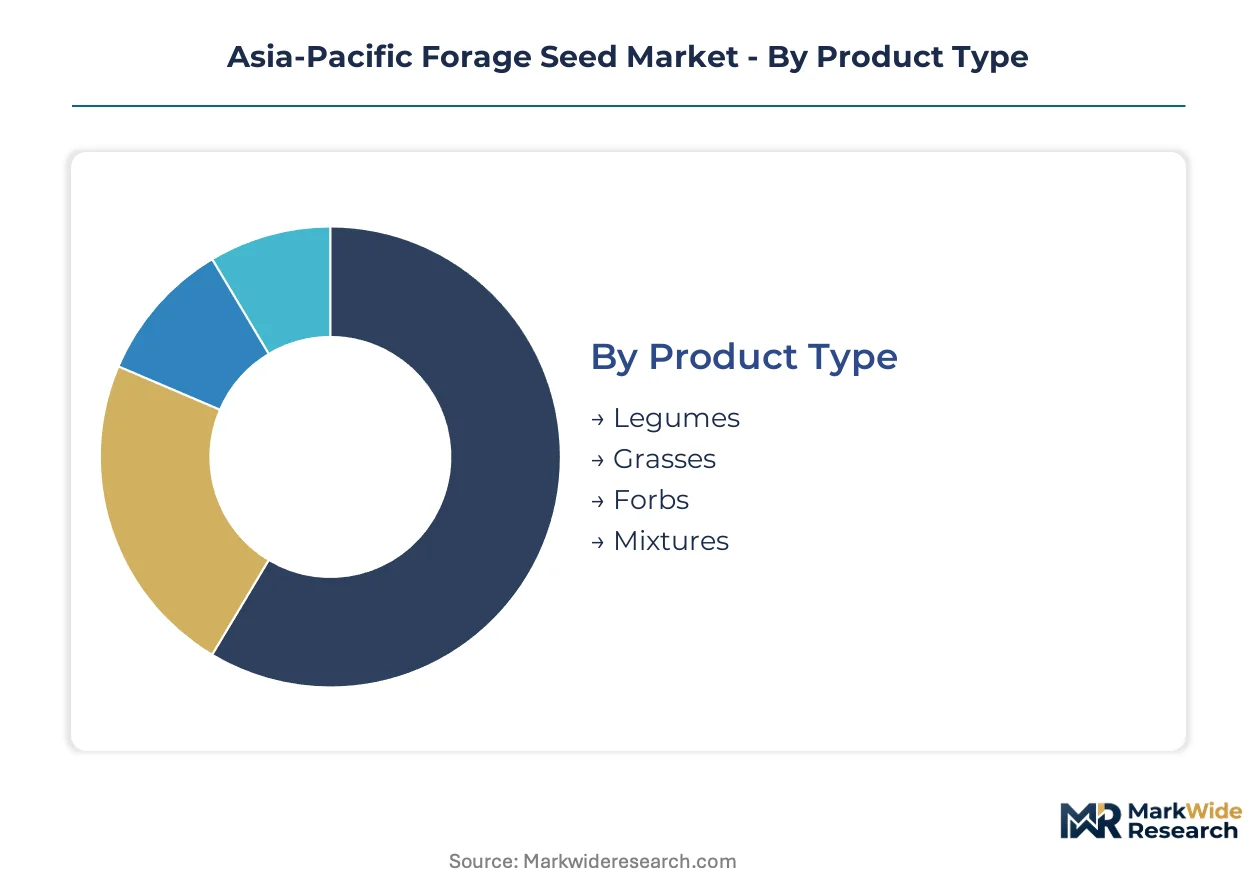
Forage seed procurement patterns across the Asia-Pacific region diverge sharply by product biology, channel access, and end-use intensity. Breeders and multipliers must align varietal portfolios with distinct agronomic requirements and purchasing behaviors that vary from India's cooperative dairy belts to Australia's station properties.
Product Type:
Mature temperate grasses dominate commercial volumes while emerging legume categories capture protein-focused renovation cycles.
- Legumes:Nitrogen-fixing species including alfalfa and berseem deliver crude protein concentrations exceeding 18 percent, reducing imported soybean meal dependency for India's crossbred cattle cooperatives in Haryana and Punjab. Irrigated acreage under certified legume seed is intensifying as dairy federations phase out farmer-saved alternatives through bundled input-finance structures.
- Grasses:Perennial ryegrass and tall fescue constitute the biological foundation of New Zealand's intensive pastoral platforms and Australia's export-oriented dairy systems. Deep-rooted cultivars with enhanced water-use efficiency are displacing shallow-rooted legacy varieties across the Murray-Darling Basin as irrigation allocations tighten.
- Forbs:Herbaceous broadleaf species such as chicory and plantain provide mineral-dense grazing components for high-performance livestock finishing systems.
- Mixtures:Pre-formulated multi-species blends target specific soil conditions and seasonal feed gaps, simplifying procurement for smallholder livestock producers.
Grasses retain volume leadership; legumes hold the steepest expansion curve.
Distribution Channel:
Channel selection reflects farm scale and technical advisory requirements across the region's fragmented livestock production base.
- Retail:Smallholder-focused agro-dealers in India's northern plains control last-mile delivery of certified berseem and oat seed, though varietal purity enforcement remains inconsistent across informal grower networks.
- Wholesale:Volume aggregators supply Australian station properties exceeding ten thousand hectares, leveraging established relationships with breeder-multiplier networks for perennial ryegrass multiplication contracts.
- Online:Digital procurement platforms are emerging for standardized varieties, constrained by germination testing verification and varietal certification traceability requirements.
- Direct Sales:Breeder-to-producer relationships dominate New Zealand's pastoral sector, embedding technical advisory and performance guarantees into seed procurement agreements.
Wholesale channels anchor volume throughput; direct sales are climbing the fastest as buyer consolidation concentrates procurement power.
End User:
End-use intensity determines seed specification tiers and certification stringency across public and private demand segments.
- Agriculture:Mixed farming operations integrate forage seed into crop rotation systems, particularly in China's Loess Plateau where national reserve policies buffer supply interruptions.
- Livestock:Dairy cooperatives and beef finishing operations drive demand for metabolizable-energy-optimized cultivars, with procurement committees now demanding multi-year performance guarantees.
- Government:Provincial stockpile mandates under China's Ministry of Agriculture and Rural Affairs fragment procurement into state-directed tenders covering two production seasons.
- Research Institutions:Pastoral research stations in New Zealand and Australia accelerate novel cultivar development for water-stressed environments, compressing traditional breeding cycles through genomic selection.
Livestock operations dominate value capture; government procurement represents the most volatile demand segment.
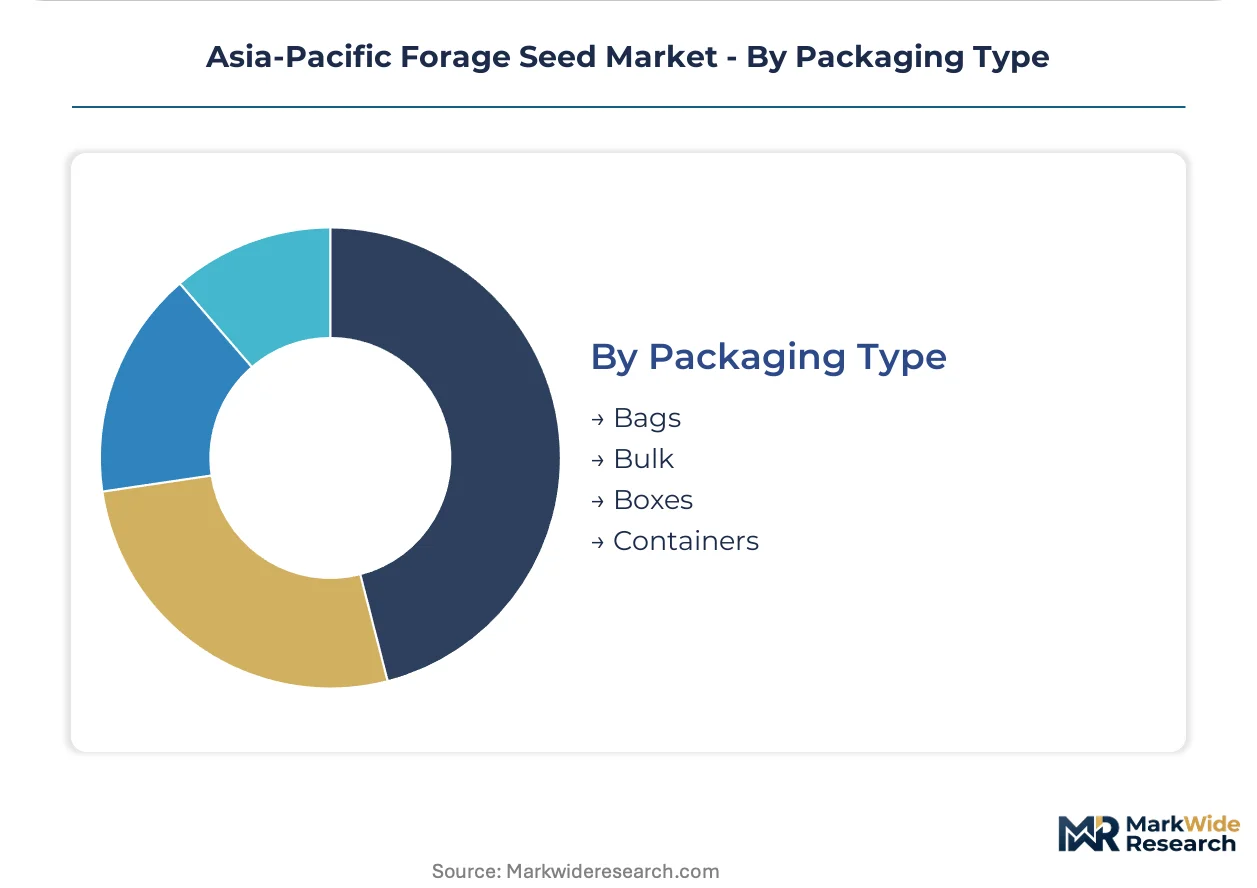
Packaging Type:
Packaging configuration aligns with seed lot sizes and handling infrastructure across diverse farm scales.
- Bags:Standard woven polypropylene units facilitate smallholder access and retail channel distribution throughout Southeast Asian highland zones.
- Bulk:Unpackaged seed delivery reduces per-unit handling costs for Australian station properties with on-farm treatment and storage infrastructure.
- Boxes:Rigid containers protect pelleted or coated seed during transport for precision sowing drone applications.
- Containers:International shipment units support New Zealand's export-oriented temperate grass trade corridors into Myanmar's underserved upland livestock zones.
Bulk packaging leads volume efficiency; containerized shipment enables the fastest geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's temperate grass seed exports flow through established trade corridors into Australia's dairy belt and Southeast Asian highland zones, while China's state reserve policies redirect procurement toward domestic multiplication partnerships.
Australia
Deep-rooted perennial cultivars displace shallow-rooted legacy varieties across the Murray-Darling Basin as irrigation allocations tighten. The country's Plant Breeder's Rights Office governs royalty collection across trans-Tasman seed trade. PGG Wrightson Seeds anchors commercial breeding activity, accelerating novel cultivar development for water-stressed environments.
China
Provincial stockpile mandates under the Ministry of Agriculture and Rural Affairs fragment procurement into state-directed tenders covering two production seasons. National forage seed reserve policies buffer livestock producers against supply interruptions during climatic stress events. Gansu and Inner Mongolia host licensed production partnerships for export-oriented seed houses.
India
Dairy cooperatives in Haryana and Punjab lock in multi-year offtake contracts for irrigated alfalfa and berseem seed systems. The Seeds Act enforcement through the Central Seed Committee shapes cultivar release timelines and mandatory field certification standards. Amul-linked federations in Gujarat and Rajasthan phase out uncertified farmer-saved seed through bundled input-finance packages.
New Zealand
Pastoral research stations compress traditional breeding cycles through genomic selection for drought-tolerant varieties. The Plant Variety Rights regime governs genetic ownership across trans-Tasman corridors. The country's intensive pastoral platforms anchor temperate grass breeding, with certified cultivars exporting throughout Southeast Asian highland zones.
Myanmar
Underserved upland livestock zones lack certified temperate grass access, creating first-mover openings for New Zealand-origin perennial ryegrass. Informal seed distribution networks dominate last-mile delivery to smallholder producers. Highland agricultural zones concentrate demand for multi-species blends targeting specific soil conditions and seasonal feed gaps.
Asia-Pacific Forage Seed Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement networks. The vendor base spans multinational agribusiness conglomerates with CRISPR-enabled trait pipelines, regional breeding stations with proprietary germplasm pools, and state-linked multiplier networks serving reserve mandates. Three archetypes dominate: technology-integrated global seed houses, temperate grass specialists with export-oriented certification systems, and domestic multiplier networks aligned with cooperative dairy procurement. Competitive moves center on licensed production partnerships in China's multiplication zones and direct breeder-to-producer relationships embedding technical advisory.
Within the technology-integrated tier, Corteva Agriscience leverages gene-editing capabilities to accelerate perennial ryegrass improvements. Bayer AG anchors regional positioning through proprietary seed treatments reducing soil-borne pathogen pressure. Among temperate grass specialists, Royal Barenbrug Group exemplifies export-oriented certification systems for intensive pastoral platforms. These three entities represent distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Bayer AG |
| Royal Barenbrug Group |
| Advanta Seeds - UPL |
| Ampac Seed Company |
| Groupe Limagrain |
| Land O'Lakes Inc |
| PGG Wrightson Seeds |
| Kaveri Seeds |
| Others |
Value Chain & Pricing Dynamics
Phosphorus input volatility across New Zealand's pastoral sector compresses margins for pasture renovation programs, forcing simultaneous price tier compression in certified ryegrass markets and accelerated backward integration into captive fertilizer blending operations across Australian multiplier networks.
Pricing Analysis
Next-generation CRISPR-enabled cultivars command substantial premiums over conventional backcrossed varieties, while legacy shallow-rooted grasses face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and embedded technical advisory intensity. Cost compression in economy-tier uncertified seed is intensifying because India's informal grower networks default on isolation protocols. Dairy cooperatives in Haryana and Punjab exhibit lowest price sensitivity due to bundled input-finance structures, while Myanmar's smallholder producers remain acutely responsive to germination rate guarantees.
Supply Chain Analysis
Tariff exposure between Australia and emerging Mediterranean germplasm sources dominates supply chain risk assessments across the Asia-Pacific forage seed corridor. Foundation stock multiplication concentrates in New Zealand's Canterbury Plains, Australia's Riverina region, and China's Gansu seed zones. Raw material dependencies include phosphorus fertilizer blends, proprietary seed treatment chemistries, and certified foundation germplasm. Distribution runs through breeder-multiplier networks for large station properties, while retail agro-dealers control last-mile delivery to India's fragmented smallholder base.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific forage seed market sits at a cyclical recovery phase driven by crossbred cattle expansion across India's cooperative dairy belts, with procurement committee consolidation creating sustained demand visibility for certified cultivar suppliers.
For Market Incumbents: Entrench germplasm ownership through accelerated PBR filings across trans-Tasman corridors, while securing licensed production partnerships in China's Gansu and Inner Mongolia multiplication zones to neutralize state reserve policy fragmentation. Counter genetic concentration risk by diversifying royalty structures through tiered licensing agreements with secondary breeders. For New Entrants and Emerging Players: Build out technical advisory capabilities targeting Myanmar's underserved upland livestock zones, where first-mover access for New Zealand-origin perennial ryegrass remains unclaimed. Penetrate through precision sowing drone service bundling, leveraging the absence of established breeder-to-producer relationships in highland agricultural areas. For Investors and Strategic Acquirers: The market sits at an expansion phase that favors temperate grass specialists with export-oriented certification systems and captive germplasm libraries. Long-term viability hinges on carbon credit integration potential across Australian perennial pasture establishment programs. Watch Australia's Clean Energy Regulator soil carbon methodology rulings as the critical inflection signal for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Licensed Production Partnership | Establishes compliant seed multiplication within China's state-directed tender framework under Ministry of Agriculture oversight. |
| Genomic Selection Platform Investment | Compresses breeding cycles for drought-tolerant cultivars targeting Murray-Darling Basin irrigation constraints. |
| Blockchain Traceability Implementation | Meets emerging procurement filters from export-oriented New Zealand dairy processors requiring immutable certification records. |
| Carbon Credit Integration Program | Aligns perennial pasture establishment with Australia's Clean Energy Regulator pilot methodologies for tradable offsets. |
| Direct Breeder-to-Producer Relationship | Embeds technical advisory and performance guarantees into seed procurement agreements for consolidated dairy cooperatives. |
Study Parameters
Desk research of customs and trade databases, Plant Breeder's Rights Office filings, and China's Ministry of Agriculture reserve policy documents preceded structured interviews with plant breeding directors, seed multiplication contract managers, dairy cooperative procurement committees, and pastoral research station leads. Bottom-up cultivar volume estimates triangulated against top-down pasture acreage projections derived from irrigation allocation data and livestock inventory reports across the analysis window.
Fixed assumptions included sustained enforcement of India's Seeds Act certification standards, stable trans-Tasman PBR enforcement regimes, and continued Chinese state reserve procurement fragmentation. Modeled dimensions spanned product biology, distribution channel concentration, end-use intensity, and regional regulatory clusters. CAGRs were synthesized from segment-level growth trajectories anchored to livestock herd expansion rates and pasture renovation cycle compression.
Stress conditions across phosphorus fertilizer cost spikes, quarantine protocol tightening, and cooperative procurement committee default rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding genomic selection adoption curves and carbon credit methodology finalization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Buckwheat Market
Seeds
Drought Tolerant Seeds Market
Seeds
Native Grass Seeds Market
Seeds
Mexico Seed Market
Seeds
Cannabis Seeds Market
Seeds
Thailand Seed Market
Seeds
Garden Seeds Market
Seeds
India Vegetable Seed Market
Seeds
India Forage Seed Market
Seeds
Chia Seeds Market
Seeds
Russia Seed Market
Seeds
Philippines Hybrid Rice Seed Market
Seeds
Global Sorghum Seed Market
Seeds
Europe Seed Market
Seeds
Spain Forage Seed Market
Seeds
Global Maize Seed Market