
 Middle East and Africa Cannabis Seeds Market | 2026-2036
Middle East and Africa Cannabis Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cannabis Seeds Market Foresight
High-CBD genetic lines are repositioning product economics across the Middle East and Africa Cannabis Seeds landscape as breeders prioritize compliant, low-THC cultivars for medical authorization. Tikun Olam-Cannbit Pharmaceuticals Ltd. leverages its vertically integrated Israeli operations to anchor regional supply. Panaxia Labs Israel Ltd. differentiates through pharmaceutical-grade extraction and seed-to-oil traceability. InterCure Ltd. controls distribution depth across multiple medical cannabis channels in the region.
Cannabis seeds are botanically classified as dormant embryonic plants encased in a protective testa, typically containing diploid chromosome sets and requiring controlled germination parameters including moisture content between 8-12% and temperatures of 20-25°C for viable propagation; their primary commercial purpose is to establish standardized, genetically consistent crops for medical, research, and licensed personal use. Feminized seeds command the dominant margin pool due to cultivation efficiency and elimination of male plant culling. Autoflowering varieties represent the fastest-expanding genetics category as they reduce cycle times and technical barriers for emerging growers. Distribution through specialty stores and licensed dispensaries captures the highest-value customer segments.
Israel's Medical Cannabis Unit under the Ministry of Health, South Africa's SAHPRA licensing regime, and various national drug enforcement frameworks across the region collectively shape product standards, import permissions, and cultivar approval pathways. Compliance with these overlapping regulatory systems determines market access and seed certification requirements. Stakeholders must monitor licensing velocity and THC threshold adjustments as decisive variables for portfolio allocation.
Market Dynamics
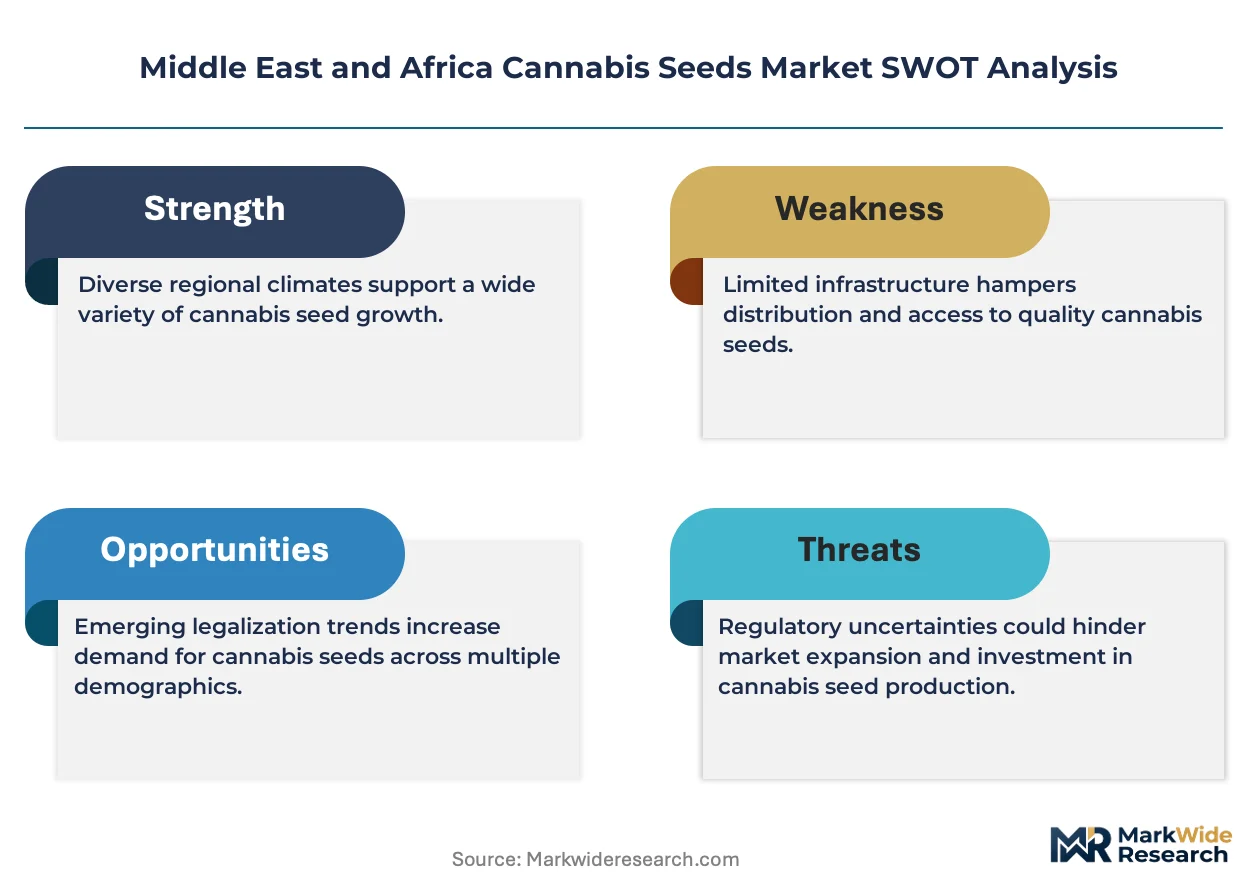
Medical authorization frameworks in Israel and South Africa are creating bifurcated demand pools, with pharmaceutical-grade cultivars commanding premium positioning against unlicensed seed trade.
Growth Catalysts
- Israeli Medical Cannabis Unit licensing:Streamlined cultivar approval pathways accelerate commercial propagation permits for standardized genetics.
- Feminized seed adoption:Commercial growers across South Africa's Western Cape eliminate male culling costs through stabilized female chromosome lines.
- Autoflowering genetics:Reduced technical barriers and compressed cycle times enable emerging cultivators in Lesotho to enter regulated production.
Market Restraints
- Import permit volatility:South Africa's SAHPRA creates seed certification bottlenecks through inconsistent cross-border documentation requirements.
- Genetic supply concentration:Israeli breeders control premium cultivar IP, limiting regional diversification of high-CBD lineages.
- THC threshold rigidity:National drug enforcement frameworks impose cultivar destruction mandates for non-compliant test results.
Strategic Opportunities
- Morocco's emerging pharmaceutical pathway:Draft cannabis legislation signals potential domestic cultivation licensing for export-oriented seed production.
- Seed-to-oil traceability integration:Blockchain-linked genetic verification meets pharmaceutical-grade extraction standards in Israeli vertically integrated operations.
- Direct-to-cultivator digital channels:Licensed e-commerce platforms bypass traditional agricultural supply intermediaries in South Africa's private use market.
Industry Challenges
- Phytosanitary certification timelines:Cross-border seed movement requires multi-jurisdictional testing protocols that extend commercialization schedules.
- Genetic IP enforcement gaps:Unlicensed propagation of proprietary cultivars undermines breeder royalty structures across regional informal markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cannabis Seeds Market |
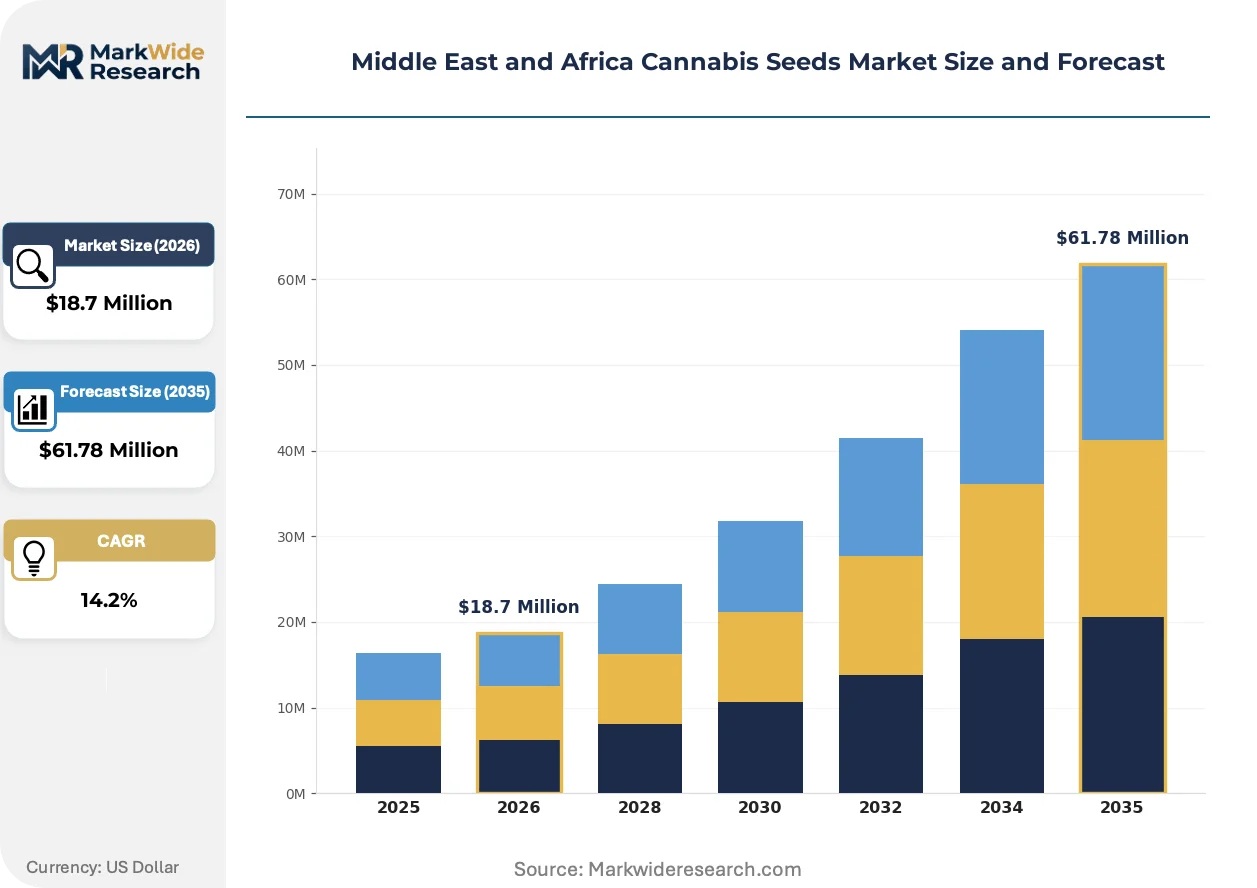
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feminized Seeds, Autoflowering Seeds, Regular Seeds, High-CBD Seeds Distribution Channel: Online Retail, Specialty Stores, Garden Centers, Dispensaries End User: Commercial Growers, Home Cultivators, Research Institutions, Medical Facilities Genetics: Indica, Sativa, Hybrid, Landrace |
| Companies Covered | Tikun Olam-Cannbit Pharmaceuticals Ltd., Panaxia Labs Israel Ltd., InterCure Ltd., BOL Pharma, IM Cannabis Corp., Seach Medical Group, Pharm Yarok, Hempco, Ecofibre, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cannabis Seeds Market Shifts & Advancements
Genetic standardization and regulatory compliance technology are reconfiguring how seed producers capture value, with traceability systems becoming as critical as germination rates for market access.
Marker-assisted breeding platforms is consolidating control over cannabinoid expression predictability. Israeli commercial operations deploy genomic selection to stabilize CBD:THC ratios within narrow pharmaceutical bands. This precision is compressing the trial-and-error cycle for cultivar registration, enabling faster regulatory submission timelines.
SAHPRA's revised licensing categories for private cultivation are creating segmented compliance tiers. Industrial-scale operators face enhanced security and reporting mandates that smaller registered growers avoid. South African seed distributors are responding with tiered product portfolios aligned to license class specifications.
Specialty store consolidation is displacing informal seed exchange networks. Licensed dispensaries in Israel and agricultural cooperatives in South Africa's Eastern Cape now dominate high-value transactions. This channel shift concentrates buyer-seller relationships and reduces price transparency for unconnected cultivators.
Middle East and Africa Cannabis Seeds Market Segmentation
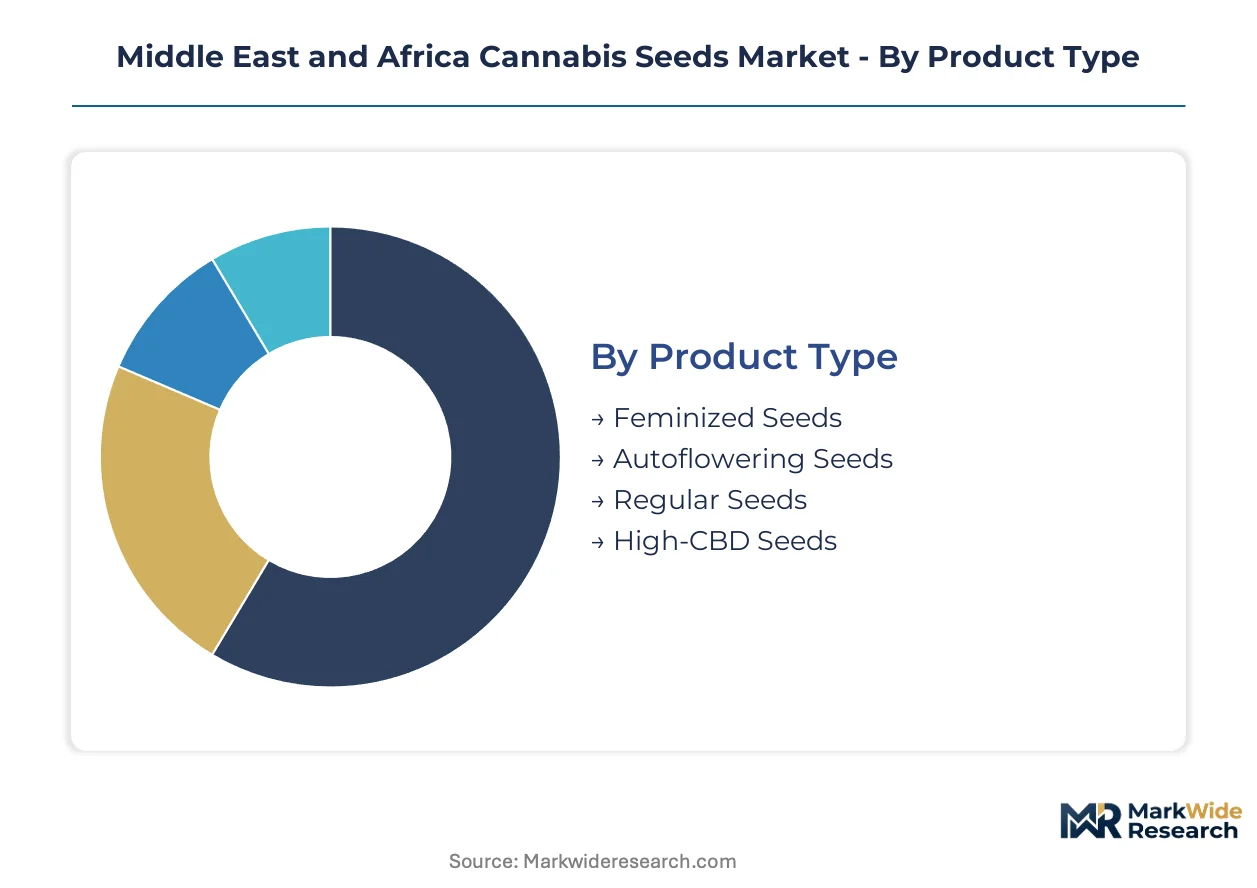
Cannabis seed segmentation in the Middle East and Africa reflects divergent buyer sophistication levels, from Israeli pharmaceutical-grade operators requiring certified genetics to South African home cultivators prioritizing cultivation simplicity. Understanding these segment boundaries enables suppliers to align breeding programs with regulatory tiers and distribution access points.
Product Type:
Buyers differentiate primarily by technical capability and scale, with commercial operations demanding genetic stability while emerging growers seek reduced operational complexity.
- Feminized Seeds:Diploid chromosome lines stabilized through ethylene inhibition or silver thiosulfate treatment eliminate male chromosomes, ensuring 99%+ female plant rates. Israeli commercial licensees under the Medical Cannabis Unit mandate feminized stock to maximize cannabinoid yield per square meter and avoid pollination control costs.
- Autoflowering Seeds:Ruderalis-crossed genetics transition from vegetative to flowering based on age rather than photoperiod, compressing harvest cycles to 8-10 weeks. Lesotho's emerging cultivators and South African private growers adopt these varieties to bypass complex light-deprivation infrastructure and reduce crop failure risk.
- Regular Seeds:Unaltered diploid genetics maintain breeding program viability through male pollen production. South African agricultural cooperatives and Israeli research institutions source regular seeds for phenotypic selection and proprietary cultivar development.
- High-CBD Seeds:Genetically stabilized for sub-0.3% THC expression to comply with pharmaceutical authorization frameworks. Israeli extraction facilities and South African medical distributors prioritize these cultivars for oil production and patient access programs.
Feminized seeds lead volumes today; autoflowering varieties are gaining share fastest.
Distribution Channel:
Channel selection correlates directly with buyer license status and transaction scale, creating parallel markets for authorized and informal procurement.
- Online Retail:Licensed e-commerce platforms with identity verification and prescription upload requirements serve Israel's registered patients and South Africa's private cultivation permit holders. These channels bypass agricultural supply intermediaries but face SAHPRA documentation bottlenecks for cross-border seed movement.
- Specialty Stores:Dedicated cannabis horticulture retailers with climate-controlled storage and genetic certification documentation capture high-value commercial buyers. Tel Aviv and Cape Town retail clusters concentrate inventory of pharmaceutical-grade feminized lines.
- Garden Centers:General agricultural suppliers stock lower-margin regular and autoflowering seeds for hobbyist cultivators. South Africa's Eastern Cape and KwaZulu-Natal garden center networks dominate this price-sensitive tier.
- Dispensaries:Medical cannabis access points in Israel and emerging licensed outlets in South Africa bundle seeds with patient education and cultivation support services. These locations require Ministry of Health or SAHPRA licensing for seed sales authorization.
Specialty stores capture the highest-value transactions; online retail channels are expanding most quickly.
End User:
User categories map to regulatory license classes, with each tier imposing distinct security, reporting, and genetic documentation requirements.
- Commercial Growers:Industrial-scale operations in Israel's Gush Dan region and South Africa's Western Cape require bulk feminized seed contracts with batch-level cannabinoid assay guarantees. These buyers negotiate direct relationships with Israeli breeders to secure proprietary genetics.
- Home Cultivators:Individual permit holders under South Africa's private use exemption and Israel's patient cultivation licenses purchase small-batch feminized and autoflowering varieties. This segment drives demand for simplified cultivation protocols and discrete packaging.
- Research Institutions:Israeli universities and South African agricultural research councils source regular seeds and landrace genetics for breeding program development and phytochemical analysis. These buyers require phytosanitary certification and genetic provenance documentation.
- Medical Facilities:Hospital-affiliated cultivation operations in Israel and licensed medical distributors in South Africa procure high-CBD seeds through tender processes with strict THC threshold compliance mandates.
Commercial growers dominate absolute volumes; home cultivators are climbing the fastest.
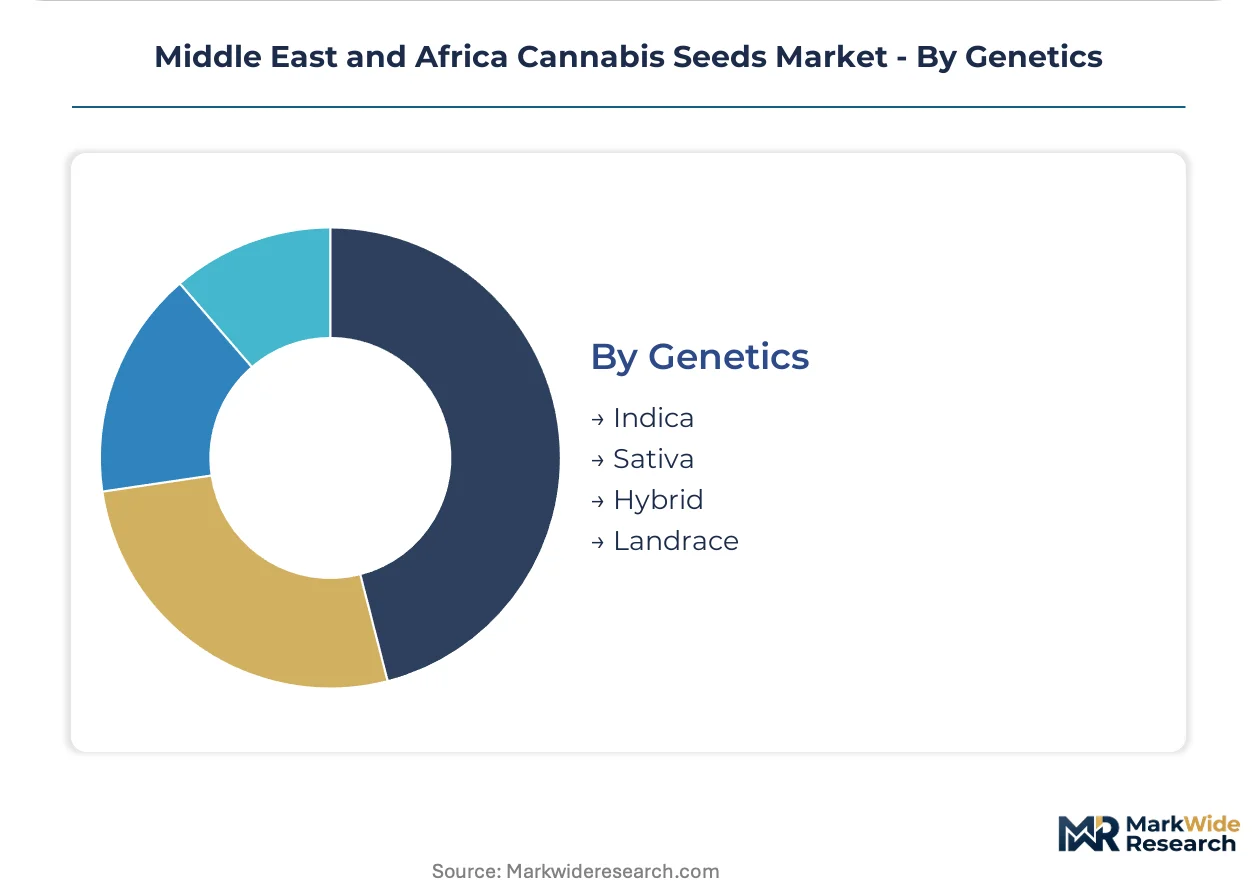
Genetics:
Genetic lineage selection reflects intended therapeutic application, cultivation environment constraints, and breeder IP availability.
- Indica:Short, bushy morphologies with rapid flowering cycles and sedative cannabinoid profiles suit Israeli indoor pharmaceutical operations and South African high-security greenhouse facilities. These genetics dominate medical authorization frameworks targeting pain and sleep disorders.
- Sativa:Tall, photoperiod-sensitive varieties with uplifting terpene profiles require extended flowering periods and precise climate control. Limited adoption in the region reflects infrastructure requirements and THC concentration variability challenges.
- Hybrid:Crossbred lineages combining Indica structure with Sativa cannabinoid expression offer stabilized yields for commercial operations. Israeli breeders dominate hybrid IP, limiting regional diversification.
- Landrace:Indigenous African and Middle Eastern cultivars preserved for genetic diversity and regional adaptation research. Moroccan and South African agricultural programs maintain seed banks for potential future commercialization under evolving pharmaceutical legislation.
Hybrid genetics lead commercial volumes today; landrace preservation programs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's Gush Dan corridor anchors pharmaceutical-grade seed propagation across the Middle East and Africa, with Tel Aviv metropolitan clusters housing vertically integrated breeding operations that supply standardized genetics to regulated medical markets.
Israel
Medical Cannabis Unit licensing drives demand for feminized high-CBD cultivars with batch-level assay guarantees. The Ministry of Health mandates phytosanitary documentation and THC threshold compliance for all commercial propagation permits. Tel Aviv and Rehovot industrial zones concentrate extraction-integrated seed operations serving domestic pharmaceutical channels.
South Africa
Western Cape greenhouse complexes and Eastern Cape agricultural cooperatives generate bifurcated demand for commercial bulk contracts and small-batch home cultivation varieties. SAHPRA's revised private use licensing creates tiered compliance categories with divergent security and reporting mandates. Cape Town specialty retailers and Durban garden center networks dominate contrasting distribution tiers.
Lesotho
Emerging export-oriented cultivation projects prioritize autoflowering genetics to bypass technical infrastructure requirements and compress harvest cycles. The country's national drug regulator coordinates with SAHPRA on cross-border phytosanitary certification protocols. Maseru and surrounding highland districts host contract growing operations supplying South African medical distributors.
Morocco
Draft pharmaceutical cannabis legislation signals potential domestic cultivation licensing for export-oriented seed production and extraction operations. The national pharmaceutical regulator evaluates EU-GMP alignment pathways for future medical authorization frameworks. Rif Mountain traditional growing regions face formalization pressures as policymakers debate transition timelines for existing cultivators.
United Arab Emirates
Research institution demand for cannabinoid analysis and genetic preservation creates niche procurement channels distinct from commercial medical markets. MOHAP maintains strict prohibition on cultivation while permitting controlled laboratory research with imported genetic materials. Dubai biotechnology parks house analytical facilities serving regional pharmaceutical development programs.
Middle East and Africa Cannabis Seeds Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities, with Israeli vertically integrated operators holding advantages in pharmaceutical-grade certification while South African distributors capture emerging private cultivation volumes. Market structure tilts toward concentration at the premium genetics tier, with informal seed exchange networks persisting at price-sensitive entry points. Three archetypes dominate: extraction-integrated pharmaceutical suppliers, specialty retail distributors with climate-controlled inventory, and agricultural supply intermediaries serving hobbyist segments. Competitive dynamics center on genetic IP protection enforcement and direct-to-cultivator digital channel development.
Within the pharmaceutical-integrated tier, Tikun Olam-Cannbit Pharmaceuticals Ltd. and Panaxia Labs Israel Ltd. exemplify vertically structured operations combining breeding programs with extraction and distribution control. InterCure Ltd. occupies a position emphasizing multi-channel distribution depth across medical cannabis access points. These Israeli-anchored entities represent the dominant archetype for regulatory-compliant supply, while South African and Lesotho-based operators compete on volume accessibility for emerging license classes.
| Leading Market Players |
|---|
| Tikun Olam-Cannbit Pharmaceuticals Ltd. |
| Panaxia Labs Israel Ltd. |
| InterCure Ltd. |
| BOL Pharma |
| IM Cannabis Corp. |
| Seach Medical Group |
| Pharm Yarok |
| Hempco |
| Ecofibre |
| Others |
Supply & Pricing Matrix
Israeli commercial growers under the Medical Cannabis Unit anchor pricing power through bulk feminized seed contracts with batch-level cannabinoid assay guarantees, establishing a contract-based long-term offtake model that compresses margins for smaller South African private cultivators.
Pricing Analysis
Input-cost pass-through from phytosanitary certification and genetic testing expenses flows directly into seed pricing, with Israeli breeders absorbing laboratory assay costs while South African distributors pass documentation burdens to buyers. Three-tier pricing structure across pharmaceutical-grade, licensed commercial, and private cultivation tiers reflects certification level and volume scale. Pricing pressure stems from SAHPRA's inconsistent import permit timelines, which extend inventory carrying costs. Home cultivators exhibit highest price sensitivity; commercial growers prioritize genetic stability over per-seed cost.
Supply Chain Analysis
Regional distribution centers in Tel Aviv and Cape Town operate hub-and-spoke patterns radiating to licensed dispensaries and agricultural cooperatives. Supply concentrates in Israel, South Africa, and Lesotho as the primary propagation and distribution nodes. The chain draws from specialized breeding stock, climate-controlled storage infrastructure, and pharmaceutical-grade extraction inputs. Single-source vulnerability around Israeli hybrid IP creates concentration risk. Distribution runs through vertically integrated pharmaceutical suppliers at the premium tier and agricultural supply intermediaries at the hobbyist level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Cannabis Seeds Market functions as a stable compounder, with medical authorization frameworks in Israel and South Africa generating recurring demand for compliant genetics across regulatory cycles.
For Market Incumbents: Deepen backward integration into captive breeding programs to secure proprietary high-CBD lineages against genetic IP enforcement gaps in regional informal markets. Expand climate-controlled storage capacity in Cape Town and Tel Aviv distribution nodes to capture specialty retail consolidation. SAHPRA's licensing velocity fluctuations threaten inventory turns; anchor long-term contracts with commercial growers to stabilize throughput. For New Entrants and Emerging Players: Begin with Lesotho's emerging export-oriented cultivation projects, where autoflowering genetics demand outpaces established supply relationships and technical barriers remain lowest. Morocco's draft pharmaceutical legislation signals a white-space opening for domestic seed production licensing. A direct-to-cultivator digital channel strategy bypasses entrenched agricultural supply intermediaries in South Africa's private use market. For Investors and Strategic Acquirers: Pharmaceutical extraction companies are the most active acquirer in this space, seeking captive seed supply to secure cannabinoid input consistency. The five-to-ten year viability window favors targets with vertically integrated breeding-to-extraction capabilities and established Ministry of Health or SAHPRA licensing relationships. Watch Morocco's formalization timeline for traditional Rif Mountain cultivators as the decisive inflection signal for regional supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Genetic Certification Investment | Batch-level THC compliance documentation unlocks Israeli Medical Cannabis Unit commercial propagation permits. |
| Climate-Controlled Distribution Expansion | Tel Aviv and Cape Town regional hubs capture specialty store consolidation displacing informal exchange networks. |
| Direct-to-Cultivator Digital Platform | Licensed e-commerce with SAHPRA documentation integration bypasses agricultural supply intermediaries. |
| Autoflowering Genetics Portfolio | Ruderalis-crossed lines reduce Lesotho emerging cultivator technical barriers and compress harvest cycles. |
| Blockchain Traceability Integration | Seed-to-oil genetic verification meets pharmaceutical-grade extraction standards in Israeli integrated operations. |
Research Methodology
Multiple input streams — primary interviews with breeding program directors, SAHPRA licensing officers, and medical cannabis dispensary procurement managers; secondary validation through Israeli Ministry of Health regulatory filings, South African agricultural trade data, and pharmaceutical extraction facility disclosures; plus customs documentation for cross-border seed movements — were reconciled through bottom-up and top-down triangulation.
Historical cultivation permit issuance patterns were cross-referenced against panel input from commercial growers and research institutions to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user license class, and genetic lineage. CAGRs were derived from license velocity projections and cannabinoid demand curves, with specific inputs from phytosanitary certification timeline assumptions and feminized seed adoption rates.
Several conditions sit outside the modeled scope, including unlicensed informal seed trade volumes, genetic IP litigation outcomes, and abrupt regulatory reversals in Moroccan or Emirati jurisdictions. Forecasts reflect documented assumptions around licensing pathway stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Rice Seed Market
Seeds
Europe Vegetable Seed Market
Seeds
North America Chia Seeds Market
Seeds
China Rice Seed Market
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Ghana Seed Extract Market
Seeds
Commercial Seed Market
Seeds
Cucumber Seeds Market
Seeds
Okra Seed Market
Seeds
Europe Quinoa Seed Market
Seeds
Ghana Seeds Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
Europe Flaxseeds Market
Seeds
Europe Amaranth Market
Seeds
Asia-Pacific Cotton Seed Market
Seeds
Global Onion Seed Market