
 South Africa Seed Market | 2026-2036
South Africa Seed Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Seed Market Analytics
Commercial grain farming is realigning South Africa's seed procurement patterns as large-scale operations expand hectarage under maize and soybean cultivation. Starke Ayres leverages its long-standing domestic breeding programs to anchor supply relationships with commercial farmers across the Highveld. Bayer AG competes through its trait technology portfolio, while Corteva Agriscience sustains its position via broad germplasm access and regional distribution infrastructure.
Seeds are reproductive units containing embryonic plants protected by seed coats and nutrient storage tissues, typically processed through cleaning, grading, and treatment with fungicides or biological inoculants to achieve specified germination rates and field establishment standards. Their primary commercial purpose is to deliver predictable genetic performance, yield potential, and pest resistance traits to agricultural producers. Grain seeds occupy the dominant value position due to staple crop hectarage, while hybrid seeds command premium positioning through proprietary trait stacks and yield consistency. Vegetable seeds represent a faster-growing margin pool as greenhouse and precision horticulture expand near urban demand centers.
South Africa's Department of Agriculture, Land Reform and Rural Development administers the Plant Improvement Act and GMO regulatory framework, conditioning market access on certified seed standards and trait approval protocols. BIS alignment for imported germplasm and OECD seed certification schemes further shape cross-border supply eligibility. Stakeholders must monitor evolving biosafety assessment timelines and water-use licensing constraints that will determine which seed varieties achieve scalable adoption across drought-exposed production zones.
Market Dynamics
Commercial maize farming operations are consolidating hectarage and procurement volumes, forcing seed suppliers to restructure distribution networks around large-scale grain producers in the Free State and North West provinces. This concentration is compressing traditional dealer margins while elevating trait performance guarantees as the primary purchasing criterion.
Growth Catalysts
- Plant Improvement Act compliance:Certified seed standards administered by South Africa's Department of Agriculture are mandating quality upgrades across commercial farming operations, accelerating replacement cycles for non-certified germplasm.
- Highveld soybean expansion:Rotational cropping patterns are diversifying seed portfolios as commercial growers add legume hectares to break maize monoculture and fix soil nitrogen.
- GMO trait stacking:Insect resistance and herbicide tolerance combinations are reducing per-hectare chemical input costs, driving premium hybrid adoption among mechanized farming operations.
Market Restraints
- Imported germplasm dependency:BIS alignment requirements and OECD certification delays for foreign genetic material are extending variety introduction timelines by 18-24 months.
- Water licensing constraints:Department of Water and Sanitation abstraction permits are restricting irrigation-dependent seed multiplication sites in drought-exposed Limpopo and Mpumalanga regions.
- Input cost volatility:Fertilizer and fuel price fluctuations are squeezing farm operating budgets, compressing discretionary spending on premium certified seed relative to farm-saved alternatives.
Strategic Opportunities
- Greenhouse horticulture clusters:Urban-adjacent vegetable seed demand is expanding near Johannesburg and Cape Town as controlled-environment agriculture shortens supply chains for fresh produce retailers.
- Biosafety assessment streamlining:Proposed amendments to GMO regulatory protocols could accelerate trait approval timelines, reducing commercialization lag for stacked-gene varieties.
- Biological inoculant bundling:Seed treatment partnerships with microbial input suppliers are creating integrated product offerings that differentiate commodity grain seed through yield protection claims.
Industry Challenges
- Plant breeder skill scarcity:Specialized maize and soybean geneticists are concentrated at legacy breeding stations, limiting expansion of regionally adapted variety pipelines for emerging production zones.
- Multi-site trial coordination:Drought stress testing across agro-ecological zones requires replicated evaluation networks that strain field research budgets and extend variety release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Seed Market |
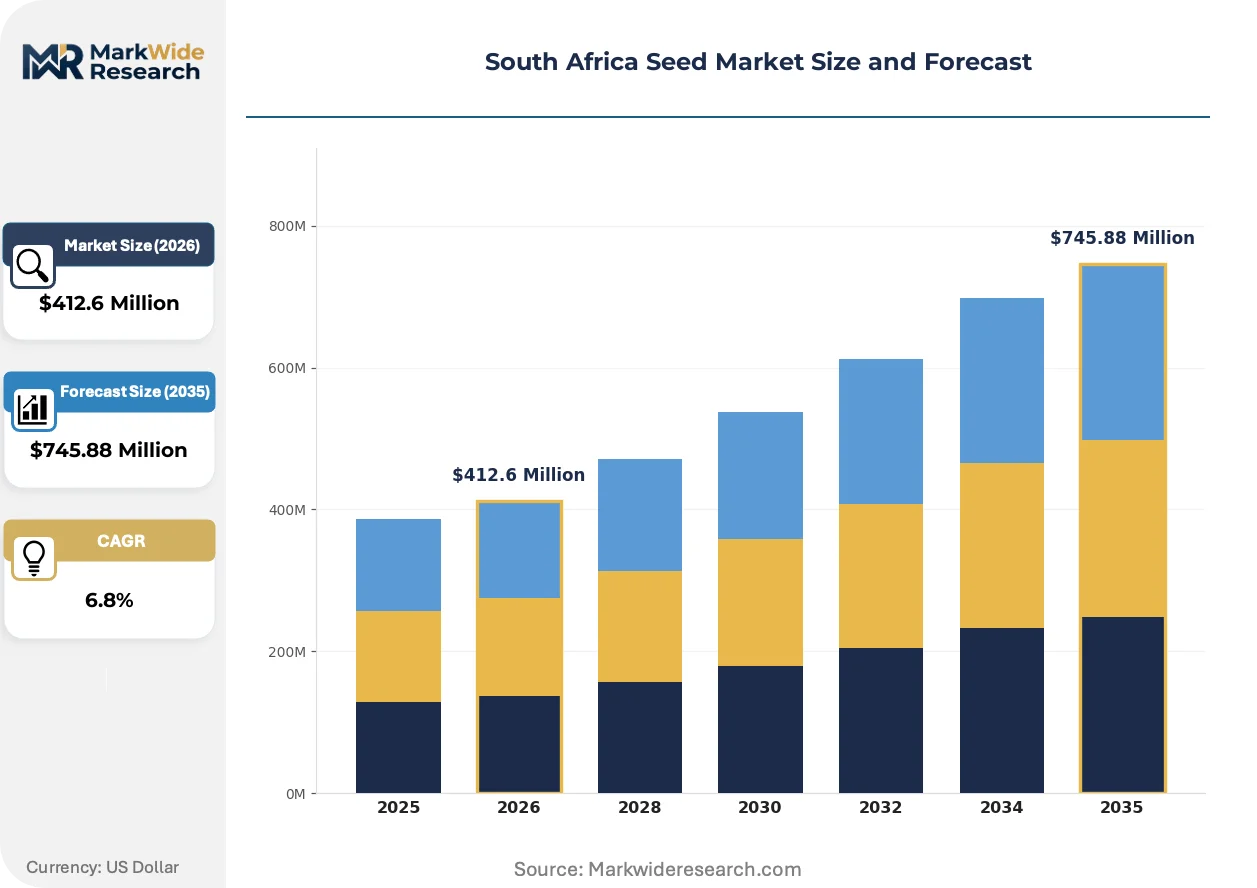
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Seeds, Flower Seeds, Grain Seeds, Turf Seeds End Use Industry: Agriculture, Horticulture, Landscaping, Forestry Distribution Channel: Retail Stores, Online Sales, Agricultural Cooperatives, Wholesale Seed Variety: Hybrid Seeds, Open Pollinated Seeds, Heirloom Seeds, Certified Seeds |
| Companies Covered | Starke Ayres, Syngenta Group, Corteva Agriscience, Bayer AG, Limagrain Zaad South Africa Ltd, Sakata Seed Corporation, Hygrotech, Sensako, Capstone Seed Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Seed Market Evolving Landscape
Digital agriculture tools are penetrating South Africa's commercial farming sector, reshaping how seed performance data is collected, verified, and converted into purchasing decisions across the Highveld grain belt.
Gene editing platforms are integrating CRISPR-based precision breeding into commercial maize development pipelines. Starke Ayres and multinational breeding stations are adopting these tools to accelerate drought tolerance trait introgression. The technology is integrating conventional phenotypic selection with genomic prediction models, compressing variety development cycles from eight years toward five.
South Africa's Department of Agriculture is tightening GMO labeling and traceability requirements under revised biosafety regulations. Seed distributors must now maintain chain-of-custody documentation from import through retail sale. Commercial maize growers in the Free State are responding by consolidating purchases through accredited depots that manage compliance documentation centrally.
Large-scale grain producers are consolidating input purchasing through cooperative procurement alliances. Traditional independent seed dealers in the North West province are losing volume to these centralized buying pools that negotiate direct supply contracts with breeding companies. This concentration is most visible among irrigation-dependent operations where input standardization across multiple farms generates volume discounts and unified technical support.
South Africa Seed Market Segmentation
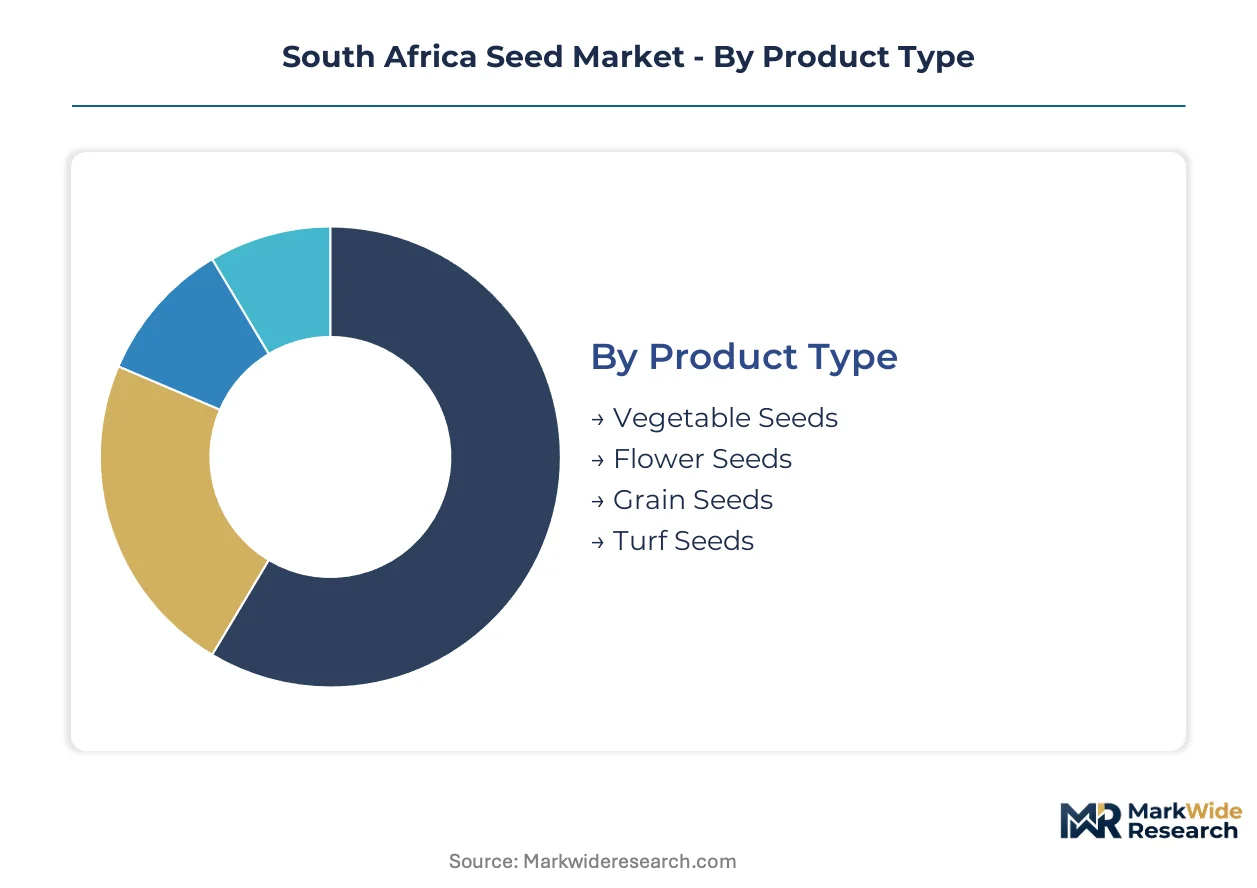
Seed purchasing in South Africa fragments across crop categories, buyer scale, and certification tiers that determine price positioning and regulatory compliance requirements. Understanding these segment boundaries clarifies where breeding investments concentrate and which distribution channels capture margin.
Product Type:
Commercial growers select seed categories based on crop economics, irrigation access, and proximity to processing infrastructure or urban markets.
- Grain Seeds:Maize and soybean germplasm dominates procurement volumes across the Free State and North West provinces. Large-scale mechanized operations prioritize hybrid trait stacks that reduce chemical input costs and deliver yield consistency under variable rainfall.
- Vegetable Seeds:Tomato, pepper, and leafy green varieties are expanding fastest near Johannesburg and Cape Town greenhouse clusters. Controlled-environment agriculture shortens supply chains for fresh produce retailers and commands premium pricing for uniform, pesticide-free output.
- Flower Seeds:Ornamental varieties serve commercial cut-flower operations and municipal landscaping contracts concentrated in Gauteng and Western Cape.
- Turf Seeds:Kikuyu and Bermuda grass cultivators target golf course maintenance, sports field renovation, and residential estate development in coastal and Highveld urban corridors.
Grain seeds lead on scale; vegetable seeds lead on momentum.
End Use Industry:
Application context determines performance specifications, volume procurement patterns, and the importance of certified germplasm documentation.
- Agriculture:Commercial grain and oilseed producers in the Free State drive the dominant share of certified seed offtake. Plant Improvement Act compliance mandates quality upgrades that accelerate replacement cycles for farm-saved alternatives.
- Horticulture:Precision greenhouse operators near urban demand centers prioritize disease-resistant vegetable varieties with uniform maturity windows. These buyers accept price premiums for germplasm that reduces crop protection applications and extends harvest windows.
- Landscaping:Municipal contracts and commercial property developers procure turf and ornamental seeds with drought tolerance specifications suited to water-restricted maintenance regimes.
- Forestry:Eucalyptus and pine plantation operators in Mpumalanga and KwaZulu-Natal select improved seed lots for pulp and timber yield optimization on long rotation cycles.
Agriculture captures the volume base; horticulture captures the margin expansion.
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and the administrative burden of GMO traceability documentation.
- Agricultural Cooperatives:Consolidated procurement alliances among large-scale grain producers negotiate direct supply contracts with breeding companies. These centralized buying pools compress traditional dealer margins while standardizing input quality across member farms.
- Wholesale:Volume distributors serve commercial farming operations requiring bulk delivery, unified technical support, and centralized compliance documentation for stacked-trait varieties.
- Retail Stores:Independent dealers and farm supply outlets retain smaller-scale growers seeking flexible purchase quantities and localized agronomic advice.
- Online Sales:Digital platforms penetrate hobbyist and smallholder segments with vegetable and flower seed varieties, though grain germplasm transactions remain minimal due to certification and trait verification requirements.
Cooperatives lead on volume concentration; wholesale leads on value capture per transaction.
Seed Variety:
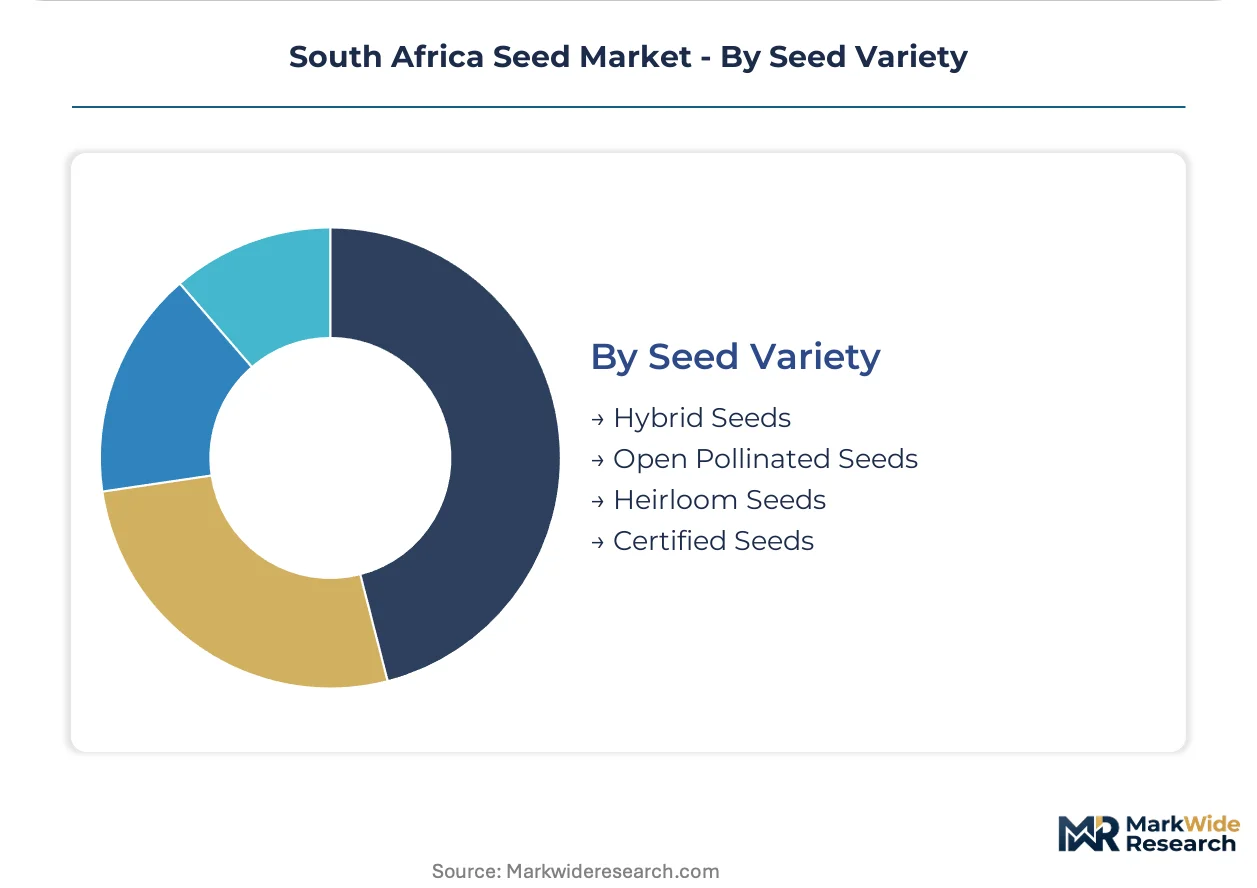
Variety classification determines intellectual property status, replanting rights, and the regulatory pathway for trait introduction.
- Hybrid Seeds:Proprietary maize and soybean crosses with stacked insect resistance and herbicide tolerance dominate commercial grain hectarage. Germplasm performance guarantees and trait reliability justify premium pricing over open-pollinated alternatives.
- Certified Seeds:Plant Improvement Act standards mandate quality verification for commercial distribution, creating a compliance tier that separates formal market supply from informal germplasm exchange.
- Open Pollinated Seeds:Self-pollinating crop varieties allow farmer seed saving and replanting, appealing to cost-constrained operations and heritage crop preservation networks.
- Heirloom Seeds:Non-hybrid vegetable and flower varieties serve niche markets for genetic diversity conservation, organic certification compliance, and specialty produce differentiation.
Hybrid seeds lead on revenue per hectare; certified seeds lead on regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting seed multiplication operations toward provinces with faster water licensing approvals and less stringent biosafety assessment timelines, compressing variety introduction cycles for breeders willing to relocate germplasm testing sites.
Free State
Large-scale maize and soybean producers dominate certified seed procurement volumes across the Highveld. The Department of Agriculture's Plant Improvement Act enforcement mandates quality verification for commercial distribution, accelerating replacement of farm-saved germplasm. Bloemfontein anchors regional distribution networks serving mechanized grain operations with stacked-trait hybrid portfolios.
North West
Irrigation-dependent farming clusters are consolidating input purchasing through cooperative procurement alliances that negotiate direct supply contracts with breeding companies. Water-use licensing constraints from the Department of Water and Sanitation are restricting seed multiplication site expansion near Rustenburg and Potchefstroom, forcing breeders toward rain-fed testing protocols.
Limpopo
Drought-exposed production zones are prioritizing drought-tolerant maize varieties with accelerated breeding cycles. Extended biosafety assessment timelines for imported germplasm are delaying trait introduction by 18-24 months across the province. Polokwane and Tzaneen host limited seed treatment facilities serving vegetable operations supplying Gauteng retail markets.
Mpumalanga
Forestry seed demand from eucalyptus and pine plantation operators sustains improved germplasm procurement for long rotation cycles. Water abstraction permit restrictions are constraining irrigation-dependent seed multiplication infrastructure near Nelspruit. The province's agro-ecological diversity supports multi-site drought stress testing for regional variety adaptation.
Western Cape
Greenhouse horticulture clusters near Cape Town are expanding vegetable seed demand for controlled-environment tomato and pepper production. Urban-adjacent precision agriculture operations command premium pricing for disease-resistant varieties with uniform maturity windows. The province's water-restricted maintenance regimes favor drought-tolerant turf and ornamental seed specifications.
South Africa Seed Market Competitive Landscape
Strategic partnerships dominate the current landscape as multinational breeders align with domestic distributors to navigate GMO traceability requirements and centralized procurement alliances. The vendor base concentrates around three tiers: global trait technology providers with proprietary germplasm stacks, regional breeding stations with long-standing farmer relationships, and specialized vegetable seed suppliers serving greenhouse clusters. Portfolio diversification into biological inoculant bundling and geographic expansion through accredited depot networks represent the dominant competitive moves reshaping channel access.
Within the multinational technology tier, Bayer AG and Corteva Agriscience exemplify archetypes competing through trait reliability guarantees and broad germplasm access. Starke Ayres occupies a position representing domestic breeding stations leveraging decades-long Highveld variety development to anchor supply relationships with commercial grain producers. Among specialized distributors, Hygrotech and Sensako sit within the vegetable and grain seed segments respectively, serving regional greenhouse clusters and mechanized farming operations with localized agronomic support.
| Leading Market Players |
|---|
| Starke Ayres |
| Syngenta Group |
| Corteva Agriscience |
| Bayer AG |
| Limagrain Zaad South Africa Ltd |
| Sakata Seed Corporation |
| Hygrotech |
| Sensako |
| Capstone Seed Group |
| Others |
Value Network & Pricing Analysis
Water-use licensing constraints from South Africa's Department of Water and Sanitation gate both qualified seed multiplication sites and premium-tier hybrid access, concentrating supply among breeders with rain-fed testing protocols and certified irrigation permits while elevating trait-guarantee pricing for drought-tolerant portfolios.
Pricing Analysis
Distributor margin compression is reshaping South Africa's seed pricing architecture as cooperative procurement alliances negotiate direct supply contracts with breeding companies. Three-tier pricing structure across premium, standard, and economy levels separates stacked-trait hybrids with insect resistance and herbicide tolerance guarantees from certified open-pollinated varieties and farm-saved alternatives. Pricing pressure stems from input cost volatility in fertilizer and fuel, squeezing operating budgets for mechanized grain operations. Small-scale vegetable growers near urban greenhouse clusters show lowest price sensitivity, accepting premiums for disease-resistant germplasm with uniform maturity windows.
Supply Chain Analysis
Specialized plant breeder scarcity in South Africa's Highveld region constrains expansion of regionally adapted variety pipelines for emerging production zones. Germplasm development draws from multinational breeding stations in the United States and Europe, with trait stacking protocols resting on proprietary genetic material subject to OECD certification delays. Single-source vulnerability runs through imported germplasm dependency, where BIS alignment requirements extend variety introduction timelines. Distribution runs through agricultural cooperatives and wholesale depots managing centralized GMO traceability documentation for stacked-trait hybrids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's seed market offers margin expansion through biological inoculant bundling and greenhouse horticulture premiumization, with cost-down drivers emerging from digital agriculture tools compressing variety development cycles.
For Market Incumbents: Lock in supply relationships with Free State cooperative procurement alliances through performance-guarantee contracts on stacked-trait hybrids. Deepen backward integration into seed treatment facilities to capture biological inoculant bundling premiums. Threat from Corteva Agriscience and Bayer AG trait technology portfolios demands accelerated CRISPR-based drought tolerance programs at domestic breeding stations. For New Entrants and Emerging Players: Launch via accredited depot networks serving Limpopo and Mpumalanga drought-exposed zones with regionally adapted open-pollinated maize varieties. Target Western Cape greenhouse horticulture clusters with disease-resistant tomato and pepper germplasm, where controlled-environment agriculture commands weakest incumbent penetration. Go-to-market angle: localized agronomic support partnerships with municipal landscaping contractors for drought-tolerant turf specifications. For Investors and Strategic Acquirers: Roll-up economics work for specialized vegetable seed distributors because urban-adjacent greenhouse clusters near Johannesburg and Cape Town fragment across sub-scale regional players lacking unified technical support infrastructure. Long-term viability centers on consolidation plays capturing premium-mid-economy pricing differentiation in precision horticulture. Acquisition target archetype: domestic breeding stations with Plant Improvement Act certification infrastructure and multi-site drought stress testing networks. Signal to watch: proposed GMO regulatory protocol amendments accelerating biosafety assessment timelines for stacked-gene varieties.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Inoculant Bundling | Seed treatment partnerships with microbial input suppliers differentiate commodity grain seed through yield protection claims. |
| Greenhouse Horticulture Expansion | Urban-adjacent controlled-environment agriculture near Cape Town shortens supply chains for fresh produce retailers. |
| Accredited Depot Network Buildout | Centralized GMO traceability documentation management captures cooperative procurement alliance volume from traditional dealers. |
| CRISPR-Based Trait Development | Gene editing platforms compress variety development cycles from eight years toward five for drought tolerance introgression. |
| Multi-Site Drought Stress Testing | Replicated evaluation networks across agro-ecological zones accelerate regional variety adaptation for Limpopo production zones. |
Research Methodology
Direct dialogue with plant breeders at Starke Ayres and multinational breeding stations, seed distribution managers at agricultural cooperatives, commercial grain producers in the Free State, and Department of Agriculture regulatory affairs officers grounded qualitative findings. Secondary validation drew from Plant Improvement Act compliance records, Department of Water and Sanitation abstraction permit databases, OECD seed certification scheme documentation, and customs data on imported germplasm volumes. Bottom-up variety-level demand estimates triangulated against top-down sector expenditure projections from agricultural census data.
Segmented outputs across grain, vegetable, flower, and turf seed categories incorporate hybrid, certified, open-pollinated, and heirloom variety classifications, with distribution channel splits between cooperatives, wholesale, retail, and online sales. CAGRs were derived from historical procurement volume trends and projected hectarage expansion under commercial maize and soybean cultivation, adjusted for GMO trait adoption rates and water licensing constraint scenarios. Forecast inputs include biosafety assessment timeline assumptions and drought frequency projections across the Highveld.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended Department of Agriculture GMO approval delays or severe drought triggering emergency water-use restrictions. Material deviation in Plant Improvement Act enforcement intensity or cooperative procurement alliance consolidation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Sorghum Seed Market
Seeds
Global Sunflower Market
Seeds
Global Seed Market
Seeds
Global Soybean Seed Market
Seeds
Chamomile Seeds Market
Seeds
China Rice Seed Market
Seeds
Europe Sesame Seed Market
Seeds
Africa Chia Seeds Market
Seeds
Hemp Seed Oil Market
Seeds
North America Tomato Seed Market
Seeds
Agricultural Seeder Market
Seeds
Asparagus Seeds Market
Seeds
India Maize Seed Market
Seeds
Mexico Seed Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Sweet Corn Seeds Market