
 Europe Grain Seed Market | 2026-2036
Europe Grain Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Grain Seed Market Foresight
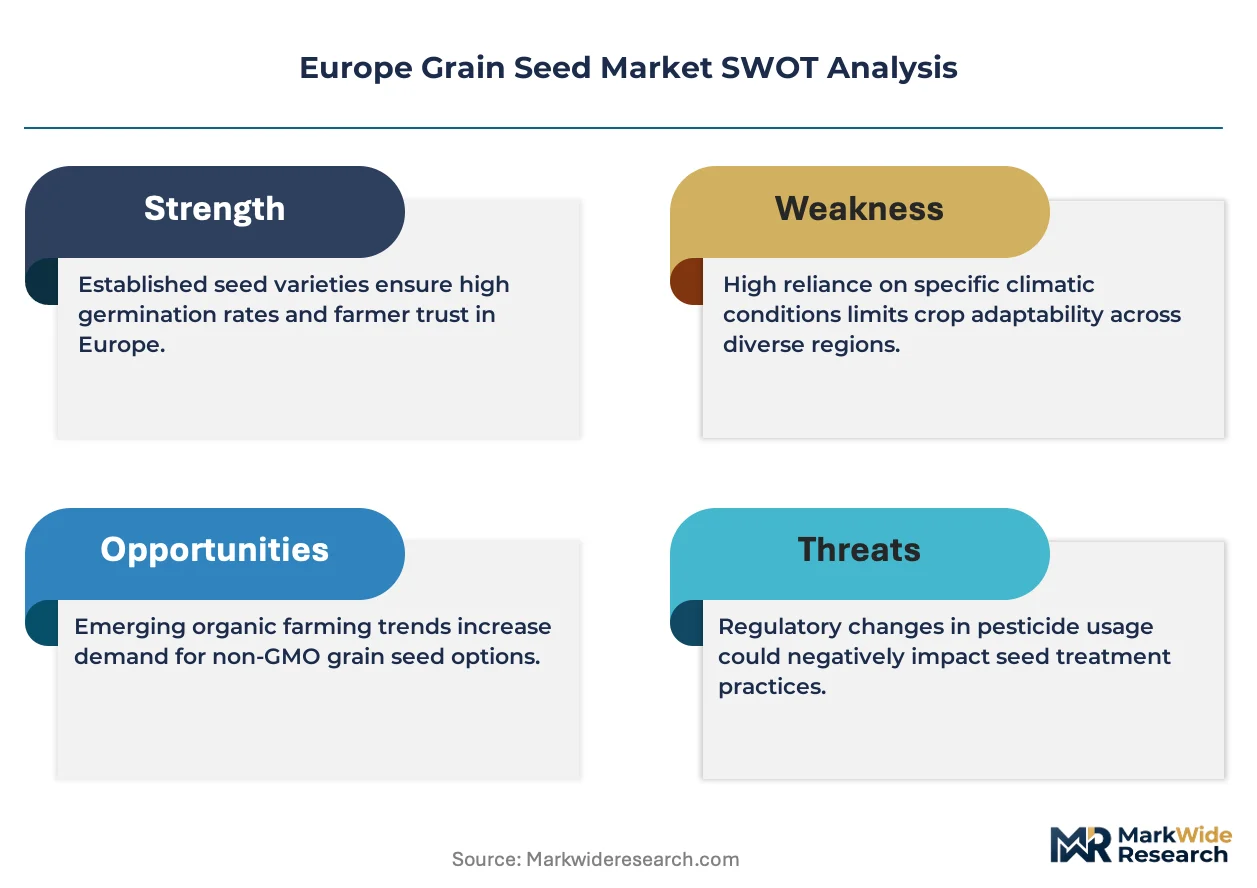
The Europe grain seed sector is restructuring around a widening performance gap between premium hybrid portfolios and commodity open-pollinated lines. KWS SAAT SE & Co. KGaA leverages its deep breeding infrastructure to dominate high-value hybrid wheat in Germany and Poland. RAGT Group anchors its position through specialized durum wheat genetics tailored to Mediterranean climates. Bayer AG competes via integrated trait platforms that bundle herbicide tolerance with yield stability across multiple cereal species.
Europe grain seed comprises genetically improved cereal propagules—typically treated with fungicides or insecticides and certified for minimum germination rates, varietal purity, and seed health standards—developed for commercial sowing in bread wheat, feed barley, grain maize, milling oats, and malting barley production. Wheat and maize segments command the deepest margin pools where hybrid conversion rates still lag North American benchmarks, while barley maintains steady demand from brewing and animal feed compounders across France, the United Kingdom, and Spain. The grade dimension shows hybrid varieties capturing investment priority from multinationals, even as open-pollinated lines retain cost-sensitive share in Eastern European markets where farm scale remains below threshold for premium seed economics.
Regulatory frameworks including the EU Seed Marketing Directives, REACH for treated seed coatings, and the EU Green Deal's pesticide reduction targets collectively reshape product registration timelines and trait investment priorities across the continent. EFSA and national variety registration authorities in France and Germany enforce distinct DUS testing protocols that filter market access for non-adapted genetics. Stakeholders must track how the EU's pending revision of seed marketing rules interacts with national derogations for organic and heterogeneous material, as this regulatory intersection will determine which breeding programs secure multi-country deployment rights.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing registration timelines for treated seed coatings while accelerating hybrid conversion rates in wheat and maize. This regulatory pressure intersects with farm consolidation in France and Germany to reshape seed economics across the continent.
Growth Catalysts
- EU Green Deal pesticide reduction targets:Breeders are redirecting R&D toward native pest resistance traits in cereal lines, creating pull-through demand for certified seed with embedded genetic protection.
- Biofuel sector expansion:German and French ethanol producers are locking multi-year contracts for high-starch maize varieties, guaranteeing offtake volumes that justify premium seed pricing.
- Gene editing acceleration:CRISPR-derived drought tolerance traits are advancing through EFSA regulatory pathways faster than transgenic alternatives, shortening variety development cycles.
Market Restraints
- REACH compliance costs for seed coatings:The ECHA authorization process for neonicotinoid alternatives adds 18-24 months to product launch timelines.
- Parent seed supply concentration:Hybrid wheat cytoplasmic male sterile lines remain concentrated among three European breeding consortia, creating germplasm access bottlenecks.
- Open-pollinated barley substitution:Farm-saved seed rates in Spain and Italy exceed 40% for feed barley, compressing addressable market for certified varieties.
Strategic Opportunities
- Polish and Romanian farm scale threshold:Consolidation in these markets is approaching minimum viable scale for hybrid wheat economics, opening conversion opportunities.
- Carbon credit certification for seed production:The EU Carbon Removal Certification Framework creates monetization pathways for low-input breeding programs.
- Direct-to-farm digital channels:Bayer and KWS are piloting variety-matching algorithms that bypass distributor markups in the Paris Basin.
Industry Challenges
- Quantitative genetics talent scarcity:European universities are producing fewer plant breeders with genomic selection expertise than industry replacement demand requires.
- DUS testing backlog at INRAE and BSA:France and Germany's variety registration authorities face 14-month queues, delaying commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Grain Seed Market |
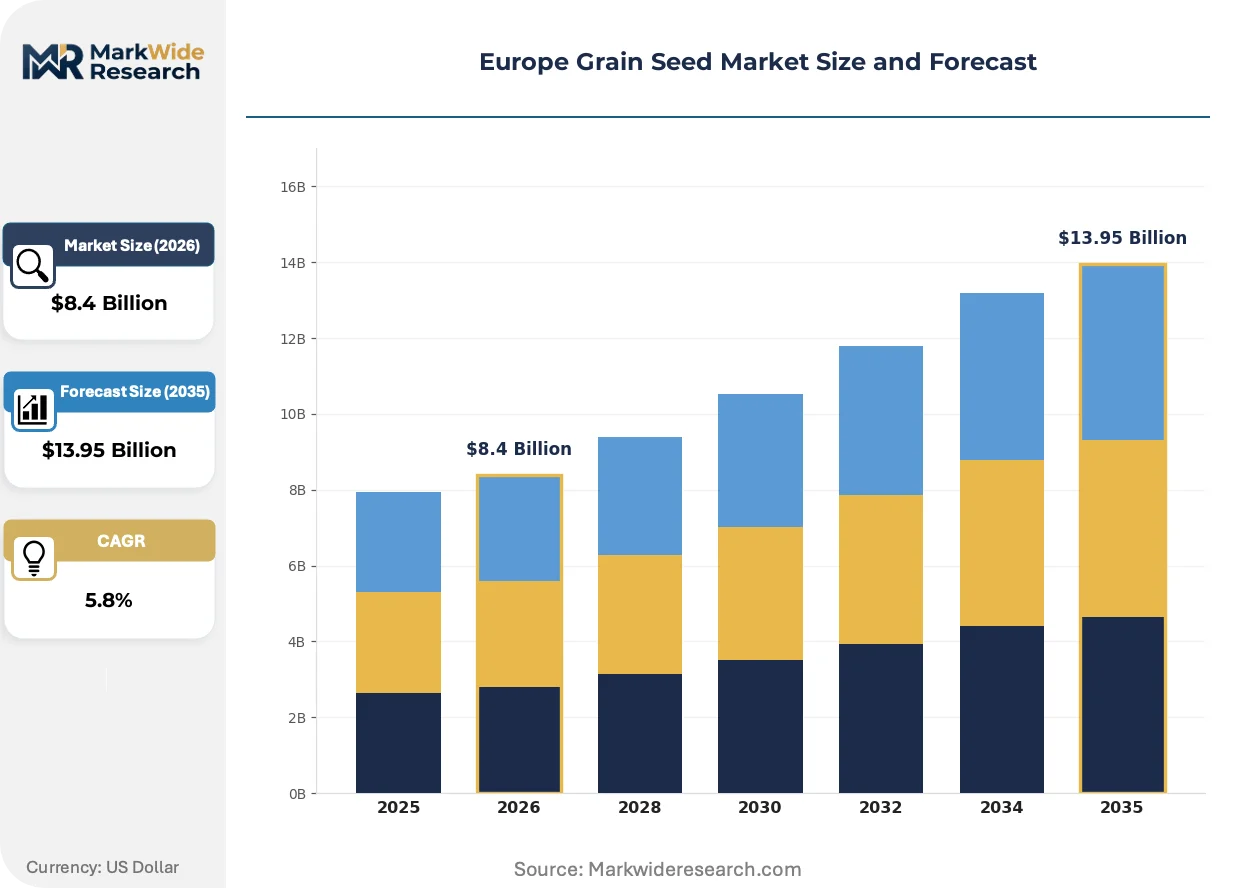
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat, Barley, Maize, Oats End Use Industry: Agriculture, Food Processing, Animal Feed, Biofuels Grade: Hybrid, Open-Pollinated, Organic, Conventional Packaging Type: Bulk Bags, Pouches, Bags, Containers |
| Companies Covered | KWS SAAT SE & Co. KGaA, RAGT Group, Bayer AG, Advanta Seeds, Euralis Group, Corteva Agriscience, Syngenta Group, Lidea, Groupe Limagrain, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Grain Seed Market Shifts & Advancements
Genomic prediction tools and accelerated breeding cycles are compressing the traditional 10-year variety development timeline. These advances intersect with regulatory pressure on chemical inputs to redefine competitive advantage in cereal seed.
Multi-environment genomic selection is rewriting how European breeders allocate field trial resources. KWS and RAGT have deployed predictive models that reduce preliminary yield trial acreage by 60%. French and German breeding stations now prioritize genotyping throughput over phenotyping scale. This compression is enabling smaller programs to compete with established hybrid wheat portfolios.
REACH authorization for novel seed treatment actives is tightening the regulatory bottleneck for fungicide-insecticide combinations. The ECHA restriction roadmap is phasing out chlorothalonil and neonicotinoid alternatives simultaneously. Malting barley and milling oat segments face the steepest compliance cliffs, as these crops lack the R&D investment depth of maize and wheat.
Cooperative procurement pools among Bavarian and Alsatian farm groups are displacing individual farm seed orders. These aggregates negotiate variety exclusivity clauses and volume-based royalty discounts directly with breeders. The channel shift is most visible in hybrid maize, where 30% of German acreage now moves through structured buying groups rather than traditional distributors.
Europe Grain Seed Market Segmentation
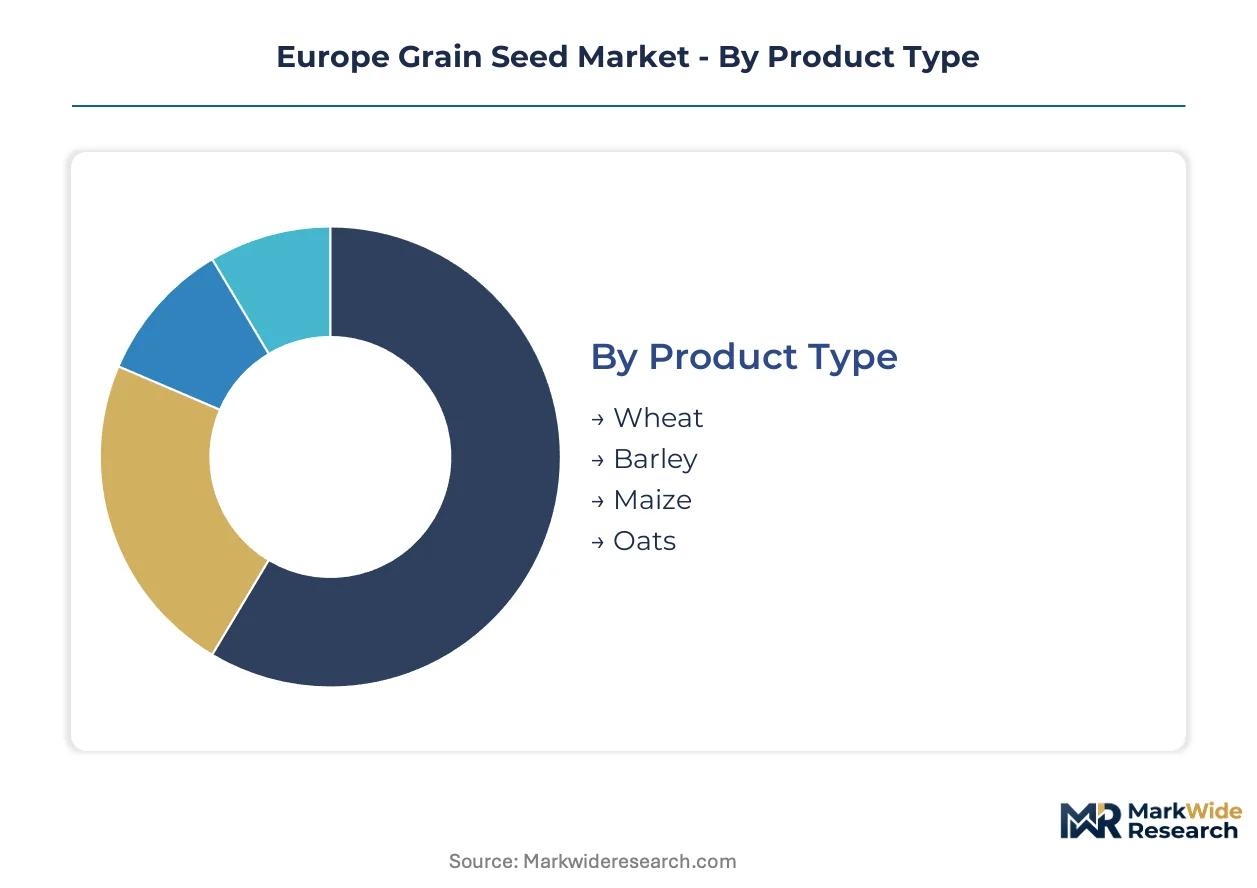
Grain seed segmentation in Europe reflects divergent capital requirements across breeding technologies and crop species. Breeders allocate R&D investment toward hybrid platforms where intellectual property protection justifies multi-decade payback periods, while open-pollinated lines serve price-sensitive volume segments.
Product Type:
Capital intensity peaks in hybrid maize and wheat, where cytoplasmic male sterile line development demands sustained breeding infrastructure investment across multiple environments.
- Wheat:Hybrid wheat conversion lags North American benchmarks, creating concentrated investment opportunity in France's Paris Basin and Germany's Bavaria where farm scale now supports premium seed economics. KWS SAAT SE maintains dominant breeding infrastructure for this transition.
- Maize:High-starch varieties command deepest margin pools as German and French biofuel producers lock multi-year offtake contracts. Parent seed production for hybrid maize requires dedicated isolation zones and multi-year inventory cycles.
- Barley:Malting specifications from brewing compounders in the United Kingdom and Spain drive certified seed demand, though farm-saved substitution exceeds 40% in Mediterranean feed barley markets.
- Oats:Milling oat breeding attracts limited multinational investment, leaving regional programs in Scandinavia and the United Kingdom to serve breakfast cereal and specialty feed niches.
Most installed capacity flows through wheat and maize. Expansion is steepest in hybrid maize as biofuel offtake guarantees accelerate.
End Use Industry:
Downstream concentration determines seed specification requirements, with biofuel and malting barley buyers imposing strict compositional standards that cascade back to variety selection.
- Agriculture:Commercial farm operations in France and Germany drive demand for performance-guaranteed hybrids with embedded trait packages for herbicide tolerance and disease resistance.
- Food Processing:Milling wheat and malting barley specifications from industrial buyers in the United Kingdom and Spain require certified seed with documented protein content and germination uniformity.
- Animal Feed:Feed compounders prioritize yield stability and dry matter digestibility, accepting open-pollinated barley and oats where farm scale falls below hybrid economics thresholds.
- Biofuels:German and French ethanol producers contract directly for high-starch maize varieties, creating guaranteed offtake that justifies premium seed pricing and dedicated breeding programs.
Volume concentration sits with agriculture and animal feed. Value capture concentrates in biofuels where contract structures de-risk seed investment.
Grade:
Regulatory differentiation between hybrid and open-pollinated varieties shapes breeding program economics, with EU Seed Marketing Directives creating compliance cost tiers that filter market access.
- Hybrid:Cytoplasmic male sterile systems command R&D priority from multinationals, though parent seed supply concentration among three European breeding consortia creates germplasm access bottlenecks for new entrants.
- Open-Pollinated:Lower seed production costs retain share in Eastern European markets where farm scale remains below threshold for premium hybrid economics, particularly in feed barley and oats.
- Organic:EU Green Deal pesticide reduction targets accelerate demand for varieties bred under organic protocols, though DUS testing backlogs at INRAE and BSA delay variety registration.
- Conventional:Treated seed coatings face REACH authorization delays of 18-24 months for neonicotinoid alternatives, compressing margins as compliance costs rise.
Revenue concentration favors hybrid platforms. Regulatory tailwinds are strengthening fastest in organic as the Farm to Fork strategy tightens sustainability criteria.
Packaging Type:
Distribution channel structure determines packaging specification, with cooperative procurement pools in Bavaria and Alsace displacing individual farm orders and favoring bulk formats.
- Bulk Bags:Structured buying groups representing 30% of German hybrid maize acreage negotiate volume-based royalty discounts, requiring tote-scale packaging and direct-to-farm logistics.
- Pouches:Small-scale specialty varieties and trial quantities move through distributor networks serving fragmented Eastern European markets.
- Bags:Standard 25-50 kg units dominate traditional distributor channels in France and Spain, though markups face pressure from digital direct-to-farm pilots by KWS and Bayer.
- Containers:Climate-controlled bulk containers serve large-scale farm operations and seed company inventory management across multiple sowing seasons.
Volume flows predominantly through bulk bags and standard bags. Channel shift toward cooperative procurement is accelerating bulk bag uptake fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plant breeding talent concentrates in Germany's Bavaria and France's Paris Basin, where university-industry partnerships sustain hybrid wheat development pipelines. These clusters anchor European cereal seed innovation.
Germany
Bavarian farm consolidation accelerates hybrid wheat uptake as operations cross minimum viable scale thresholds. The Federal Office of Plant Varieties enforces distinct DUS testing protocols that filter market access for non-adapted genetics. KWS SAAT SE maintains deep breeding infrastructure around Einbeck, supplying cytoplasmic male sterile lines across Central Europe.
France
Paris Basin growers drive demand for performance-guaranteed hybrids with embedded disease resistance traits. INRAE variety registration queues stretch 14 months, delaying commercial launches for new entrants. Euralis Group and RAGT Group anchor specialized durum wheat programs in southwestern production zones.
Poland
Farm scale thresholds in Greater Poland Voivodeship approach viability for premium hybrid economics. National regulators align with EU Seed Marketing Directives while maintaining flexibility for regional adaptation trials. Cooperative procurement pools in Mazovia negotiate volume-based royalty discounts directly with breeders.
Spain
Andalusian feed barley markets exhibit 40% farm-saved seed substitution, compressing certified variety demand. Spanish variety registration authorities process DUS applications under EU harmonized standards with national derogations for Mediterranean climates. Malting specifications from brewing compounders in Catalonia sustain premium certified seed pockets.
United Kingdom
East Anglian milling wheat producers impose strict protein content specifications cascading back to variety selection. The Agriculture and Horticulture Development Board coordinates recommended list trials that gate market access for new genetics. Distinct malting barley demand from Scottish whisky distillers maintains specialized breeding investment.
Europe Grain Seed Market Competitive Landscape
Top-tier vendors anchor hybrid platform development, while mid-tier specialists and regional cooperatives occupy differentiated positions. The vendor base stratifies across three archetypes: multinational integrated trait platforms, specialized cereal breeding houses, and farmer-owned cooperative seed enterprises. Consolidation pressure intensifies as REACH compliance costs and genomic selection infrastructure requirements raise capital barriers. Dominant competitive moves include strategic partnerships for germplasm access and direct-to-farm digital channel pilots.
Among German-based breeding houses, KWS SAAT SE & Co. KGaA exemplifies the deep infrastructure archetype for hybrid wheat development. Bayer AG occupies a position within the integrated trait platform tier, bundling crop protection compatibility with seed genetics. RAGT Group represents specialized adaptation to Mediterranean climate zones. These three anchors illustrate how competitive positioning stratifies across breeding technology depth, geographic specialization, and downstream channel control.
| Leading Market Players |
|---|
| KWS SAAT SE & Co. KGaA |
| RAGT Group |
| Bayer AG |
| Advanta Seeds |
| Euralis Group |
| Corteva Agriscience |
| Syngenta Group |
| Lidea |
| Groupe Limagrain |
| Others |
Supply & Pricing Matrix
Hybrid conversion in wheat and maize simultaneously compresses per-unit seed production costs and concentrates germplasm ownership among three European breeding consortia, reshaping how value flows through the Europe grain seed supply chain. This technological transition amplifies pricing power for integrated trait platforms while squeezing margins for open-pollinated specialists.
Pricing Analysis
Bundled trait packages versus unbundled commodity seed splits the Europe grain seed pricing architecture. Three-tier pricing structure across premium hybrid, certified standard, and farm-saved economy levels dominates transaction structures, with biofuel contract tiers commanding the deepest premiums. Price differentiation hinges on germplasm exclusivity and volume scale, with cooperative procurement pools in Bavaria extracting 15-20% royalty discounts. Pricing pressure stems from REACH compliance cost pass-through for neonicotinoid alternative coatings. Animal feed compounders exhibit highest price sensitivity, while biofuel ethanol producers show lowest sensitivity due to multi-year offtake guarantees.
Supply Chain Analysis
Parent seed supply rests on concentrated breeding infrastructure in Germany, France, and the Netherlands, where cytoplasmic male sterile line development demands multi-year inventory cycles. Critical inputs include hybrid maize inbred lines, wheat cytoplasmic male sterile germplasm, and REACH-compliant seed treatment actives. Single-source vulnerability concentrates around three European consortia controlling hybrid wheat parent lines. Distribution runs through cooperative procurement pools displacing traditional agricultural distributors, with 30% of German hybrid maize acreage now moving through structured buying groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe grain seed market functions as a stable compounder anchored by biofuel sector offtake guarantees that de-risk seed investment across economic cycles.
For Market Incumbents: Anticipate regulatory compression from EU Green Deal pesticide reduction targets by accelerating native pest resistance trait pipelines. Defensive consolidation through germplasm access partnerships with Polish and Romanian breeding stations counters Eastern European farm scale thresholds approaching hybrid viability. Channel control investments in direct-to-farm digital platforms protect margin pools from cooperative procurement displacement. For New Entrants and Emerging Players: Direct-to-farm variety-matching algorithms offer the lowest-friction entry route around entrenched distributor networks. White-space concentrates in organic heterogeneous material varieties where INRAE and BSA registration backlogs delay incumbent launches. Target malting barley segments in Spain and Italy where farm-saved substitution exceeds 40% and certified variety demand remains underpenetrated. For Investors and Strategic Acquirers: Valuations sit cheapest among regional cooperative seed enterprises with captive grower bases and underutilized breeding infrastructure. Long-term viability across a 5-10 year window depends on genomic selection capability depth and EFSA regulatory pathway experience. The signal to watch is Polish and Romanian farm consolidation velocity as a proxy for hybrid wheat conversion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Native Pest Resistance Trait Pipeline | EU Green Deal pesticide reduction targets redirect R&D toward embedded genetic protection traits. |
| Cooperative Procurement Partnership | Bavarian and Alsatian farm groups negotiate volume-based royalty discounts displacing distributor markups. |
| Direct-to-Farm Digital Channel | Bayer and KWS pilot variety-matching algorithms bypassing traditional distribution infrastructure. |
| Gene Editing Regulatory Pathway | CRISPR-derived drought tolerance advances through EFSA faster than transgenic alternatives. |
| Carbon Credit Certification Program | EU Carbon Removal Certification Framework monetizes low-input breeding program differentiation. |
Research Methodology
Multiple input streams — breeder R&D executives, cooperative procurement managers, biofuel offtake contract officers, and EFSA regulatory affairs specialists — were reconciled against secondary validation from EU Seed Marketing Directives filings, ECHA authorization databases, national variety registration authority queues, and farm structure census data. Bottom-up acreage and seeding rate estimates were triangulated against top-down market value reconstructions.
Data-stream reconciliation anchored the forecast framework across product type, end-use industry, grade tier, and regional adoption pattern dimensions. CAGRs were derived from segmented growth trajectory modeling incorporating biofuel contract volume guarantees, farm consolidation velocity thresholds, and hybrid conversion rate assumptions. Industry-specific inputs included parent seed inventory cycles, DUS testing queue durations, and REACH compliance cost pass-through elasticity.
The model assumes a particular technology adoption path; alternative pathways for gene-edited trait commercialization would alter the outlook through accelerated variety development cycles or regulatory pathway fragmentation. Forecasts reflect assumptions about EU Green Deal implementation pace and biofuel mandate stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Maize Seed Market
Seeds
Avena Sativa Market
Seeds
Global Oilseed Market
Seeds
Garlic Chive Seeds Market
Seeds
Ghana Seed Extract Market
Seeds
North America Cannabis Seeds Market
Seeds
Watermelon Seeds Market
Seeds
Psyllium Seed Market
Seeds
China Vegetable Seed Market
Seeds
Pigeon Pea Market
Seeds
Southeast Asia Seed Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
India Forage Seed Market
Seeds
Morocco Seed Market
Seeds
Spain Forage Seed Market
Seeds
South America Seed Market