
 Philippines Seed Market | 2026-2036
Philippines Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Seed Market Analytics
Domestic seed multiplication capacity in the Philippines is shifting toward hybrid vegetable and rice parent lines. East-West Seed leverages its integrated breeding stations in Bulacan and Pampanga to shorten variety release cycles. SL Agritech Corporation anchors the hybrid rice segment with proprietary two-line system germplasm. Bayer AG competes through its vegetable seed portfolio, particularly in solanaceous crops for the Bicol processing corridor.
Philippines seed comprises genetically stable or hybridized propagules, typically treated with polymer coatings for moisture retention and pathogen protection, supplied to growers for crop establishment and yield optimization. Hybrid seeds command premium positioning due to heterosis-driven yield gains in rice and tropical vegetables, while open-pollinated varieties retain cost-sensitive share among subsistence operators in Mindanao. Certification stratifies margin pools: quality-certified hybrids generate distributor premiums, whereas organic-certified lines remain nascent with concentrated demand from Negros Occidental sugarcane rotation systems.
The Bureau of Plant Industry enforces seed quality standards under the Seed Industry Development Act, while the Department of Agriculture's National Seed Quality Control Services conducts field inspection and varietal purity testing. Fertilizer and Pesticide Authority regulations on treated seed coatings influence product registration timelines and label claims. Stakeholders must track varietal approval backlogs and irrigation infrastructure commitments in the Mindanao River Basin to calibrate inventory and breeding pipeline investments.
Market Dynamics
The Bureau of Plant Industry's seed certification mandate is compressing variety release timelines and forcing breeders to front-load quality assurance investments before commercial deployment.
Growth Catalysts
- Seed Industry Development Act enforcement:The Bureau of Plant Industry's tightened quality thresholds create competitive moats for certified producers and accelerate replacement of uncertified informal seed channels.
- Hybrid rice adoption in Central Luzon:Irrigation access across the rice and corn belt enables certified seed deployment at scale, concentrating demand pull in this production corridor.
- Vegetable processing corridor expansion:Bicol's solanaceous crop processing infrastructure drives uptake of hybrid tomato and pepper varieties with uniform maturity profiles.
Market Restraints
- Parent line import dependency:Domestic multiplication capacity gaps force reliance on imported hybrid rice and vegetable parent lines, exposing margins to currency volatility and shipping disruptions.
- Smallholder cost sensitivity:Open-pollinated varieties retain dominant share among Mindanao subsistence operators who cannot absorb hybrid seed premiums despite yield penalties.
- Fertilizer and Pesticide Authority coating regulations:Treated seed registration timelines extend commercialization windows and constrain label claims for polymer-coated offerings.
Strategic Opportunities
- Mindanao River Basin irrigation commitments:Department of Agriculture infrastructure investments will expand addressable acreage for certified rice and corn seed in currently rain-fed production zones.
- Organic-certified line development:Negros Occidental sugarcane rotation systems generate concentrated demand for organic-certified vegetable seed, a nascent segment with limited supplier competition.
- Two-line system germplasm licensing:Proprietary hybrid rice breeding platforms offer technology transfer revenue streams for domestic seed companies seeking breeding capability gaps.
Industry Challenges
- Field inspection capacity constraints:National Seed Quality Control Services staffing limitations create varietal approval backlogs that delay inventory planning and pipeline investments.
- Parent line multiplication expertise scarcity:Hybrid seed production requires specialized skills in emasculation and crossing protocols that outpace technical training program outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Seed Market |
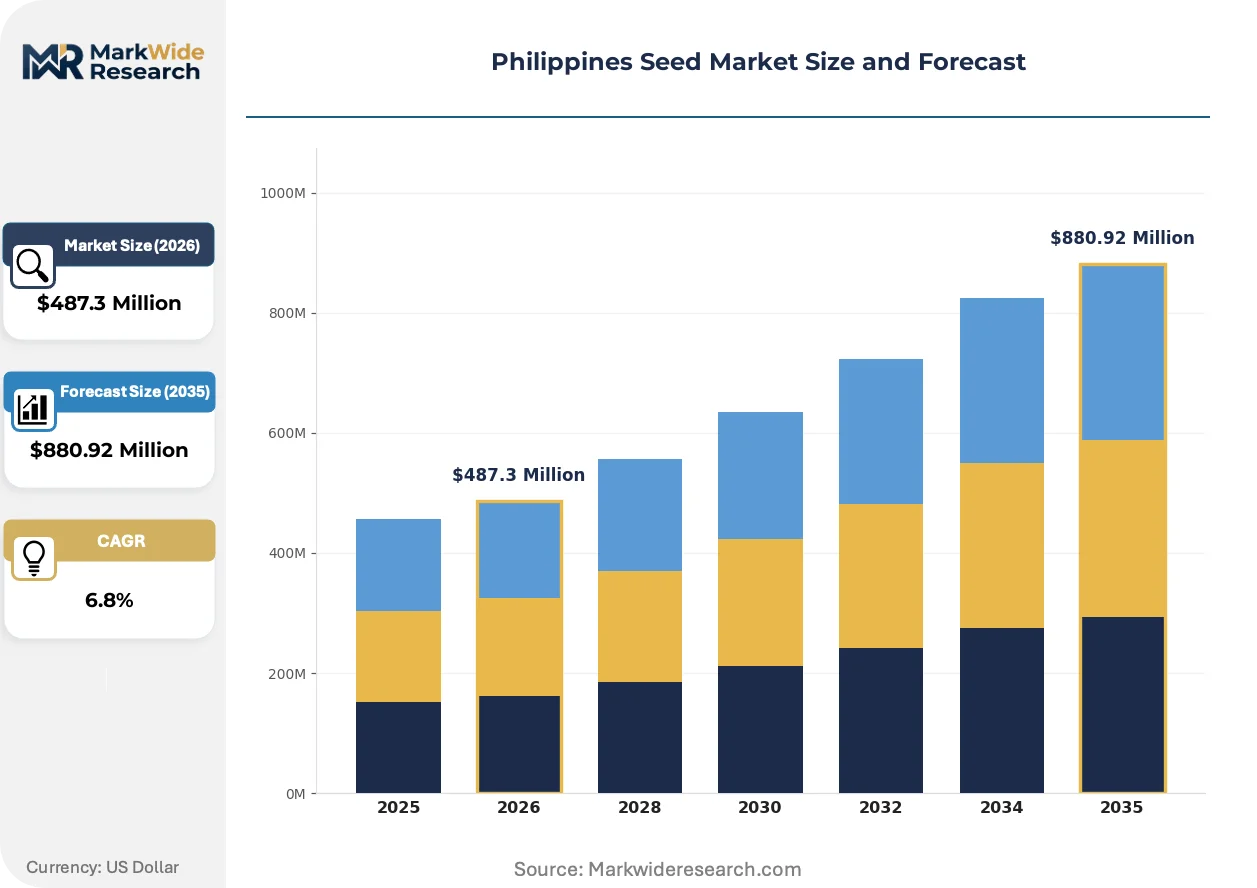
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Seeds, GMO Seeds, Organic Seeds End Use: Agriculture, Horticulture, Forestry, Landscape Distribution Channel: Retail, Wholesale, Online, Direct Sales Certification: Quality Certified, Organic Certified, Non-GMO Verified, Others |
| Companies Covered | East-West Seed, Allied Botanical Corporation, Bayer AG, SL Agritech Corporation, Charoen Pokphand Group, Syngenta Group, Rijk Zwaan Zaadteelt en Zaadhandel BV, Advanta Seeds - UPL, Corteva Agriscience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Seed Market Evolving Landscape
Philippine seed development is pivoting from yield-centric breeding toward trait packages that align with processor specifications and climate resilience requirements.
Gene editing for disease resistance is electrifying breeding pipelines. CRISPR-Cas9 applications target bacterial wilt in solanaceous crops and blast resistance in rice. Large vegetable processors in the Bicol corridor are specifying edited varieties in procurement contracts. This technology is electrifying competitive differentiation between integrated breeders and conventional open-pollinated suppliers.
The Department of Agriculture's National Seed Quality Control Services is expanding field inspection protocols under the Seed Industry Development Act. Varietal purity testing now requires molecular marker verification for hybrid rice certification. Central Luzon distributors are restructuring inventory systems to accommodate extended testing windows and batch-specific traceability requirements.
Contract growing arrangements are displacing spot market seed purchases among commercial vegetable operations. Integrated processors in Ilocos and Bicol are specifying variety, planting density, and input protocols in advance production agreements. This shift is most visible in tomato and pepper segments where uniform harvest timing commands processor premiums over commodity auction prices.
Philippines Seed Market Segmentation
Philippine seed buyers fragment sharply across production scale and risk tolerance. Smallholders prioritize cost containment over yield optimization, while commercial operators absorb premium pricing for genetic uniformity and trait reliability.
Product Type:
Cost tier separates subsistence operators from capitalized commercial farms across the archipelago.
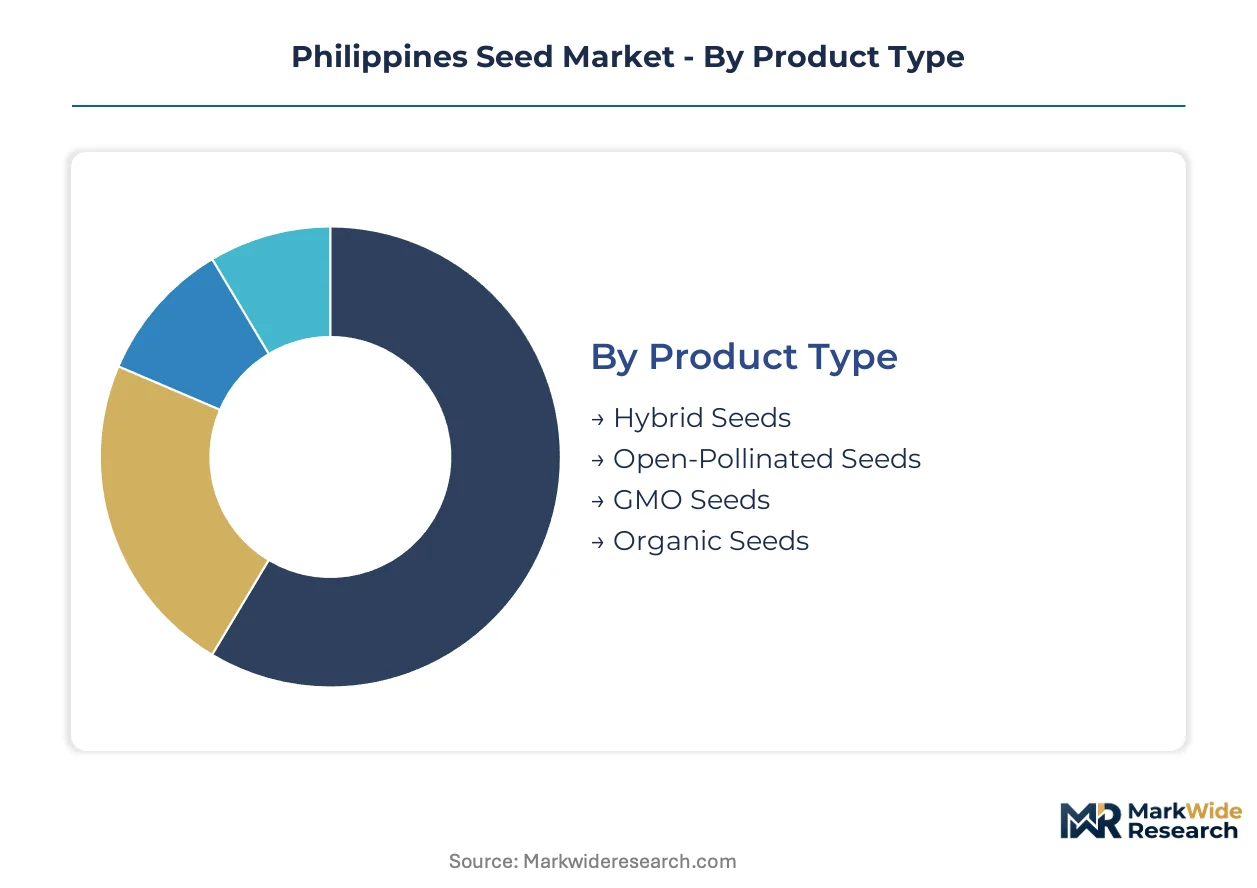
- Hybrid Seeds:Genetically crossed parent lines exploit heterosis for yield gains in rice and solanaceous vegetables. Central Luzon irrigation districts concentrate demand from contract growers supplying Bicol processing facilities. The Bureau of Plant Industry's quality thresholds create distributor premiums for certified lots.
- Open-Pollinated Seeds:Genetically stable varieties propagate through natural pollination without controlled crossing. Mindanao subsistence operators dominate procurement due to lower upfront costs despite yield penalties. Seed saving practices reduce replacement frequency.
- GMO Seeds:Transgenic germplasm with engineered pest resistance traits. Regulatory approval backlogs under the Seed Industry Development Act constrain commercial deployment timelines.
- Organic Seeds:Cultivated without synthetic inputs and certified under national organic standards. Negros Occidental sugarcane rotation systems generate concentrated demand from diversifying growers.
Open-pollinated seeds lead volumes today; hybrid seeds are gaining share fastest.
End Use:
Application intensity varies with commercialization depth and processor integration.
- Agriculture:Field crop establishment for rice, corn, and feed grain production. Central Luzon's rice and corn belt dominates certified seed deployment where irrigation access supports scale.
- Horticulture:Intensive vegetable production for fresh market and processing channels. Ilocos region farmers drive uptake of hybrid tomato and pepper varieties with uniform maturity profiles.
- Forestry:Reforestation and timber plantation establishment. Department of Environment and Natural Resources contracts shape species selection priorities.
- Landscape:Ornamental and turf applications for urban development and estate maintenance. Metro Manila corridor concentrates demand from real estate developers.
Agriculture leads volumes today; horticulture is expanding most quickly.
Distribution Channel:
Customer type and purchase frequency determine channel viability across island geographies.
- Retail:Provincial agro-supply stores serving smallholders with broken lot sizes. Palawan and Mindanao eastern provinces rely heavily on municipal retail networks.
- Wholesale:Volume aggregation for distributor networks and cooperative procurement. Central Luzon warehouse operations supply the rice and corn belt.
- Online:E-commerce platforms with varietal specification databases and traceability documentation. Younger commercial operators in Metro Manila periphery adopt first.
- Direct Sales:Breeder-to-grower contracts with embedded technical advisory. Integrated vegetable processors in Ilocos and Bicol specify varieties in advance production agreements.
Retail leads volumes today; direct sales are climbing the fastest.
Certification:
Margin pools stratify sharply around verification burden and buyer willingness to pay.
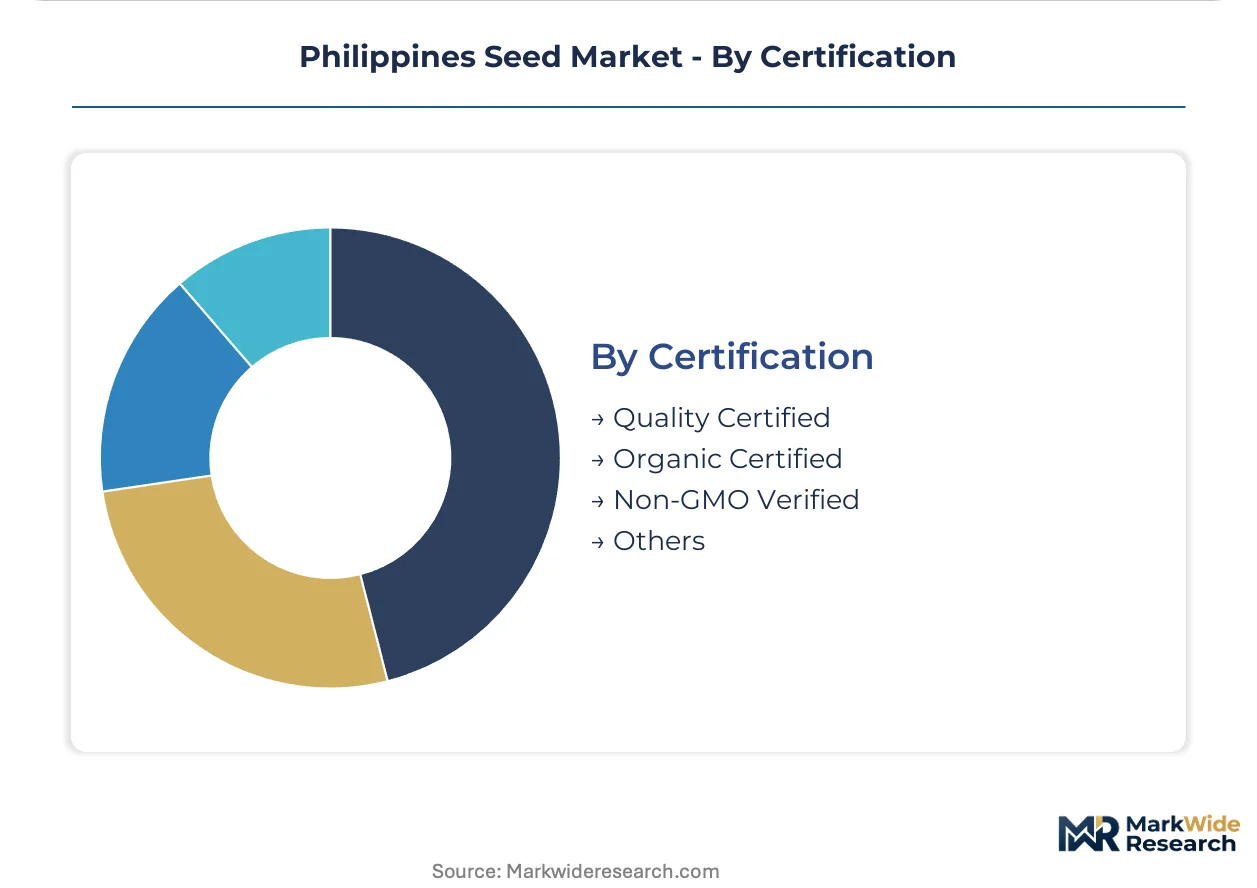
- Quality Certified:Bureau of Plant Industry verification of varietal purity and germination standards. Hybrid rice distributors command premium positioning in Central Luzon certified seed channels.
- Organic Certified:Third-party audit of cultivation practices and input prohibition. Negros Occidental organic sugar rotations generate nascent vegetable seed demand with limited supplier competition.
- Non-GMO Verified:Identity preservation and testing protocols excluding transgenic content. Export-oriented processors specify verification for EU-bound consignments.
- Others:Heirloom designations, participatory breeding certifications, and regional specialty claims. Niche collectors and heritage crop networks sustain minimal volumes.
Quality certified leads volumes today; organic certified shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seed production migrates toward regions where Bureau of Plant Industry certification costs are offset by irrigation infrastructure density and processor procurement scale. The cost-of-compliance gap between certified hybrid channels and informal seed systems shapes geographic deployment patterns across Philippine production zones.
Central Luzon
Irrigation access across the rice and corn belt concentrates certified hybrid seed demand from contract growers. The Department of Agriculture's National Irrigation Administration channels support large-scale deployment of quality-certified rice varieties. Pampanga and Bulacan breeding stations anchor parent line multiplication for vegetable seed producers.
Ilocos Region
Vegetable farmers drive uptake of hybrid tomato and pepper varieties with uniform maturity profiles for fresh market and processing channels. The Bureau of Plant Industry's field inspection protocols govern varietal purity testing for commercial distribution. La Union and Ilocos Norte clusters supply Bicol processing facilities through advance production agreements.
Bicol Region
Solanaceous crop processing infrastructure generates procurement contracts specifying hybrid variety, planting density, and input protocols. The Seed Industry Development Act mandates quality thresholds for seed entering commercial channels. Albay and Camarines Sur processing corridors concentrate demand for disease-resistant germplasm with edited trait packages.
Mindanao
Rain-fed production zones retain dominant open-pollinated variety share among cost-sensitive subsistence operators. Department of Agriculture infrastructure commitments in the Mindanao River Basin will expand addressable acreage for certified seed deployment. Davao del Sur and South Cotabato smallholders practice seed saving that reduces replacement frequency.
Negros Occidental
Sugarcane rotation systems generate concentrated demand for organic-certified vegetable seed from diversifying growers. Third-party audit requirements under national organic standards constrain supplier participation in this nascent segment. Bacolod-area cooperatives specify organic-certified lines for crop diversification programs.
Philippines Seed Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue organic-certified and gene-edited specialty lines. The market structures around integrated breeders with captive parent line capacity, multinational agrochemical conglomerates with vegetable seed portfolios, and domestic hybrid rice specialists with proprietary germplasm. Three archetypes dominate: integrated breeding stations controlling vertical seed production, technology licensors monetizing two-line system platforms, and distributor networks aggregating certified inventory for irrigation-corridor deployment. Competitive moves center on breeding station expansion to shorten variety release cycles and contract growing arrangements that displace spot market purchases.
Within the integrated breeding tier, East-West Seed and SL Agritech Corporation exemplify domestic capacity buildout through Bulacan and Pampanga station networks. Bayer AG occupies a position representing multinational agrochemical seed portfolio deployment. These three anchors illustrate divergent strategic postures: captive parent line multiplication versus licensed germplasm access versus global vegetable trait pipelines.
| Leading Market Players |
|---|
| East-West Seed |
| Allied Botanical Corporation |
| Bayer AG |
| SL Agritech Corporation |
| Charoen Pokphand Group |
| Syngenta Group |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Advanta Seeds - UPL |
| Corteva Agriscience |
| Others |
Value Network & Pricing Analysis
The Bureau of Plant Industry's organic certification mandate gates both qualified supply and premium-tier pricing access, as seed producers must absorb field inspection and molecular verification costs before capturing distributor margins in certified channels.
Pricing Analysis
Distributor margin compression sits at the channel-margin layer, with certified hybrid rice seed commanding three-tier pricing structure across premium, standard, and economy levels based on germination rates and varietal purity grades. Price differentiation hinges on Bureau of Plant Industry certification status and irrigation corridor proximity, with Central Luzon contract growers showing lowest price sensitivity due to processor-backed offtake guarantees. Pricing pressure stems from parent line import dependency exposing peso-denominated margins to currency volatility. Mindanao subsistence operators represent the most price-sensitive segment, perpetuating open-pollinated variety dominance despite yield penalties.
Supply Chain Analysis
Single-source vulnerability sits with imported hybrid rice and vegetable parent lines from China, Thailand, and India, exposing domestic multiplication networks to shipping disruptions and phytosanitary holdups. Raw material dependencies center on polymer coating chemistries, cold storage infrastructure, and specialized emasculation labor pools. Supply chain risk concentrates in regulatory restriction exposure, as Fertilizer and Pesticide Authority treated seed registration timelines extend commercialization windows unpredictably. Distribution runs through Bureau of Plant Industry-certified warehouse networks in Central Luzon, with direct breeder-to-processor contracts displacing spot market purchases in Ilocos and Bicol vegetable corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines Seed Market functions as a stable compounder, with the Seed Industry Development Act's quality enforcement creating durable competitive moats that protect certified producers from informal channel erosion.
For Market Incumbents: Hedge against parent line import dependency by deepening backward integration into captive breeding station capacity across Bulacan and Pampanga. Lock in irrigation corridor access through exclusive distribution agreements with National Irrigation Administration-supported cooperatives in Central Luzon, defending against emerging entrants with licensed two-line system germplasm.
For New Entrants and Emerging Players: The price-point gap between premium certified hybrids and economy open-pollinated varieties in Mindanao rain-fed zones offers white-space penetration. Target organic-certified vegetable seed supply to Negros Occidental sugarcane rotation systems, where third-party audit requirements constrain incumbent participation. Pursue gene-edited trait licensing from integrated breeders to bypass parent line multiplication expertise scarcity.
For Investors and Strategic Acquirers: Valuations sit cheapest among open-pollinated variety distributors serving Mindanao subsistence operators, where consolidation-ready networks await certified channel conversion. Long-term viability over a five-to-ten-year window favors integrated breeding stations with captive parent line capacity and Bureau of Plant Industry certification infrastructure. Watch Mindanao River Basin irrigation commitment disbursement velocity as the inflection signal for certified seed addressable acreage expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Parent Line Multiplication Capacity Expansion | Bulacan and Pampanga breeding stations shorten variety release cycles for hybrid vegetable producers. |
| Organic Certification Program Investment | Third-party audit infrastructure captures Negros Occidental sugarcane rotation system demand. |
| Direct Contract Growing Arrangements | Bicol processing facilities specify varieties, planting density, and input protocols in advance production agreements. |
| Gene-Edited Trait Licensing Agreement | CRISPR-Cas9 bacterial wilt resistance differentiates solanaceous crop offerings for processor procurement. |
| Irrigation Corridor Distribution Partnership | National Irrigation Administration channel access concentrates certified rice seed deployment in Central Luzon. |
Research Methodology
Direct dialogue with seed company breeding directors, Bureau of Plant Industry certification officers, National Seed Quality Control Services field inspectors, Central Luzon cooperative procurement managers, and Ilocos vegetable processor agronomists grounded qualitative findings. Secondary validation drew from Seed Industry Development Act regulatory filings, Department of Agriculture irrigation infrastructure commitment disclosures, Fertilizer and Pesticide Authority registration databases, and Bureau of Plant Industry varietal approval backlogs. Bottom-up acreage and replacement rate estimates triangulated against top-down seed industry revenue aggregates.
Market size and growth trajectory outputs across the analysis window reflect segment-level modeling of hybrid versus open-pollinated adoption curves, certification tier penetration, and irrigation corridor expansion timing. Segmentation dimensions span product type, end use, distribution channel, and certification status, with regional production cluster density as an industry-specific overlay. CAGRs derive from compounding annual replacement frequency shifts and certified channel share migration, informed by parent line import cost trajectories and molecular marker verification adoption in varietal purity testing.
The model assumes a particular technology adoption path; alternative pathways for gene-edited trait commercialization would alter the outlook if regulatory approval timelines compress or processor procurement specifications shift. Forecasts embed assumptions around Bureau of Plant Industry field inspection capacity expansion and Mindanao River Basin irrigation disbursement schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Arnica Montana Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Chia Seeds Market
Seeds
Chamomile Seeds Market
Seeds
Native Grass Seeds Market
Seeds
Wax Gourd Seed Market
Seeds
Europe Cannabis Seeds Market
Seeds
South Africa Forage Seed Market
Seeds
Europe Quinoa Seed Market
Seeds
Genetically Modified Seeds Market
Seeds
Global Sorghum Seed Market
Seeds
Global Sports Turf Seed Market
Seeds
Pumpkin Seeds Market
Seeds
United States Forage Seed Market
Seeds
South America Forage Seed Market
Seeds
Cucumber Seeds Market