
 India Seed Market | 2026-2036
India Seed Market Size, Share, and Industry Trends Forecast 2026-2036
India Seed Market Outlook
The FSSAI's quality benchmarks for agricultural inputs is hardening compliance requirements across the seed value chain. Mahyco leverages its deep R&D infrastructure to sustain dominance in cotton and vegetable hybrids. Kaveri Seeds anchors its position through specialized corn and rice germplasm portfolios. Syngenta Group competes on trait technology leadership while extending its dealer network into tier-two districts.
India seeds comprise genetically improved or preserved reproductive units of agricultural crops, typically treated with polymer coatings, fungicides, or micronutrient fortifiers to achieve specified germination rates and field establishment. Their primary commercial purpose is to deliver yield stability, pest resistance, and climate adaptability to farmers operating across diverse agro-ecological zones. Hybrid seeds command the dominant value share due to proprietary trait control and recurring purchase cycles, while organic seeds represent a faster-growing but smaller margin pool as certified farming expands. Open-pollinated varieties retain substantial volume in food grains where farmer-saved seed practices persist, constraining branded penetration in certain crop categories.
BIS certification norms and the CEA's seed quality directives shape product standards and market access for domestic and imported germplasm alike. The PLI scheme for agriculture inputs redirects capital toward domestic breeding programs and processing infrastructure. State seed corporations and cooperative societies function as parallel regulatory gatekeepers through their certification and distribution roles. Stakeholders must monitor how trait approval timelines and royalty structure negotiations between breeders and farmer groups recalibrate competitive economics across the sector.
Market Dynamics
Proprietary trait control through hybrid germplasm is concentrating value capture among integrated breeders while marginalizing open-pollinated variety suppliers across India's cotton and vegetable belts.
Growth Catalysts
- PLI scheme for agriculture inputs:Capital subsidies redirect domestic manufacturing toward breeding infrastructure and polymer coating facilities, reducing import dependency for critical germplasm inputs.
- Maharashtra cotton belt demand concentration:Smallholder clusters in Vidarbha and Marathwada accelerate hybrid seed turnover due to bollworm pressure and shorter replacement cycles.
- Gene editing protocols:CRISPR-based trait development compresses varietal release timelines from conventional backcrossing programs, enabling faster climate adaptation.
Market Restraints
- Phosphorus and micronutrient cost volatility:Seed treatment input prices fluctuate with global fertilizer markets, compressing margin buffers for mid-tier processors.
- Andhra Pradesh and Telangana distribution chokepoints:State seed corporation procurement monopolies in these rice-dominant regions limit direct market access for private breeders.
- Farmer-saved seed persistence:Open-pollinated rice and wheat varieties sustain non-commercial circulation, constraining branded penetration in food grain categories.
Strategic Opportunities
- Gujarat groundnut zones:Underpenetrated districts in Saurashtra present white space for certified seed substitution of farm-retained stock.
- BIS certification harmonization:Streamlined quality benchmarks create regulatory tailwind for integrated players with captive testing infrastructure.
- Drone-enabled pollination:UAV-based male line distribution in hybrid seed production fields reduces labor dependency and isolation distance requirements.
Industry Challenges
- Trait approval timeline uncertainty:CEA seed quality directives and environmental release committees impose unpredictable review durations, freezing R&D capital for 18-36 month windows.
- Polymer coating equipment capex:Automated film-coating lines for micronutrient and fungicide application require capital commitments that exclude regional formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Seed Market |
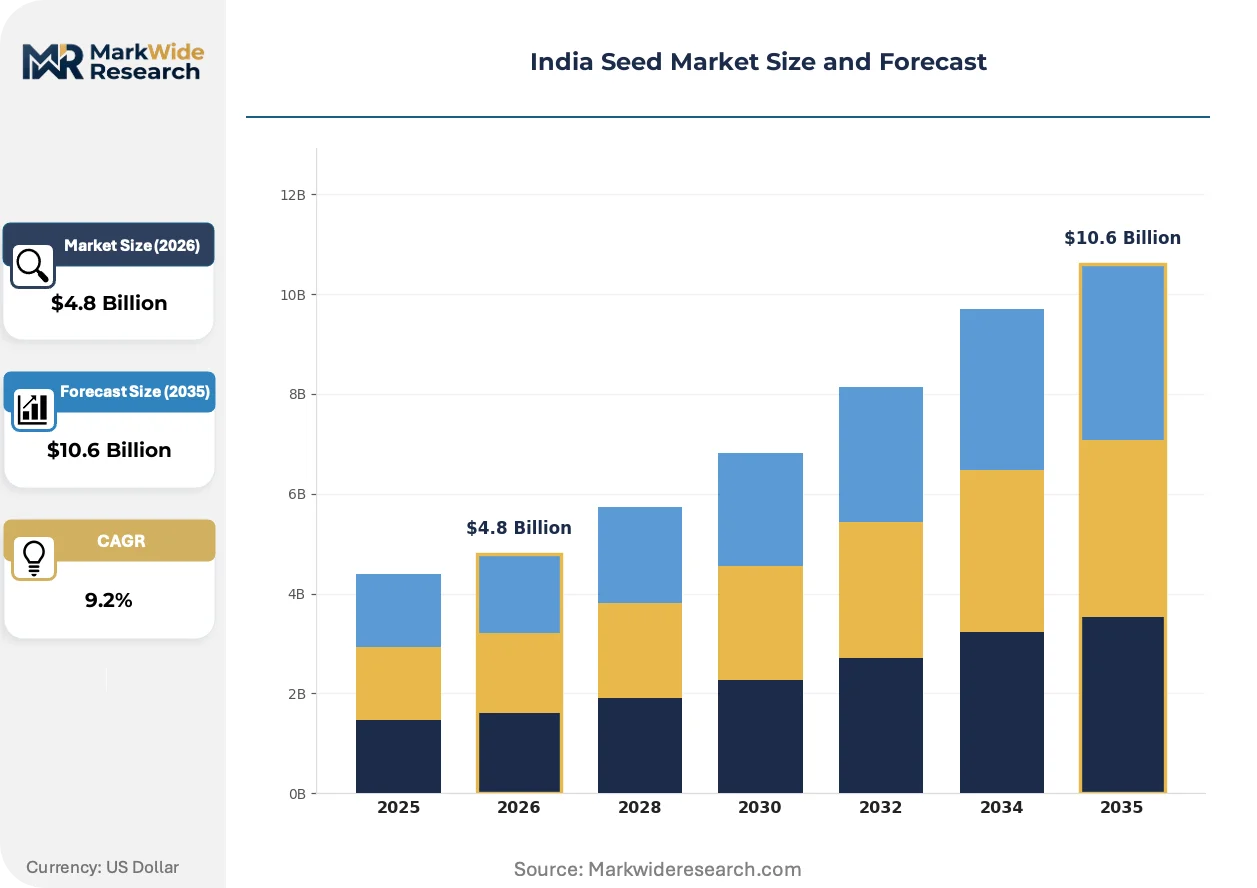
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Seeds, GM Seeds, Organic Seeds End Use: Crops, Vegetables, Fruits, Turf Distribution Channel: Direct Sales, Retail, Online, Cooperative Societies Packaging Type: Bulk Packaging, Retail Packaging, Custom Packaging, Eco-Friendly Packaging |
| Companies Covered | Mahyco, Syngenta Group, Kaveri Seeds, Nuziveedu Seeds, VNR Seeds Private Limited, Bayer AG, UPL Limited, Rasi Seeds Private Limited, JK Agri Genetics Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Seed Market Strategic Shifts
Digital phenotyping platforms and molecular marker-assisted selection are compressing varietal development cycles while regulatory tightening around genetic resource access reshapes competitive boundaries.
Marker-assisted breeding is overtaking conventional pedigree selection in cotton and corn programs. Leading breeders deploy high-throughput genotyping to stack multiple stress-tolerance traits within single-cycle improvements. This acceleration is compressing the effective patent window for proprietary hybrids and forcing faster portfolio refresh rates.
FSSAI quality benchmarks for agricultural inputs are hardening compliance requirements across the seed value chain. Processors must now document treatment chemical residues and germination uniformity to stricter tolerances. Small-scale coating operators in Uttar Pradesh and Madhya Pradesh face consolidation pressure from testing cost burdens.
Farmer procurement patterns are fragmenting away from village-level dealer monopolies toward cooperative aggregation models. Input societies in Karnataka and Haryana now pool germplasm demand for direct breeder contracts. This channel shift compresses distributor margins while rewarding breeders with captive supply relationships.
India Seed Market Segmentation
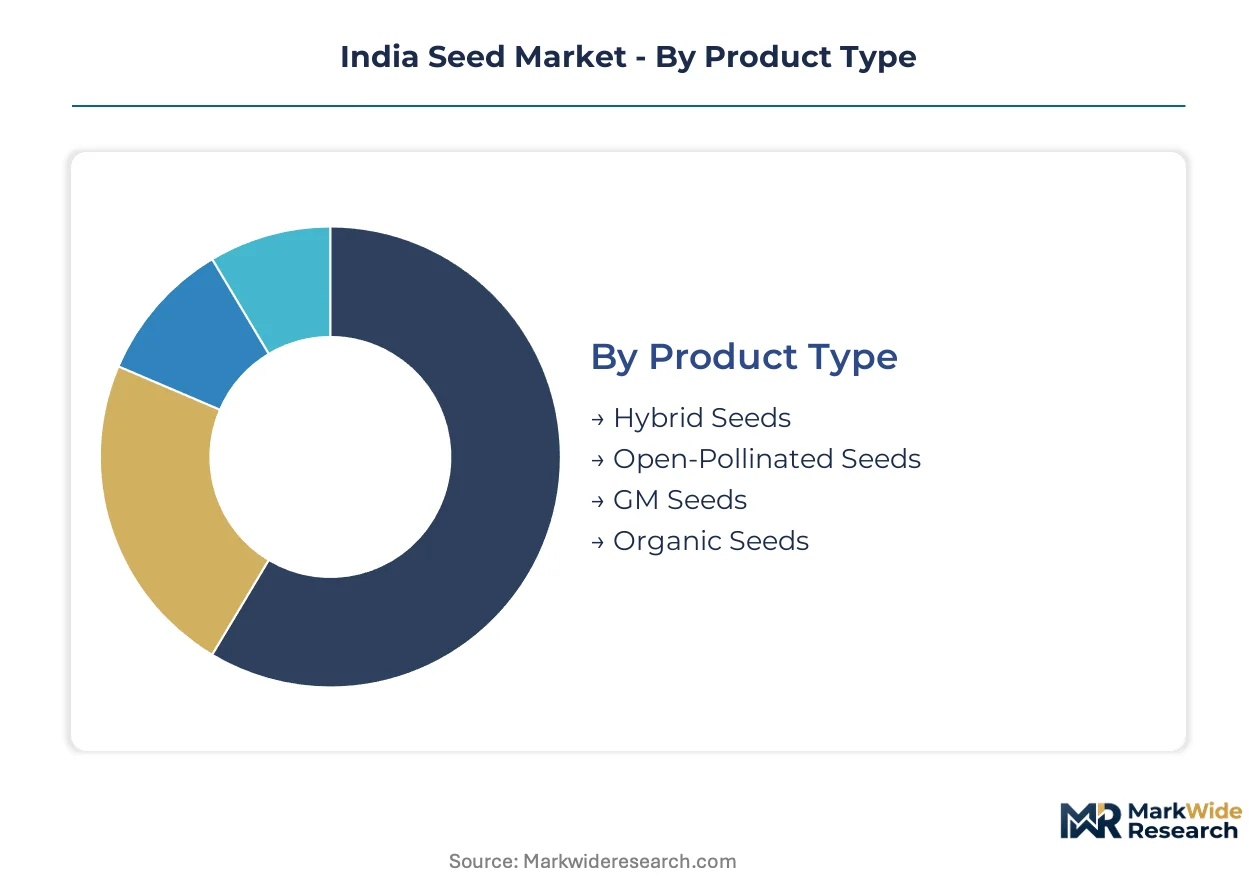
Segmentation reveals how proprietary germplasm control, farmer procurement patterns, and regulatory compliance reshape competitive boundaries across India's seed value chain. Breeders calibrate portfolio investments against replacement-cycle intensity and state-specific distribution access.
Product Type:
Upgrade cycles vary dramatically by genetic control mechanism, with proprietary hybrids forcing annual repurchase while open-pollinated varieties sustain multi-season farm retention.
- Hybrid Seeds:Cross-pollinated varieties incorporating proprietary male-sterile lines deliver yield stability and pest resistance through controlled trait expression. Demand concentrates in Maharashtra's cotton belt and Gujarat's vegetable zones where bollworm pressure and export-grade quality requirements accelerate replacement cycles.
- Open-Pollinated Seeds:Naturally pollinated varieties retain genetic diversity across generations, enabling farmer-saved seed practices. Penetration persists in Andhra Pradesh and Telangana rice belts where state procurement monopolies and food grain self-sufficiency norms limit branded hybrid conversion.
- GM Seeds:Transgenic varieties incorporating Bt or HT trait stacks require CEA environmental release approvals and BIS certification.
- Organic Seeds:Certified non-GMO germplasm meets FSSAI quality benchmarks for residue-free agricultural inputs.
Volume placements concentrate in Hybrid Seeds; the faster expansion belongs to Organic Seeds.
End Use:
Application-specific trait requirements drive divergent R&D priorities, with vegetable and fruit segments commanding premium pricing against commodity crop thin margins.
- Crops:Cotton, corn, rice, and wheat germplasm dominate unit volumes through smallholder coverage. Adoption clusters in Vidarbha's cotton zones and Haryana's corn belts where integrated processors bundle seed with micronutrient coatings.
- Vegetables:Tomato, chili, and okra hybrids demand precise climate adaptability and shelf-life extension traits. Karnataka's input societies and Maharashtra's contract farming clusters generate concentrated procurement for export-grade varieties.
- Fruits:Papaya and melon seeds require extended germination viability and disease resistance stacking.
- Turf:Lawn and ornamental grass varieties serve urban landscaping and golf course maintenance.
Revenue concentration sits with Crops; steepest expansion trajectory characterizes Vegetables.
Distribution Channel:
Channel economics shift as cooperative aggregation erodes traditional dealer margins and digital platforms penetrate tier-two districts.
- Direct Sales:Breeder-to-farmer contracts bypass distributor markups through input society aggregation. Karnataka and Haryana cooperative societies pool germplasm demand for volume-based pricing.
- Retail:Village-level dealer networks maintain last-mile access in Uttar Pradesh and Madhya Pradesh smallholder clusters.
- Online:E-commerce platforms extend reach into underserved districts with digitized germination certificates and treatment documentation.
- Cooperative Societies:State-backed procurement channels function as regulatory gatekeepers in rice-dominant regions.
Transaction volume flows through Retail; channel share gains most rapidly accrue to Cooperative Societies.
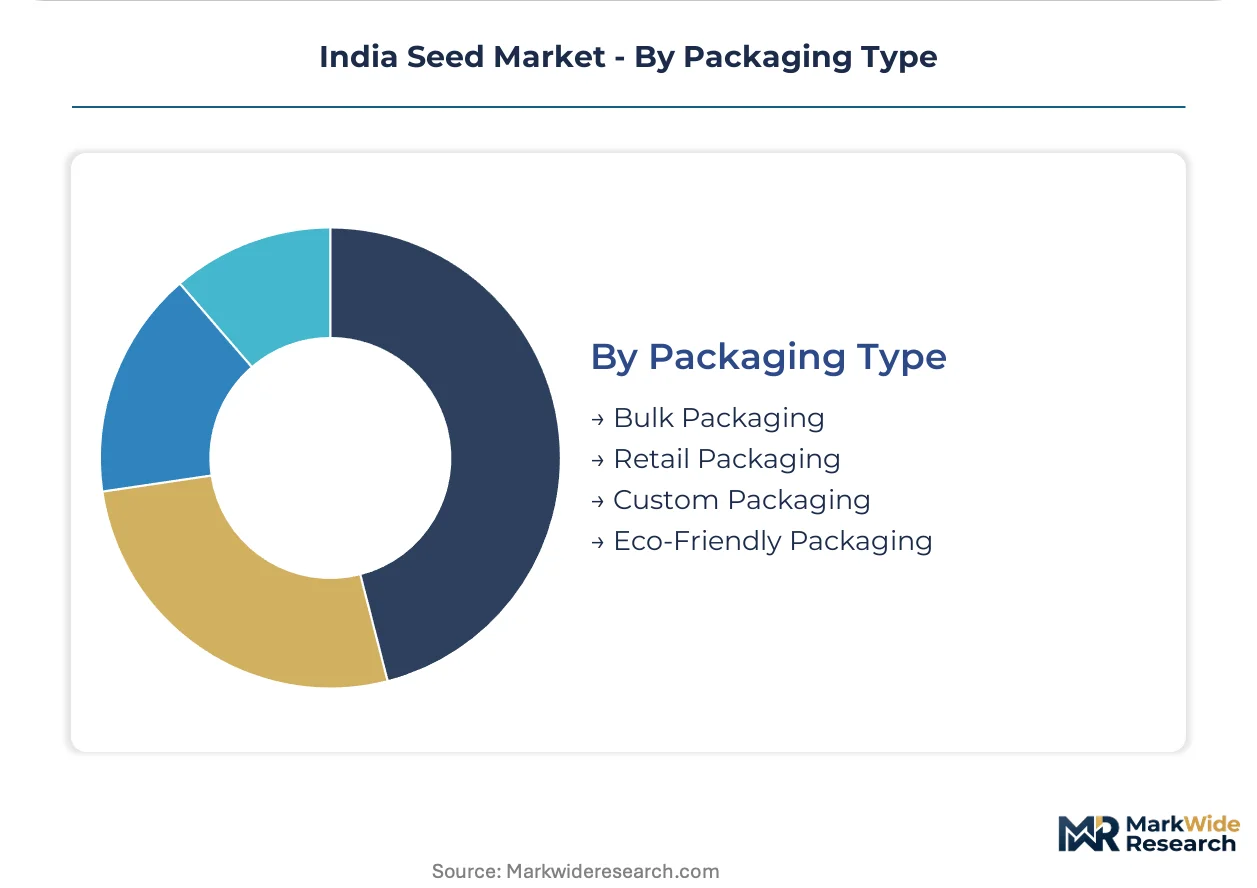
Packaging Type:
Packaging specifications balance treatment chemical stability, traceability requirements, and sustainability pressures across divergent customer scales.
- Bulk Packaging:50kg woven sacks serve state seed corporations and large input societies with standardized germplasm lots. Procurement concentrates in Punjab and Haryana where cooperative aggregation generates scale-appropriate order sizes.
- Retail Packaging:Laminated pouches with moisture barriers and QR-coded traceability dominate dealer-channel sales. Penetration is deepest in Maharashtra and Gujarat where smallholder plot sizes require fractional unit purchases.
- Custom Packaging:Private-label configurations accommodate corporate farming and export-oriented contract growers.
- Eco-Friendly Packaging:Biodegradable films and reduced-plastic formats respond to sustainability procurement criteria.
Shipment volumes cluster in Bulk Packaging; the segment climbing fastest is Eco-Friendly Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nagpur anchors hybrid cotton seed distribution across the Vidarbha plateau, with dealer networks radiating into Marathwada's smallholder clusters. State seed corporations and private breeders compete for shelf space through differentiated trait stacks and micronutrient coating formulations.
Maharashtra
Vidarbha's cotton belt generates concentrated demand for bollworm-resistant hybrids with compressed replacement cycles. The state's seed certification framework under the Maharashtra State Seeds Corporation channels procurement through regulated distribution nodes. Jalna and Aurangabad host processing facilities where polymer coating lines treat germplasm for Marathwada's rainfed plots.
Gujarat
Saurashtra's groundnut zones present certified seed substitution opportunities against farm-retained stock persistence. BIS certification norms govern quality benchmarks for domestic and imported germplasm entering Gujarat's processing infrastructure. Rajkot and Junagadh cluster seed treatment facilities serving export-oriented contract farming networks.
Karnataka
Input societies in the state's corn and vegetable belts aggregate germplasm demand for direct breeder contracts. The Karnataka State Seeds Corporation functions as a parallel regulatory gatekeeper through certification and distribution roles. Hubli-Dharwad and Mysore concentrate hybrid tomato and chili seed processing for southern Indian markets.
Haryana
Cooperative societies pool demand for corn and rice germplasm across the Indo-Gangetic plains. State procurement monopolies in rice-dominant districts limit direct market access for private breeders. Karnal and Hisar anchor breeding infrastructure where marker-assisted selection programs compress varietal development timelines.
Andhra Pradesh
State seed corporation procurement channels constrain branded penetration in rice belts where farmer-saved practices persist. The Andhra Pradesh State Seed Development Corporation directs distribution through cooperative networks. Guntur and West Godavari host processing facilities treating hybrid chili and cotton seed for coastal agro-climatic zones.
India Seed Market Competitive Environment
Premium-margin players sit above commodity-margin players across trait control and germplasm ownership dimensions. Integrated breeders with captive R&D infrastructure capture disproportionate value in cotton and vegetable hybrids. Three archetypes dominate: multinational trait technology leaders, domestic hybrid specialists with regional germplasm banks, and state-backed seed corporations with distribution monopolies. Competitive moves center on gene editing protocol licensing and automated coating line capacity expansion.
Among domestic hybrid specialists, Mahyco and Kaveri Seeds occupy positions reflecting divergent crop focus strategies. Mahyco exemplifies the integrated breeder archetype through sustained dominance in cotton and vegetable germplasm. Kaveri Seeds anchors the specialized corn and rice portfolio segment. Syngenta Group represents multinational trait technology leadership within India's regulatory framework. These three entities illustrate how proprietary male-sterile line control and dealer network extension into tier-two districts differentiate competitive positioning.
| Leading Market Players |
|---|
| Mahyco |
| Syngenta Group |
| Kaveri Seeds |
| Nuziveedu Seeds |
| VNR Seeds Private Limited |
| Bayer AG |
| UPL Limited |
| Rasi Seeds Private Limited |
| JK Agri Genetics Limited |
| Others |
Value Chain & Pricing Dynamics
Polymer coating chemical costs cascade from global fertilizer markets through Maharashtra's processing facilities to tier-two dealer markups, compressing margin buffers for mid-tier formulators while rewarding integrated breeders with captive micronutrient sourcing.
Pricing Analysis
Yield-per-hectare guarantees anchor value-based pricing for proprietary cotton and vegetable hybrids in Vidarbha and Saurashtra. Three-tier pricing structure across premium, standard, and economy levels reflects germplasm trait complexity, BIS certification grade, and bundled after-sales agronomic support. Pricing pressure stems from phosphorus and micronutrient input volatility, squeezing processors without backward integration into coating chemical supply. Smallholder clusters in Uttar Pradesh and Madhya Pradesh exhibit highest price sensitivity, while export-oriented contract growers in Gujarat absorb premium tiers for traceability-assured germplasm.
Supply Chain Analysis
Single-source vulnerability sits with male-sterile line germplasm concentrated among three domestic breeders and two multinational technology licensors. Critical inputs draw from China for polymer coating chemicals, Germany for automated film-coating equipment, and domestic sources for micronutrient fortifiers. Tariff exposure on imported trait technologies and breeding equipment amplifies cost unpredictability. Distribution runs through state seed corporation procurement monopolies in Andhra Pradesh and Telangana, parallel dealer networks in Maharashtra and Gujarat, and emerging cooperative aggregation channels in Karnataka and Haryana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene editing protocols displace conventional backcrossing programs, compressing varietal development timelines and recalibrating R&D capital efficiency thresholds across the competitive landscape.
For Market Incumbents: Deepen captive breeding infrastructure investments in Haryana and Karnataka to defend against CRISPR-enabled challengers eroding trait control premiums. Accelerate automated polymer coating line deployment to offset labor cost inflation and micronutrient price volatility. Secure exclusive male-sterile line licensing agreements before regulatory harmonization opens germplasm access. For New Entrants and Emerging Players: Enter via Saurashtra's underpenetrated groundnut zones where farm-retained seed persistence creates certified substitution white space. Target direct-to-farmer cooperative contracts in Karnataka's input societies, bypassing dealer margin extraction. Lead with drone-enabled pollination cost advantages in hybrid seed production to offset scale disadvantages against integrated incumbents. For Investors and Strategic Acquirers: CEA trait approval timeline acceleration is the leading indicator that regulatory risk premiums are compressing, unlocking value capture for gene editing specialists. Position for five-to-ten year holding periods around breeders with captive germplasm banks and tier-two distribution network density. Monitor BIS certification harmonization progress as the signal for consolidation timing in fragmented coating and processing tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Editing Protocol Licensing | CRISPR trait stacks compress development cycles for climate-adaptive germplasm releases. |
| Automated Coating Line Expansion | Polymer film-coating capacity in Maharashtra and Gujarat reduces import dependency for treatment inputs. |
| Cooperative Society Direct Contracts | Karnataka and Haryana input society aggregation bypasses dealer margin extraction for volume pricing. |
| Drone-Enabled Pollination Deployment | UAV male line distribution cuts labor costs and isolation distance requirements in hybrid seed fields. |
| BIS Certification Infrastructure Investment | Captive testing facilities capture regulatory tailwind from harmonized quality benchmarks. |
Study Parameters
Company annual reports, BIS certification registries, and CEA environmental release filings formed the secondary backbone, cross-referenced with primary interviews across breeding program directors, state seed corporation procurement officers, polymer coating equipment suppliers, and cooperative society aggregation managers. Bottom-up germplasm volume estimates from state-level dealer network mapping were triangulated against top-down seed industry revenue disclosures.
Bottom-up modeling anchored forecasts, with top-down macro validation across the projection horizon. Segmentation dimensions included genetic control mechanism, crop category, distribution channel type, and state-specific regulatory cluster. CAGRs were derived from replacement cycle intensity curves and hybrid adoption penetration slopes. Industry-specific inputs incorporated PLI scheme capital subsidy disbursement trajectories and FSSAI quality benchmark implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under trait approval timeline delays, phosphorus price spike scenarios, and state seed corporation procurement policy reversals. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Hemp Seeds Market
Seeds
Agricultural Seeder Market
Seeds
Nepal Seeds Market
Seeds
South Africa Forage Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
United States Forage Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Organic Sesame Seed Market
Seeds
Philippines Seed Market
Seeds
Guar Market
Seeds
Global Maize Seed Market
Seeds
North America Vegetable Seed Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Caraway Seeds Market
Seeds
Vietnam Seed Market
Seeds
E. Angustifolium Market