
 Agriculture Container and Tank Cleaning Market | 2026-2036
Agriculture Container and Tank Cleaning Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Container and Tank Cleaning Market Analytics
EPA's revised pesticide container regulations is pivoting the competitive landscape toward capital-intensive cleaning infrastructure. Lechler GmbH leverages its nozzle-technology heritage to dominate high-pressure wash systems for liquid tanks. Ecolab sustains its position through integrated chemical-cleaning programs that bundle formulation with application equipment hygiene. Clean Harbors anchors North American demand with its hazardous-waste handling permits and mobile tank-cleaning fleets.
Agriculture container and tank cleaning encompasses the mechanical and chemical remediation of vessels used for pesticide, fertilizer, and feed storage, typically requiring pressure thresholds exceeding 150 bar and pH-neutralizing rinse cycles to eliminate bioaccumulation risks. The primary purpose centers on preventing cross-contamination between crop chemistries and ensuring compliance with residue tolerance thresholds for food-chain entry. Liquid tanks command the largest product-type share due to their ubiquity in precision-application fleets, while chemical-cleaning methods capture expanding margin pools as formulation complexity rises. Spray equipment represents the fastest-growing cleaning-method segment because nozzle clogging from suspended polymers drives more frequent service intervals.
EPA's Container Containment Regulations and OSHA's Hazard Communication Standard jointly elevate compliance costs for on-site cleaning operations, pushing smaller farms toward third-party service providers. The EU's Sustainable Use of Pesticides Directive and REACH chemical-registration requirements create parallel compliance burdens for exporters serving European food-processing supply chains. Stakeholders must weigh captive cleaning investments against outsourced service contracts as regulatory stringency diverges across their customer geographies.
Market Dynamics
EPA's Worker Protection Standard revisions are compressing service intervals and forcing capital deployment into automated wash systems across precision-agriculture fleets.
Growth Catalysts
- Regulatory stringency:The EPA's Container Containment Regulations mandate residue thresholds that exceed manual cleaning capabilities, pushing operations toward high-pressure infrastructure investments.
- Brazil's Mato Grosso soybean belt:Co-op consolidation at scale creates centralized demand for tank-cleaning services that individual farms cannot replicate economically.
- Spray equipment polymerization:Suspended polymers in modern crop-protection formulations clog nozzles faster, shortening cleaning cycles and expanding addressable service volume.
Market Restraints
- Stainless steel supply concentration:High-pressure wash system fabrication depends on specialty-grade steel inputs subject to volatile pricing and geographic supply bottlenecks.
- REACH compliance friction:EU chemical-registration requirements create parallel documentation burdens for exporters serving European food-processing supply chains, elevating fixed costs.
- On-site cleaning substitution:Third-party mobile services displace captive infrastructure investments among mid-scale operations, compressing equipment manufacturer margins.
Strategic Opportunities
- California specialty crop expansion:Tightening residue limits in tree-nut and vineyard operations create demand for pH-neutralizing rinse-cycle technology that smaller service providers cannot supply.
- IoT-enabled wash monitoring:Sensor integration with pressure-threshold logging creates compliance documentation trails that differentiate premium service tiers from commodity cleaning.
- OSHA Hazard Communication Standard alignment:Training and certification programs bundled with equipment sales capture recurring revenue streams adjacent to hardware margins.
Industry Challenges
- High-pressure system technician scarcity:Specialized mechanical and chemical-handling skills required for 150+ bar system maintenance outpace vocational training program output.
- Legacy tank retrofit complexity:Older liquid storage vessels lack structural reinforcement for automated wash-arm installation, forcing costly vessel replacement versus upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Container and Tank Cleaning Market |
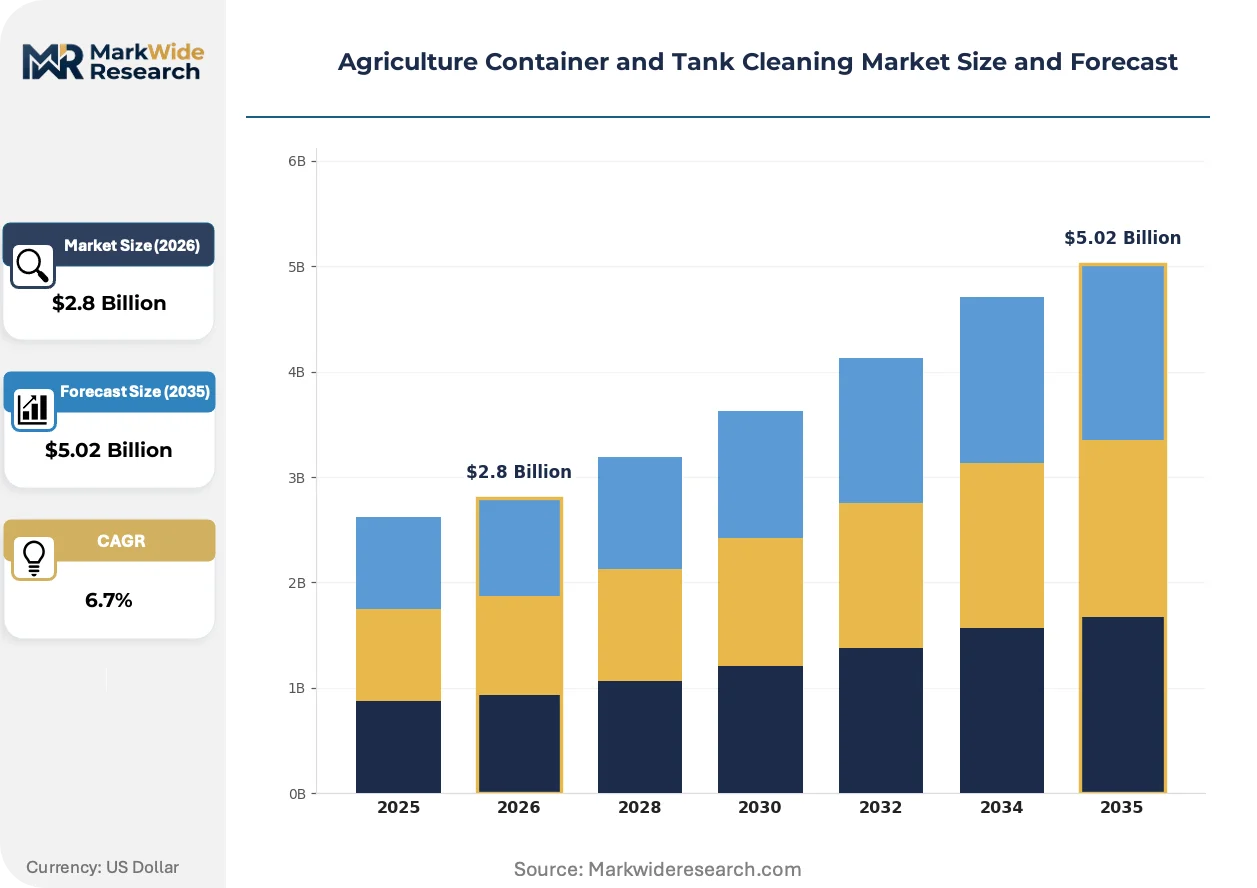
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Tanks, Bulk Containers, Spray Equipment, Drums Cleaning Method: High-Pressure Washing, Chemical Cleaning, Steam Cleaning, Manual Cleaning End User: Farms, Agricultural Cooperatives, Food Processing Plants, Chemical Manufacturers Service Type: On-Site Cleaning, Off-Site Cleaning, Equipment Rental, Consultation Services |
| Companies Covered | Lechler GmbH, Loveland Products, Alfred Kärcher GmbH, Clean Harbors, Veolia Environmental Services, Tradebe Refinery Services, Evergreen Industrial Services, SWS Environmental Services, Ecolab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Container and Tank Cleaning Market Evolving Landscape
Automation of cleaning protocols is compressing labor dependency while sensor integration creates audit-ready compliance trails that manual processes cannot replicate.
Robotic wash-arm systems are automating interior surface coverage for liquid fertilizer tanks, eliminating confined-space entry requirements that slow turnaround times. Large co-operative operations in Brazil and the US Midwest are deploying these systems at fleet scale to maintain spray schedules during narrow application windows. The technology is automating documentation of pressure and dwell-time parameters that regulators now require for residue-verification protocols.
REACH chemical-registration requirements are tightening documentation burdens for cleaning-agent formulations used on equipment serving EU export supply chains. Formulators must now submit toxicity dossiers for rinse-water discharge that previously faced minimal scrutiny. Specialty crop exporters in California and Florida are responding by specifying third-party-certified cleaning programs that bundle chemical selection with equipment hygiene verification.
Service-contract unbundling is separating equipment cleaning from chemical supply relationships that historically locked buyers into single-vendor dependencies. Independent tank-cleaning operators in agricultural clusters are capturing share by offering multi-brand compatibility and transparent per-wash pricing. This pattern is most visible in Florida's citrus belt, where grower co-ops negotiate spot contracts based on residue-test outcomes rather than annual chemical volume commitments.
Agriculture Container and Tank Cleaning Market Segmentation
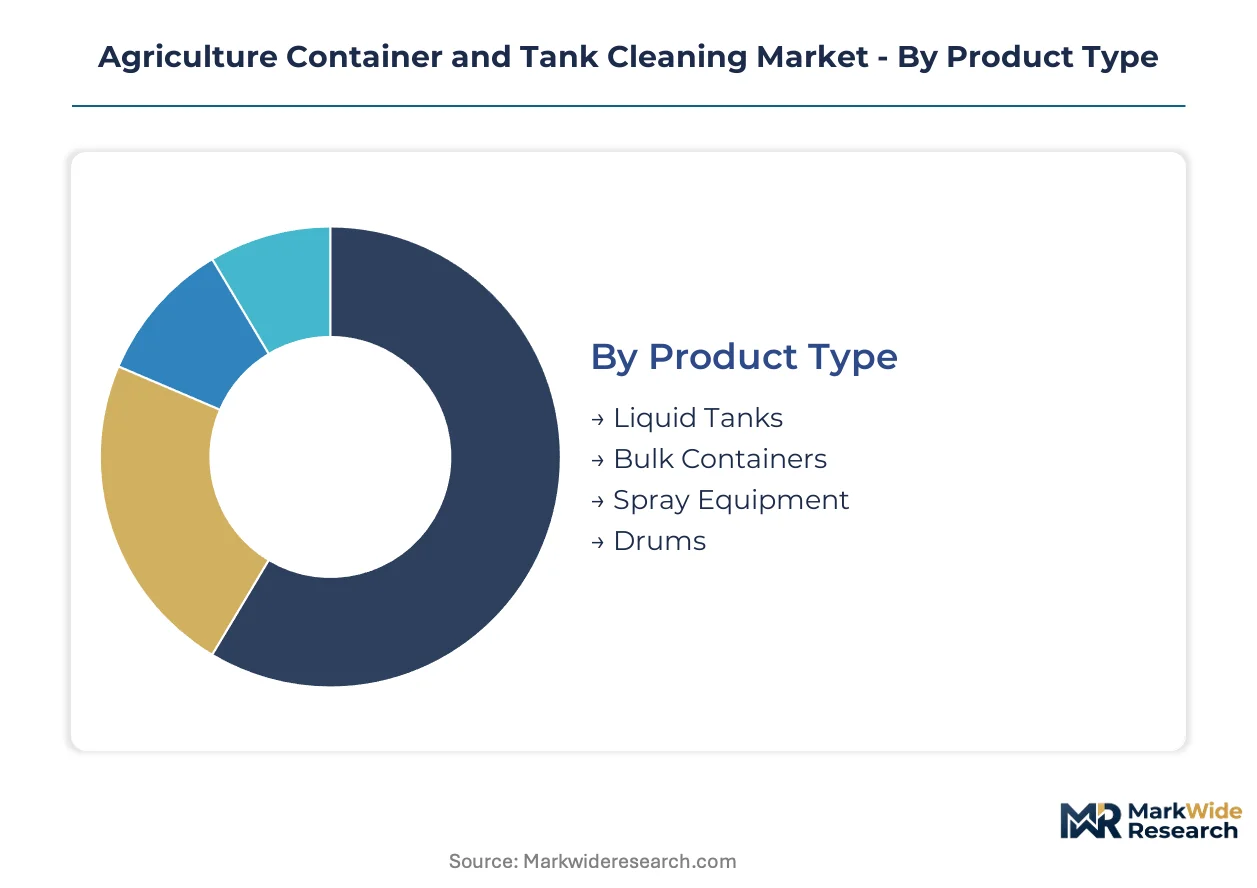
Cleaning infrastructure investment decisions pivot on vessel geometry, residue chemistry, and operational scale. Each segmentation dimension reveals distinct margin structures and compliance burdens that reshape vendor positioning across precision-agriculture supply chains.
Product Type:
Supply concentration in high-pressure system fabrication favors segments requiring 150+ bar wash capability and automated dwell-time documentation.
- Liquid Tanks:Horizontal and vertical vessels for pesticide, fertilizer, and feed storage dominate fleet-scale cleaning demand. EPA residue-threshold mandates in California's Central Valley and Florida's citrus belt compress turnaround schedules for these units.
- Spray Equipment:Booms, nozzles, and pump assemblies face polymer clogging from suspended crop-protection chemistries. Brazil's Mato Grosso soybean co-ops deploy dedicated cleaning lines to maintain narrow application windows during planting season.
- Bulk Containers:Intermediate bulk totes and rigid intermediate bulk containers (IBCs) serve specialty crop exporters with REACH-compliant rinse protocols for EU-bound produce.
- Drums:Standard 55-gallon and 30-gallon pesticide containers require manual pre-rinse and high-pressure finishing cycles at third-party service depots.
Today's leader: Liquid Tanks. Tomorrow's challenger: Spray Equipment.
Cleaning Method:
Margin pools concentrate where formulation complexity demands pH-neutralizing chemistry and automated documentation trails.
- Chemical Cleaning:Formulation-specific surfactants and neutralizing agents address polymer residues and bioaccumulation risks. REACH dossier requirements for rinse-water discharge elevate service-provider certification barriers in export-oriented growing regions.
- High-Pressure Washing:Systems exceeding 150 bar remove tenacious residue films from tank interiors. Stainless steel supply bottlenecks constrain fabrication capacity for these units.
- Steam Cleaning:Thermal remediation suits temperature-tolerant vessel materials in organic-certified operations. California tree-nut growers specify steam protocols for residue-limit compliance.
- Manual Cleaning:Brush-and-rinse methods persist for small drum volumes and legacy equipment lacking automated wash-arm retrofit compatibility.
Today's leader: Chemical Cleaning. Tomorrow's challenger: High-Pressure Washing.
End User:
Customer scale determines captive-versus-outsourced cleaning economics and compliance-documentation depth.
- Agricultural Cooperatives:Fleet-scale operations in Brazil's Mato Grosso and the US Midwest justify centralized cleaning infrastructure with robotic wash-arm deployment. Co-op consolidation creates demand concentration that individual farms cannot replicate.
- Farms:Mid-scale operations face EPA Worker Protection Standard upgrade costs that push cleaning spend toward third-party mobile services. On-site infrastructure investments compress as service-contract unbundling accelerates.
- Food Processing Plants:Post-harvest handling facilities require container hygiene verification for supply-chain entry into EU and North American retail channels.
- Chemical Manufacturers:Formulation producers maintain captive cleaning for research-scale vessels and quality-control sampling equipment.
Today's leader: Agricultural Cooperatives. Tomorrow's challenger: Farms.
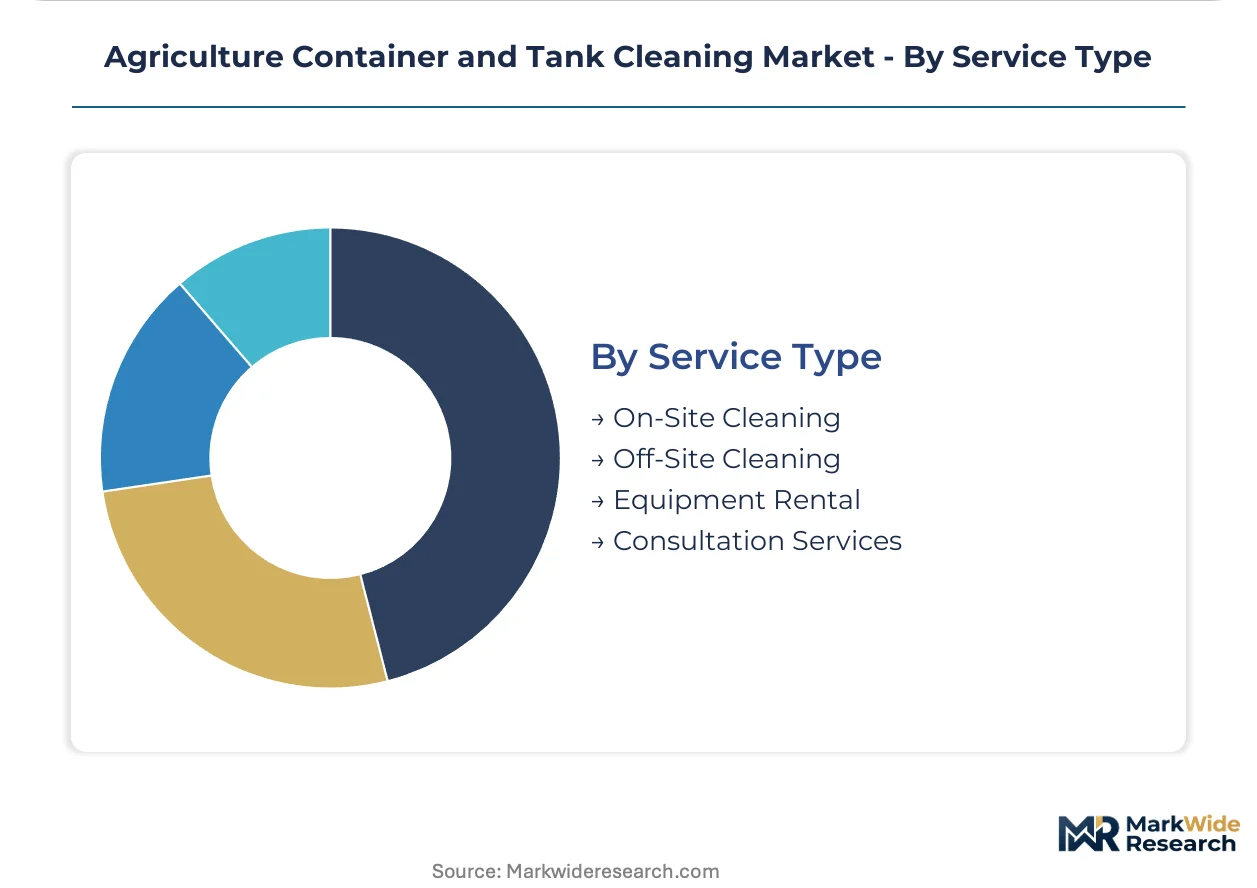
Service Type:
Revenue-model evolution separates equipment-access plays from recurring compliance-documentation services.
- On-Site Cleaning:Mobile high-pressure units and chemical-formulation trucks deliver scheduled service at farm and co-op locations. OSHA Hazard Communication Standard training requirements elevate technician-certification costs for these operators.
- Off-Site Cleaning:Centralized depots with fixed wash bays capture drum and small-container volumes. Florida citrus belt growers negotiate spot contracts based on residue-test outcomes rather than annual commitments.
- Equipment Rental:Pressure-wash system leasing with maintenance bundling serves seasonal demand peaks without capital deployment.
- Consultation Services:Compliance-program design and EPA documentation support address regulatory-stringency divergence across customer geographies.
Today's leader: On-Site Cleaning. Tomorrow's challenger: Off-Site Cleaning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized technician pools for high-pressure system maintenance concentrate in agricultural machinery corridors across Brazil, the United States, Germany, and Australia. These workforce clusters anchor regional cleaning infrastructure deployment patterns.
United States
EPA Worker Protection Standard revisions force precision-agriculture fleets in California's Central Valley and Florida's citrus belt toward automated wash systems. The EPA's Container Containment Regulations exceed manual cleaning capabilities for residue thresholds. Iowa's corn-soybean cooperatives deploy centralized cleaning depots to maintain narrow planting-season application windows.
Brazil
Co-op consolidation in Mato Grosso's soybean belt creates fleet-scale demand that individual farms cannot replicate economically. ANVISA pesticide residue protocols align with EU export requirements for European food-processing supply chains. São Paulo state's sugarcane ethanol processors invest in shared tank-cleaning infrastructure for flex-fuel distribution networks.
Germany
REACH chemical-registration requirements elevate documentation burdens for cleaning-agent formulations serving EU export supply chains. ECHA toxicity dossier submissions for rinse-water discharge constrain smaller service providers. Bavaria's precision-agriculture equipment manufacturers integrate wash-system modules into original sprayer specifications.
Australia
Grain-handling cooperatives in Western Australia's wheat belt specify third-party-certified cleaning programs for Asian export markets. The country's national chemical regulator enforces residue limits matching EU and Japanese import standards. Queensland's sugar industry clusters adopt steam-cleaning protocols for organic-certified operations supplying premium Asian buyers.
Canada
Health Canada and PMRA joint oversight of pesticide container management elevates compliance costs for prairie grain operations. Alberta's canola processing facilities require container hygiene verification for EU biodiesel supply-chain entry. Ontario's fruit and vegetable growers negotiate spot contracts based on residue-test outcomes rather than annual chemical volume commitments.
Agriculture Container and Tank Cleaning Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment fabrication, chemical formulation, and third-party service delivery. The vendor base separates into three strategic archetypes: nozzle-technology heritage firms, integrated chemical-cleaning program providers, and hazardous-waste handling permit holders. Consolidation pressure intensifies as regulatory stringency compresses margins for undifferentiated service operators. Dominant competitive moves include M&A for geographic coverage expansion and strategic partnerships for IoT-enabled compliance documentation.
Within the integrated service tier, Clean Harbors and Veolia Environmental Services anchor North American and European demand through hazardous-waste handling permits and mobile fleet deployment. Lechler GmbH occupies a position among nozzle-technology heritage specialists leveraging precision-spray knowledge into high-pressure wash system design. Ecolab exemplifies the chemical-program bundling archetype, combining formulation supply with equipment hygiene verification for export-oriented growing regions.
| Leading Market Players |
|---|
| Lechler GmbH |
| Loveland Products |
| Alfred Kärcher GmbH |
| Clean Harbors |
| Veolia Environmental Services |
| Tradebe Refinery Services |
| Evergreen Industrial Services |
| SWS Environmental Services |
| Ecolab |
| Others |
Value Network & Pricing Analysis
EPA's Container Containment Regulations gate qualified supply and premium-tier pricing access, forcing equipment vendors to absorb certification costs or cede share to hazardous-waste permit holders. Buyers face tiered service economics where robotic wash-arm documentation commands surcharge premiums over manual cleaning alternatives.
Pricing Analysis
The bundled-vs-unbundled service split separates annual chemical-commitment contracts from spot-priced per-wash transactions. Pricing stratifies across premium, standard, and economy tiers based on IoT-enabled compliance documentation and technician certification depth. Cost compression in the economy tier intensifies as mobile third-party services displace captive infrastructure among mid-scale farms. Agricultural cooperatives show least price sensitivity due to fleet-scale throughput, while individual farms negotiate aggressively on per-wash rates.
Supply Chain Analysis
High-pressure wash system fabrication rests on specialty-grade stainless steel inputs concentrated in Germany, Japan, and South Korea. Robotic wash-arm assemblies draw from precision-machining clusters in Bavaria and São Paulo state. Single-source vulnerability persists for 150+ bar pump assemblies sourced from German industrial pump specialists. Distribution runs through OEM-integrated channels for new equipment and independent service depots for aftermarket cleaning contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Worker Protection Standard revisions force recurring capital deployment and service-interval compression across precision-agriculture fleets.
For Market Incumbents: Anchor market position through hazardous-waste permit expansion into adjacent agricultural clusters and backward integration into stainless steel fabrication partnerships. IoT-enabled compliance documentation investments defend against commodity service erosion from unbundled mobile operators. Certification depth in REACH-aligned chemistry formulations creates switching costs for export-oriented specialty crop growers. For New Entrants and Emerging Players: Enter via California's Central Valley and Florida's citrus belt where residue-limit tightening outpaces incumbent service capacity. Mid-scale farm segments in Iowa and Illinois present the most penetrable white-space, as EPA upgrade costs push cleaning spend toward outsourced providers. A per-wash spot-contract model with transparent residue-test outcomes disrupts legacy annual chemical-volume commitments. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mobile tank-cleaning operators lacking IoT documentation capabilities but holding EPA and OSHA permit foundations. Long-term viability favors hazardous-waste handling specialists with geographic expansion optionality into Brazil's Mato Grosso co-op consolidation. Watch ANVISA-EU regulatory alignment acceleration as the signal for cross-border service scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Compliance Documentation | Sensor-integrated pressure logging creates audit trails that EPA residue-verification protocols now require. |
| Backward Integration into Stainless Steel Sourcing | Captive supply of specialty-grade inputs insulates fabrication margins from volatile commodity pricing. |
| Hazardous-Waste Permit Geographic Expansion | Clean Harbors and Veolia anchor North American demand through regulatory moats that smaller operators cannot replicate. |
| Robotic Wash-Arm Fleet Deployment | Automated interior coverage eliminates confined-space entry requirements and compresses turnaround times for narrow application windows. |
| REACH-Aligned Chemical Formulation Certification | ECHA toxicity dossier submission capabilities differentiate service providers in California and Florida export corridors. |
Research Methodology
Direct dialogue with tank-cleaning service operators, precision-agriculture fleet managers, EPA compliance officers, stainless steel fabrication procurement leads, and hazardous-waste permit specialists grounded qualitative findings. Secondary validation drew from EPA enforcement action databases, OSHA injury and illness records, ANVISA residue monitoring reports, ECHA REACH dossier submissions, and SEC 10-K filings from diversified environmental services conglomerates. Bottom-up and top-down triangulation cross-checked service-volume estimates against equipment shipment data and regulatory inspection frequency trends.
Bottom-up modeling built from individual vessel cleaning-frequency assumptions by crop type and application season, while top-down analysis anchored on agricultural chemical consumption patterns and co-op consolidation trajectories. Segmentation dimensions included vessel geometry, cleaning-method chemistry, end-user scale, and service-delivery model across the analysis window. CAGRs derived from regression of historical service-price indices against regulatory milestone timing and technician wage inflation.
The model holds under steady regulatory enforcement intensity and stainless steel supply continuity; deviation in tariff escalation or REACH-ANVISA harmonization acceleration would shift equipment-deployment timing and service-contract pricing. A small set of named triggers—EPA inspection frequency changes, Brazilian co-op merger waves, and EU import standard tightening—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Lawn Aerators Market