
 Genetically Modified Feed Market | 2026-2036
Genetically Modified Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Genetically Modified Feed Market Analysis
Multi-source trait licensing is expanding as seed developers broaden their germplasm partnerships. Bayer AG sustains its position through proprietary herbicide-tolerance stacks in corn and soybean germplasm. BASF SE anchors European demand with high-oleic soybean traits tailored for monogastric rations. Corteva Agriscience differentiates via CRISPR-edited nutrient-density profiles in forage varieties.
Genetically modified feed comprises plant-derived ingredients carrying recombinant DNA traits—herbicide tolerance, insect resistance, or altered fatty-acid profiles—introduced through Agrobacterium-mediated transformation or biolistic particle delivery, then processed into meal, silage, or oil for livestock consumption. Corn and soybean dominate product-type volumes, with corn silage commanding premium pricing in ruminant systems due to stacked-trait royalties embedded in seed costs. Application demand tilts toward poultry and swine, where amino-acid-optimized soybean meal reduces supplemental synthetic lysine requirements and tightens feed conversion ratios.
The USDA's Animal and Plant Health Inspection Service governs trait deregulation for interstate commerce, while the FDA evaluates stacked-trait safety under its voluntary consultation program, creating dual compliance pathways that lengthen time-to-market for novel events. The EPA mandates refuge requirements for insect-resistant varieties, directly influencing seed pricing and grower contract structures. Stakeholders must monitor evolving gene-editing regulatory distinctions, as USDA-FDA jurisdictional clarity on CRISPR versus transgenic approaches will reshape trait development investment priorities.
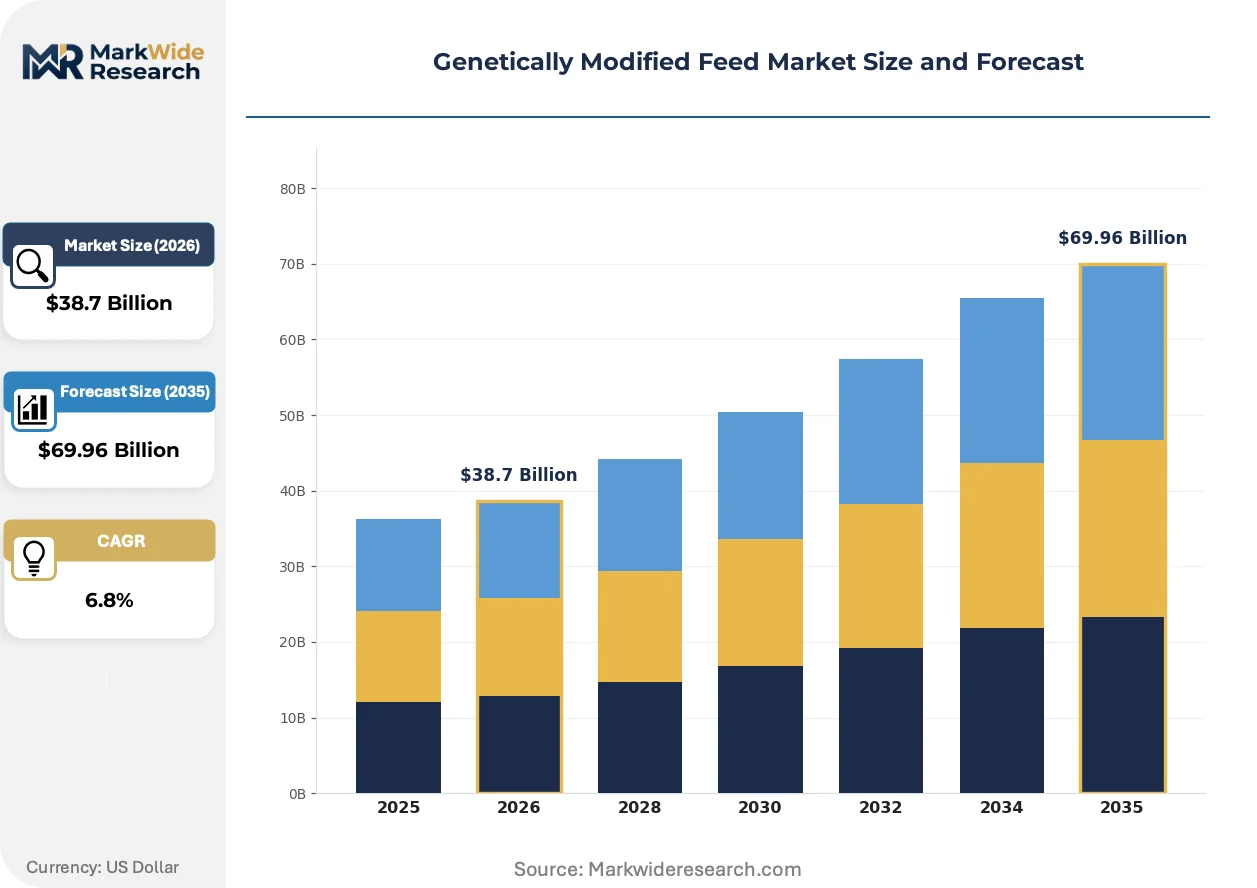
Market Dynamics
Stacked-trait royalty structures embedded in seed costs are compressing margins for contract growers while concentrating purchasing power among integrated livestock processors in the United States Corn Belt.
Growth Catalysts
- Poultry sector expansion:Amino-acid-optimized soybean meal reduces synthetic lysine supplementation costs for broiler operations. Tighter feed conversion ratios drive contract volume commitments from vertically integrated processors.
- CTNBio streamlined approvals:Brazil's national biosafety regulator accelerates trait deregulation timelines for imported soybean varieties. Faster market access for stacked-herbicide-tolerance events expands germplasm options for Brazilian growers.
- CRISPR nutrient density:Gene-edited forage varieties with enhanced metabolizable protein profiles command premium positioning in dairy rations. Reduced supplemental protein requirements lower total mixed ration costs for high-producing herds.
Market Restraints
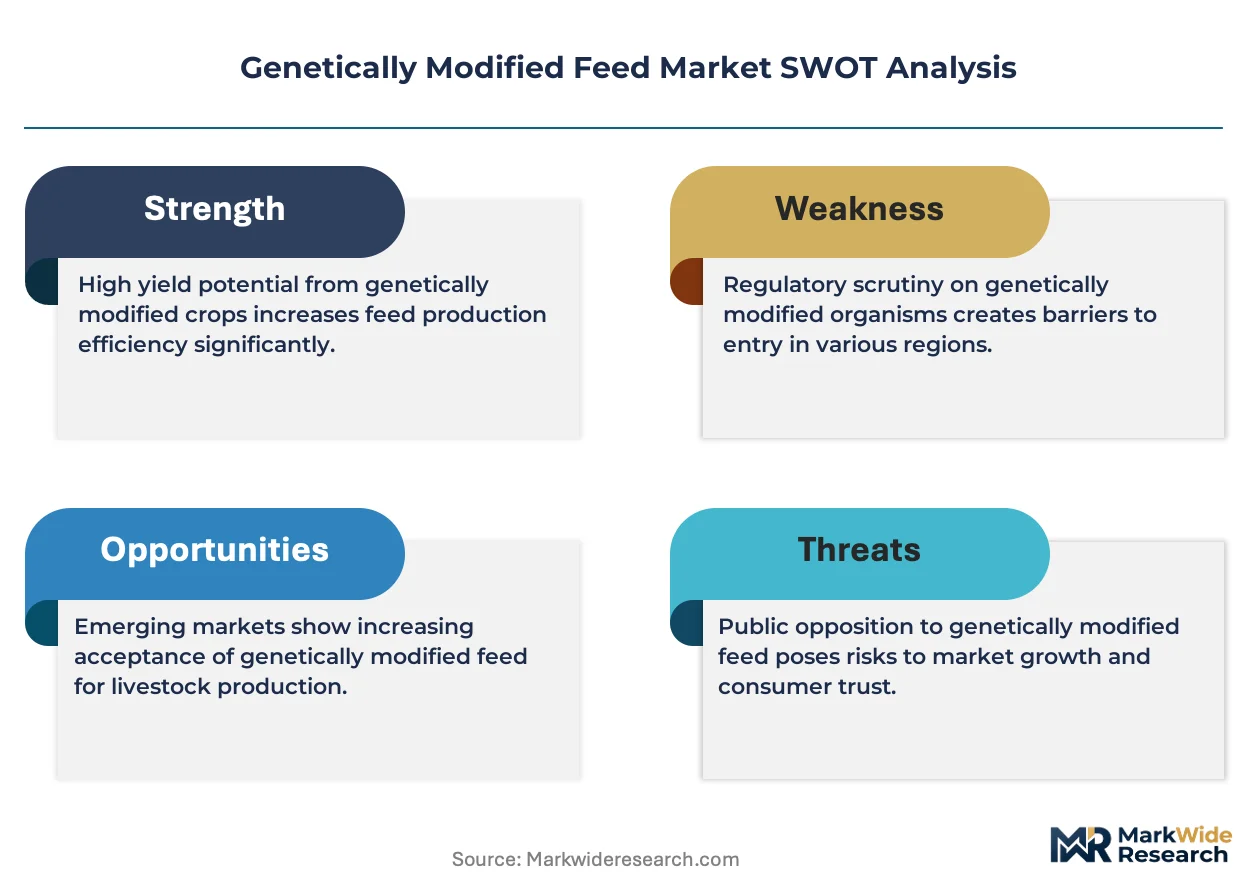
- Dual compliance pathways:USDA-APHIS interstate commerce rules and FDA voluntary consultation programs create overlapping jurisdiction. Novel stacked-trait events face extended time-to-market delays from redundant safety evaluations.
- Refuge mandate costs:EPA requirements for insect-resistant corn varieties mandate structured refuge planting. Seed pricing incorporates compliance premiums that transfer directly to grower contract structures.
- Gene-editing regulatory uncertainty:USDA-FDA jurisdictional boundaries on CRISPR versus transgenic classification remain unresolved. Investment prioritization for trait development pipelines stalls pending formal guidance.
Strategic Opportunities
- Monogastric precision nutrition:High-oleic soybean traits tailored for swine and poultry rations reduce omega-6 fatty acid supplementation. European demand for improved pork fat quality profiles creates specialized product positioning.
- Direct processor contracting:Livestock integrators in Iowa and Illinois are bypassing grain elevators for herbicide-tolerant corn silage. Captive supply arrangements lock in trait royalty pass-through structures.
- Silage premium capture:Stacked-trait corn silage with enhanced fiber digestibility commands price premiums in ruminant systems. Dairy nutritionists in Wisconsin and California prioritize NDF digestibility metrics in purchasing decisions.
Industry Challenges
- Trait licensing complexity:Multi-source germplasm partnerships require navigation of overlapping intellectual property estates. Seed developers face royalty stacking disputes when combining events from different patent holders.
- Gene-editing talent scarcity:CRISPR protocol optimization for forage species demands specialized molecular breeding expertise. Public-sector breeding programs struggle to retain personnel against private-sector compensation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetically Modified Feed Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn, Soybean, Canola, Alfalfa Application: Poultry, Swine, Ruminants, Aquaculture Grade: Feed Grade, Premium Grade, Standard Grade, Organic Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors |
| Companies Covered | BASF SE, Bayer AG, Syngenta Crop Protection AG, Corteva Agriscience, Groupe Limagrain Holding, KWS SAAT SE & Co. KGaA, J.R. Simplot Company, Okanagan Specialty Fruits Inc., Stine Seed Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetically Modified Feed Market Emerging Trajectories
Digital phenotyping platforms and automated trait selection pipelines are compressing variety development cycles while regulatory frameworks scramble to classify novel breeding outputs.
CRISPR-Cas9 editing of fatty-acid biosynthesis pathways is automating the development of high-oleic soybean lines with altered linoleic acid profiles. Poultry integrators in the southeastern United States are adopting these varieties at accelerating rates for broiler rations. The technology is automating what previously required multi-generational backcrossing programs, collapsing development timelines from eight years to three.
EU Green Deal sustainability criteria are tightening import tolerances for deforestation-linked soybean meal. European feed compounders now demand mass-balance certification for South American origin material. The regulation is forcing procurement pattern changes, with Dutch and Danish processors prioritizing verified supply chains over lowest-cost sourcing.
Integrated livestock processors are consolidating feed-milling capacity under captive ownership to secure trait-specific ingredient flows. Direct origination from Corn Belt growers displaces spot-market purchasing through traditional grain merchants. This concentration is most visible in Iowa, where two processors now contract directly for over sixty percent of regional herbicide-tolerant corn silage production.
Genetically Modified Feed Market Segmentation
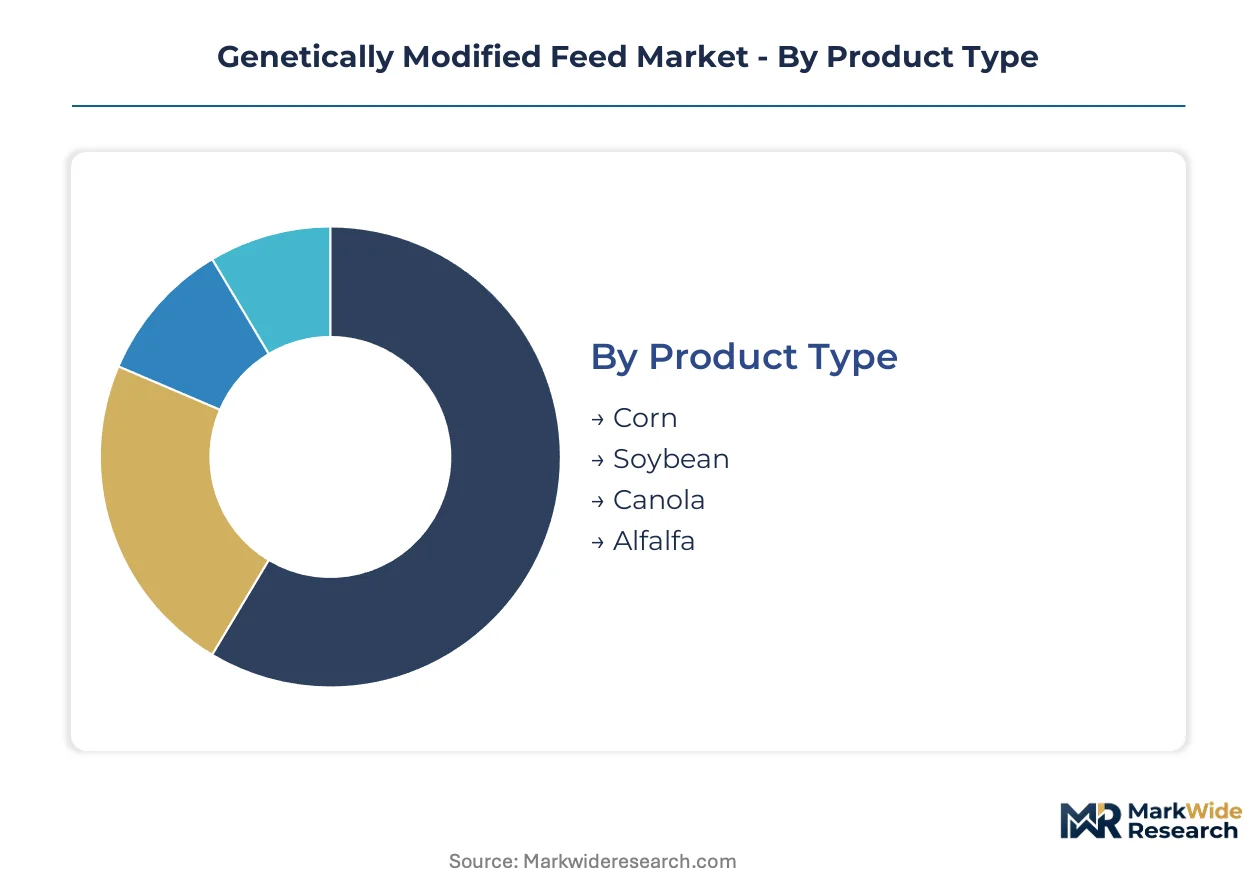
Segmentation in the genetically modified feed market reflects divergent buyer priorities across livestock systems. Trait royalty structures, amino-acid optimization requirements, and processor contracting patterns reshape how each segment captures value.
Product Type:
Procurement volume concentrates where stacked-trait royalties align with feed conversion economics in named livestock systems.
- Corn:Herbicide-tolerant and insect-resistant corn varieties dominate ruminant silage and poultry energy formulations. Demand clusters in the United States Corn Belt, where Iowa and Illinois processors contract directly for stacked-trait silage to lock in fiber digestibility premiums.
- Soybean:Amino-acid-optimized meal reduces synthetic lysine supplementation in monogastric rations. Brazilian growers accelerate adoption following CTNBio's streamlined import approval timelines for stacked-herbicide-tolerance events.
- Canola:High-oleic oil profiles serve specialized swine fat quality specifications in European compound feed formulations.
- Alfalfa:CRISPR-edited lignin-modified varieties target dairy metabolizable protein optimization in Wisconsin and California high-producing herds.
Volume sits with corn and soybean; growth tilts toward alfalfa as gene-editing protocols collapse development timelines.
Application:
Feed conversion ratio targets and synthetic amino-acid substitution economics determine species-specific trait premiums.
- Poultry:Broiler operations drive contract volume commitments for amino-acid-optimized soybean meal. Vertically integrated southeastern United States processors prioritize reduced synthetic lysine dependency in ration formulations.
- Swine:High-oleic soybean traits improve pork fat quality profiles for European retail specifications. Danish and Dutch compounders demand mass-balance certification for deforestation-free South American origin material.
- Ruminants:Stacked-trait corn silage with enhanced NDF digestibility commands nutritionist prioritization in Wisconsin dairy systems.
- Aquaculture:Specialized fatty-acid profiles from modified oilseeds address omega-3 substitution requirements in salmonid feed.
Poultry and swine anchor current procurement volumes; ruminant systems capture expanding silage premium structures.
Grade:
Certification requirements and trait royalty pass-through mechanisms stratify pricing tiers across buyer segments.
- Feed Grade:Baseline stacked-trait formulations serve cost-sensitive bulk purchasers in spot-market transactions.
- Premium Grade:Enhanced nutrient-density profiles and verified supply chain documentation support processor captive contracting arrangements.
- Standard Grade:Single-trait or conventional alternatives fill price-sensitive ration slots where synthetic supplementation remains economical.
- Organic:Excludes GM ingredients entirely, creating parallel procurement channels for certified livestock operations.
Feed grade dominates transaction volume; premium grade expands most quickly under direct processor origination models.
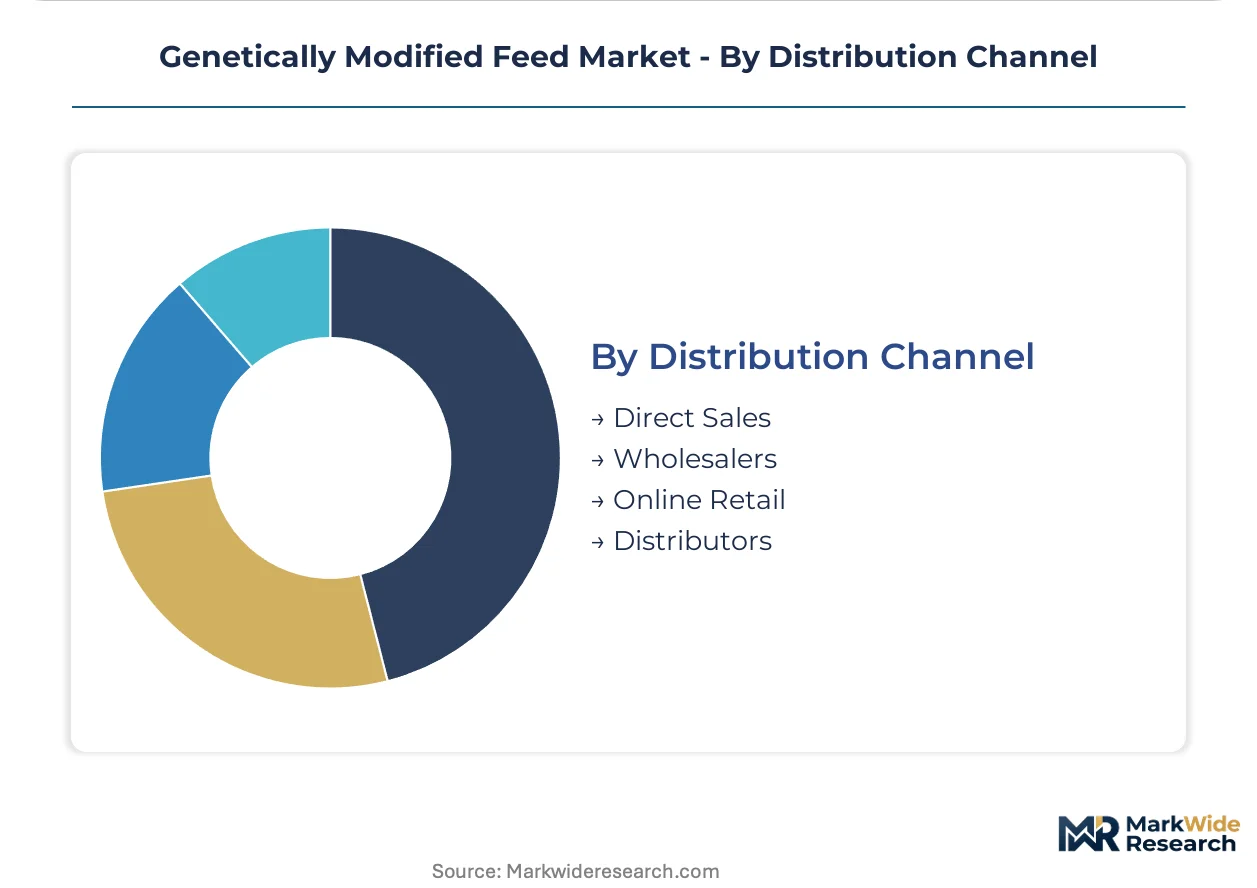
Distribution Channel:
Supply chain control preferences and trait traceability requirements reshape intermediary roles across livestock systems.
- Direct Sales:Integrated livestock processors in Iowa and Illinois bypass grain elevators for herbicide-tolerant corn silage, locking in royalty pass-through structures through captive supply arrangements.
- Wholesalers:Regional grain merchants aggregate smaller grower volumes for spot-market delivery to independent feed mills.
- Online Retail:Digital platforms serve specialty ingredient procurement for niche livestock operations and research institutions.
- Distributors:Multi-regional networks handle imported soybean meal logistics for coastal compound feed manufacturers.
Direct sales concentrate volume in Corn Belt silage systems; distributor channels retain importance for South American import flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean origination from Brazil's Cerrado and corn production across the United States Corn Belt anchor the genetically modified feed supply base. Regulatory divergence between major producing jurisdictions shapes trait approval timelines and market access patterns.
United States
Integrated poultry processors in Georgia and Arkansas contract directly for amino-acid-optimized soybean meal to reduce synthetic lysine dependency. The USDA's Animal and Plant Health Inspection Service governs interstate commerce deregulation while the FDA evaluates stacked-trait safety under voluntary consultation. Iowa and Illinois processors now source over sixty percent of regional herbicide-tolerant corn silage through captive supply arrangements bypassing traditional grain elevators.
Brazil
CTNBio streamlined approval timelines for imported stacked-herbicide-tolerance soybean varieties accelerate germplasm adoption among Mato Grosso growers. The national biosafety regulator's faster deregulation processes expand trait options for Brazilian producers. São Paulo-based compounders secure verified supply chains to meet EU Green Deal deforestation-free import requirements for European export markets.
China
Domestic soybean crushing capacity expansion in coastal provinces drives import demand for South American GM meal. The Ministry of Agriculture and Rural Affairs maintains a phased approval system for foreign trait events entering food and feed channels. Shandong and Jiangsu processors concentrate import origination through dedicated port facilities with integrated testing laboratories for biosafety certificate verification.
Germany
High-oleic soybean demand from Danish and Dutch compounders flows through Hamburg port logistics for monogastric precision nutrition formulations. EFSA evaluates novel trait safety for EU market access while member state cultivation bans fragment adoption geography. Bavarian dairy nutritionists prioritize CRISPR-edited alfalfa varieties with enhanced metabolizable protein profiles for high-producing herd rations.
India
Poultry sector expansion in Telangana and Andhra Pradesh drives soybean meal procurement from domestic crushing capacity. The Food Safety and Standards Authority of India governs GM food and feed approval pathways with import authorization requirements for foreign-origin material. Maharashtra oilseed processors navigate regulatory uncertainty pending formal gene-editing classification guidance from central authorities.
Genetically Modified Feed Market Vendor Landscape
Global majors compete with regional champions across trait licensing networks and germplasm distribution systems. The vendor base concentrates around integrated agrochemical-seed conglomerates with proprietary biotechnology pipelines and multi-source partnership architectures. Three archetypes dominate: diversified chemistry-seed conglomerates with stacked-trait platforms, specialized seed developers with regional germplasm expertise, and gene-editing specialists with CRISPR protocol capabilities. Competitive moves center on multi-source trait licensing agreements and direct processor contracting arrangements that displace traditional grain merchant intermediaries.
Among chemistry-seed conglomerates, BASF SE and Bayer AG occupy positions defined by proprietary herbicide-tolerance stacks and broad germplasm access. Corteva Agriscience exemplifies the gene-editing specialist archetype through CRISPR-edited nutrient-density profiles. These three entities anchor the competitive structure while KWS SAAT SE & Co. KGaA represents regional European seed development with specialized forage and cereal germplasm expertise.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Crop Protection AG |
| Corteva Agriscience |
| Groupe Limagrain Holding |
| KWS SAAT SE & Co. KGaA |
| J.R. Simplot Company |
| Okanagan Specialty Fruits Inc. |
| Stine Seed Company |
| Others |
Supply Flow & Price Mechanics
Integrated livestock processors in Iowa and Illinois anchor pricing power through captive corn silage contracting that locks in trait royalty pass-through structures and displaces spot-market grain elevator intermediation.
Pricing Analysis
Seed cost bundling with mandatory refuge compliance premiums shapes the dominant pricing structure, with EPA-mandated structured refuge planting for insect-resistant corn varieties embedding compliance costs directly into grower contracts. Price differentiation hinges on fiber digestibility certification tiers and synthetic amino-acid substitution economics in monogastric formulations. Pricing pressure stems from stacked-trait royalty stacking disputes among multi-source germplasm licensors compressing seed developer margins. Independent feed mills exhibit highest price sensitivity due to spot-market volume exposure, while vertically integrated poultry processors absorb premiums through captive supply arrangements.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian germplasm dependence for stacked-herbicide-tolerance soybean events approved through CTNBio's streamlined import pathways. Raw material flows draw from United States Corn Belt corn production, Brazilian Cerrado soybean origination, and German port logistics for European high-oleic oilseed processing. Supply chain risk centers on EU Green Deal deforestation-free certification requirements disrupting South American meal flows to Danish and Dutch compounders. Distribution runs through direct processor origination networks in Iowa and Illinois, with coastal distributor channels handling Brazilian import logistics for Chinese and European crushing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trait development pipeline capacity constraints prop pricing premiums as gene-editing regulatory classification delays stall CRISPR protocol investment prioritization across public and private breeding programs.
For Market Incumbents: Deploy multi-source trait licensing architectures to defuse royalty stacking disputes when combining events from disparate patent holders. BASF SE and Bayer AG should deepen backward integration into CRISPR forage development capabilities before Corteva Agriscience consolidates nutrient-density positioning. Seed developers must secure direct processor contracting relationships in Wisconsin and California dairy systems to preempt grain elevator displacement.
For New Entrants and Emerging Players: CTNBio streamlined approvals in Brazil open a window for specialized soybean developers to capture germplasm adoption among Mato Grosso growers ahead of incumbent portfolio expansion. Target alfalfa gene-editing protocols for Wisconsin high-producing herd rations where public-sector breeding programs face talent retention deficits. Pursue mass-balance certification capabilities for EU Green Deal compliance as a differentiated origination service for São Paulo-based compounders.
For Investors and Strategic Acquirers: The window for entry favors CRISPR protocol specialists with demonstrated forage species optimization capabilities. Long-term viability rests on regulatory clarity arbitrage between USDA-FDA gene-editing jurisdictional boundaries. Monitor EFSA novel trait safety evaluation timelines as the inflection indicator for European market access premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Trait Licensing Agreement | Resolves royalty stacking disputes across overlapping intellectual property estates in stacked-trait corn. |
| Direct Processor Contracting Expansion | Locks in captive supply arrangements with Iowa and Illinois integrators bypassing traditional grain elevators. |
| CRISPR Protocol Development Investment | Collapses alfalfa development timelines from eight years to three for Wisconsin dairy metabolizable protein optimization. |
| Mass-Balance Certification Program | Enables São Paulo compounders to meet EU Green Deal deforestation-free import requirements for European export markets. |
| Gene-Editing Regulatory Engagement | Clarifies USDA-FDA jurisdictional boundaries to unlock investment prioritization for novel trait pipelines. |
Methodological Framework
Independent corroboration across seed developer R&D directors, integrated poultry processor procurement leads, and CTNBio regulatory affairs specialists underwrites the qualitative findings. Primary interviews with dairy nutritionists in Wisconsin and California, Brazilian Mato Grosso growers, and Hamburg port logistics operators combined with secondary validation from USDA-APHIS deregulation filings, CTNBio approval databases, and EU Green Deal regulatory texts. Bottom-up volume modeling across corn, soybean, canola, and alfalfa product types triangulated against top-down value estimates from seed cost structures and trait royalty pass-through mechanisms.
Comparable historical reference periods anchored the projection framework to observed adoption curves for stacked-trait events and CRISPR-edited variety commercialization. Segmentation dimensions modeled include product type, livestock application, certification grade tier, and distribution channel structure across the analysis window. CAGRs derived from trend extrapolation of contract volume commitments and processor captive supply expansion rates, with inputs from amino-acid optimization economics and fiber digestibility premium capture in ruminant systems.
The model assumes a particular technology adoption path; alternative pathways for CRISPR regulatory classification would alter the outlook. Forecasts reflect assumptions regarding CTNBio approval velocity, EU deforestation enforcement stringency, and USDA-FDA jurisdictional clarity that remain subject to revision. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
Singapore Floriculture Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Ghana Agriculture Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Netherlands Cashew Market
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Organic Farming Market