
 Canary Seeds Market | 2026-2036
Canary Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Canary Seeds Market Outlook
Subscription-based seed replenishment services is shifting how canary seeds reach hobbyist breeders and small-scale aviaries. Saskatchewan Seed Company leverages its prairie milling infrastructure to dominate North American bulk supply. Globus Seeds S.A. anchors South American export flows through Buenos Aires port logistics. Bird City International, Inc. specializes in curated retail assortments for specialty pet stores.
Canary seeds are small, hard caryopses of Phalaris canariensis, typically containing 20% protein and 5% oil by weight, cleaned and graded to 99% purity for commercial trade. The crop serves primarily as a high-energy feed component for caged songbirds and, increasingly, as a gluten-free human food ingredient. Organic canary seeds command premium positioning as health supplements and specialty flour applications expand, while conventional grades still occupy the volume core of pet food and bird feed formulations. Single-serve packs are capturing margin pools in urban convenience retail, whereas bulk containers sustain commodity economics for millers and blenders.
Health Canada and the Canadian Food Inspection Agency enforce strict phytosanitary and varietal purity rules that shape import eligibility and domestic cultivation incentives. The USDA's Animal and Plant Health Inspection Service and the FDA's food safety frameworks govern U.S. market access and labeling for human-grade canary seed products. Stakeholders must monitor evolving gluten-free certification standards and shifting pet humanization trends to anticipate which product grades will capture downstream value.
Market Dynamics
Canada's tightening organic certification standards are forcing import-dependent processors to restructure sourcing networks and accelerate domestic varietal development programs.
Growth Catalysts
- Health Canada varietal purity mandates:Domestic millers gain preferential access to certified seed stocks, incentivizing prairie acreage expansion.
- Plant-based protein diversification:Food manufacturers reformulate gluten-free flour blends to incorporate canary seed isolates for amino acid completeness.
- Buenos Aires port infrastructure:Argentina's bulk handling capacity reduces trans-Pacific shipping friction for Asian feed compounders.
Market Restraints
- Fertilizer input cost volatility:Nitrogen and phosphorus price swings compress margins for Saskatchewan contract growers operating on fixed-price delivery agreements.
- Single-origin concentration risk:Argentina's Pampas region supplies over half of export-grade stocks, exposing buyers to drought-induced yield shocks.
- Substitution pressure from millet:Lower-cost panicum varieties displace canary seed in price-sensitive avian feed formulations across Southeast Asian markets.
Strategic Opportunities
- Subscription seed replenishment channels:Direct-to-aviary platforms capture recurring revenue from hobbyist breeders previously served by pet store intermediaries.
- EU gluten-free certification alignment:EFSA novel food approvals open human-grade ingredient positioning for Canadian organic exporters.
- CRISPR-accelerated breeding convergence:Gene-edited Phalaris canariensis lines with elevated methionine content target poultry feed premiumization.
Industry Challenges
- Organic transition timeline compression:Three-year land history requirements under Canada's COR standard delay new entrant certification for contract growers.
- Specialized cleaning equipment capex:99% purity thresholds demand optical sorter investments that smallholder cooperatives cannot amortize across limited tonnage.
- Phytosanitary documentation complexity:USDA APHIS import permits require varietal origin tracing that fragments procurement from multi-source aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canary Seeds Market |
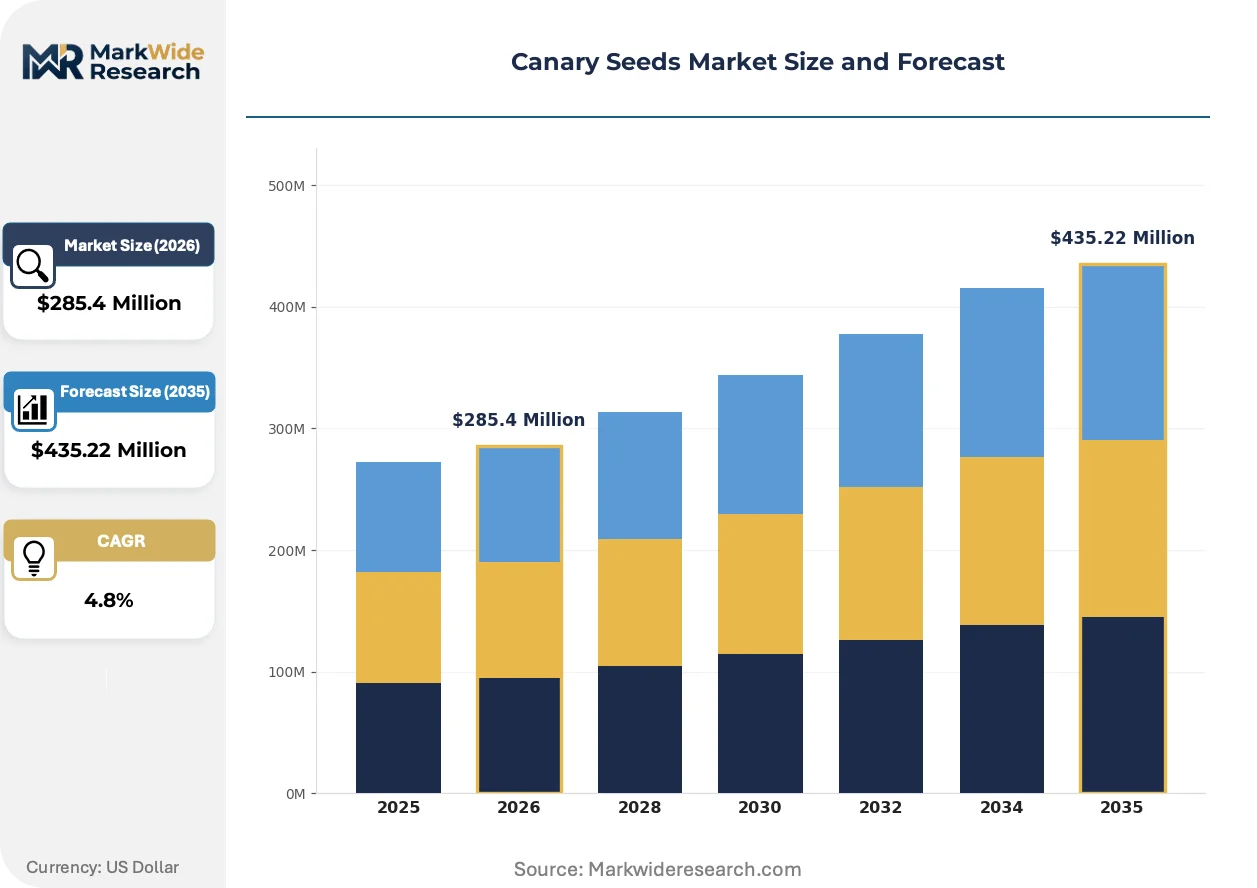
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Canary Seeds, Conventional Canary Seeds, Sprouted Canary Seeds, Roasted Canary Seeds End Use: Pet Food, Bird Feed, Human Consumption, Health Supplements Packaging Type: Bags, Bulk Containers, Single-Serve Packs, Retail Packs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Pepef Seeds Corporation, Bird City International, Inc., Saskatchewan Seed Company, Tarquin Seeds Ltd., True Grass Seeds Ltd., Hometown Seeds, Globus Seeds S.A., Grain Millers, Inc., Finseed Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canary Seeds Market Strategic Shifts
Digital traceability platforms and gene-edited breeding pipelines are compressing traditional quality assurance cycles while opening novel human-food positioning for a crop historically confined to avian feed.
Optical sorting technology is modularizing quality control workflows across prairie cleaning facilities. Mid-scale processors in Saskatchewan and Manitoba deploy machine-vision systems that separate ergot-contaminated kernels at throughput rates previously achievable only by centralized exporters. This capability diffusion enables regional cooperatives to bypass traditional bulk aggregators and contract directly with specialty pet food manufacturers.
Health Canada's updated gluten-free labeling regulations are tightening cross-contamination thresholds for human-grade canary seed products. The Canadian Food Inspection Agency now mandates lot-specific allergen testing for any ingredient destined for bakery applications. Domestic millers respond by segregating food-grade handling lines entirely from pet feed operations, creating parallel supply chains with divergent cost structures.
Urban hobbyist breeders increasingly source canary seed through curated subscription boxes rather than agricultural supply depots. Specialty retailers in Toronto, Vancouver, and Montreal bundle varietal assortments with veterinary-formulated mineral supplements, capturing margin pools that commodity distributors cannot access. This channel shift rewards packagers with in-house blending capabilities and direct-to-consumer logistics infrastructure.
Canary Seeds Market Segmentation
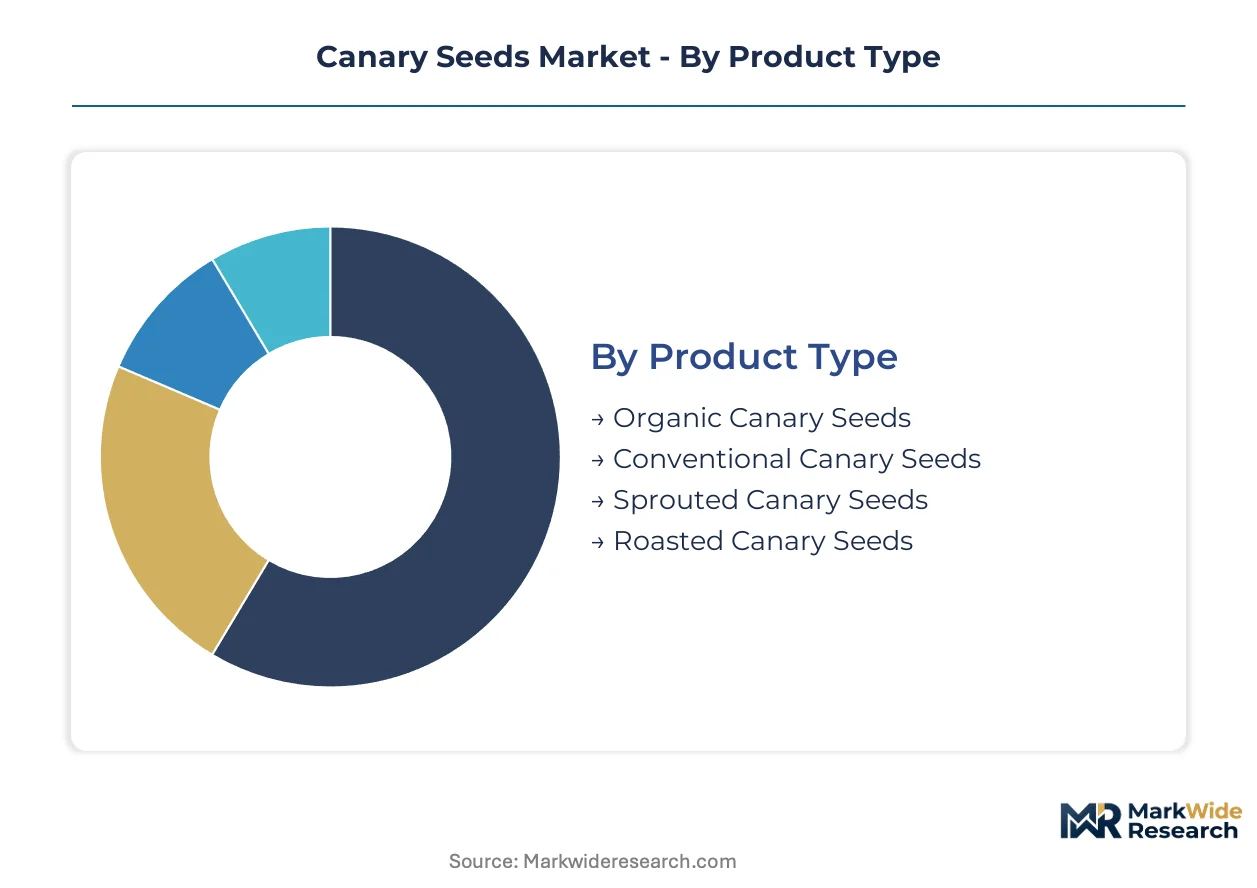
Canary seed segmentation reflects divergent certification burdens across product grades. Human-grade positioning demands Health Canada gluten-free validation and CFIA lot-specific allergen testing, while pet feed segments operate under less stringent purity thresholds.
Product Type:
Organic canary seeds carry the heaviest regulatory load, requiring COR three-year land history documentation and varietal purity certificates for import eligibility into Canada.
- Organic Canary Seeds:These seeds meet Canada's COR standard with full traceability from field to package. Saskatchewan contract growers dominate supply, with Health Canada mandates accelerating domestic acreage expansion. Premium positioning in health supplements and gluten-free flour applications commands price multiples over conventional grades.
- Conventional Canary Seeds:Standard 99% purity grades serve volume pet food and bird feed formulations without organic certification overhead. Argentina's Pampas region anchors export supply, though drought exposure creates procurement volatility for North American millers.
- Sprouted Canary Seeds:Germinated forms target raw food enthusiasts and specialty health retailers requiring enhanced enzymatic profiles.
- Roasted Canary Seeds:Thermal processing reduces moisture content for extended shelf stability in snack applications.
Leading the category by volume: Conventional Canary Seeds. Growing fastest: Organic Canary Seeds.
End Use:
Application segments separate by margin structure, with human consumption commanding equipment segregation investments that pet feed processors avoid.
- Pet Food:Formulations for caged companion birds represent the historical demand core. Conventional grades dominate, with millet substitution pressure strongest in Southeast Asian price-sensitive markets.
- Bird Feed:Hobbyist breeders and commercial aviaries drive recurring consumption through subscription replenishment channels. Toronto and Vancouver specialty retailers capture margin pools via curated assortments bundled with mineral supplements.
- Human Consumption:Gluten-free flour and bakery ingredient applications demand parallel handling lines segregated from pet feed operations. CFIA mandates lot-specific allergen testing, fragmenting supply chains into food-grade and feed-grade streams with divergent cost structures.
- Health Supplements:Plant-based protein isolates and amino acid concentrates target fitness and wellness positioning. EFSA novel food approvals would unlock EU market access for Canadian organic exporters.
Highest margin capture: Health Supplements. Steepest expansion trajectory: Human Consumption.
Packaging Type:
Format selection tracks customer scale and urban density, with single-serve solutions targeting convenience retail while bulk containers sustain commodity economics.
- Single-Serve Packs:Pre-portioned formats capture urban convenience retail margins in Montreal, Toronto, and Vancouver. Packagers with in-house blending capabilities and direct-to-consumer logistics infrastructure extract premium pricing from time-constrained hobbyist breeders.
- Bulk Containers:Tote bags and super sacks sustain miller and blender procurement economics across prairie cleaning facilities. Saskatchewan and Manitoba mid-scale processors leverage optical sorting technology to contract directly with compounders, bypassing traditional aggregators.
- Bags:Standard multi-kilogram formats serve agricultural supply depots and regional distributors.
- Retail Packs:Branded consumer-facing formats occupy shelf space in specialty pet stores and supermarket pet aisles.
Dominant by tonnage: Bulk Containers. Gaining share fastest: Single-Serve Packs.
Distribution Channel:
Channel structure determines customer access costs, with digital platforms compressing intermediaries while wholesale retains institutional volume.
- Online Retail:Direct-to-aviary subscription platforms displace pet store intermediaries for hobbyist breeders. Curated varietal assortments with veterinary-formulated supplements reward logistics investment with recurring revenue streams.
- Wholesale:Bulk aggregators and agricultural supply depots sustain commodity flows to millers and large-scale aviaries. Buenos Aires port infrastructure reduces trans-Pacific shipping friction for Asian feed compounders sourcing Argentine origin stocks.
- Supermarkets:Mass retail penetration remains limited to pet aisle placement for conventional bird feed grades.
- Specialty Stores:Independent retailers in urban Canadian markets bundle canary seed with avian veterinary services and premium housing equipment.
Volume concentration: Wholesale. Channel expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buenos Aires anchors South American export flows through its port logistics infrastructure, while Saskatoon dominates North American prairie milling capacity. Regulatory divergence across these production clusters shapes sourcing strategies for compounders and specialty retailers.
Argentina
The Pampas region supplies over half of export-grade canary seed stocks to Asian feed compounders. Buenos Aires port infrastructure reduces trans-Pacific shipping friction for bulk handling operations. Drought exposure in Córdoba and Santa Fe provinces creates yield volatility that procurement teams must hedge through forward contracting.
Canada
Saskatchewan contract growers expand prairie acreage in response to Health Canada varietal purity mandates that grant domestic millers preferential access to certified seed stocks. The Canadian Food Inspection Agency enforces strict phytosanitary rules that reshape import eligibility for foreign-origin stocks. Toronto and Vancouver specialty retailers capture urban margin pools through curated subscription assortments bundled with veterinary supplements.
United States
The USDA's Animal and Plant Health Inspection Service governs import permit requirements that fragment procurement from multi-source aggregators. FDA food safety frameworks shape labeling protocols for human-grade canary seed products entering bakery applications. Midwest blenders and compounders source through Saskatchewan prairie infrastructure to bypass documentation complexity.
Brazil
ANVISA regulatory frameworks govern novel food ingredient approvals that determine human-grade positioning potential for South American exporters. São Paulo-based distributors serve as intermediaries for Argentine-origin stocks entering domestic avian feed formulations. The country's agricultural supply depots face substitution pressure from lower-cost panicum varieties in price-sensitive Southeast Asian re-export markets.
Australia
TGA oversight of gluten-free certification creates parallel compliance burdens for exporters targeting health supplement positioning. Victorian and South Australian cleaning facilities deploy optical sorting technology to achieve 99% purity thresholds demanded by Japanese and South Korean compounders. Melbourne specialty retailers test subscription channel viability for hobbyist breeder segments.
Canary Seeds Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across a market structure that concentrates bulk supply in prairie milling infrastructure and South American port logistics. Saskatchewan Seed Company and Globus Seeds S.A. anchor opposing hemispheres of export-oriented production. Three strategic archetypes dominate: prairie-integrated millers with captive cleaning capacity, Buenos Aires-port-anchored exporters with bulk handling specialization, and urban-focused packagers with direct-to-consumer logistics. Competitive moves center on optical sorting technology deployment and subscription channel infrastructure buildout.
Among prairie-integrated operators, Saskatchewan Seed Company exemplifies the capital-heavy archetype with upstream control over varietal development and cleaning infrastructure. Globus Seeds S.A. represents the export-specialist tier, leveraging Buenos Aires port logistics for trans-Pacific flows. Bird City International, Inc. occupies the curated retail position, targeting specialty pet stores and urban hobbyist breeders with bundled assortments. These three anchors illustrate how geographic concentration and channel specialization stratify competitive positioning.
| Leading Market Players |
|---|
| Pepef Seeds Corporation |
| Bird City International, Inc. |
| Saskatchewan Seed Company |
| Tarquin Seeds Ltd. |
| True Grass Seeds Ltd. |
| Hometown Seeds |
| Globus Seeds S.A. |
| Grain Millers, Inc. |
| Finseed Ltd. |
| Others |
Value Chain & Pricing Dynamics
Organic-conventional grade bifurcation creates parallel value capture mechanisms across prairie milling infrastructure and South American port logistics. Health Canada gluten-free certification mandates force food-grade processors into segregated handling lines with 40-60% cost premiums over pet feed operations, while Buenos Aires bulk exporters compete on nitrogen input efficiency and varietal purity thresholds.
Pricing Analysis
Cost-down pressure on conventional grades accelerates as Saskatchewan contract growers absorb fertilizer price volatility under fixed-price delivery agreements. Three-tier pricing structure across organic certified, conventional 99% purity, and sprouted value-added tiers separates buyers by certification burden and end-use application. Subscription replenishment channels extract 25-35% premiums from urban hobbyist breeders, while Argentine-origin spot markets face millet substitution pressure across Southeast Asian compounders. Pet food manufacturers show highest price sensitivity; health supplement brands accept organic premiums for EFSA novel food positioning.
Supply Chain Analysis
Freight cost differentials between Buenos Aires bulk terminals and prairie railheads shape procurement economics for Asian versus North American buyers. Supply concentrates in Argentina, Canada, and Australia, with each node serving distinct regulatory compliance requirements. Raw material flows draw from phosphate fertilizer inputs, optical sorting equipment, and varietal seed stock development programs. Single-origin concentration in the Pampas region exposes buyers to drought-induced yield shocks. Distribution runs through wholesale agricultural depots for volume compounders and direct-to-consumer platforms for specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from Health Canada organic certification timelines and optical sorting capex requirements will force sub-scale cleaning cooperatives into acquisition or exit. Three-year land history mandates and 99% purity equipment investments favor capital-heavy prairie millers over fragmented smallholders.
For Market Incumbents: Lock in prairie acreage through forward contracting with Saskatchewan and Manitoba growers ahead of CFIA import restriction tightening. Acquire optical sorting capabilities to bypass traditional bulk aggregators and contract directly with specialty pet food manufacturers. Millet substitution threats in Southeast Asia demand varietal differentiation investment. For New Entrants and Emerging Players: CRISPR-accelerated breeding platforms offer entry pathways into methionine-enhanced poultry feed segments underserved by conventional germplasm. Target subscription replenishment channels in Toronto and Vancouver where curated assortments with veterinary supplements capture margin pools inaccessible to commodity distributors. Lead with direct-to-aviary logistics infrastructure rather than agricultural supply depot relationships. For Investors and Strategic Acquirers: Re-rating potential sits with prairie-integrated millers possessing captive cleaning capacity and Health Canada certification relationships given EFSA novel food approval catalysts. Five-to-ten year viability hinges on human-grade ingredient positioning expansion. Watch for CFIA gluten-free labeling threshold tightening as signal for food-grade supply chain fragmentation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Technology Deployment | Machine-vision systems enable prairie cooperatives to bypass traditional bulk aggregators and contract directly with compounders. |
| Subscription Channel Infrastructure Buildout | Direct-to-aviary platforms displace pet store intermediaries and capture recurring revenue from urban hobbyist breeders. |
| EFSA Novel Food Approval Pursuit | EU regulatory alignment unlocks premium positioning for Canadian organic exporters targeting gluten-free bakery applications. |
| CRISPR Breeding Pipeline Investment | Gene-edited Phalaris canariensis lines with elevated methionine content target poultry feed premiumization opportunities. |
| Prairie Acreage Forward Contracting | Health Canada varietal purity mandates grant domestic millers preferential access to certified seed stocks. |
Study Parameters
Trade databases, agricultural census records, and CFIA regulatory filings formed the secondary backbone for supply-side calibration. Primary interviews with prairie contract growers, Buenos Aires export logistics coordinators, Toronto specialty retailers, and health supplement formulators validated demand assumptions. Bottom-up acreage and yield modeling combined with top-down trade flow analysis across the analysis window.
Historical trendline analysis of prairie planting decisions and Argentine export volumes established baseline growth patterns. Segmentation modeling incorporated product grade tiers, end-use applications, packaging formats, and distribution channel structures. CAGRs derived from weighted average of supply expansion trajectories and demand shift elasticities, with particular sensitivity to Health Canada regulatory timeline assumptions and EFSA approval pathway probabilities.
Several conditions sit outside the modeled scope, including extreme weather events in the Pampas region, abrupt shifts in gluten-free certification thresholds, and unforeseen millet variety substitution breakthroughs. Forecasts reflect documented assumptions around regulatory implementation pacing and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Dragon Fruit Seeds Market
Seeds
South America Quinoa Seeds Market
Seeds
Nepal Seeds Market
Seeds
United States Vegetable Seed Market
Seeds
Global Grain Seed Market
Seeds
Flower Seed Market
Seeds
United States Forage Seed Market
Seeds
Eucommia Seed Oil Market
Seeds
Global Soybean Seed Market
Seeds
Seed Cracker Market
Seeds
North America Vegetable Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Global Seed Market
Seeds
Europe Cannabis Seeds Market
Seeds
Safflower Seeds Market
Seeds
Americas Seeds Market